
 Event Insurance Market | 2026-2036
Event Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Event Insurance Market Analysis
Market Context with Strategic Players
Parametric weather coverage is restructuring how event organizers evaluate risk transfer, shifting from traditional indemnity models toward predefined trigger-based payouts. K&K Insurance leverages its long-standing specialization in sports and entertainment liability to sustain competitive positioning in high-frequency event verticals. Markel anchors its market presence through bespoke underwriting capabilities for complex festival and concert exposures. Thimble competes on immediacy, offering on-demand, micro-duration policies that match the gig-economy cadence of modern event production.
Technical Definition and Structural Segments
Event insurance constitutes a specialized class of short-tail property and casualty coverage designed to indemnify policyholders against financial losses stemming from event cancellation, third-party bodily injury, or venue property damage, with policies typically specifying per-occurrence limits, aggregate caps, and named peril schedules tied to discrete temporal windows. Its primary commercial purpose centers on enabling event execution by transferring operational risk from organizers to carriers, thereby unlocking capital commitments from venues, sponsors, and municipal permit-granting authorities. General liability coverage occupies the largest premium pool given its near-universal contractural mandate by venues and municipalities, while cancellation policies command elevated pricing elasticity in regions with concentrated hurricane or wildfire exposure. Single-day coverage is maturing into a commoditized layer with compressed margins, whereas multi-day and seasonal structures retain pricing power through customized risk engineering and embedded weather derivatives.
Regulatory Framework and Forward Outlook
State insurance commissioners across the United States enforce rate filing requirements and solvency standards that govern carrier participation in event lines, while the National Association of Insurance Commissioners coordinates model laws affecting policy form approvals and claims handling timelines. The Federal Emergency Management Agency's evolving flood zone remappings indirectly shape demand for supplemental weather coverage by altering baseline perceptions of acceptable uninsured retention. Stakeholders must monitor how climate attribution science advances influence judicial interpretations of force majeure exclusions and whether regulators accelerate mandated disclosure of parametric coverage alternatives at point of sale.
Market Dynamics
Parametric weather triggers and embedded sensor networks are compressing claims settlement cycles from months to hours, forcing carriers to rebuild core infrastructure around real-time data ingestion rather than retrospective loss adjustment.
Growth Catalysts
- Texas Senate Bill 12 (2025):Mandates parametric coverage disclosure for outdoor events exceeding 5,000 attendees, accelerating buyer education in high-hurricane-exposure zones.
- Drone-based venue inspection protocols:Reduce underwriting turnaround from 72 hours to 4 hours, enabling same-day policy issuance for spontaneous event bookings.
- Embedded insurance APIs:Ticketing platforms in California and Florida now auto-enroll purchasers into micro-duration cancellation riders at checkout.
Market Restraints
- Reinsurance capacity contraction:London and Bermuda markets have tightened retrocession for Florida wind-exposed event portfolios since 2023.
- Legacy core system architectures:Regional carriers in the Midwest operate on policy administration platforms incapable of parametric trigger integration.
- Alternative risk transfer vehicles:Large festival promoters in Nevada and Tennessee increasingly self-insure through captive structures, bypassing commercial markets entirely.
Strategic Opportunities
- Underpenetrated college athletics segment:NCAA Division II and III programs in Ohio, Pennsylvania, and Michigan carry minimal cancellation coverage despite multimillion-dollar broadcast commitments.
- Convergence of IoT sensors and blockchain oracles:Enables automated, tamper-proof weather verification for instant parametric payouts without adjuster involvement.
- On-demand gig-worker liability bundles:Catering and AV technician marketplaces in New York and Illinois seek per-shift coverage integration with labor platforms.
Industry Challenges
- Parametric actuarial talent scarcity:Fewer than 200 qualified modelers exist domestically who can structure index-based triggers for non-standard perils like air quality cancellation.
- Venue management system fragmentation:Integration of insurance APIs with legacy property management software used by 60% of municipal-owned facilities requires bespoke middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Insurance Market |
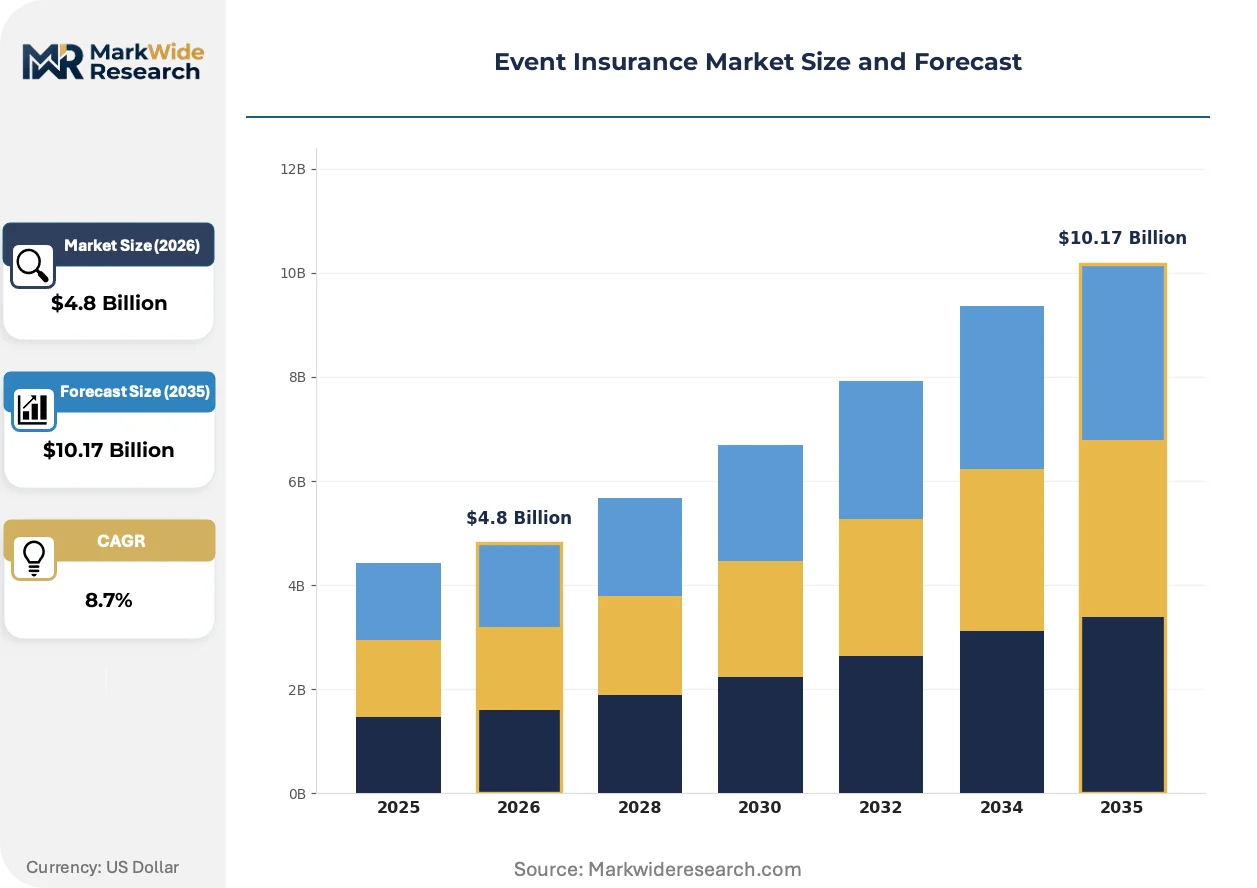
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: General Liability, Cancellation, Weather, Liability for Accidental Damage Event Type: Corporate Events, Weddings, Festivals, Trade Shows Coverage Duration: Single-Day, Multi-Day, Annual, Seasonal Client Type: Individuals, Corporations, Nonprofits, Event Planners |
| Companies Covered | K&K Insurance, Markel, Insurance Canopy, Thimble, GatherGuard, Direct Event Insurance, RV Nuccio & Associates, EventHelper, Eventsured, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Insurance Market Emerging Trajectories
Real-time atmospheric monitoring and automated payout infrastructure are collapsing the traditional boundaries between risk assessment, policy binding, and claims resolution into single-session digital workflows.
Parametric weather indices linked to NOAA satellite feeds are overtaking traditional indemnity structures for outdoor event cancellation coverage. Festival promoters in coastal Texas and Florida now specify exact rainfall millimeter thresholds and wind speed ceilings in policy riders rather than submitting post-event proof of loss. This compression eliminates the 90-day claims investigation window that previously strained vendor relationships and municipal permit renewals.
The National Association of Insurance Commissioners' 2024 model law on parametric disclosure requirements is forcing carriers to standardize policy language across state lines. Texas and Florida regulators have adopted the framework verbatim, while California's Department of Insurance has appended supplemental cooling-off period mandates. Carriers operating multi-state event portfolios must now maintain parallel policy forms or absorb compliance engineering costs that disadvantage regional specialists.
Corporate procurement departments are consolidating event insurance purchasing from decentralized departmental budgets into centralized risk management functions. Fortune 500 headquarters in Illinois and New Jersey now mandate enterprise-wide event coverage through master policies rather than permitting individual business units to source ad-hoc protection. This concentration rewards carriers with multi-line capabilities and squeezes single-product underwriters into niche municipal and nonprofit segments where procurement sophistication lags.
Event Insurance Market Segmentation
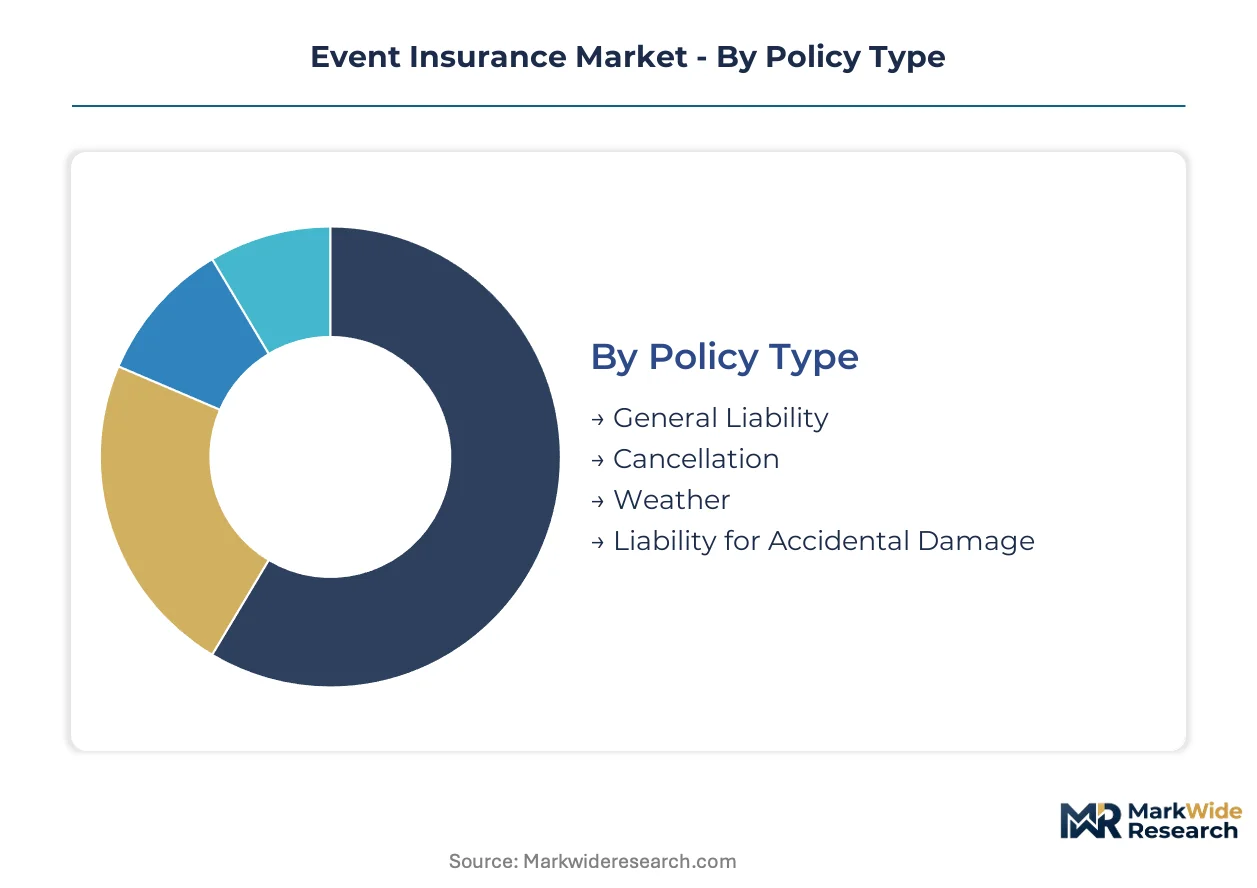
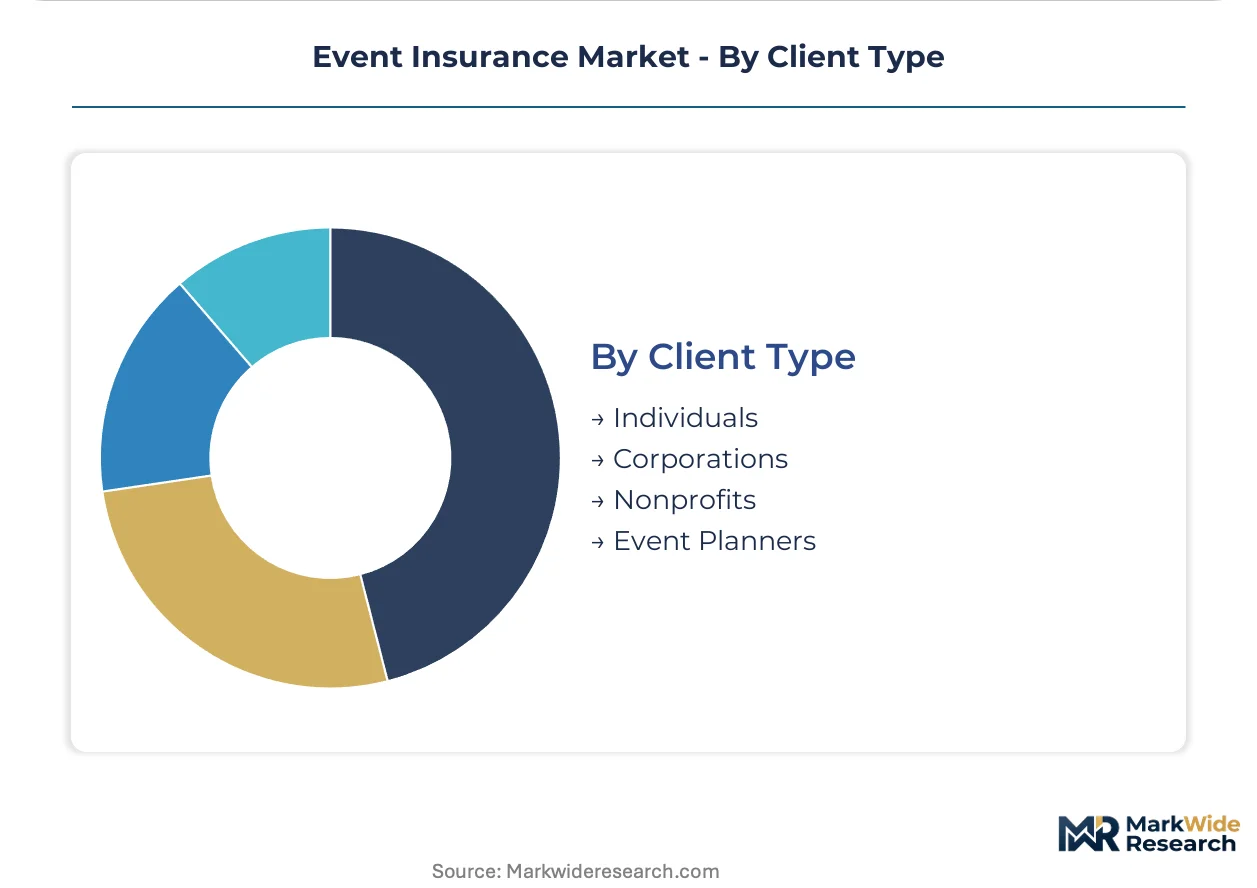
Event insurance segmentation reflects divergent risk profiles across policy structures, event formats, and buyer sophistication levels. Carriers calibrate pricing engines and distribution channels around these distinctions, with parametric triggers and embedded APIs reshaping how each segment accesses coverage.
Policy Type:
Buyers in this category differ fundamentally in how they quantify and transfer operational risk, with some prioritizing third-party protection and others seeking balance sheet preservation against force majeure.
- General Liability:Covers bodily injury and property damage to third parties arising from event operations. Venue contracts in Texas and Florida mandate this coverage universally, with municipal permit authorities requiring certificates naming them as additional insureds.
- Cancellation:Indemnifies against financial losses from event abandonment due to named perils including severe weather, terrorism, or non-appearance of key personnel. Festival promoters in coastal hurricane zones specify parametric rainfall and wind speed triggers rather than traditional proof-of-loss documentation.
- Weather:Parametric structures tied to NOAA satellite feeds enable automatic payouts when predefined atmospheric thresholds breach. Texas Senate Bill 12 mandates disclosure for outdoor events exceeding 5,000 attendees.
- Liability for Accidental Damage:Protects against unintentional harm to venue infrastructure or rented equipment. Corporate procurement departments in Illinois and New Jersey increasingly bundle this into master policies rather than sourcing ad-hoc protection.
General Liability leads volumes today; Weather coverage is gaining share fastest.
Event Type:
Commercial significance varies sharply by event scale, repeat frequency, and sponsor capital commitment, with some formats enabling multi-year risk engineering relationships.
- Corporate Events:Conferences, product launches, and shareholder meetings requiring professional liability overlays. Fortune 500 headquarters consolidate purchasing through centralized risk management functions rather than departmental budgets.
- Weddings:Personal lines coverage with high emotional purchase drivers and compressed decision windows. Wedding planners in California and Florida represent an expanding intermediary channel with commission-based incentive alignment.
- Festivals:Multi-day outdoor gatherings with concentrated weather exposure and complex vendor ecosystems. Promoters in Nevada and Tennessee increasingly self-insure through captive structures, bypassing commercial markets entirely.
- Trade Shows:Recurring exhibition formats with predictable loss histories and scale economies. Exhibition management companies in New York and Illinois seek annual blanket coverage with per-show endorsements.
Corporate Events anchor premium concentration; Festivals show the steepest expansion trajectory as outdoor formats proliferate.
Coverage Duration:
Policy tenure directly determines pricing elasticity, underwriting resource allocation, and the viability of embedded sensor networks for real-time risk monitoring.
- Single-Day:Compressed-margin commodity product with automated issuance through ticketing platform APIs. Thimble and on-demand carriers compete on four-hour turnaround from quote to bind.
- Multi-Day:Customized risk engineering for festivals and tournament series with embedded weather derivatives. Retains pricing power through bespoke peril scheduling and aggregate limit negotiation.
- Annual:Blanket protection for recurring event producers with portfolio diversification benefits. Corporate risk managers in New Jersey favor this structure for budget predictability.
- Seasonal:Agricultural fairs, holiday markets, and summer concert series with defined temporal windows. NCAA Division II and III athletics programs in Ohio and Michigan remain underpenetrated despite multimillion-dollar broadcast commitments.
Multi-Day structures dominate absolute premium; Single-Day is expanding most quickly via platform-embedded distribution.
Client Type:
Procurement sophistication and risk retention capacity separate buyers in this category, with some seeking transactional protection and others engineering multi-year risk transfer programs.
- Individuals:Wedding hosts and private celebration organizers purchasing through direct-to-consumer channels. High price sensitivity and limited policy comparison capability characterize this segment.
- Corporations:Centralized risk management functions with enterprise-wide event coverage mandates. Master policies in Illinois and New Jersey squeeze single-product underwriters into niche segments.
- Nonprofits:Fundraising galas and community events with budget constraints and volunteer-dependent operations. Municipal-owned facilities in the Midwest often require coverage certificates despite limited procurement sophistication.
- Event Planners:Professional intermediaries with portfolio-scale purchasing power and carrier relationship depth. Wedding planners represent the fastest-growing intermediary channel in high-climate-exposure states.
Corporations lead premium volume; Event Planners are climbing the fastest as professionalization of the gig economy accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates parametric weather coverage adoption for outdoor events, while Germany's corporate event sector drives demand for professional liability overlays across trade show and conference formats.
United States
Texas, Florida, and California generate concentrated demand for hurricane and wildfire-exposed cancellation policies. Texas Senate Bill 12 mandates parametric coverage disclosure for outdoor events exceeding 5,000 attendees. Houston and Miami festival promoters now specify NOAA-linked rainfall thresholds in policy riders rather than traditional proof-of-loss documentation.
Germany
Corporate procurement departments in Frankfurt and Munich consolidate event insurance purchasing through centralized risk management functions. Germany's national insurance regulator enforces solvency standards governing carrier participation in short-tail property lines. Bavaria's exhibition management companies seek annual blanket coverage with per-show endorsements for recurring trade formats.
United Kingdom
Wedding planners in London and the Southeast represent an expanding intermediary channel with commission-based incentive alignment. The Financial Conduct Authority coordinates disclosure requirements affecting policy form approvals and claims handling timelines. Edinburgh's festival ecosystem drives demand for multi-day customized risk engineering with embedded weather derivatives.
France
Luxury event organizers in Paris and the Côte d'Azur prioritize bespoke underwriting for high-value private celebrations. ANSM and CNIL frameworks indirectly shape data governance for parametric trigger verification systems. Lyon corporate headquarters increasingly mandate enterprise-wide event coverage through master policies rather than departmental ad-hoc sourcing.
Australia
Sydney and Melbourne outdoor event promoters face elevated climate risk exposure from bushfire and flood perils. The national prudential regulator enforces capital adequacy requirements for carriers writing weather-indexed cancellation coverage. Queensland's agricultural fair circuit remains underpenetrated despite seasonal revenue concentration risks.
Event Insurance Market Vendor Landscape
Top-tier vendors anchor the specialist underwriting tier, while on-demand digital platforms compete on immediacy and compressed issuance cycles. The market structure fragments across legacy indemnity carriers, parametric specialists, and embedded API distributors. Three archetypes dominate: established sports and entertainment liability underwriters, bespoke festival and concert risk engineers, and gig-economy-aligned micro-duration issuers. Carriers pursue portfolio diversification into parametric weather products and geographic expansion through state-by-state rate filings.
Within the established specialist tier, K&K Insurance and Markel occupy positions representing long-standing vertical expertise and complex exposure underwriting capabilities respectively. Thimble exemplifies the on-demand archetype, competing through four-hour turnaround from quote to bind for spontaneous event bookings. These three entities collectively illustrate how competitive positioning stratifies between legacy relationship depth and digital-native immediacy.
| Leading Market Players |
|---|
| K&K Insurance |
| Markel |
| Insurance Canopy |
| Thimble |
| GatherGuard |
| Direct Event Insurance |
| RV Nuccio & Associates |
| EventHelper |
| Eventsured |
| Others |
Supply Flow & Price Mechanics
Corporate procurement consolidation in Illinois and New Jersey is forcing regional carriers to absorb compliance engineering costs or retreat to niche municipal segments, compressing margins for single-product underwriters while rewarding multi-line specialists with pricing power.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for parametric weather coverage as carriers compete for outdoor event portfolios exposed to hurricane and wildfire perils. Pricing stratifies across premium bespoke underwriting, standard multi-day bundled structures, and economy single-day commoditized layers. Cost compression in the single-day tier is intensifying because Thimble and on-demand platforms automate four-hour issuance cycles. Wedding planners and individual event organizers show highest price sensitivity, while Fortune 500 risk managers demonstrate lowest sensitivity due to master policy consolidation.
Supply Chain Analysis
Returns and policy cancellation flows from embedded ticketing platform APIs are creating reverse-logistics complexity as California and Florida auto-enrollment systems generate mid-cycle opt-out surges. Underwriting capacity concentrates in the United States, United Kingdom, and Bermuda, with London and Bermuda markets supplying critical reinsurance retrocession. Carrier infrastructure draws from legacy policy administration platforms, parametric trigger modeling software, and real-time NOAA satellite data feeds. Single-source vulnerability sits with the scarce pool of fewer than 200 qualified parametric actuarial modelers domestically. Distribution runs through wedding planner intermediaries, corporate risk management departments, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where buyer sophistication has shifted toward parametric specifications and automated payout infrastructure as baseline requirements rather than premium differentiators.
For Market Incumbents: Acquire parametric actuarial modeling capabilities to offset talent scarcity that constrains product expansion into air quality and non-standard peril triggers. Defend against embedded insurance API distributors by deepening venue management system integrations through bespoke middleware development. Capacity additions in Texas and Florida should anchor geographic defense.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in NCAA Division II and III athletics programs offers white-space entry with minimal incumbent saturation. Target Ohio, Pennsylvania, and Michigan for seasonal coverage penetration where multimillion-dollar broadcast commitments lack cancellation protection. Lead with drone-based venue inspection protocols that compress underwriting turnaround from 72 hours to 4 hours as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Asymmetric upside sits with parametric specialist carriers possessing NOAA satellite feed integration and automated oracle infrastructure. Long-term viability favors underwriters with demonstrated state-by-state rate filing success across multiple jurisdictions. Monitor Texas Senate Bill 12 compliance adoption curves as the inflection signal for parametric coverage standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Integration | NOAA satellite feed connectivity enables automatic payouts without adjuster involvement, collapsing settlement cycles. |
| Embedded API Distribution | Ticketing platform partnerships in California and Florida auto-enroll purchasers at checkout, capturing spontaneous demand. |
| Drone-Based Underwriting | Venue inspection protocols reduce turnaround from 72 hours to 4 hours for same-day policy issuance. |
| Captive Structure Expansion | Nevada and Tennessee festival promoters increasingly self-insure, bypassing commercial markets entirely. |
| Middleware Development | Integration with legacy property management software used by 60% of municipal-owned facilities unlocks distribution. |
Methodological Framework
Multiple input streams — carrier underwriting executives, state insurance commissioner filings, and wedding planner intermediaries — were reconciled against secondary validation from National Association of Insurance Commissioners model law documentation, NOAA climate data repositories, and municipal permit authority records. Bottom-up policy issuance volume estimates were triangulated with top-down premium pool calculations derived from rate filings across Texas, Florida, and California.
Historical parametric adoption curves were cross-referenced against panel input from festival promoters and corporate risk managers to inform projection trajectories across the analysis window. Segmentation dimensions modeled include policy type, event format, coverage duration, and client procurement sophistication. CAGRs were derived from iterative reconciliation of carrier capacity expansion plans and climate exposure remapping by FEMA flood zone updates.
Caveats apply where climate attribution science advances or judicial reinterpretations of force majeure exclusions could materially shift the outlook for cancellation coverage demand. Practitioners should monitor Texas and Florida regulatory adoption of parametric disclosure mandates and reinsurance capacity contraction signals from London and Bermuda markets for early indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Analytics Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Europe Parametric Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Europe Car Insurance Market
Insurance
Cargo Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
Medical Professional Liability Insurance Market