
 Engineering Insurance Market | 2026-2036
Engineering Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Insurance Market Analysis
Claims settlement margins from legacy property damage coverage is narrowing as insurers redirect capital toward cyber risk and business interruption products. Allianz leverages its engineering risk modeling platforms to dominate complex infrastructure placements across emerging economies. Zurich Insurance Group anchors its competitiveness through captive reinsurance structures that sustain pricing power in volatile catastrophe zones. Munich Re differentiates via parametric triggers tied to equipment breakdown sensors, reducing indemnity lag for industrial clients.
Engineering insurance encompasses specialized property and liability coverage designed to protect capital-intensive construction, installation, and operational assets against physical damage, mechanical failure, and consequential financial loss during project execution and operational life. Policies typically incorporate loss-of-profits clauses, advanced risk retention structures, and sub-limits calibrated to equipment criticality ratings, serving to transfer catastrophic construction and operational exposures from balance sheets to risk capital markets. Contractors All Risk coverage commands the largest premium pool given its mandatory status on financed infrastructure projects, while Cyber Risk represents the fastest-expanding segment as operational technology networks in power plants and manufacturing facilities face elevated ransomware exposure. Equipment Breakdown coverage retains concentrated margin contribution due to specialized inspection protocols and proprietary failure-mode databases that limit competitive entry.
The National Association of Insurance Commissioners coordinates state-level reserving standards and rate filing requirements across US jurisdictions, while Solvency II in Europe mandates risk-based capital adequacy that shapes product design and pricing granularity for cross-border engineering programs. Emerging markets including India and Indonesia apply BIS structural safety codes and local content requirements that condition coverage terms and local capacity retention. Stakeholders must monitor regulatory divergence between developed and developing market frameworks as project finance structures increasingly span multiple jurisdictions with incompatible insurance compliance architectures.
Market Dynamics
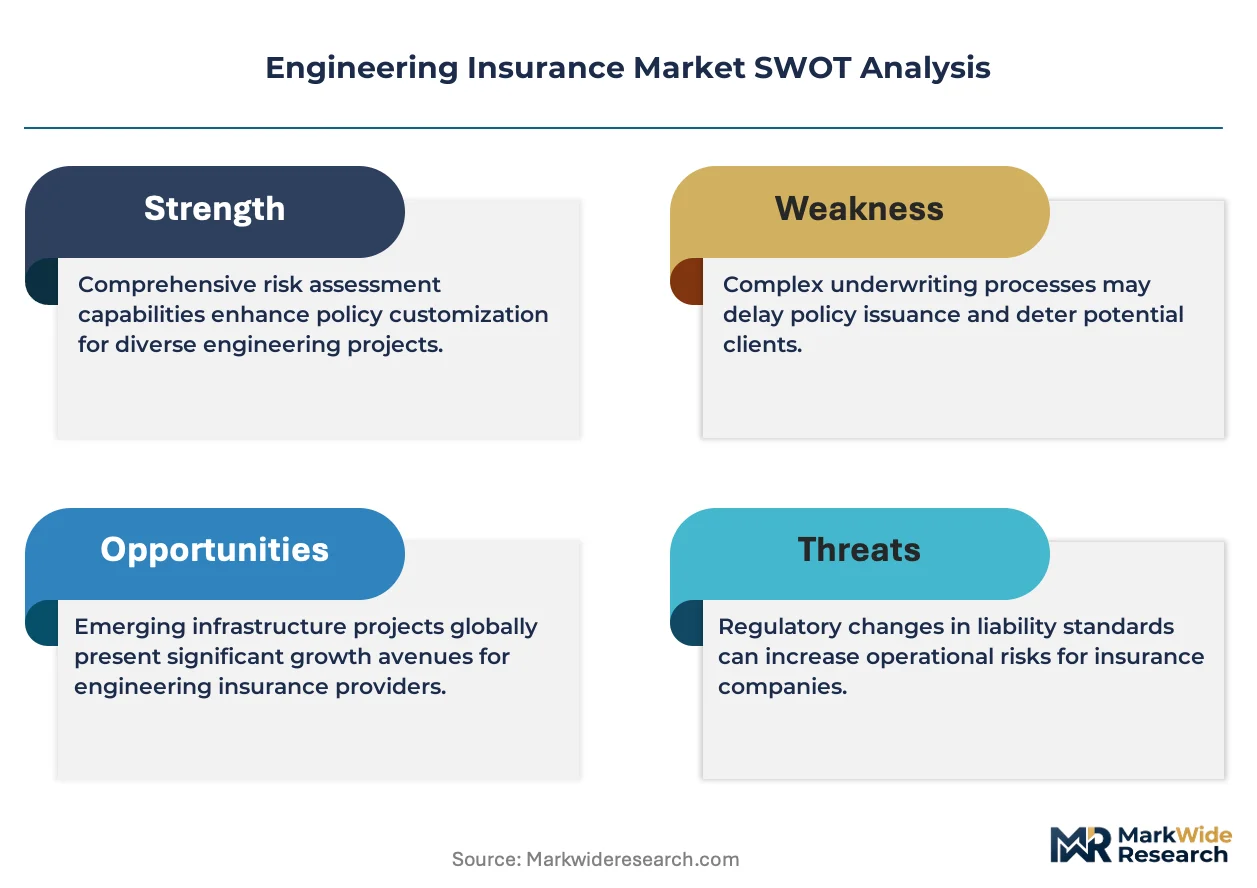
Capital reallocation from legacy property lines toward cyber and business interruption products is compressing traditional engineering margins while forcing carriers to rebuild underwriting infrastructure around sensor-based risk telemetry.
Growth Catalysts
- Climate Resilience Mandates:Coastal jurisdictions in Indonesia, Vietnam, and the Philippines now require parametric coverage triggers for flood and typhoon exposure on financed infrastructure. These mandates accelerate policy upgrades across power generation and transport assets.
- Power Sector Foreign Direct Investment:Southeast Asian governments are attracting capital into grid modernization and renewable generation. Engineering insurance penetration deepens as lenders mandate Contractors All Risk coverage for project finance closure.
- Equipment Sensor Networks:Industrial IoT deployments in manufacturing facilities and process plants enable real-time equipment health monitoring. Insurers leverage this data stream to refine Equipment Breakdown pricing and reduce indemnity lag.
Market Restraints
- Nat-Cat Capacity Concentration:Reinsurance capital for catastrophe-exposed construction projects concentrates among Zurich and Munich Re captive structures. This supply limitation sustains pricing volatility in Philippine and Indonesian coastal zones.
- Legacy System Integration Costs:Carriers face technical debt from decades-old policy administration platforms. Migration expenses consume underwriting innovation budgets and delay parametric product rollouts.
- Alternative Risk Transfer Competition:Captive insurance formations and catastrophe bonds siphon premium volume from traditional engineering markets. Large infrastructure sponsors increasingly retain construction risk through project-specific vehicles.
Strategic Opportunities
- Underpenetrated Indian Infrastructure:India's National Infrastructure Pipeline targets expansion in urban transit and renewable energy. Local content requirements under BIS codes create demand for domestically compliant coverage structures.
- Cyber-Physical Convergence:Operational technology networks in power plants face elevated ransomware exposure. Insurers can bundle Equipment Breakdown with cyber extortion coverage for integrated risk transfer.
- EU Green Deal Alignment:The EU Taxonomy for sustainable activities creates regulatory tailwind for engineering coverage of carbon capture and hydrogen infrastructure. Carriers with ESG-linked pricing frameworks capture placement priority.
Industry Challenges
- Actuarial Talent Scarcity:Specialized expertise in equipment failure-mode modeling and construction delay quantification remains concentrated among senior practitioners. Succession gaps threaten underwriting quality in complex infrastructure placements.
- Multi-Jurisdictional Compliance Complexity:Project finance structures spanning Solvency II territories, US state-level NAIC frameworks, and emerging market capital requirements create documentation friction. Legal and compliance teams struggle to harmonize incompatible reserving standards.
- Sensor Data Standardization:Equipment manufacturers deploy proprietary IoT protocols that resist interoperability. Insurers cannot aggregate failure-mode databases across vendor silos, limiting predictive underwriting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Insurance Market |
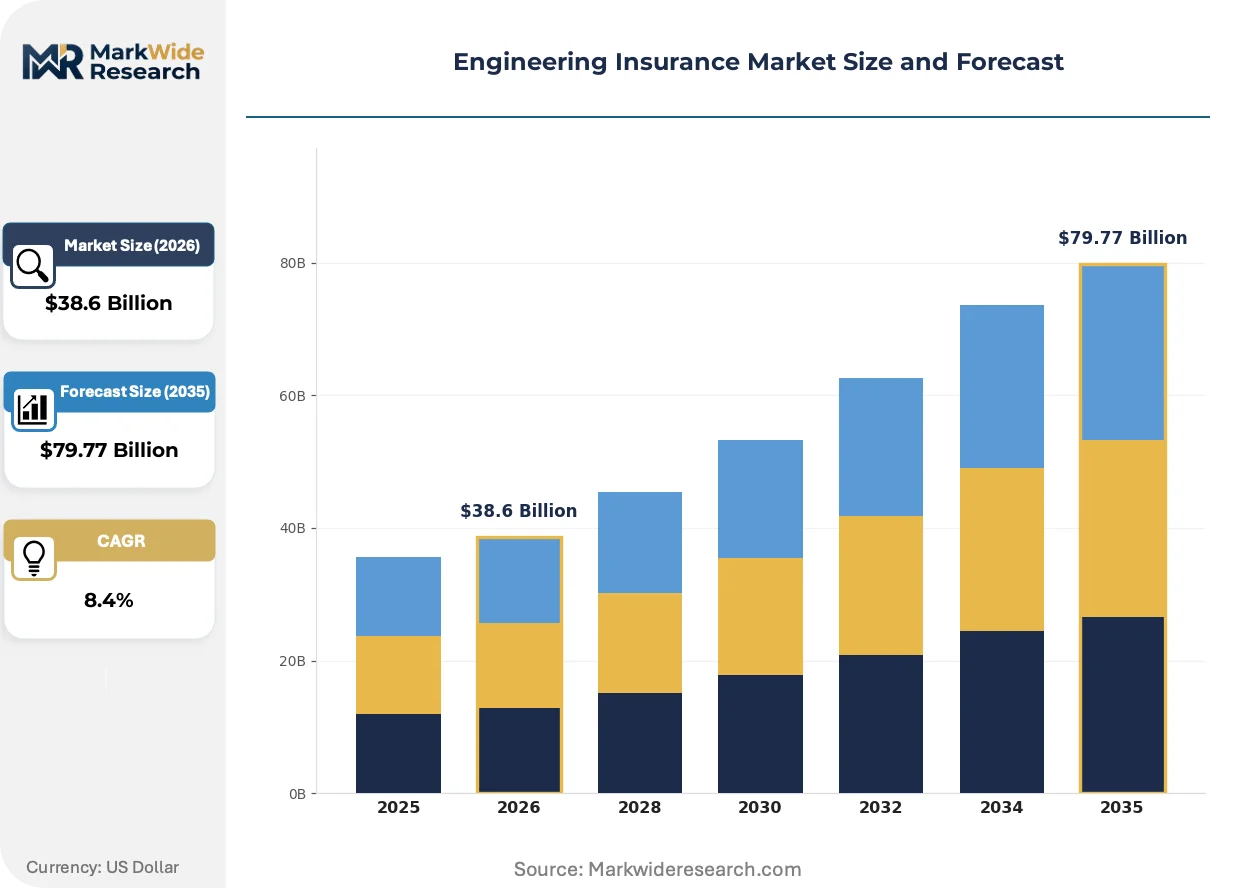
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Contractors All Risk, Erection All Risk, Boiler and Machinery, Cyber Risk Coverage Type: Property Damage, Third-Party Liability, Equipment Breakdown, Business Interruption End User: Construction Firms, Engineering Consultants, Public Sector, Utilities Policy Structure: Single Project, Multiple Projects, Comprehensive Package, Short-Term |
| Companies Covered | Allianz, Zurich Insurance Group, AXA XL, The Travelers Indemnity Company, AIG, Swiss Re, Chubb, Bajaj Allianz Life Insurance, Munich Re, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Insurance Market Emerging Trajectories
Parametric triggers and embedded sensor networks are displacing traditional indemnity-based settlement models across industrial risk transfer. Carriers now compete on data infrastructure rather than balance sheet scale alone.
Real-time equipment monitoring is migrating from pilot installations to standard coverage requirements for large industrial risks. Power plant operators and semiconductor fabs now mandate sensor integration as a condition of preferred pricing. This technology shift is compressing claims investigation cycles from months to days and enabling usage-based premium structures that reflect actual operating stress rather than rated exposure.
The EU's Corporate Sustainability Reporting Directive now mandates disclosure of climate-related physical risks across insured asset portfolios. Engineering carriers must embed carbon footprint and resilience metrics into underwriting workflows. European infrastructure sponsors face reporting obligations that favor insurers with validated ESG scoring methodologies, reshaping placement dynamics on cross-border renewable energy projects.
Buyer concentration among mega-project sponsors is consolidating procurement leverage. EPC contractors and infrastructure funds now demand multi-year master policies with embedded rate caps, displacing annual renewal negotiations. This pattern is most visible in Indonesian and Vietnamese power generation markets where foreign direct investment has concentrated project ownership among a handful of regional developers.
Engineering Insurance Market Segmentation
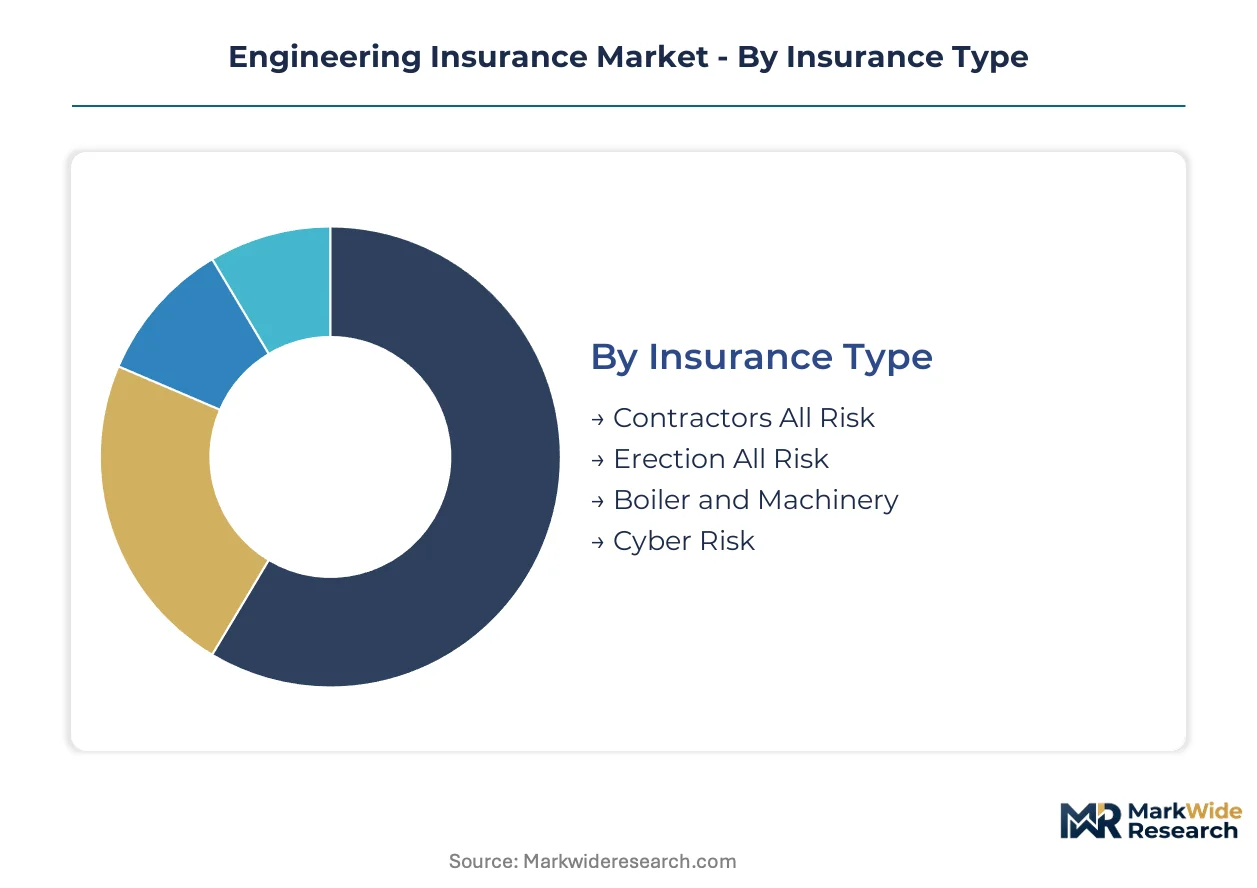
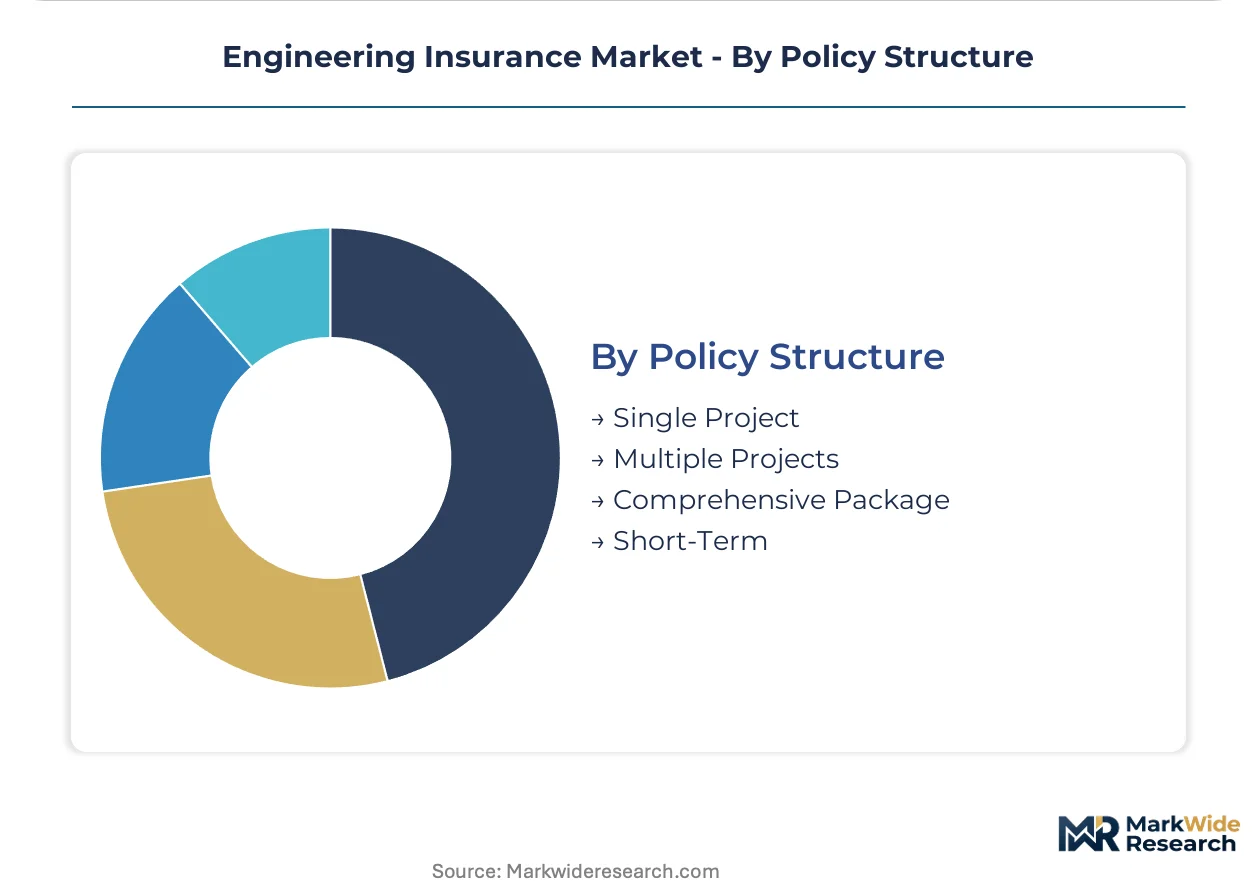
Engineering insurance segmentation reveals how capital intensity and project duration shape risk transfer structures. Policy structures align with construction cycle lengths, while coverage types map to asset criticality ratings and regulatory mandates.
Insurance Type:
Policy renewal cycles vary dramatically across this category, with annual cyber endorsements turning over fastest and multi-year infrastructure placements extending slowest.
- Contractors All Risk:Wraps construction-phase exposures including material damage, third-party injury, and delay penalties under unified terms. Demand concentrates on Indonesian and Vietnamese power generation projects where foreign lenders mandate coverage for financial closure.
- Cyber Risk:Covers operational technology intrusions, ransomware extortion, and system restoration costs for industrial control networks. Expansion concentrates among European power utilities facing EU NIS2 directive compliance deadlines and elevated grid vulnerability assessments.
- Erection All Risk:Protects installation-phase mechanical and electrical equipment during assembly and commissioning.
- Boiler and Machinery:Covers pressure vessel failures, turbine breakdowns, and consequential damage from mechanical defects.
Contractors All Risk dominates premium volume. Cyber Risk is where expansion concentrates.
Coverage Type:
Premium allocation across this category follows asset replacement cost hierarchies, with business interruption commanding highest pricing granularity due to revenue modeling complexity.
- Property Damage:Indemnifies physical loss to structures, equipment, and materials from named perils including fire, flood, and collapse. Demand concentrates in Philippine coastal zones where stricter building codes now require upgraded limits for typhoon resilience.
- Equipment Breakdown:Responds to mechanical failure, electrical arcing, and centrifugal force damage excluded from standard property forms. Margin contribution remains concentrated among carriers with proprietary failure-mode databases and certified inspection protocols.
- Third-Party Liability:Defends against bodily injury and property damage claims arising from construction operations.
- Business Interruption:Covers lost profits and continuing expenses during operational downtime following insured physical damage.
Property Damage commands the largest installed base. Equipment Breakdown captures the steepest expansion trajectory as sensor-enabled pricing gains adoption.
End User:
Procurement sophistication varies sharply across buyer types, with infrastructure funds negotiating multi-year master policies while public entities cycle through annual competitive tenders.
- Construction Firms:EPC contractors purchasing project-specific coverage or annual umbrella programs depending on backlog concentration. Demand concentrates among Southeast Asian contractors executing foreign-financed transport infrastructure where BIS-equivalent safety codes condition coverage terms.
- Utilities:Grid operators and generation owners securing operational-phase equipment breakdown and business interruption protection. Procurement patterns favor multi-year placements with embedded rate caps as buyer consolidation deepens.
- Engineering Consultants:Design firms securing professional liability and project-specific contingent coverage.
- Public Sector:Government agencies procuring coverage through mandated tender processes with local content requirements.
Construction Firms dominate transaction volume. Utilities represent the fastest-growing buyer segment as renewable asset portfolios expand.
Policy Structure:
Administrative burden scales inversely with policy integration, with single-project placements requiring full underwriting review while comprehensive packages automate renewals.
- Single Project:Standalone coverage tailored to specific construction or installation exposures with bespoke terms. Demand concentrates on Indian urban transit projects where National Infrastructure Pipeline funding triggers lender-mandated Contractors All Risk placement.
- Comprehensive Package:Integrated multi-line programs spanning construction, operational, and liability phases under unified terms. Procurement leverage concentrates among Indonesian and Vietnamese infrastructure funds consolidating coverage across generation portfolios.
- Multiple Projects:Master policies covering rolling portfolios of construction sites with scheduled reporting.
- Short-Term:Temporary coverage for discrete activities including demolition, retrofit, or maintenance shutdowns.
Single Project structures dominate current placements. Comprehensive Package formats are where carrier investment in automation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indonesia and Vietnam demonstrate the highest price elasticity as foreign lenders mandate coverage for project finance closure. German and Swiss utilities exhibit lowest sensitivity, absorbing premium increases for multi-year master policies with embedded rate caps.
Indonesia
Power generation and transport infrastructure attract concentrated foreign direct investment. BIS-equivalent structural safety codes condition coverage terms on mega-projects. Jakarta and Surabaya host engineering insurance procurement hubs where captive reinsurance structures dominate catastrophe-exposed placements.
Vietnam
Grid modernization and renewable generation drive deepening policy penetration. Local content requirements under national infrastructure programs shape domestically compliant coverage structures. Ho Chi Minh City and Hanoi concentrate EPC contractor demand for Contractors All Risk on foreign-financed developments.
Germany
Industrial IoT deployments in manufacturing facilities enable real-time equipment health monitoring. EU Green Deal alignment through the EU Taxonomy creates regulatory tailwind for carbon capture and hydrogen infrastructure coverage. The Rhine-Ruhr industrial corridor anchors Equipment Breakdown policy volume with sensor-enabled pricing adoption.
United States
State-level NAIC reserving standards coordinate rate filing requirements across jurisdictions. Cyber-physical convergence in power plant operational technology networks elevates ransomware exposure. Texas and California utility operators negotiate multi-year master policies as buyer consolidation deepens procurement leverage.
India
The National Infrastructure Pipeline targets expansion in urban transit and renewable energy. BIS structural safety codes and local content requirements condition coverage terms. Maharashtra and Gujarat concentrate construction firm demand for project-specific Contractors All Risk placement on lender-mandated financings.
Engineering Insurance Market Vendor Landscape
Capability concentration sits with specialized engineering risk modelers; scale advantage sits with diversified global carriers with captive reinsurance structures. The market exhibits tiered consolidation where a handful of European and North American groups control catastrophe capacity while regional specialists capture domestically compliant placements. Three archetypes dominate: sensor-integrated parametric underwriters, captive-reinsurance scale players, and emerging market compliance specialists. Competitive moves center on M&A for failure-mode databases and strategic partnerships for IoT data access.
Within the sensor-integrated tier, Allianz and Munich Re exemplify carriers leveraging engineering risk modeling platforms and parametric triggers tied to equipment breakdown sensors. Zurich Insurance Group anchors the captive-reinsurance archetype with structures sustaining pricing power in volatile catastrophe zones. These three European-based groups occupy positions that define competitive intensity across Indonesian power generation and Vietnamese transport infrastructure placements.
| Leading Market Players |
|---|
| Allianz |
| Zurich Insurance Group |
| AXA XL |
| The Travelers Indemnity Company |
| AIG |
| Swiss Re |
| Chubb |
| Bajaj Allianz Life Insurance |
| Munich Re |
| Others |
Supply Flow & Price Mechanics
The Singapore-Jakarta maritime corridor anchors reinsurance capital flows into Indonesian power generation placements, with freight cost volatility compressing margins on catastrophe-exposed Contractors All Risk policies while amplifying price spreads between Zurich's captive structures and standard market capacity.
Pricing Analysis
Extended maintenance service agreements and sensor-enabled condition monitoring contracts now drive lifetime value capture for Equipment Breakdown underwriters. Three-tier pricing structure across premium, standard, and economy levels separates Zurich's captive-reinsurance placements from Munich Re's parametric sensor offerings and standard indemnity markets. Price differentiation hinges on certified inspection protocols and proprietary failure-mode database depth. Cost compression in Philippine coastal zones is intensifying because nat-cat capacity concentrates among European captive structures. Construction firms in Vietnam demonstrate highest price sensitivity as foreign lender mandates force coverage purchases, while German utilities absorb premium increases for multi-year master policies with embedded rate caps.
Supply Chain Analysis
Supplier-financing facilities extended by Munich Re and Swiss Re to sensor network vendors are accelerating IoT protocol standardization across industrial equipment manufacturers. Reinsurance capital concentrates in Germany, Switzerland, and Bermuda, with primary underwriting capacity anchored in London, Singapore, and Zurich. The supply chain draws from specialized actuarial talent pools in the UK and US, certified inspection labor in Germany and Japan, and parametric modeling capabilities in Bermuda. Single-source vulnerability in sensor data interoperability creates aggregation risk for predictive underwriting accuracy. Distribution runs through broker networks in Jakarta, Ho Chi Minh City, and Mumbai for emerging market placements, and direct carrier relationships for European utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering insurance functions as a substitution defense against alternative risk transfer vehicles, with catastrophe bonds and captive formations threatening to disintermediate traditional carrier placements on large infrastructure projects.
For Market Incumbents: Entrench proprietary sensor data partnerships to lock in predictive underwriting advantage against parametric newcomers. Deepen captive reinsurance structures in Indonesian and Philippine catastrophe zones to defend pricing power against Zurich's established scale. Invest in certified inspection protocol expansion to maintain Equipment Breakdown margin contribution as sensor-enabled competitors enter.
For New Entrants and Emerging Players: Establish a beachhead in Indian urban transit coverage where National Infrastructure Pipeline funding creates lender-mandated demand and domestic compliance requirements limit European carrier penetration. Target Vietnamese renewable generation placements where local content requirements under BIS-equivalent codes create structural barriers to incumbent scale. Lead with cyber-physical bundled offerings that combine Equipment Breakdown with operational technology ransomware coverage.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with validated IoT data pipelines and parametric trigger infrastructure over balance-sheet-scale generalists. Long-term viability over the next decade rests on predictive underwriting accuracy and sensor network integration depth. Acquisition targets should display proprietary failure-mode databases and certified inspection labor pools. Watch for inflection when EU Taxonomy disclosure mandates force ESG-linked pricing framework adoption across European infrastructure sponsors.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Integration | Sensor-based settlement models reduce indemnity lag for Munich Re's industrial clients. |
| Captive Reinsurance Expansion | Zurich's catastrophe zone structures sustain pricing power in Philippine coastal placements. |
| Cyber-Physical Coverage Bundling | Combined Equipment Breakdown and ransomware protection captures EU NIS2 compliance demand. |
| ESG-Linked Pricing Framework | EU Taxonomy alignment secures placement priority on carbon capture infrastructure. |
| Failure-Mode Database Acquisition | Proprietary mechanical defect libraries limit competitive entry into Equipment Breakdown. |
Methodological Framework
A spread of perspectives from underwriting executives at European carriers, risk managers at Southeast Asian EPC contractors, reinsurance brokers in Singapore, and regulatory affairs specialists at the NAIC converged on the working assumptions driving this analysis. Primary interviews with engineering consultants, power utility procurement officers, and captive insurance managers were cross-validated against secondary sources including Solvency II regulatory filings, BIS structural safety code documentation, SEC insurance holding company disclosures, and project finance lender mandate databases. Bottom-up policy volume estimates were triangulated against top-down reinsurance capital allocation data.
Demand-supply balance modeling across the analysis window incorporated policy structure segmentation by project duration, coverage type granularity by asset criticality rating, and end-user procurement sophistication tiers. CAGRs were derived from premium volume trajectories modeled against foreign direct investment flows into Indonesian and Vietnamese infrastructure, equipment sensor network penetration rates in German manufacturing, and regulatory mandate adoption timelines for EU Green Deal alignment. Forecast inputs included climate resilience code upgrade schedules in Philippine coastal jurisdictions and National Infrastructure Pipeline project commissioning timelines in India.
Stress conditions across nat-cat reinsurance capacity availability, sensor data standardization progress, and actuarial talent succession were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory mandate enforcement intensity and foreign lender coverage requirement stability. Macroeconomic deviation in emerging market currencies, regulatory fragmentation across Solvency II and NAIC frameworks, or breakthroughs in equipment failure prediction algorithms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cannabis Crop Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Online Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Insurance Third Party Administrators Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
Canada House Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Financial Protection Market
Insurance
Parametric Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Takaful Market
Insurance
India Liability Insurance Market
Insurance
Fire Insurance Market