
 Asia-Pacific Surety Market | 2026-2036
Asia-Pacific Surety Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surety Market Insights
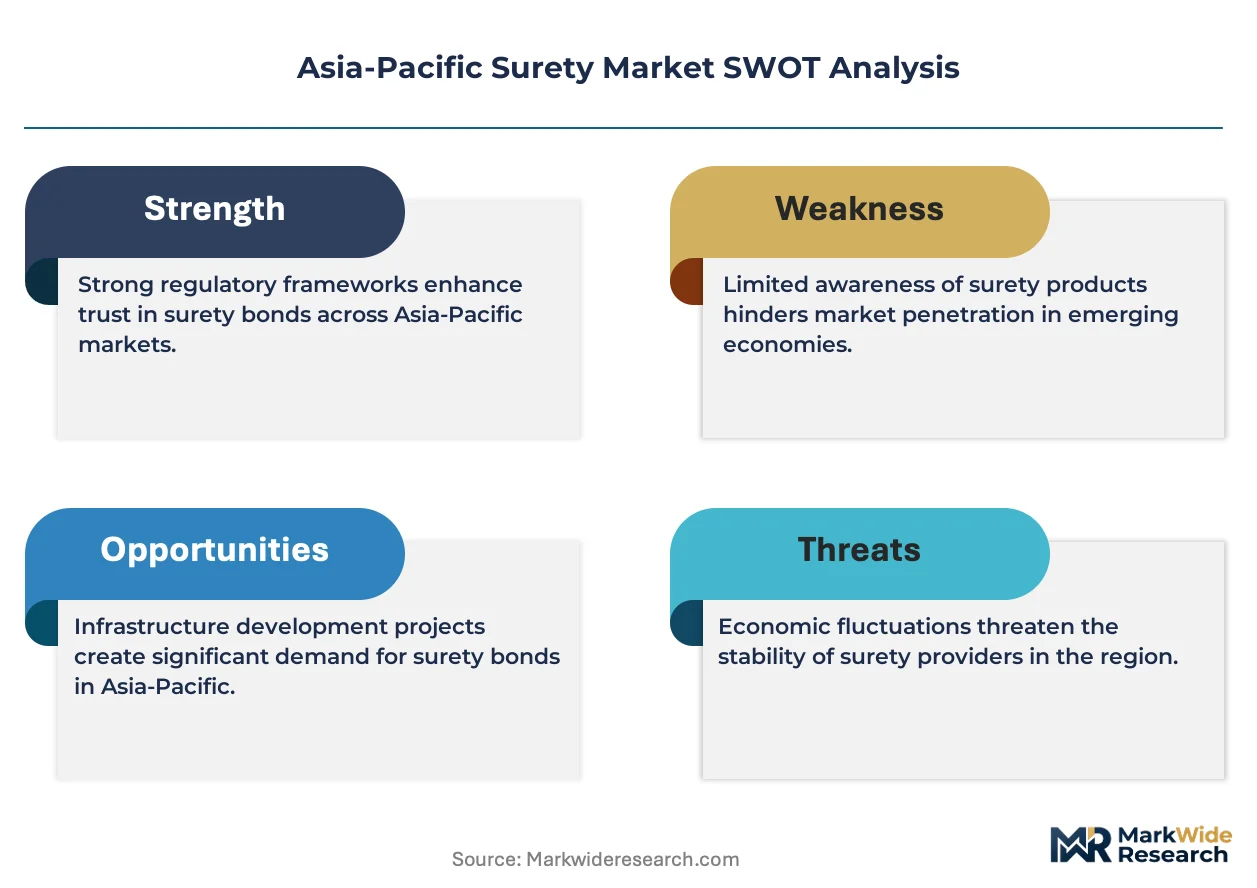
Digital documentation platforms are replacing paper-based bond issuance across the Asia-Pacific surety landscape, and this shift is realigning product economics toward faster underwriting cycles and lower administrative drag. Tokio Marine Holdings leverages its captive data infrastructure to pre-qualify contractors across Japan's public works pipeline. QBE Insurance Group Limited anchors its regional position through specialized mining surety products tailored to Australian resource projects. Liberty Mutual Group competes by extending facultative reinsurance arrangements that de-risk primary underwriters in emerging Southeast Asian markets.
Asia-Pacific surety denotes a tripartite guarantee instrument where the surety assumes obligation for a principal's performance or payment default to an obligee, typically structured with indemnity agreements, collateral thresholds, and claim reserves calibrated to project duration and counterparty credit quality. Contract surety dominates premium flows across the region given the scale of government-backed infrastructure procurement, while commercial surety is gaining traction fastest among small and medium enterprises seeking license and permit bonds. Judicial surety occupies a mature, lower-margin niche concentrated in court systems across India and the Philippines where litigation volumes sustain steady but unexceptional demand.
India's Ministry of Finance mandates surety bonds for all public works contracts exceeding prescribed value thresholds, while Australia's Australian Prudential Regulation Authority governs insurer capital adequacy for surety underwriters. Japan's Financial Services Agency requires segregation of surety reserves from general insurance liabilities, shaping product design and pricing discipline. Stakeholders must monitor how China's evolving bond insurance regulations and its national standardization administration's draft surety guidelines will reshape market access for foreign carriers operating through joint venture structures.
Market Dynamics
Digital documentation platforms are compressing underwriting cycles across the Asia-Pacific surety landscape, forcing incumbents to restructure legacy workflows or cede ground to technology-enabled competitors. This structural shift is redrawing product economics and elevating data infrastructure from cost center to competitive moat.
Growth Catalysts
- India's Ministry of Finance mandate:Mandatory surety bonds for public works contracts above value thresholds are institutionalizing demand across state and central government procurement pipelines.
- Contractor default protection:Australia's mining and energy corridors now require surety instruments as non-negotiable conditions for project finance approval, embedding surety into capital structures.
- Digital pre-qualification systems:Captive data infrastructure enables real-time contractor risk scoring, accelerating bond issuance velocity and reducing administrative overhead.
Market Restraints
- Collateral threshold rigidity:High collateral requirements exclude smaller contractors from contract surety markets, particularly in emerging Southeast Asian economies where asset bases are thin.
- Reserve segregation mandates:Japan's Financial Services Agency requires surety reserves to sit apart from general insurance liabilities, compressing capital flexibility and constraining product line expansion.
- Judicial surety margin compression:Court systems in India and the Philippines generate steady but low-margin volume, trapping capacity in mature, unprofitable segments.
Strategic Opportunities
- Vietnam and Indonesia infrastructure pipelines:Southeast Asian governments are accelerating transport and energy projects where foreign surety capacity remains underdeployed relative to financing needs.
- Commercial surety among SMEs:License and permit bonds for small and medium enterprises represent a fast-growing white space as regulatory compliance requirements proliferate across the region.
- API-enabled distribution:Embedded surety products through construction management software platforms are opening direct channels to contractors bypassing traditional broker networks.
Industry Challenges
- Legacy system integration friction:Incumbent insurers face substantial technical debt when connecting digital documentation platforms to decades-old policy administration systems.
- Specialized underwriting talent scarcity:Deep expertise in project finance risk assessment and construction sector credit analysis is concentrated among a shrinking cohort of senior practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surety Market |
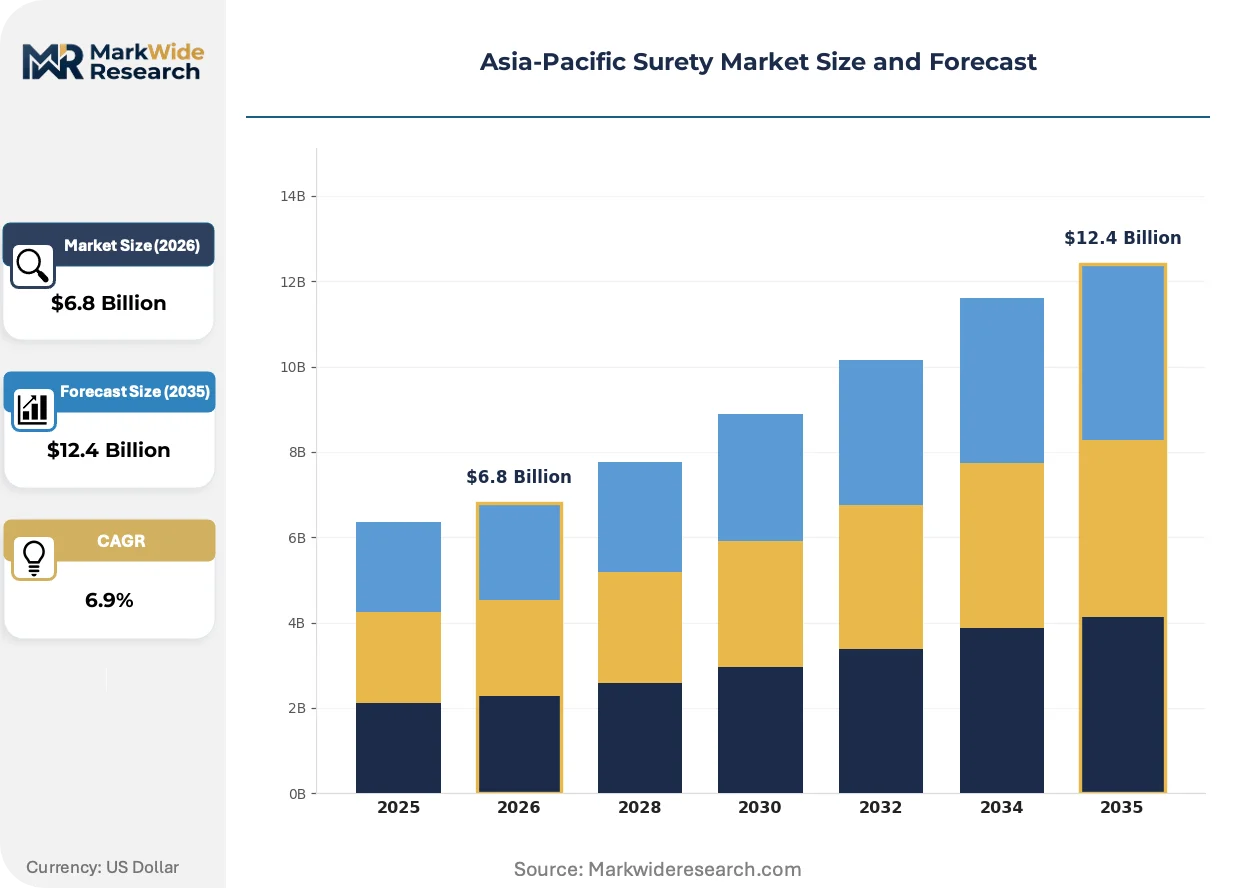
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.4 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Surety Type: Contract Surety, Commercial Surety, Judicial Surety, Fidelity Bonds Market Driver: Infrastructure Development, Public Projects, Private Sector Investments, Regulatory Requirements Industry Segment: Construction, Manufacturing, Transportation, Energy Client Type: Government Entities, Contractors, Suppliers, Service Providers |
| Companies Covered | Tokio Marine Holdings, AXA, Liberty Mutual Group, Intact Financial Corporation, QBE Insurance Group Limited, Chubb Limited, Allianz Trade, CNA Financial Corporation, Zurich Insurance Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surety Market Trends and Innovations
Technology, regulation, and procurement behavior are converging to restructure how surety products are designed, distributed, and consumed across the Asia-Pacific region. These shifts are compressing legacy value chains and elevating data-centric competitors.
Blockchain-enabled smart bonds are overtaking paper-based instruments in high-volume contract surety segments. Australian mining contractors and Japanese public works bidders are adopting these instruments to automate claim triggers and reduce intermediary verification delays. This compression of documentation and settlement layers is eliminating friction costs that previously sustained broker-centric distribution models.
Australia's Prudential Regulation Authority is tightening capital adequacy requirements for surety underwriters, forcing carriers to recalibrate risk selection and pricing discipline. The regulatory pressure is concentrating capacity among well-capitalized incumbents while marginalizing smaller players with thinner reserve buffers. Contract surety lines in Australian resource projects are experiencing the most acute capacity constraints as underwriters retreat to defensible credit profiles.
Project owners are unbundling surety procurement from general insurance placement, establishing standalone surety panels with direct digital interfaces. This behavioral shift is disintermediating traditional brokers in Singapore and Hong Kong infrastructure finance markets. Construction firms are responding by consolidating surety relationships with fewer carriers capable of delivering integrated risk analytics alongside bond instruments.
Asia-Pacific Surety Market Segmentation
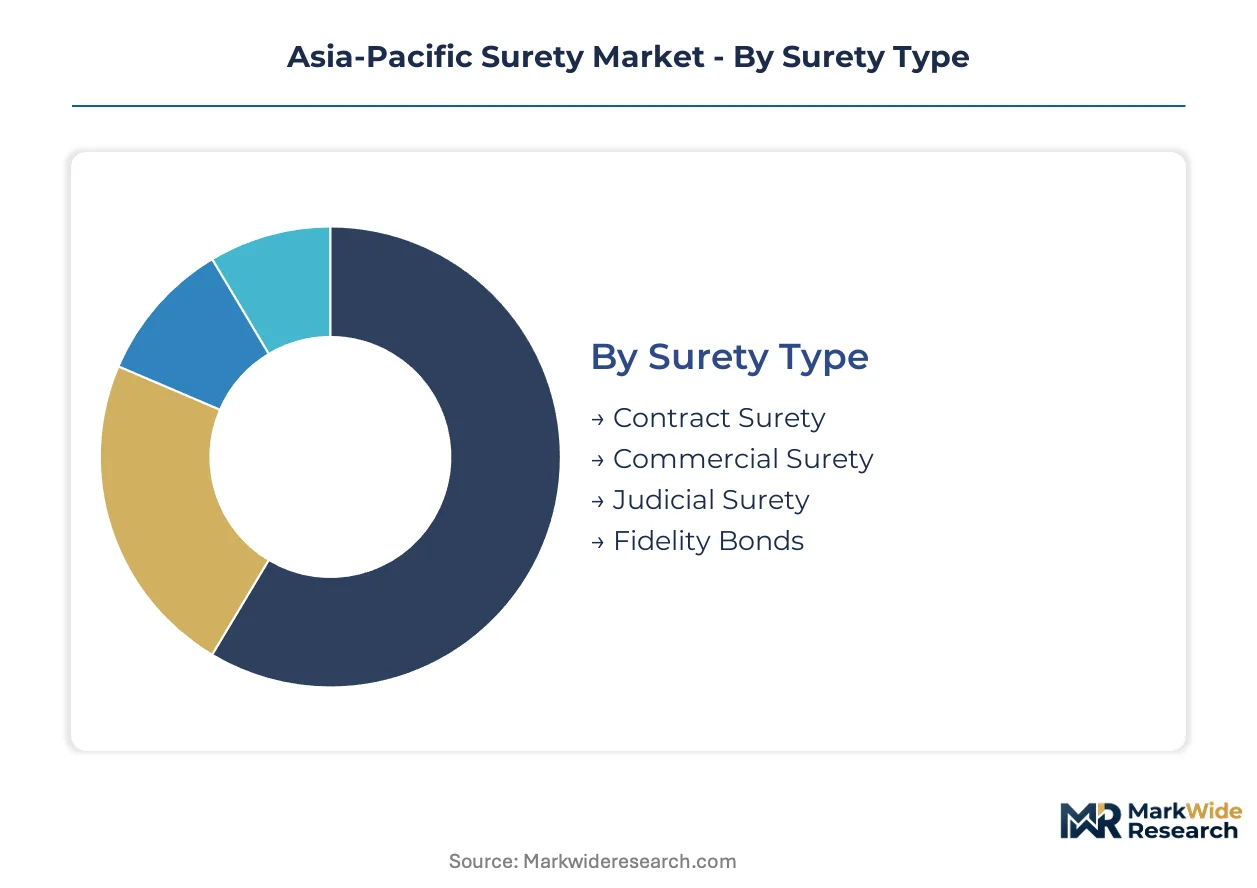
Surety instruments in Asia-Pacific fragment across guarantee purpose, procurement channel, and counterparty risk profile. Each segmentation axis reveals distinct pricing disciplines, collateral thresholds, and distribution economics that shape carrier strategy.
Surety Type:
Contract surety commands premium volumes through government procurement pipelines, while commercial surety and judicial instruments occupy divergent margin positions.
- Contract Surety:Tripartite guarantees covering contractor performance and payment obligations to project owners. India's Ministry of Finance mandates dominate demand flows across state and central public works contracts exceeding prescribed value thresholds.
- Commercial Surety:License, permit, and regulatory compliance bonds for private enterprises. SME compliance requirements across Southeast Asia are expanding fastest among non-contract segments as licensing regimes tighten.
- Judicial Surety:Court-ordered guarantees securing litigation outcomes or fiduciary appointments. India's and the Philippines' court systems sustain steady but compressed-margin volume with limited pricing power.
- Fidelity Bonds:Employee dishonesty coverage protecting employers from theft or fraud losses. Financial institutions and professional services firms in Singapore and Hong Kong anchor regional uptake.
Today's leader: Contract Surety. Tomorrow's challenger: Commercial Surety.
Market Driver:
Procurement origin determines bond structure, with public mandates institutionalizing demand and private investment cycles introducing volatility.
- Infrastructure Development:Transport, energy, and urban project pipelines across Vietnam, Indonesia, and the Philippines generate sustained contract surety placement. Multilateral development bank financing conditions increasingly embed surety requirements into loan covenants.
- Public Projects:Government procurement mandates in India and Australia create non-discretionary demand with standardized bond terms and collateral schedules. These instruments carry lower default frequency but compressed spreads due to competitive tendering.
- Private Sector Investments:Mining, energy, and real estate developments in Australia's resource corridors and Japan's industrial zones require customized surety structures. Project finance lenders treat surety as a condition precedent for financial close.
- Regulatory Requirements:Licensing authorities across the region mandate permit bonds for market entry. Compliance-driven placements exhibit high renewal rates and limited price sensitivity.
Public procurement provides volume stability. Private investment delivers margin expansion.
Industry Segment:
Sector risk profiles diverge sharply, with construction concentration exposing carriers to cyclical default waves and energy projects demanding specialized underwriting expertise.
- Construction:Contract surety penetration peaks here, covering bid bonds, performance guarantees, and payment obligations. Australia's mining-related construction and India's highway programs concentrate regional exposure.
- Manufacturing:Commercial surety for environmental compliance, customs bonds, and supply chain guarantees. Japanese automotive suppliers and South Korean electronics manufacturers drive structured instrument demand.
- Transportation:Logistics licensing, fleet operator permits, and port authority compliance bonds. Southeast Asian port modernization and aviation infrastructure expansion are climbing the fastest.
- Energy:Renewable project construction, decommissioning guarantees, and grid connection bonds. Australia's offshore wind pipeline and Japan's hydrogen infrastructure projects require long-duration surety capacity.
Construction anchors current premium. Energy infrastructure commands tomorrow's pricing power.
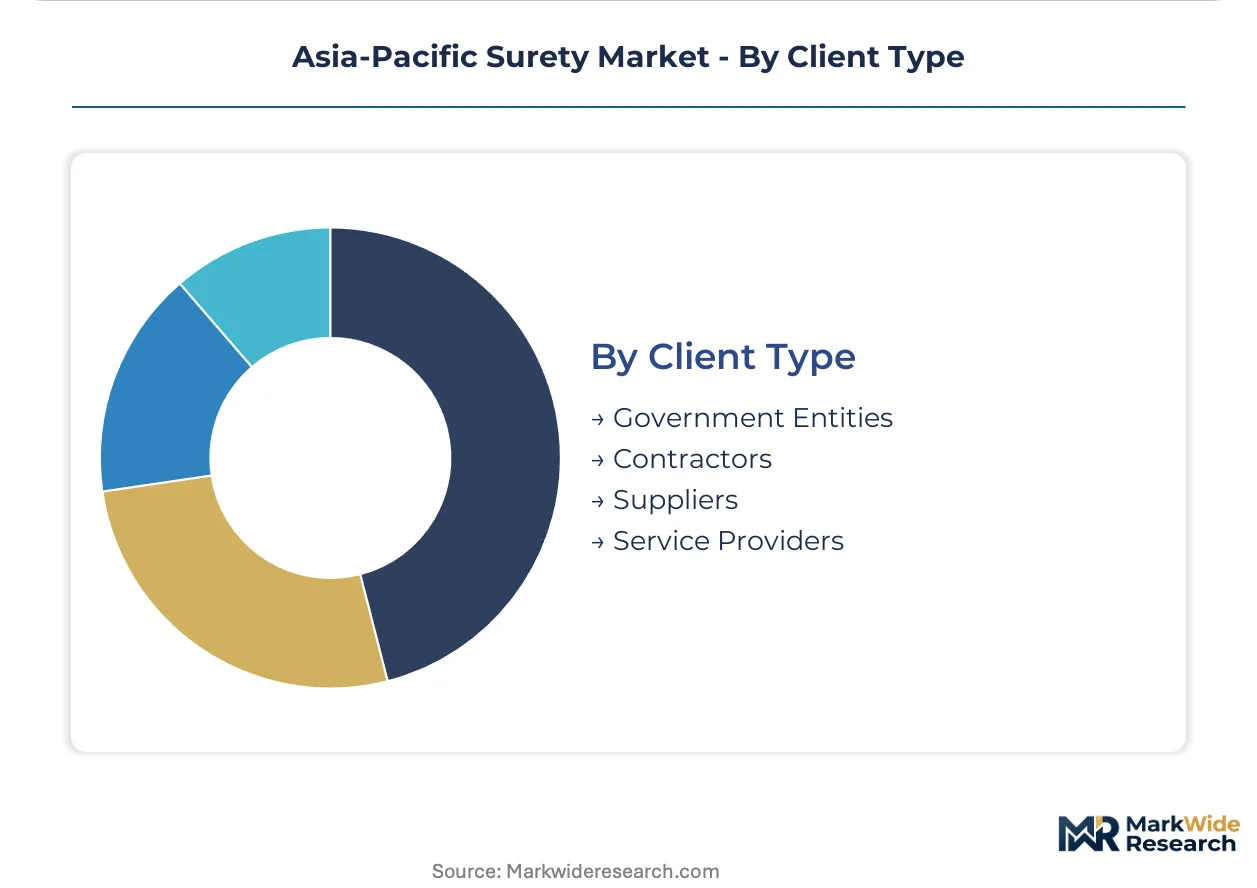
Client Type:
Counterparty sophistication shapes distribution economics, with government entities demanding streamlined digital interfaces and contractors requiring pre-qualification support.
- Government Entities:Central and state procurement agencies mandate standardized bond formats with digital submission portals. India's Ministry of Finance directives and Australia's state infrastructure authorities dominate placement volumes.
- Contractors:Construction firms seeking bid, performance, and payment bonds. Tier-one contractors with captive data infrastructure command preferential pricing; smaller builders face collateral exclusion.
- Suppliers:Material and equipment vendors requiring payment guarantees or advance payment bonds. Manufacturing supply chains in Japan and South Korea generate recurring commercial surety demand.
- Service Providers:Professional firms, consultants, and facility operators needing license bonds or fidelity coverage. Technology-enabled distribution is expanding fastest among this fragmented client base.
Government procurement delivers scale. Service provider segments promise distribution innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's mining and energy corridors anchor regional surety demand, with contractor default protection now embedded as a non-negotiable condition for project finance across the Asia-Pacific. Infrastructure procurement pipelines in India and Southeast Asian markets are tightening compliance standards and accelerating bond issuance velocity.
Australia
Mining construction and offshore wind development drive contract surety placement across Western Australia and Queensland. The Australian Prudential Regulation Authority tightens capital adequacy requirements for surety underwriters, compressing capacity among thinner reserve buffers. Perth-based resource contractors now mandate digital bond submission portals for bid, performance, and payment guarantees.
India
Highway programs and public works contracts institutionalize demand through central and state procurement pipelines. The Ministry of Finance mandates surety bonds for all contracts exceeding prescribed value thresholds, standardizing collateral schedules and bond formats. Construction activity concentrates in Maharashtra and Gujarat where state infrastructure authorities dominate placement volumes.
Japan
Public works bidding and industrial zone development sustain performance guarantee demand across Kanto and Kansai regions. The Financial Services Agency requires segregation of surety reserves from general insurance liabilities, constraining capital flexibility and product line expansion. Tokyo-based contractors leverage captive data infrastructure for real-time pre-qualification and accelerated bond issuance.
Vietnam
Transport and energy infrastructure pipelines generate sustained contract surety placement across northern and southern economic zones. Multilateral development bank financing conditions increasingly embed surety requirements into loan covenants for port modernization and highway construction. Ho Chi Minh City and Hanoi corridor projects attract foreign surety capacity that remains underdeployed relative to financing needs.
Singapore
Construction management platforms and financial services infrastructure enable API-enabled surety distribution to regional contractors. Project owners unbundle surety procurement from general insurance placement, establishing standalone panels with direct digital interfaces. Marina Bay and Jurong Island developments anchor commercial surety demand among professional firms and facility operators.
Asia-Pacific Surety Market Competitive Landscape
Digital pre-qualification systems dominate the current competitive landscape as carriers restructure legacy workflows to match technology-enabled rivals. The market concentrates among well-capitalized incumbents with captive data infrastructure, while smaller players face exclusion from high-volume contract surety segments. Three archetypes define positioning: diversified global carriers with regional surety specialization, domestic insurers leveraging public sector relationships, and technology-forward entrants compressing underwriting cycles through automated risk scoring. Competitive intensity centers on portfolio diversification into commercial surety and geographic expansion across underpenetrated Southeast Asian markets.
Within the diversified global tier, Tokio Marine Holdings and QBE Insurance Group Limited exemplify contrasting regional strategies. Tokio Marine leverages its Japanese domestic base and captive data infrastructure to pre-qualify contractors across public works pipelines. QBE anchors its position through specialized mining surety products tailored to Australian resource projects. Liberty Mutual Group occupies a distinct position by extending facultative reinsurance arrangements that de-risk primary underwriters in emerging Southeast Asian markets.
| Leading Market Players |
|---|
| Tokio Marine Holdings |
| AXA |
| Liberty Mutual Group |
| Intact Financial Corporation |
| QBE Insurance Group Limited |
| Chubb Limited |
| Allianz Trade |
| CNA Financial Corporation |
| Zurich Insurance Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed surety capacity in Japan and Australia anchors regional pricing discipline, with state-linked insurers leveraging preferential reserve treatment to undercut private carriers on public works contracts while extracting margin premiums from resource sector placements. This ownership pattern concentrates supply-side pricing power among well-capitalized incumbents and forces mid-tier competitors toward collateral-heavy, lower-margin commercial surety segments.
Pricing Analysis
Collateral cost pass-through dominates contract surety pricing, with Japan's Financial Services Agency reserve segregation requirements and Australia's APRA capital adequacy rules elevating cost bases for compliant carriers. Premium-mid-economy pricing differentiation separates Tier 1 contractors with captive data infrastructure from smaller builders facing 100% collateral calls. Pricing pressure stems from digital documentation platforms compressing underwriting cycles and eroding broker-mediated margin layers. Government procurement entities exhibit lowest price sensitivity given mandatory bond requirements, while SME commercial surety buyers demonstrate highest elasticity to premium movements.
Supply Chain Analysis
Certification gating through Japan's JIS standards and Australia's APRA prudential framework restricts surety capacity to licensed insurers with segregated reserves and minimum capital thresholds. Supply concentrates among Tokyo, Sydney, and Singapore underwriting hubs drawing from reinsurance capacity in Bermuda and London. Raw material dependencies include actuarial data infrastructure, credit scoring algorithms, and legal documentation templates. Single-source vulnerability runs through proprietary contractor pre-qualification databases held by Tokio Marine and QBE. Distribution runs through broker networks for contract surety and API-enabled platforms for commercial surety segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific surety functions as a geographic-arbitrage play where India's Ministry of Finance mandates create non-discretionary demand at compressed spreads, while Australian resource projects deliver premium pricing for specialized default protection. Regulatory divergence between Japan's reserve segregation and Southeast Asia's lighter touch generates cost-structure dispersion.
For Market Incumbents: To counter technology-enabled entrants compressing underwriting cycles, incumbents must accelerate captive data infrastructure deployment for real-time contractor pre-qualification and secure exclusive panel appointments with Singapore and Hong Kong project owners unbundling surety from general insurance placement. Backward integration into construction management software platforms anchors distribution control against API-enabled disintermediation. For New Entrants and Emerging Players: The 200-400 basis point spread gap between premium mining surety and economy-tier judicial bonds in the Philippines and India creates entry opportunity. White space concentrates in Vietnam and Indonesia infrastructure pipelines where foreign capacity remains underdeployed relative to multilateral development bank financing conditions. Embedded surety products through contractor procurement platforms offer direct channel access bypassing established broker networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier domestic insurers with concentrated public sector relationships and legacy policy administration systems requiring modernization. Long-term viability hinges on digital transformation execution and geographic diversification beyond single-market regulatory dependence. The signal to watch is APRA or Japan FSA relaxation of reserve segregation mandates, which would compress well-capitalized incumbents' structural cost advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pre-Qualification Platform Deployment | Tokio Marine's captive data infrastructure accelerates bond issuance velocity across Japan's public works pipeline. |
| Mining Surety Product Specialization | QBE anchors regional position through tailored default protection for Western Australian resource projects. |
| API-Enabled Distribution Partnership | Singapore construction management platforms open direct contractor channels bypassing traditional broker networks. |
| Facultative Reinsurance Arrangement Extension | Liberty Mutual de-risks primary underwriters in emerging Southeast Asian markets with thinner capital buffers. |
| Commercial Surety SME Segment Expansion | License and permit bond demand proliferates across Indonesia and Vietnam as regulatory compliance regimes tighten. |
Research Methodology
Multiple input streams — senior underwriters at global surety carriers, project finance lenders at Australian resource banks, procurement officers at India's Ministry of Finance, and regulatory affairs leads at Japan's Financial Services Agency — were reconciled against secondary validation from APRA prudential filings, Japan FSA regulatory circulars, multilateral development bank procurement guidelines, and construction sector credit databases. Bottom-up premium aggregation across contract, commercial, and judicial surety segments was cross-referenced with top-down market sizing from insurer regulatory returns.
Historical premium trajectories were cross-referenced against panel input from surety executives and project finance practitioners to calibrate growth assumptions across the projection horizon. Segmentation dimensions modeled include surety type, procurement channel, industry vertical, and client sophistication tier. CAGRs were derived from trend extrapolation adjusted for regulatory mandate timing and infrastructure pipeline visibility. Industry-specific forecast inputs encompass India's highway program contract awards and Australia's offshore wind development financing conditions.
Caveats apply where China's evolving bond insurance regulations or national standardization administration draft surety guidelines could materially shift market access conditions for foreign carriers. Forecasts reflect assumptions regarding continued infrastructure procurement momentum and stable regulatory capital treatment. A model refresh is warranted upon material change in India's Ministry of Finance mandate scope or APRA capital adequacy recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Engineering Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Endowment Insurances Market
Insurance
Parametric Insurance Market
Insurance
India Dental Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Property Insurance Market
Insurance
Cancer Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Online Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Medical Claims Processing Services Market