
 Telecommunication Insurance Market | 2026-2036
Telecommunication Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Telecommunication Insurance Market Analytics
GDPR's extraterritorial reach into telecom data governance is consolidating the cost-of-entry calculus for insurers underwriting European network operators. Allianz SE leverages its industrial risk engineering heritage to dominate large-tower portfolio coverage across Continental Europe. Chubb Limited anchors its competitive position through specialized equipment breakdown policies tailored to base station and switching facility exposures. Zurich Insurance Group Ltd. competes by extending captive reinsurance structures that absorb catastrophic natural peril concentrations in hurricane-prone coastal markets.
Telecommunication insurance encompasses risk transfer instruments designed to indemnify physical infrastructure assets, revenue streams, and third-party liabilities inherent to voice, data, and broadcast network operations, with policies typically specifying replacement-cost valuation for cell towers, fiber optic cable, and switching equipment subject to per-site deductibles ranging from fifty thousand to two million dollars. The primary commercial purpose centers on stabilizing capital expenditure planning for network operators facing correlated geographic perils and technology obsolescence cycles. Cybersecurity service type leads premium generation as ransomware frequency against signaling infrastructure escalates, while equipment damage coverage retains the densest margin pool due to specialized appraisal requirements and limited standardization. Network operators within customer type represent the fastest-growing buyer segment as 5G capital intensity drives lenders to mandate comprehensive property and business interruption covenants.
FCC outage reporting rules in the United States, the EU's DORA framework, and Japan's METI critical infrastructure guidelines collectively reshape product standards by mandating demonstrable resilience investments as preconditions to insurability. EMA and national cyber regulators increasingly embed insurance adequacy into operating license conditions, directly conditioning market access on carrier proof of coverage. Stakeholders must monitor whether emerging quantum encryption standards trigger policy exclusion revisions before retrofitting obligations crystallize.
Market Dynamics
5G network densification is compressing carrier capital cycles and forcing synchronized coverage upgrades across tower portfolios, while the EU's DORA framework mandates cyber resilience investments as binding license conditions.
Growth Catalysts
- FCC outage reporting mandates:US carriers face escalating penalties for service interruptions, driving demand for business interruption riders that indemnify revenue losses during network failures.
- Signaling infrastructure ransomware:Attack frequency against SS7 and Diameter protocols compels underwriters to develop specialized cyber policies with named-peril exclusions for protocol-specific vulnerabilities.
- Germany's fiber rollout obligations:Spectrum license conditions require universal coverage guarantees, bundling property and liability coverage into carrier financing covenants.
Market Restraints
- Specialized appraisal scarcity:Base station and switching equipment valuations require electromagnetic interference testing and thermal load modeling that few adjusters can perform, elongating claims resolution.
- Natural peril concentration:Coastal tower portfolios in Florida and Gulf Coast states accumulate correlated hurricane exposure that reinsurers increasingly cap or exclude.
- Quantum encryption uncertainty:NIST post-quantum cryptographic standards remain in draft, preventing underwriters from pricing retroactive exclusion clauses for algorithmic obsolescence.
Strategic Opportunities
- India's Smart Cities Mission:Municipal fiber backbone deployments create first-mover positions for insurers bundling cyber-physical coverage for integrated command centers.
- Parametric wind speed triggers:Index-based settlement structures bypass traditional loss adjustment for tower damage, compressing payout cycles from months to days.
- Japan METI critical infrastructure guidelines:Mandatory resilience certifications for submarine cable landing stations open captive insurance structures for consortium operators.
Industry Challenges
- RF engineer talent scarcity:Underwriting teams lack personnel capable of assessing electromagnetic compatibility risks between 5G mmWave arrays and legacy aviation radar systems.
- Multi-jurisdictional claims coordination:Submarine cable faults spanning territorial waters trigger conflicting national liability regimes that delay settlement and inflate legal costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecommunication Insurance Market |
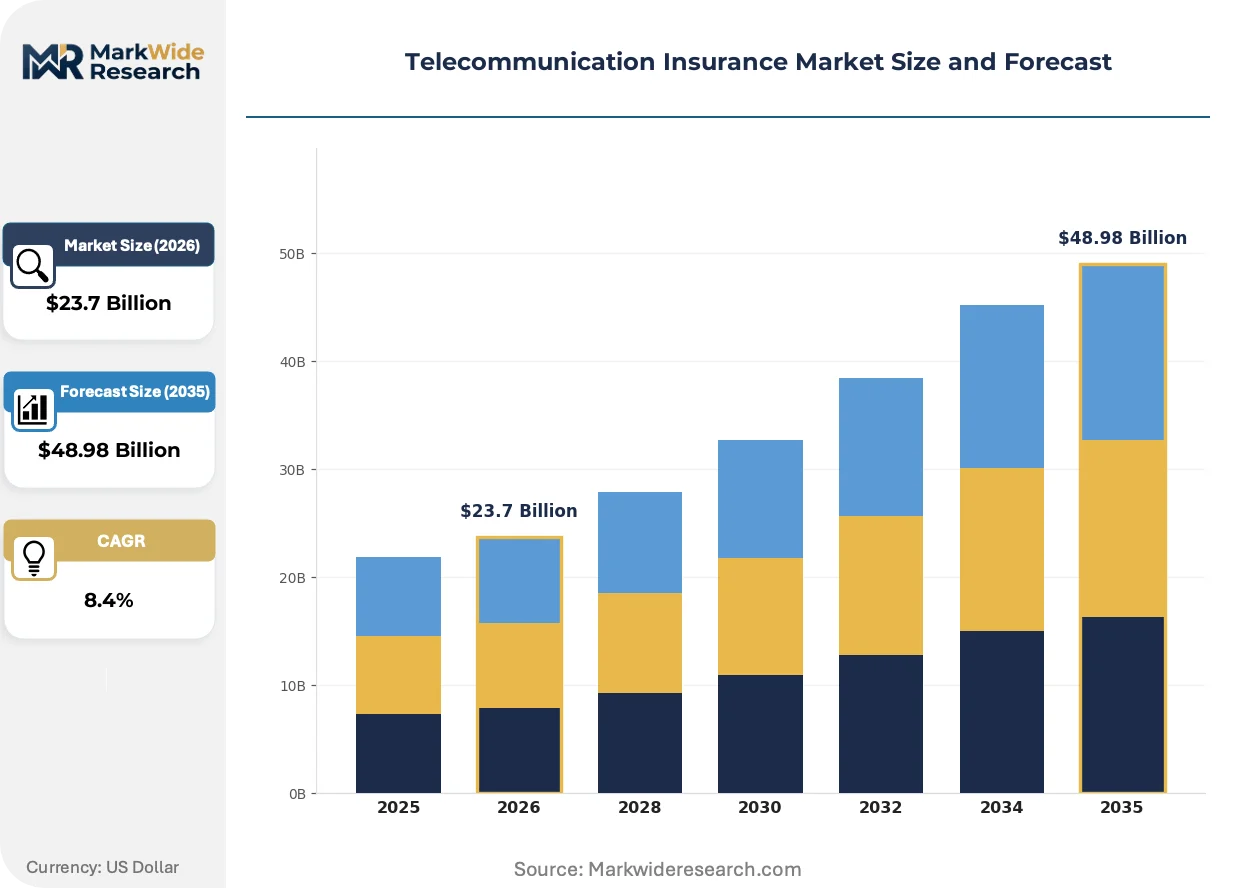
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cybersecurity, Property Insurance, Business Interruption, Equipment Damage Customer Type: Service Providers, Network Operators, Resellers, Enterprises Coverage Type: Liability Coverage, Equipment Coverage, Fleet Coverage, Data Breach Coverage Distribution Channel: Direct Sales, Brokers, Online Platforms, Agencies |
| Companies Covered | The Travelers Companies Inc., Aon PLC, Allianz SE, Arthur J. Gallagher & Co., CNA Financial Corporation, Zurich Insurance Group Ltd., Sompo International Holdings Ltd., Chubb Limited, Liberty Mutual Insurance Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecommunication Insurance Market Evolving Landscape
Telecommunication insurance products are fragmenting into modular, event-triggered instruments that separate physical asset coverage from revenue protection and cyber liability, enabling carriers to unbundle and rebalance risk portfolios quarterly.
AI-powered predictive maintenance platforms are consolidating underwriting workflows by ingesting real-time tower sensor data—vibration, thermal, and power draw metrics—to dynamically adjust premiums based on demonstrated infrastructure health. Tower operators in Germany and the Netherlands are piloting these telemetry-linked policies, with underwriters reducing rates by fifteen to twenty percent for sites meeting predictive reliability thresholds. This sensor-integration is consolidating risk selection around carriers with capital reserves to absorb correlated tower-cluster failures.
The EU's Digital Operational Resilience Act is consolidating compliance burdens across Continental Europe by requiring telecom operators to demonstrate insurance adequacy as a precondition for operating licenses. National regulators in France, Italy, and Spain are embedding DORA's cyber coverage minimums into spectrum auction terms, forcing bidders to pre-commit policy structures before network build-out begins. Mid-sized carriers without captive reinsurance capabilities face exclusion from license pools.
Buyers are consolidating procurement around multi-year master policies that aggregate property, cyber, and business interruption coverage under single deductible structures. Japanese mobile network operators pioneered this bundled approach following METI's 2023 critical infrastructure guidelines, and the model is displacing siloed annual renewals in South Korea and Australia. Towercos with geographically diversified portfolios leverage this consolidation to negotiate rate caps that freeze premiums across three-year capital expenditure cycles.
Telecommunication Insurance Market Segmentation
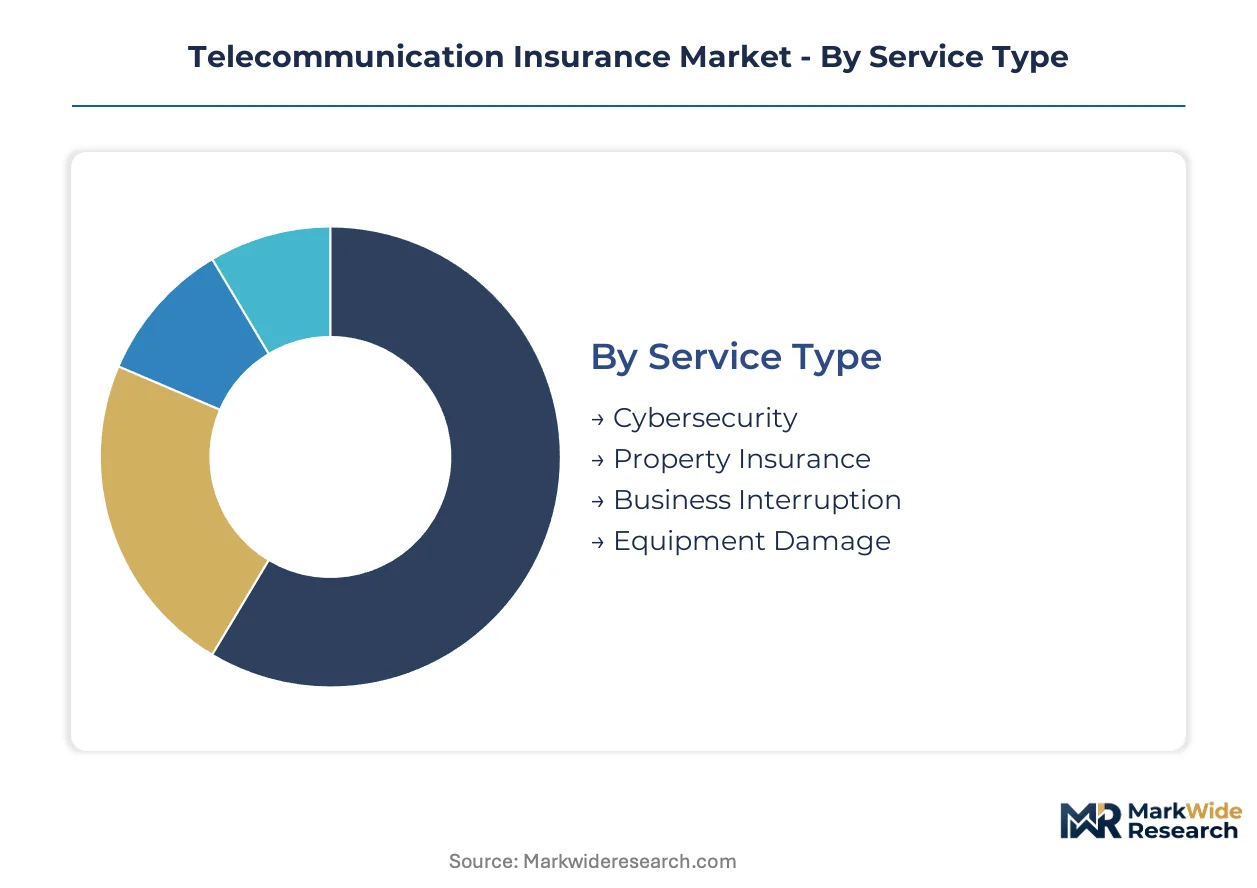
Telecommunication insurance products fragment across four structural dimensions that determine pricing granularity and underwriting complexity. Service type and customer type classifications drive premium volume concentration, while coverage type and distribution channel configurations shape margin capture and claims velocity.
Service Type:
Cybersecurity commands the largest premium pool by value, though equipment damage retains the densest underwriting margins due to specialized appraisal requirements.
- Cybersecurity:Policies indemnify network operators against ransomware attacks targeting SS7 and Diameter signaling protocols, with named-peril exclusions for protocol-specific vulnerabilities. Demand concentrates acutely in Germany and the Netherlands where DORA mandates cyber resilience investments as binding license conditions.
- Equipment Damage:Coverage specifies replacement-cost valuation for cell towers, fiber optic cable, and switching equipment subject to per-site deductibles ranging from fifty thousand to two million dollars. German tower operators bundle this coverage into spectrum license financing covenants, compressing capital expenditure planning cycles.
- Property Insurance:Physical infrastructure policies covering tower real estate and switching facilities against fire, theft, and natural perils.
- Business Interruption:Revenue protection riders indemnifying carriers against service outage losses, increasingly mandated by FCC reporting rules in the United States.
Mature deployment sits with equipment damage. Newer deployment is concentrated in cybersecurity.
Customer Type:
Network operators generate the steepest premium expansion trajectory as 5G capital intensity drives lenders to mandate comprehensive coverage covenants.
- Network Operators:Mobile carriers and fixed-line providers building proprietary infrastructure face correlated geographic perils and technology obsolescence cycles that demand synchronized coverage upgrades across tower portfolios. Japanese operators under METI guidelines pioneered multi-year master policies aggregating property, cyber, and business interruption coverage.
- Service Providers:Wholesale bandwidth and managed service vendors requiring liability protection for third-party network dependencies. Towercos with geographically diversified portfolios leverage bundled procurement to negotiate rate caps freezing premiums across three-year capital expenditure cycles.
- Enterprises:Corporate entities self-provisioning private 5G networks and edge computing infrastructure.
- Resellers:Virtual network operators and MVNOs purchasing contingent business interruption coverage against host network failures.
Procurement consolidation favors network operators. Margin compression hits resellers.
Coverage Type:
Liability coverage and equipment coverage split the market by risk transfer mechanism, with data breach coverage emerging as the fastest-climbing premium category.
- Liability Coverage:Third-party protection against subscriber data exposure and service outage claims, with GDPR's extraterritorial reach tightening cost-of-entry calculus for European network operators. French, Italian, and Spanish regulators embed coverage adequacy into spectrum auction terms.
- Equipment Coverage:First-party indemnification for base station and switching facility assets requiring electromagnetic interference testing and thermal load modeling during claims adjustment.
- Data Breach Coverage:Specialized riders covering forensic investigation costs, regulatory notification expenses, and credit monitoring services for affected subscribers.
- Fleet Coverage:Mobile equipment policies protecting service vehicles and portable cell-on-wheels deployments used for emergency network restoration.
Standardized terms govern equipment coverage. Bespoke structuring dominates data breach coverage.
Distribution Channel:
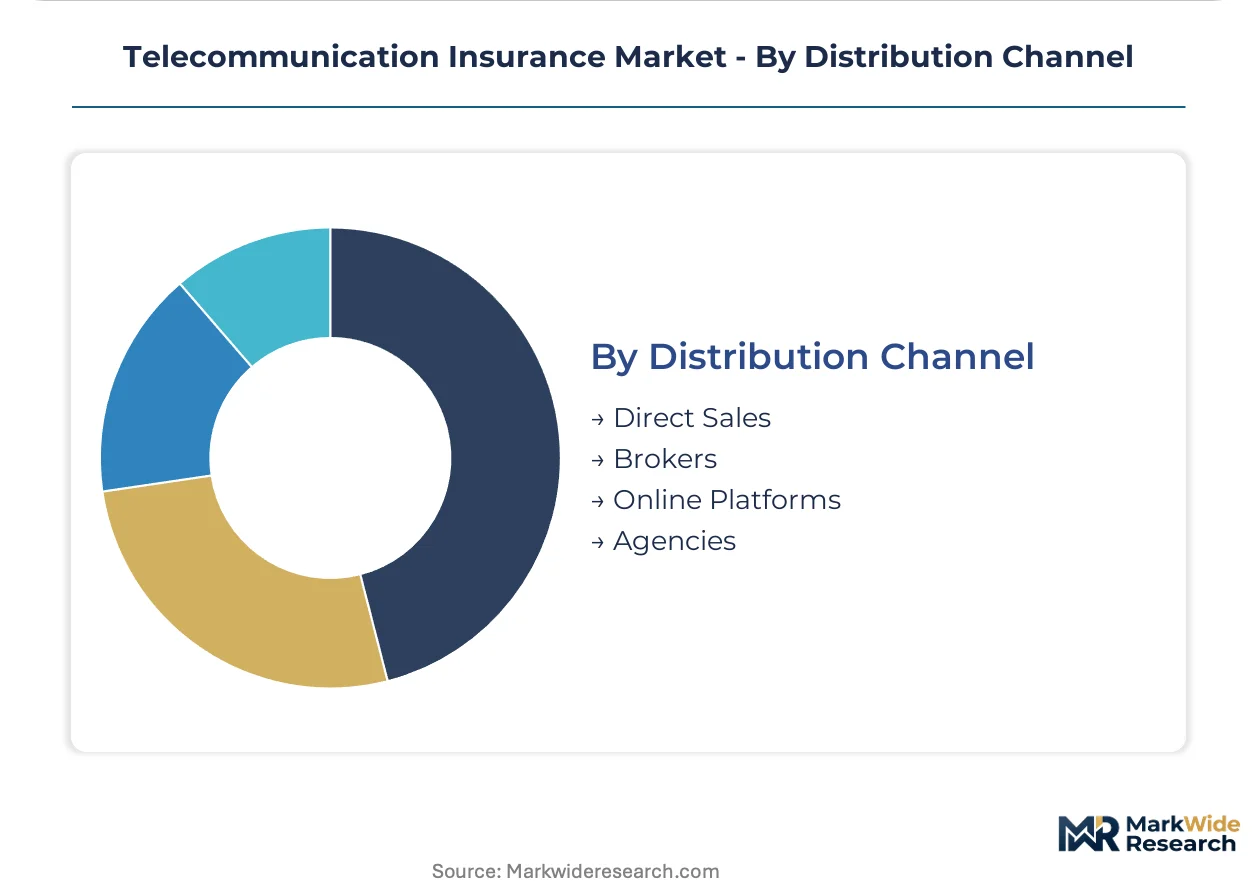
Broker intermediation retains premium placement dominance for complex tower portfolios, while direct sales channels capture standardized cyber policy volumes.
- Brokers:Intermediaries structuring multi-year master policies with single deductible aggregations for towercos and multinational carriers. Broker relationships consolidate around industrial risk engineering capabilities in Continental Europe.
- Direct Sales:Carrier-direct underwriting for cyber policies and equipment breakdown coverage with standardized peril schedules. Online platforms displace agency placement for small-tower portfolios in South Korea and Australia.
- Agencies:Captive and independent agents serving regional carriers with localized natural peril expertise.
- Online Platforms:Digital placement engines enabling real-time premium quoting for parametric wind speed trigger products.
Relationship intensity clusters with brokers. Transaction velocity concentrates in online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the steepest premium expansion as fiber rollout obligations and spectrum license conditions force carriers to bundle property and business interruption policies into financing covenants. Tower operators across the Rhine-Ruhr corridor and Bavaria are synchronizing coverage upgrades with 5G densification timelines.
United States
FCC outage reporting mandates drive demand for business interruption riders that indemnify revenue losses during network failures. Carriers face escalating penalties for service interruptions, compressing procurement cycles for comprehensive coverage. Tower portfolios in Florida and Gulf Coast states accumulate correlated hurricane exposure that reinsurers increasingly cap.
Japan
METI critical infrastructure guidelines mandate resilience certifications for submarine cable landing stations, opening captive insurance structures for consortium operators. Mobile network operators pioneered multi-year master policies aggregating property, cyber, and business interruption coverage under single deductible structures. Tokyo-Osaka corridor operators leverage bundled procurement to negotiate rate caps freezing premiums across three-year capital expenditure cycles.
Netherlands
Tower operators pilot telemetry-linked policies where AI-powered predictive maintenance platforms adjust premiums based on real-time sensor data. Underwriters reduce rates by fifteen to twenty percent for sites meeting predictive reliability thresholds. Rotterdam-Amsterdam logistics clusters concentrate specialized risk engineering capabilities for electromagnetic interference testing.
India
Municipal fiber backbone deployments under the Smart Cities Mission create first-mover positions for insurers bundling cyber-physical coverage for integrated command centers. TRAI spectrum allocation rules increasingly embed insurance adequacy into operating license conditions. Bengaluru and Hyderabad technology corridors concentrate tower portfolio diversification strategies.
France
ANSM and national cyber regulators embed DORA's cyber coverage minimums into spectrum auction terms, forcing bidders to pre-commit policy structures before network build-out begins. Mid-sized carriers without captive reinsurance capabilities face exclusion from license pools. Paris-Saclay research clusters concentrate quantum encryption uncertainty assessments for policy exclusion revisions.
Telecommunication Insurance Market Competitive Landscape
Continental European insurers anchor one tier; North American brokers and underwriters hold specialized positions in cyber liability and equipment breakdown coverage. The market structures around industrial risk engineering heritage, captive reinsurance capabilities, and parametric product innovation. Three archetypes dominate: diversified multi-line carriers with tower portfolio expertise, specialist cyber underwriters with signaling infrastructure focus, and broker intermediaries structuring multi-year master policies. Competitive moves concentrate on telemetry-linked policy development and captive reinsurance expansion for natural peril concentration.
Within the diversified carrier tier, Allianz SE and Zurich Insurance Group Ltd. represent established positions in large-tower portfolio coverage across Continental Europe. Chubb Limited occupies a specialist position in equipment breakdown policies tailored to base station and switching facility exposures. These three companies exemplify the strategic emphasis on industrial risk engineering capabilities and captive reinsurance structures that absorb catastrophic natural peril concentrations in coastal markets.
| Leading Market Players |
|---|
| The Travelers Companies Inc. |
| Aon PLC |
| Allianz SE |
| Arthur J. Gallagher & Co. |
| CNA Financial Corporation |
| Zurich Insurance Group Ltd. |
| Sompo International Holdings Ltd. |
| Chubb Limited |
| Liberty Mutual Insurance Company |
| Others |
Value Network & Pricing Analysis
Towercos with geographically diversified portfolios concentrate procurement leverage, compressing premium rates through multi-year master policy aggregation that bundles property, cyber, and business interruption coverage under single deductible structures.
Pricing Analysis
Short lead-time coverage for emergency network restoration commands substantial premium loading, while spot inventory policies for standard equipment damage settle at discounted rates. Three-tier pricing structure across premium, standard, and economy levels segments buyers by captive reinsurance capability and portfolio scale, with DORA-mandated cyber minimums forcing mid-sized carriers into premium tiers regardless of loss history. Cost compression in standard equipment coverage is intensifying because electromagnetic interference testing and thermal load modeling create specialized appraisal scarcity that elongates claims resolution. Resellers and virtual network operators exhibit acute price sensitivity, whereas Japanese mobile network operators under METI guidelines demonstrate rate cap tolerance across three-year capital expenditure cycles.
Supply Chain Analysis
Dual-sourcing requirements for reinsurance capacity mandate that primary underwriters qualify multiple catastrophe bond sponsors and retrocession panels, particularly for Florida and Gulf Coast hurricane exposure. Supply concentrates in Germany, the United States, and Japan for specialized risk engineering capabilities and captive insurance structuring. Raw material dependencies include electromagnetic compatibility testing equipment, thermal load modeling software, and real-time tower sensor telemetry platforms. Single-source vulnerability sits with RF engineer talent capable of assessing mmWave array interference risks. Distribution runs through broker intermediaries for complex tower portfolios and direct sales channels for standardized cyber policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecommunication insurance is becoming a vertical-integration race where underwriting profitability hinges on captive reinsurance structures and in-house predictive maintenance platform development.
For Market Incumbents: Extend telemetry-linked policy offerings by integrating AI-powered predictive maintenance platforms that adjust premiums based on real-time tower sensor data, defending against emerging InsurTech entrants with capital-light parametric products. Deepen backward integration into captive reinsurance structures for catastrophic natural peril concentrations, particularly hurricane-exposed coastal portfolios where third-party retrocession capacity is tightening. For New Entrants and Emerging Players: Launch via online platforms targeting parametric wind speed trigger products for small-tower portfolios in South Korea and Australia, where transaction velocity concentrates and relationship intensity requirements are minimal. White-space opportunities sit with municipal fiber backbone deployments under India's Smart Cities Mission, where cyber-physical coverage bundling for integrated command centers remains underpenetrated by established carriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized carriers with spectrum license exposure in France, Italy, and Spain where DORA compliance costs are forcing exits from license pools. Long-term viability centers on underwriting teams with RF engineering capabilities and demonstrated predictive reliability threshold pricing. Watch quantum encryption standard finalization as the signal for policy exclusion revision cycles that will trigger retrofitting obligation crystallization and coverage repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-Linked Policy Development | AI-powered predictive maintenance platforms enable dynamic premium adjustment based on real-time tower sensor data from German and Dutch pilots. |
| Captive Reinsurance Expansion | In-house catastrophe capacity absorption reduces dependency on third-party retrocession for hurricane-exposed Florida and Gulf Coast portfolios. |
| Parametric Product Innovation | Index-based wind speed triggers compress payout cycles from months to days for tower damage claims across coastal markets. |
| Multi-Year Master Policy Structuring | Single deductible aggregation across property, cyber, and business interruption coverage locks in rate caps for Japanese mobile operators. |
| Specialized Risk Engineering Investment | Electromagnetic interference testing capabilities in Rotterdam-Amsterdam clusters differentiate Continental European underwriting margins. |
Research Methodology
Document review covered regulatory filings from FCC, METI, and EU DORA implementation texts, complemented by interviews with underwriting directors at diversified multi-line carriers, broker intermediaries structuring multi-year master policies, tower portfolio risk managers, and predictive maintenance platform engineers. Secondary validation drew from EIOPA insurance statistics, NAIC market conduct examinations, reinsurance treaty term sheets, and tower sensor telemetry disclosure reports. Bottom-up policy-level data triangulated against top-down premium pool estimates across service type and customer type segmentations.
Historical premium growth trajectories cross-referenced against panel input from industry stakeholders informed the analytical framework across the analysis window. Segmentation dimensions modeled include service type, customer type, coverage type, and distribution channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived through regression analysis of capital expenditure cycle synchronization and mandated coverage covenant expansion. Forecast inputs incorporated 5G densification timelines and spectrum license condition evolution.
Quantum encryption standard finalization, NIST post-quantum cryptographic timeline shifts, and reinsurer appetite for correlated hurricane exposure are the dominant revision risks to premium pool projections. Deviation in quantum encryption standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Life and Non-Life Insurance Market
Insurance
Financial Protection Market
Insurance
Intellectual Property Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Insurance Claims Services Market
Insurance
Workers Compensation Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Microinsurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
UK Travel Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
US Travel Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
AI in Insurance Market