
 Employee Benefit Broker Market | 2026-2036
Employee Benefit Broker Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Benefit Broker Market Analytics
Digital enrollment platforms are restructuring traditional broker economics by displacing paper-based benefits administration with API-connected HRIS integrations. Mercer leverages its consulting heritage to anchor large-account relationships across Fortune 500 employers. Arthur J. Gallagher & Co. competes through decentralized agency ownership that sustains local market responsiveness. Aon differentiates via proprietary analytics tools that extend risk-assessment capabilities beyond standard brokerage.
An employee benefit broker is a licensed intermediary that designs, negotiates, and administers employer-sponsored benefit programs, typically operating under ERISA fiduciary standards and state insurance codes. The broker evaluates carrier networks, plan designs, and cost-sharing structures to optimize coverage against employer budgets and workforce demographics. Health insurance dominates service-type revenue due to premium volume and annual renewal complexity. Small businesses represent the fastest-expanding client type as ACA marketplace rules and state mandates push sub-fifty-employee firms toward formal broker relationships. Virtual services and online platforms are capturing margin pools previously held by in-person consulting, particularly for routine enrollment and claims support.
ERISA regulations enforced by the Department of Labor impose fiduciary disclosure requirements that shape broker compensation transparency and plan sponsor liability. State insurance departments and the IRS jointly govern tax-qualified retirement plans and premium tax incentives, creating multi-layer compliance obligations that drive employer reliance on specialized brokerage expertise. Stakeholders must monitor how the SECURE Act provisions and emerging state-level public-option legislation reshape the boundary between broker advisory and fiduciary roles.
Market Dynamics
API-connected HRIS platforms are compressing traditional broker commission structures by automating enrollment workflows that previously required manual intervention. This technology shift forces intermediaries to reposition around advisory services rather than transactional placement.
Growth Catalysts
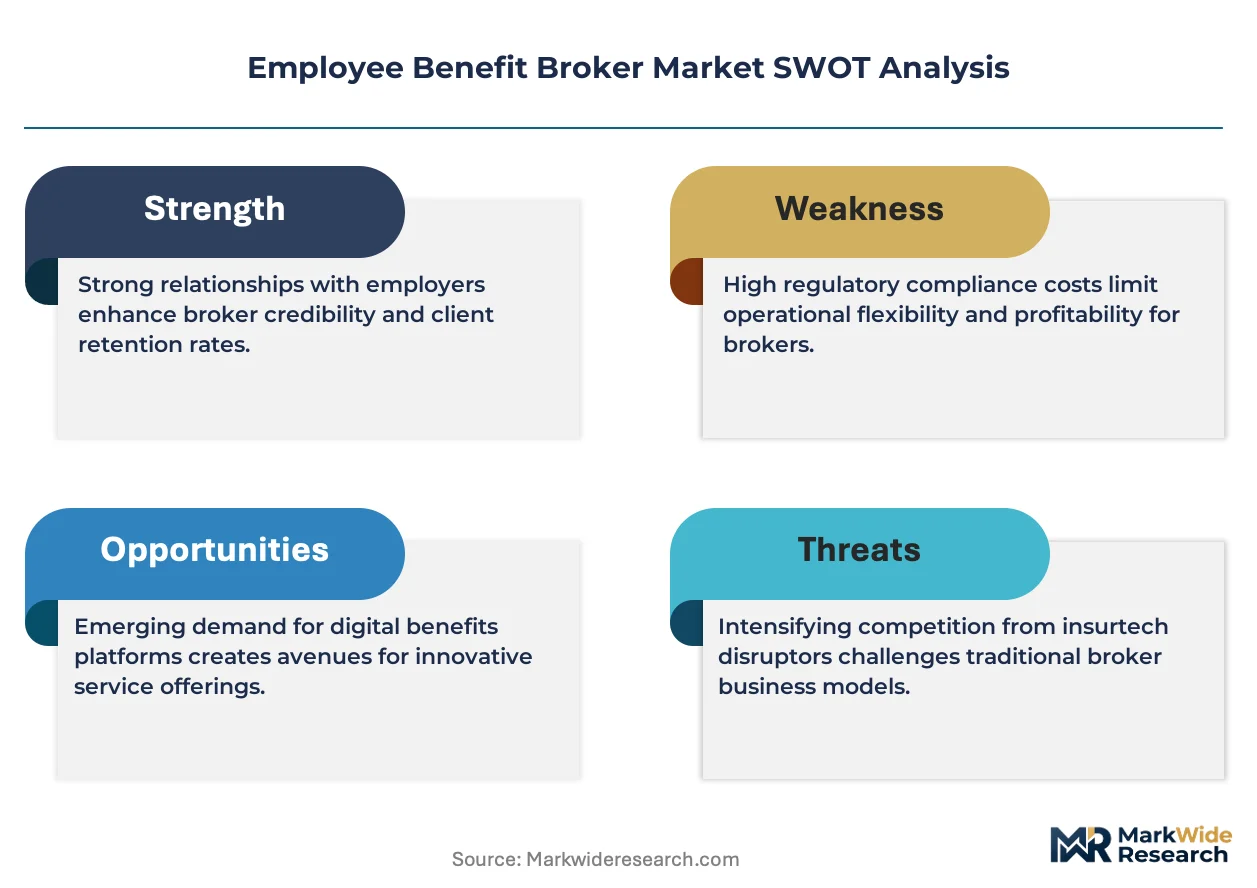
- ACA State Mandates:Sub-fifty-employee firms in California, New York, and Massachusetts face expanded reporting obligations that necessitate formal broker relationships for compliance navigation.
- Mid-Sized Employer Expansion:Technology and professional services clusters are outsourcing benefits administration complexity as workforce demographics diversify across multiple states.
- Cloud-Based Administration:Real-time eligibility verification and digital claims tracking reduce administrative burden for HR departments managing multi-site operations.
Market Restraints
- Carrier Consolidation:Three national insurers control network access in most metropolitan statistical areas, limiting broker negotiating leverage on plan design and premium rates.
- Commission Compression:Standardized ACA marketplace products cap compensation spreads, squeezing revenue per enrolled life for brokers serving individual and small-group markets.
- ERISA Fiduciary Exposure:Department of Labor disclosure requirements impose liability on plan sponsors who fail to document broker fee transparency, chilling advisory engagements.
Strategic Opportunities
- Texas and Florida Growth Corridors:Rapid employer formation in Austin, Dallas, Miami, and Tampa creates first-mover advantage for brokers establishing local advisory presence.
- SECURE Act Retirement Integration:Auto-enrollment mandates and pooled employer plans enable brokers to bundle health and 401(k) administration under unified service contracts.
- Telehealth Benefit Packaging:Virtual primary care and mental health modules allow brokers to differentiate through customized plan designs beyond standard carrier offerings.
Industry Challenges
- Data Interoperability:Legacy payroll systems in manufacturing and retail verticals resist API integration, requiring costly custom development for seamless enrollment connectivity.
- Specialized Compliance Talent:Shortage of professionals credentialed in both ERISA fiduciary standards and state insurance licensing constraints broker capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Benefit Broker Market |
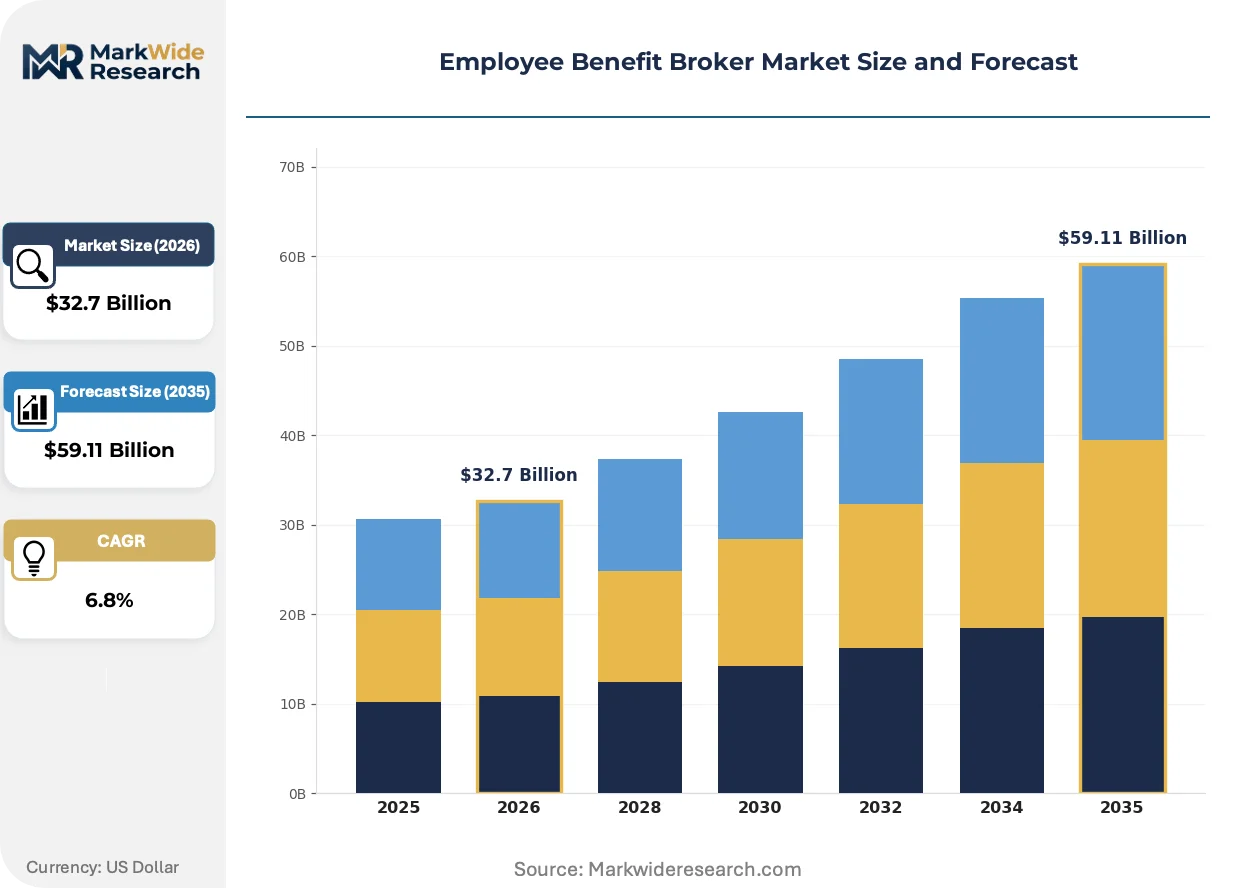
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Health Insurance, Retirement Planning, Disability Coverage, Employee Assistance Programs Client Type: Small Businesses, Corporations, Nonprofits, Startups Delivery Model: Virtual Services, In-Person Consulting, Telephonic Support, Online Platforms Compliance Area: ERISA Regulations, Tax Incentives, Healthcare Mandates, Labor Laws |
| Companies Covered | Mercer, Arthur J. Gallagher & Co., Aon, Willis Towers Watson, Lockton Companies, USI Insurance Services, Alliant Insurance Services, Brown & Brown Insurance, HUB International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Benefit Broker Market Evolving Landscape
Digital infrastructure is redefining how employers evaluate broker value, shifting procurement criteria from relationship tenure to measurable enrollment efficiency and claims advocacy outcomes.
Artificial intelligence-powered predictive analytics is rewriting how brokers model plan utilization and recommend cost-sharing structures. Mid-sized employers in technology corridors are adopting these tools within eighteen-month procurement cycles. The technology is compressing the traditional annual renewal negotiation into continuous plan optimization.
The SECURE Act 2.0 provisions administered by the Department of Labor and IRS are mandating automatic retirement plan features that reshape broker service bundles. Employers must now document fiduciary processes for selecting qualified default investment alternatives. Small and mid-sized plan sponsors in Illinois and Washington are responding by consolidating health and retirement advisory under single broker relationships.
Self-service benefits administration portals are displacing phone-based enrollment support as the standard employee interaction model. Large employers in financial services and healthcare verticals are unbundling implementation consulting from ongoing administrative support. This pattern is most visible in the Northeast corridor, where HR technology budgets exceed national averages and employee digital literacy supports platform adoption.
Employee Benefit Broker Market Segmentation
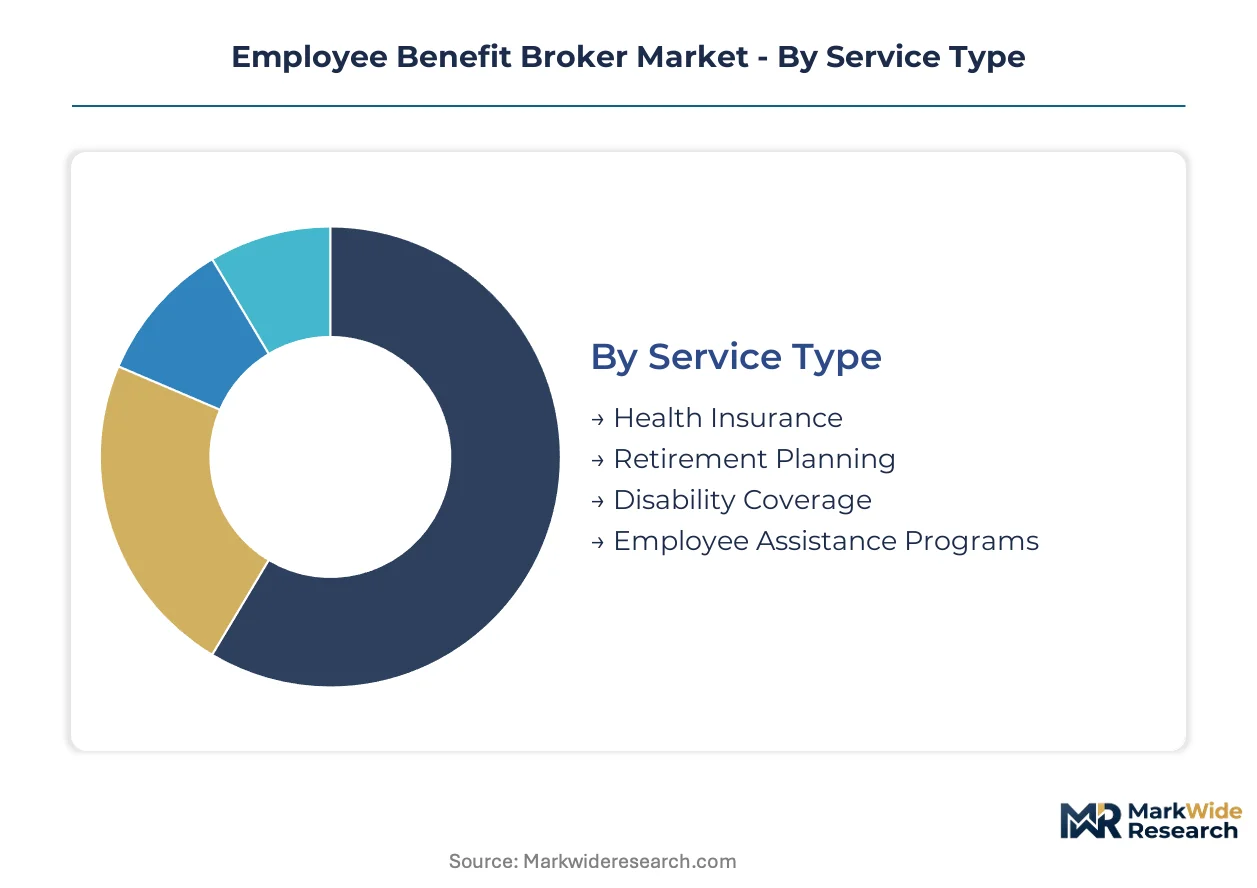
Broker service portfolios fragment across compliance intensity and client scale, with regulatory complexity determining margin structures and delivery economics. Segmentation reveals how intermediaries allocate specialized talent toward high-touch advisory versus automated enrollment processing.
Service Type:
Health Insurance and Retirement Planning carry distinct fiduciary certification burdens under Department of Labor enforcement, while Disability Coverage and Employee Assistance Programs operate under lighter state insurance department oversight.
- Health Insurance:Premium volume concentration and annual renewal complexity drive revenue weighting. Technology and professional services clusters in California and Massachusetts generate concentrated demand as ACA state mandates expand reporting obligations.
- Retirement Planning:Auto-enrollment mechanics and qualified default investment alternative documentation now dominate advisory scope. Mid-sized employers in Illinois and Washington are consolidating health and 401(k) administration under unified broker contracts following SECURE Act 2.0 provisions.
- Disability Coverage:Short-term and long-term income protection products require coordination with state-mandated paid leave programs.
- Employee Assistance Programs:Mental health and work-life service modules attach to core medical contracts as differentiation tools.
Health Insurance sits at the top of the volume ranking, with Retirement Planning climbing the fastest as fiduciary documentation requirements deepen.
Client Type:
Cost tier stratification separates enterprise accounts with dedicated consulting teams from automated platform clients served through standardized enrollment portals.
- Small Businesses:Sub-fifty-employee firms face compressed commission spreads on ACA marketplace products. California, New York, and Massachusetts reporting obligations are pushing these employers toward formal broker relationships for compliance navigation.
- Corporations:Fortune 500 accounts sustain large-account advisory practices through multi-year consulting engagements. Mercer and Aon compete here via proprietary analytics and risk-assessment capabilities.
- Nonprofits:Tax-exempt status creates unique premium tax incentive optimization requirements.
- Startups:Rapid formation corridors in Austin, Dallas, Miami, and Tampa generate first-mover opportunity for brokers establishing local presence.
Corporations anchor current revenue concentration, though Small Businesses are gaining share fastest as state mandate expansion accelerates formal brokerage adoption.
Delivery Model:
Application-based segmentation tracks how enrollment workflow automation displaces labor-intensive consulting across routine versus complex benefit events.
- Virtual Services:Cloud-based eligibility verification and digital claims tracking reduce HR administrative burden for multi-site operations. Technology and professional services employers with distributed workforces are adopting these tools within accelerated procurement cycles.
- In-Person Consulting:High-stakes renewal negotiations and fiduciary process documentation retain premium pricing. Large financial services and healthcare employers in the Northeast corridor continue unbundling implementation consulting from ongoing administrative support.
- Telephonic Support:Call center enrollment assistance persists in manufacturing and retail verticals with legacy payroll system constraints.
- Online Platforms:Self-service portals displace phone-based support as the standard employee interaction model where digital literacy and HR technology budgets permit.
Online Platforms command the steepest expansion trajectory, while In-Person Consulting defends margin concentration in complex advisory segments.
Compliance Area:
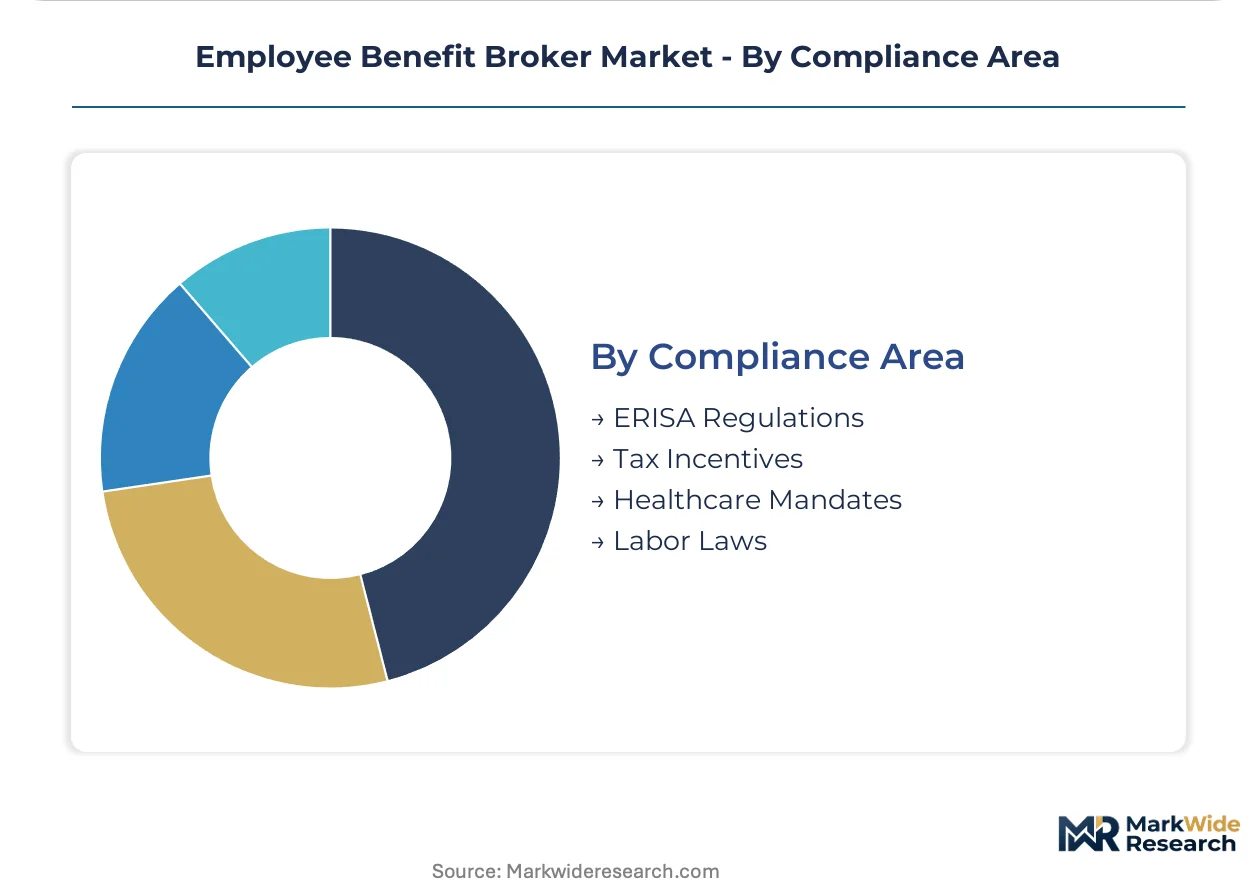
Geography determines which regulatory layer dominates broker engagement scope, with multi-state employers facing overlapping federal and state obligation matrices.
- ERISA Regulations:Department of Labor fiduciary disclosure requirements impose liability on plan sponsors who fail to document broker fee transparency. This chills advisory engagements where fee structures resist clean separation from carrier compensation.
- Tax Incentives:IRS governance of premium tax credits and retirement plan qualification creates optimization opportunity for specialized brokerage expertise.
- Healthcare Mandates:State-level public-option legislation and individual mandate resurrections in Massachusetts and California reshape plan design requirements.
- Labor Laws:State paid family leave and scheduling regulations intersect with disability and EAP product configuration.
ERISA Regulations generate the highest advisory intensity, with Healthcare Mandates expanding most quickly as state legislative activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology and professional services clusters in the United States generate the highest broker engagement intensity as ACA state mandates reshape compliance requirements across employer segments.
United States
Mid-sized employers in technology corridors are expanding formal broker relationships to navigate multi-state workforce compliance. The Department of Labor enforces ERISA fiduciary disclosure requirements that document broker fee transparency. Austin and Dallas brokerages capture rapid employer formation in Texas growth corridors.
Canada
Provincial healthcare integration creates demand for supplemental benefit navigation among mid-market employers. Health Canada coordinates with provincial regulators on group insurance standards that shape broker advisory scope. Toronto and Vancouver financial services clusters drive sophisticated retirement plan bundling requirements.
United Kingdom
Auto-enrollment pension mandates expand broker service bundles beyond traditional health placement. The Financial Conduct Authority governs intermediary conduct standards that reshape compensation disclosure. London professional services firms consolidate advisory relationships under unified brokerage contracts.
Germany
Works council consultation requirements create specialized compliance demand for benefit restructuring advisory. BaFin insurance supervision imposes product governance obligations on intermediary distribution. Munich and Frankfurt employer clusters seek integrated health and pension administration platforms.
Australia
Superannuation guarantee expansion drives retirement advisory bundling with group insurance placement. The Australian Prudential Regulation Authority governs default fund selection processes that reshape broker fiduciary exposure. Sydney and Melbourne technology employers adopt cloud-based benefits administration for distributed workforces.
Employee Benefit Broker Market Competitive Landscape
Strategic partnerships dominate the current landscape as intermediaries reposition around advisory services rather than transactional placement. The vendor base concentrates among large-account consultancies with proprietary analytics capabilities, mid-market specialists leveraging decentralized ownership models, and technology-enabled platforms capturing routine enrollment automation. Three archetypes define competitive positioning: consulting-heritage giants, decentralized agency networks, and digital-first administrators. M&A activity and API integration partnerships represent the dominant competitive vectors reshaping service delivery economics.
Within the consulting-heritage tier, Mercer and Aon exemplify large-account advisory positioning through analytics-driven risk assessment capabilities. Willis Towers Watson occupies a position bridging traditional brokerage with technology-enabled plan optimization. Arthur J. Gallagher & Co. represents the decentralized agency archetype, sustaining local market responsiveness through distributed ownership structures that compete for mid-sized employer relationships.
| Leading Market Players |
|---|
| Mercer |
| Arthur J. Gallagher & Co. |
| Aon |
| Willis Towers Watson |
| Lockton Companies |
| USI Insurance Services |
| Alliant Insurance Services |
| Brown & Brown Insurance |
| HUB International |
| Others |
Value Network & Pricing Analysis
Medical trend indices published by national actuarial societies cascade through carrier pricing models into three-tier broker compensation structures across large-account, mid-market, and small-group segments. This cost transmission mechanism concentrates pricing power among national insurers while compressing margins for intermediaries serving standardized ACA marketplace products.
Pricing Analysis
Input-cost pass-through from carrier medical loss ratio requirements drives commission compression across standardized small-group products. Three-tier pricing structure across premium advisory, standard placement, and economy platform tiers separates dedicated consulting teams from automated enrollment portals. Pricing pressure stems from API-connected HRIS platforms displacing manual enrollment workflows. Small businesses exhibit highest price sensitivity due to compressed commission spreads on ACA marketplace products, while Fortune 500 accounts sustain premium advisory rates through multi-year consulting engagements.
Supply Chain Analysis
Regional distribution centers operated by national carriers in Texas, Florida, and California anchor hub-and-spoke delivery patterns for broker support infrastructure. Technology vendors in the United States, Ireland, and India supply cloud-based eligibility verification and claims tracking platforms. Supply chain risk centers on single-source vulnerability for proprietary analytics tools that differentiate large-account advisory. Distribution runs through carrier-direct relationships for national accounts, independent agency networks for mid-market penetration, and digital platforms for small-group automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The employee benefit broker market functions as a stable compounder, with regulatory complexity from ERISA fiduciary standards and state mandate expansion driving steady employer reliance on specialized intermediaries.
For Market Incumbents: Acquire specialized compliance talent pools credentialed in both ERISA fiduciary standards and state insurance licensing. Consolidate advisory relationships under unified health and retirement service contracts to counter margin compression from API-connected enrollment automation. Build proprietary analytics capabilities that extend risk-assessment tools beyond standard brokerage placements.
For New Entrants and Emerging Players: Capture first-mover positions in Austin, Dallas, Miami, and Tampa employer formation corridors where rapid business creation outpaces established advisory presence. Target sub-fifty-employee firms in California, New York, and Massachusetts facing expanded ACA reporting obligations. Deploy cloud-based benefits administration platforms with telehealth packaging modules to differentiate from legacy in-person consulting.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-market specialists possessing decentralized agency ownership models and strong local market responsiveness. Five-to-ten year viability hinges on advisory service bundling capabilities that transcend transactional placement. Watch SECURE Act implementation pace as inflection indicator for retirement planning advisory demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Connects broker platforms with HRIS systems to automate enrollment workflows and reduce administrative burden. |
| Compliance Talent Acquisition | Builds specialized capacity in ERISA fiduciary standards and multi-state insurance licensing requirements. |
| Telehealth Benefit Packaging | Differentiates plan designs through virtual primary care and mental health modules beyond carrier standard offerings. |
| Geographic Expansion | Establishes advisory presence in Texas and Florida growth corridors with rapid employer formation. |
| Retirement Service Bundling | Consolidates health and 401(k) administration under unified contracts following SECURE Act provisions. |
Research Methodology
Coverage spans the United States, Canada, United Kingdom, Germany, and Australia, with primary inputs from each market informing demand calibration. The analysis combines structured interviews with benefits directors, HR technology procurement officers, carrier network managers, and compliance officers with secondary validation from Department of Labor disclosure filings, state insurance department regulatory updates, SEC 10-K insurance segment disclosures, and HR technology platform documentation. Bottom-up enrollment volume estimates triangulate against top-down premium flow analysis.
Granularity-level modeling captures service type segmentation at the product-line level, client type at employee-count tier, and delivery model at automation-intensity tier across the projection horizon. CAGRs derive from enrollment volume trends, commission rate trajectories, and advisory service mix shifts. Industry-specific forecast inputs include ACA state mandate implementation schedules and SECURE Act regulatory phase-in patterns.
Underlying measurement precision varies by segment; large-account advisory relationships carry tighter precision than fragmented small-group automated enrollment. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Earthquake Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Business Income Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Peer to Peer Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Takaful Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Insurance Protection Products Market