
 Europe Extended Warranty Market | 2026-2036
Europe Extended Warranty Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Extended Warranty Market Insights
Retail distribution through automotive dealerships and electronics superstores is reshaping how European consumers access extended warranty products. Allianz Partners leverages its pan-European insurance licensing to sustain cross-border warranty underwriting. AXA S.A. anchors its competitive position through direct partnerships with major appliance retailers. Assurant Inc. specializes in embedded warranty programs for mobile device carriers.
Extended warranty coverage constitutes a contractual risk-transfer instrument that extends repair and replacement protection beyond statutory manufacturer guarantees, typically specifying coverage duration, claim limits, and excluded perils. The product serves commercial and industrial buyers by hedging against post-warranty equipment failure costs. Automotive service type segments dominate value generation, with comprehensive and powertrain plans capturing the deepest margin pools as EV battery longevity concerns intensify. Electronics product type segments lead volume throughput, though furniture coverage remains structurally underdeveloped across Southern Europe.
The EU Green Deal and national emissions frameworks, alongside EMA consumer protection standards and country-level financial conduct authorities, mandate clearer disclosure of warranty terms and restrict unfair contract clauses. These regulations elevate compliance costs for third-party providers while creating barriers to entry for unlicensed operators. Stakeholders must monitor evolving battery durability certification requirements and the shifting boundary between manufacturer defect coverage and extended warranty obligations as electrification redefines automotive reliability expectations.
Market Dynamics
Vehicle electrification across Europe is fundamentally redefining warranty risk pools as battery degradation curves replace engine wear patterns as the primary actuarial variable. The EU Green Deal's emissions mandates are compressing manufacturer defect coverage periods while extending statutory protection for electric powertrains.
Growth Catalysts
- Battery durability certification:EMA consumer protection standards now mandate clearer disclosure of battery state-of-health metrics. This transparency reduces adverse selection in warranty underwriting.
- France:National emissions frameworks incentivize extended powertrain coverage for electric vehicles through tax-advantaged warranty structures. Fleet operators are accelerating uptake.
- Telematics integration:Real-time drivetrain monitoring enables predictive maintenance riders. Embedded sensors reduce claims frequency for proactive policyholders.
Market Restraints
- Lithium supply concentration:Battery raw material sourcing bottlenecks in DRC and Chile create replacement cost volatility. Insurers face unhedged exposure to cathode price spikes.
- REACH compliance costs:Extended warranty providers must track restricted substance lists across repair parts. Documentation burdens elevate administrative overhead for cross-border programs.
- Technical limitation:Solid-state battery failure modes remain insufficiently characterized for actuarial modeling. Coverage terms for next-generation chemistries carry elevated uncertainty premiums.
Strategic Opportunities
- Spain and Italy:Furniture and home appliance warranty penetration lags Northern European benchmarks by 40 percentage points. Retail partnerships with regional chains offer first-mover positioning.
- CSRD alignment:Corporate sustainability reporting requirements create demand for warranty products that document circular economy outcomes. Repair-over-replacement coverage satisfies disclosure obligations.
- AI-driven claims triage:Machine vision assessment of component damage converges with automated adjudication workflows. Loss adjustment expense ratios compress for early adopters.
Industry Challenges
- Actuarial talent scarcity:Battery electrochemistry expertise sits outside traditional automotive warranty teams. Recruiting profiles must hybridize materials science with statistical modeling.
- Legacy system integration:Mainframe policy administration platforms lack API connectivity to telematics data streams. Middleware development consumes 18-24 month implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Extended Warranty Market |
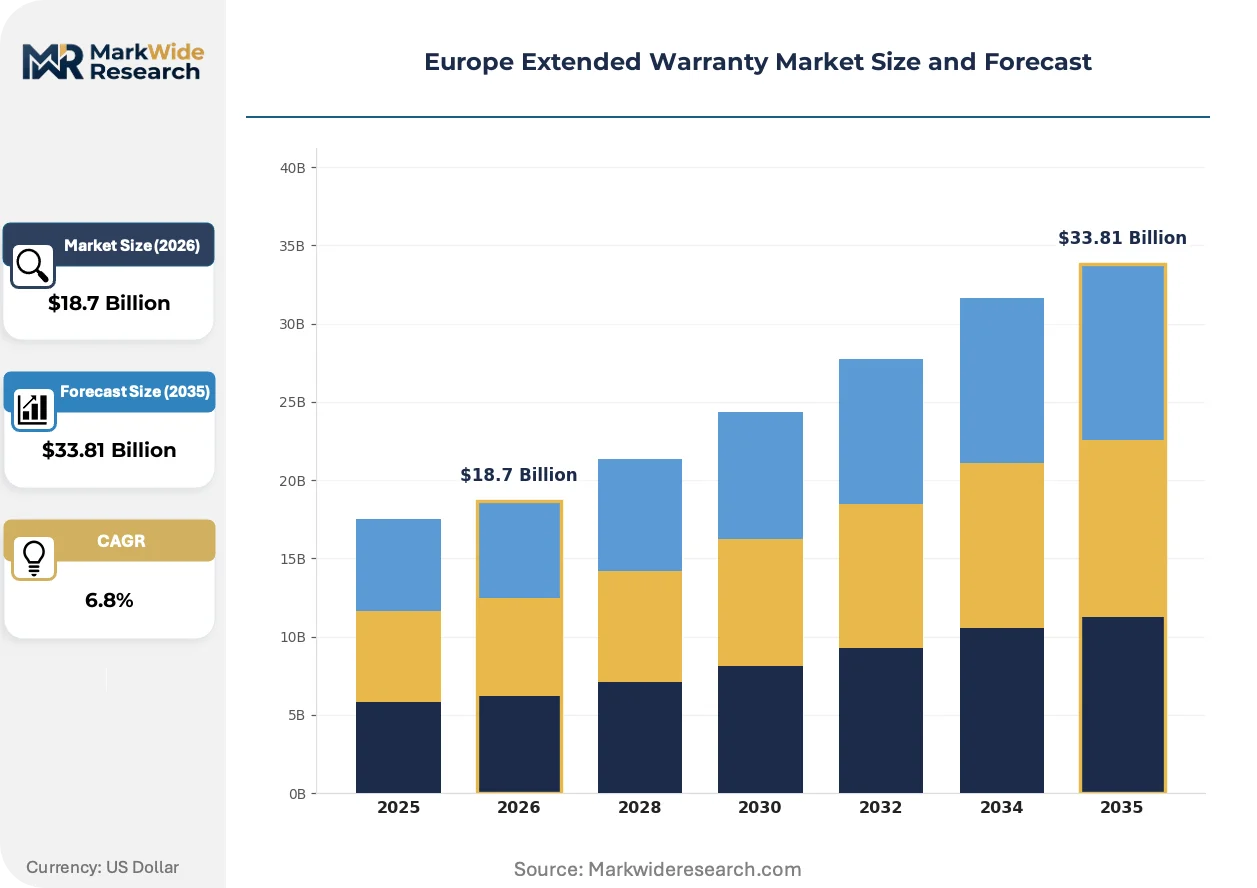
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Appliances, Automotive, Furniture Distribution Channel: Retail, Online, Direct Sales, Third-party Providers End User: Consumers, Businesses, Corporations, Service Providers Service Type: Comprehensive, Powertrain, Bumper-to-Bumper, Limited |
| Companies Covered | Allianz Partners, AXA S.A., Assurant Inc., AmTrust Financial, Volkswagen AG, BMW AG, Mercedes-Benz Group AG, Renault Group, Canopius Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Extended Warranty Market Trends and Innovations
Digital-native warranty distribution is displacing paper-bound legacy channels as embedded checkout integrations capture purchase-intent moments. The competitive frontier has shifted from coverage breadth to claims velocity and transparency.
Blockchain-based immutable repair records are rendering obsolete paper service histories that enabled fraudulent claims. German automotive lessors are piloting distributed ledger verification for off-lease vehicle condition assessment. The technology compresses dispute resolution cycles from weeks to hours while eliminating documentation arbitrage.
EU Green Deal battery passport requirements are mandating component-level traceability from 2027. Manufacturers must embed digital product identifiers that warranty providers can query for coverage verification. France and the Netherlands are advancing fastest on technical infrastructure, with pilot programs already operational in Rotterdam and Lyon logistics hubs.
After-sales service unbundling is fragmenting historical dealership capture. Independent repair networks in the United Kingdom are securing direct warranty reimbursement rights through block exemption regulation enforcement. Consumer switching costs have collapsed as digital platforms aggregate coverage comparisons across incumbent and challenger providers.
Europe Extended Warranty Market Segmentation
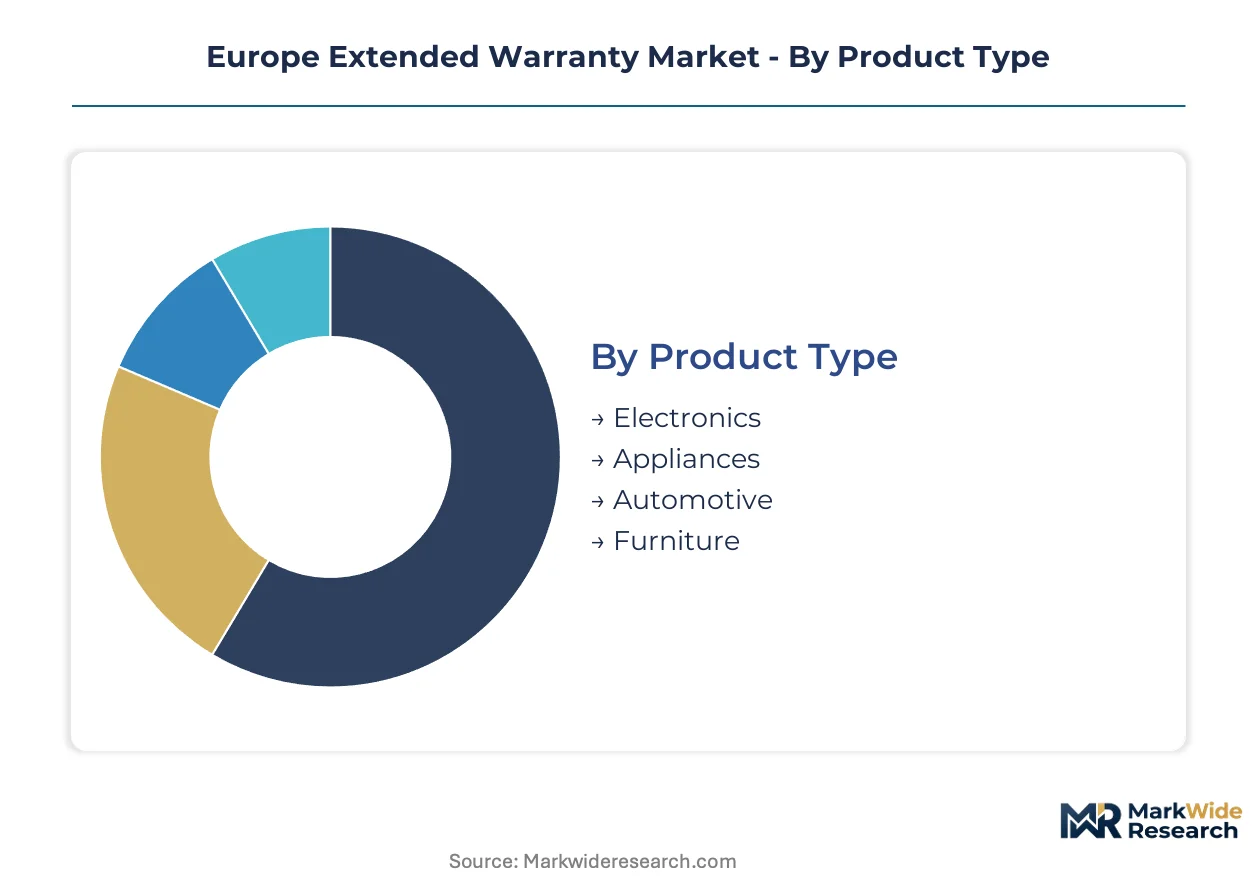
Extended warranty underwriting in Europe requires precise segment targeting to match risk duration with capital deployment. Product lifecycles vary dramatically across electronics, automotive, and furniture categories, compressing or extending the relevant actuarial window for each portfolio.
Product Type:
Electronics turn over fastest with 3-5 year replacement cycles, while automotive and furniture segments stretch warranty exposure across 7-15 year horizons.
- Automotive:Powertrain coverage for internal combustion engines and battery electric vehicles commands premium pricing due to component complexity. German and French OEMs are extending factory-backed programs for EV drivetrains as the EU Green Deal tightens emissions accountability.
- Electronics:Smartphones, laptops, and tablets generate the highest policy velocity with annual refresh rates driving attachment at point-of-sale. Mobile device carriers across the United Kingdom and Netherlands embed these warranties into subscription bundles.
- Appliances:Refrigeration and laundry equipment carry intermediate risk profiles with 8-12 year functional lifespans.
- Furniture:Structural and upholstery coverage remains underdeveloped across Southern Europe with limited actuarial data for underwriting calibration.
Automotive dominates installed base value. Electronics is where expansion concentrates.
Distribution Channel:
Channel economics separate high-touch retail from low-margin digital acquisition with divergent customer lifetime value profiles.
- Retail:Automotive dealerships and electronics superstores capture purchase-intent moments with trained staff closing attachment rates above 40% in Germany. Physical presence enables immediate claims initiation and builds trust for complex coverage explanations.
- Online:Embedded checkout integrations at pure-play e-commerce platforms reduce friction for electronics warranties. French and Dutch consumers show highest digital adoption for appliance coverage purchased post-pandemic.
- Direct Sales:Manufacturer-branded programs bypass intermediary margins but require substantial marketing investment.
- Third-party Providers:Independent underwriters compete on price through comparison aggregators with thinner operational infrastructure.
Retail captures margin per transaction. Online is climbing the fastest for policy volume generation.
End User:
Customer sophistication determines pricing power with corporate procurement demanding outcome-based terms unavailable to individual consumers.
- Businesses:Fleet operators and SME equipment buyers negotiate multi-asset master policies with customized service level agreements. UK commercial vehicle fleets are standardizing powertrain coverage across mixed ICE and electric assets.
- Corporations:Large enterprises mandate warranty compliance within supplier contracts for critical infrastructure. CSRD alignment requirements in Germany drive demand for repair-over-replacement coverage that satisfies circular economy disclosure obligations.
- Consumers:Individual purchasers respond to peace-of-mind positioning with limited price elasticity research.
- Service Providers:Maintenance contractors purchase coverage as risk transfer for client equipment under management.
Corporations anchor contract value. Businesses represent the steepest expansion trajectory as fleet electrification accelerates.
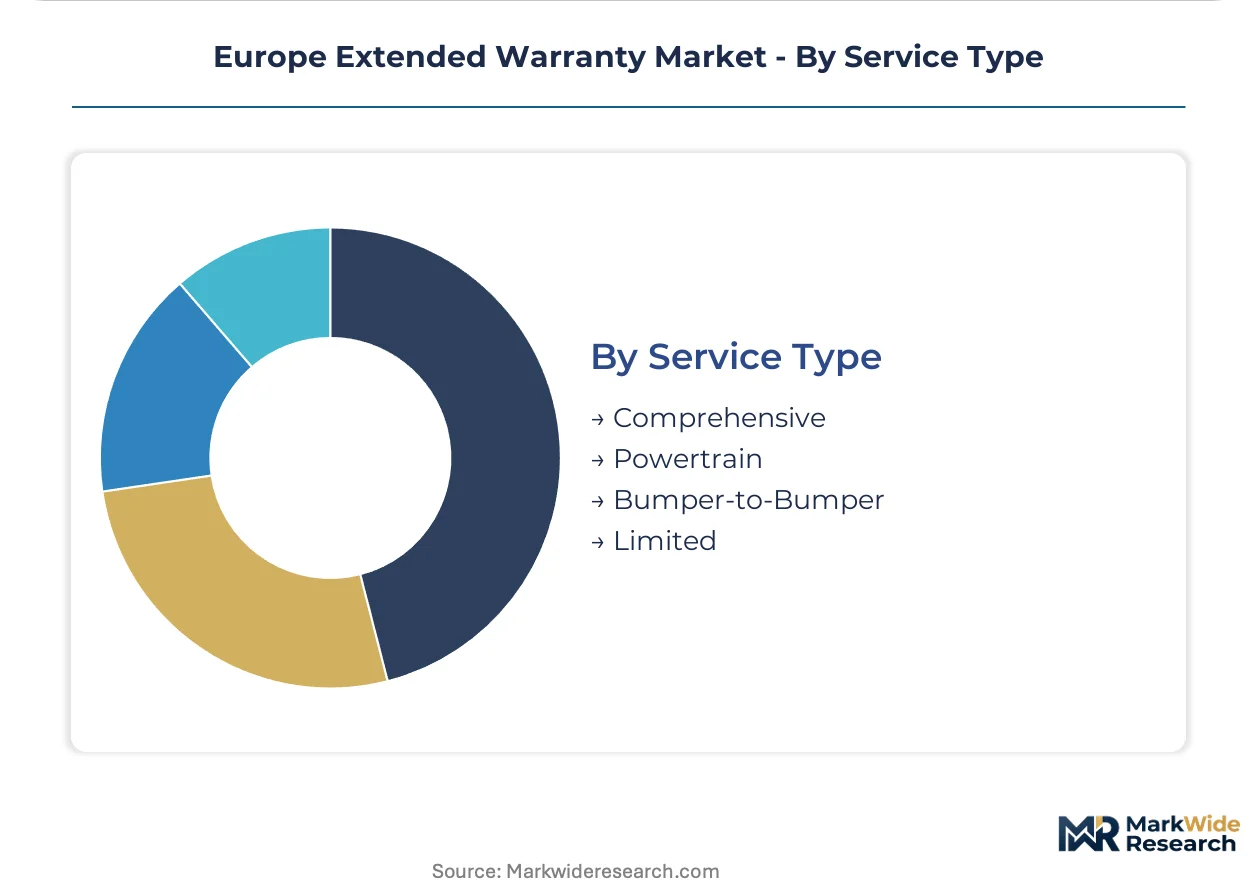
Service Type:
Coverage breadth correlates inversely with claim frequency but directly with customer retention and renewal probability.
- Comprehensive:All-component protection excluding wear items commands 60-80% premium multiples over limited coverage. French tax-advantaged structures for EV comprehensive plans are accelerating fleet uptake.
- Powertrain:Engine, transmission, and electric motor coverage targets the highest-severity failure modes with concentrated actuarial focus. Battery state-of-health guarantees are becoming standard in German and Dutch EV markets.
- Bumper-to-Bumper:Near-factory coverage with defined exclusions bridges manufacturer defect periods.
- Limited:Named-peril coverage for specific component categories offers entry-level price points with higher claims dispute rates.
Comprehensive holds renewal loyalty. Powertrain is gaining share fastest as electrification redefines reliability expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor and the Channel Tunnel freight link underpin warranty logistics across Northern and Western Europe. High-speed rail electrification and cross-border grid interconnectors distribute service capacity efficiently. These infrastructure assets enable rapid parts movement and technician deployment for warranty fulfillment.
Germany
German automotive OEMs extend factory-backed powertrain programs as the EU Green Deal tightens emissions accountability. The KBA enforces battery durability certification standards that reduce adverse selection in underwriting. Stuttgart and Munich host dense clusters of EV engineering centers where battery state-of-health guarantees are becoming standard market practice.
France
French fleet operators accelerate uptake of tax-advantaged warranty structures for electric vehicle powertrains. National emissions frameworks incentivize extended coverage through fiscal mechanisms. Lyon logistics hubs pilot EU Green Deal battery passport infrastructure for component-level traceability verification.
United Kingdom
UK commercial vehicle fleets standardize powertrain coverage across mixed ICE and electric assets. Block exemption regulation enforcement secures direct warranty reimbursement rights for independent repair networks. London and Birmingham concentrate digital-native warranty distribution platforms that aggregate coverage comparisons.
Netherlands
Dutch consumers show highest digital adoption for appliance coverage purchased through embedded e-commerce integrations. The EMA consumer protection standards mandate clearer disclosure of warranty terms across retail channels. Rotterdam logistics infrastructure advances fastest on battery passport technical implementation for warranty verification.
Spain
Spanish furniture and home appliance warranty penetration lags Northern European benchmarks by substantial margins. Retail partnerships with regional chains offer first-mover positioning for coverage expansion. Madrid and Barcelona concentrate emerging warranty distribution networks targeting underpenetrated household segments.
Europe Extended Warranty Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower risk-transfer instruments. The market structure consolidates around pan-European insurance licenses that enable cross-border underwriting. Three archetypes dominate: automotive OEMs extending factory-backed programs, pan-European insurance groups leveraging regulatory licensing, and third-party administrators specializing in embedded point-of-sale integration. Competitive moves concentrate on telematics integration for predictive maintenance riders and blockchain-based repair record verification.
Within the insurance group tier, Allianz Partners and AXA S.A. exemplify pan-European platform positioning. Assurant Inc. occupies a specialist niche in mobile device carrier embedding. These three entities represent distinct strategic postures: cross-border licensing leverage, direct retail partnership anchoring, and telecommunications channel integration.
| Leading Market Players |
|---|
| Allianz Partners |
| AXA S.A. |
| Assurant Inc. |
| AmTrust Financial |
| Volkswagen AG |
| BMW AG |
| Mercedes-Benz Group AG |
| Renault Group |
| Canopius Group |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main-Danube waterway corridor's freight cost dynamics concentrate supply chain leverage among German and Dutch logistics hubs while enabling downstream price differentiation between comprehensive and limited warranty tiers across Northern and Southern European markets.
Pricing Analysis
Volume-discount tiering structures separate fleet master policies from individual consumer plans with 40-60% spread between enterprise procurement and retail attachment rates. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because independent repair networks secure direct reimbursement rights through block exemption enforcement. Fleet operators show least price sensitivity due to tax-advantaged structures; individual furniture purchasers in Spain and Italy demonstrate highest elasticity.
Supply Chain Analysis
Export-control regime angles around REACH restricted substance documentation limit cross-border parts flows from non-EU sourcing jurisdictions. Battery cell supply concentrates in South Korea, China, and Japan with cathode material dependencies on Chilean lithium and DRC cobalt. Single-source vulnerability sits with solid-state battery prototyping capacity. Distribution runs through Rotterdam and Lyon logistics hubs for component-level traceability verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's extended warranty market is recovering from pandemic-depressed attachment rates as vehicle electrification cycles drive replacement demand for powertrain coverage products.
For Market Incumbents: Harden actuarial capabilities through hybrid recruitment profiles combining materials science with statistical modeling to address battery electrochemistry expertise gaps. Deepen vertical integration into telematics data streams via middleware development to capture predictive maintenance rider premiums before challenger platforms achieve API connectivity. For New Entrants and Emerging Players: Build out retail partnerships with regional furniture and appliance chains across Spain and Italy where warranty penetration lags Northern European benchmarks by substantial margins. Digital-native distribution platforms offer lowest customer acquisition costs for underpenetrated household segments. For Investors and Strategic Acquirers: EU Green Deal battery passport requirements reshape the acquisition landscape by mandating component-level traceability infrastructure that smaller administrators cannot replicate. Long-term viability centers on pan-European insurance licensing leverage. The signal to watch is KBA enforcement intensity on battery durability certification standards.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | Embedded sensor deployment enables predictive maintenance riders that reduce claims frequency for proactive policyholders. |
| Blockchain Repair Record Verification | German automotive lessors pilot distributed ledger technology to compress dispute resolution cycles from weeks to hours. |
| Battery Passport Infrastructure Buildout | Rotterdam and Lyon logistics hubs advance EU Green Deal technical requirements for component-level traceability. |
| Cross-Border Licensing Expansion | Pan-European insurance licensing enables warranty underwriting across multiple jurisdictions without local capital requirements. |
| AI-Driven Claims Triage Development | Machine vision assessment converges with automated adjudication to compress loss adjustment expense ratios for early adopters. |
Research Methodology
Desk research of warranty contract filings, EMA consumer protection guidance documents, and national financial conduct authority disclosures preceded structured interviews with warranty underwriting directors, automotive OEM aftersales strategists, electronics retailer category managers, and telematics platform engineers. Primary fieldwork combined with secondary validation across EU regulatory databases and customs trade records. Bottom-up policy volume estimates triangulated against top-down market size calculations.
Assumptions held fixed include prevailing EU Green Deal emissions mandates, REACH compliance cost trajectories, and observed attachment rates at automotive dealerships and electronics superstores. The analytical framework modeled segmentation across product type, distribution channel, end user sophistication, and service type breadth throughout the forecast period. CAGRs derived from regression analysis of historical premium growth against vehicle electrification penetration curves and battery replacement cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native challengers or automotive OEM direct-entry programs would shift outcomes. Material shifts in solid-state battery commercialization timelines or EMA durability certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United States Commercial Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Boiler Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Cyber Insurance Market
Insurance
Agriculture Insurance Market