
 Explosive Detectors Market | 2026-2036
Explosive Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Detectors Market Analysis
North American defense contractors is rebalancing production schedules toward dual-use explosive detection platforms that serve military and civilian checkpoints. Smiths Detection leverages integrated checkpoint architectures spanning airports and critical infrastructure nodes. L3Harris Technologies sustains long-term service contracts with the TSA and Department of Homeland Security. Rapiscan Systems anchors its position through dense installed bases at major international hub airports.
Explosive detectors are instruments engineered to identify trace quantities of energetic materials through spectroscopic, chromatographic, or imaging modalities, typically achieving detection thresholds in the parts-per-billion range for vapor-phase samples. These systems serve the primary commercial purpose of preventing transport of improvised explosive devices into controlled spaces including aircraft cabins, government facilities, and mass transit networks. Handheld detectors dominate field military operations where portability outweighs throughput requirements, while stationary detectors command premium pricing in airport checkpoint installations due to integration complexity and certification overhead. Ion mobility spectrometry occupies the largest installed base among core detection technologies, though infrared spectroscopy gains share in next-generation platforms promising reduced false alarm rates.
The TSA mandates certification under 49 CFR for all checked baggage and passenger checkpoint systems deployed in US airports, while the EU ESR framework establishes performance baselines for explosive trace detection equipment across member state borders. The UK's Department for Transport enforces additional national standards for aviation security equipment that exceed baseline EU requirements in certain sensitivity parameters. Stakeholders must monitor evolving harmonization tensions between national certification regimes and emerging international standards to anticipate procurement specification shifts.
Market Dynamics
Transportation security agencies are forcing compressed replacement cycles for legacy ion mobility spectrometry systems as next-generation platforms promise reduced false alarm rates and higher passenger throughput.
Growth Catalysts
- Aviation Security Mandates:The TSA's 49 CFR certification requirements and EU ESR framework revisions compel airports to upgrade checkpoint and checked baggage screening infrastructure on accelerated timelines.
- Critical Infrastructure Expansion:Mass transit networks, government facilities, and public venues are deploying stationary detection systems as standard perimeter security equipment.
- Spectroscopic Convergence:Infrared spectroscopy is capturing share from established detection modalities as manufacturers integrate multi-technology architectures into single-platform solutions.
Market Restraints
- Certification Cost Burden:TSA certification under 49 CFR and EU ESR compliance create multi-year approval timelines that freeze procurement decisions and elevate total cost of ownership for system integrators.
- Semiconductor Component Concentration:Specialized sensor arrays and signal processing chips depend on concentrated Asian foundry capacity, exposing production schedules to geopolitical supply disruptions.
- False Alarm Trade-offs:Sensitivity thresholds required for aviation security applications generate elevated false positive rates that consume operator attention and erode checkpoint efficiency.
Strategic Opportunities
- UAE Airport Modernization:Abu Dhabi and Dubai international hubs are executing billion-dollar terminal expansions that specify next-generation integrated checkpoint architectures with unified passenger and baggage screening.
- Dual-Use Military-Civilian Platforms:Defense contractors are repurposing field-proven handheld and vehicle-mounted detection systems for border security and critical infrastructure protection contracts.
- Service Contract Unbundling:Dense installed bases at major international hub airports create captive aftermarket revenue streams through multi-year maintenance, calibration, and software upgrade agreements.
Industry Challenges
- Spectroscopy Talent Scarcity:The specialized physics and engineering expertise required for algorithm development and sensor calibration outpaces university pipeline output.
- Legacy System Integration:Airport operators face complex retrofit requirements when embedding new detection platforms into existing baggage handling conveyor networks and passenger flow architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Detectors Market |
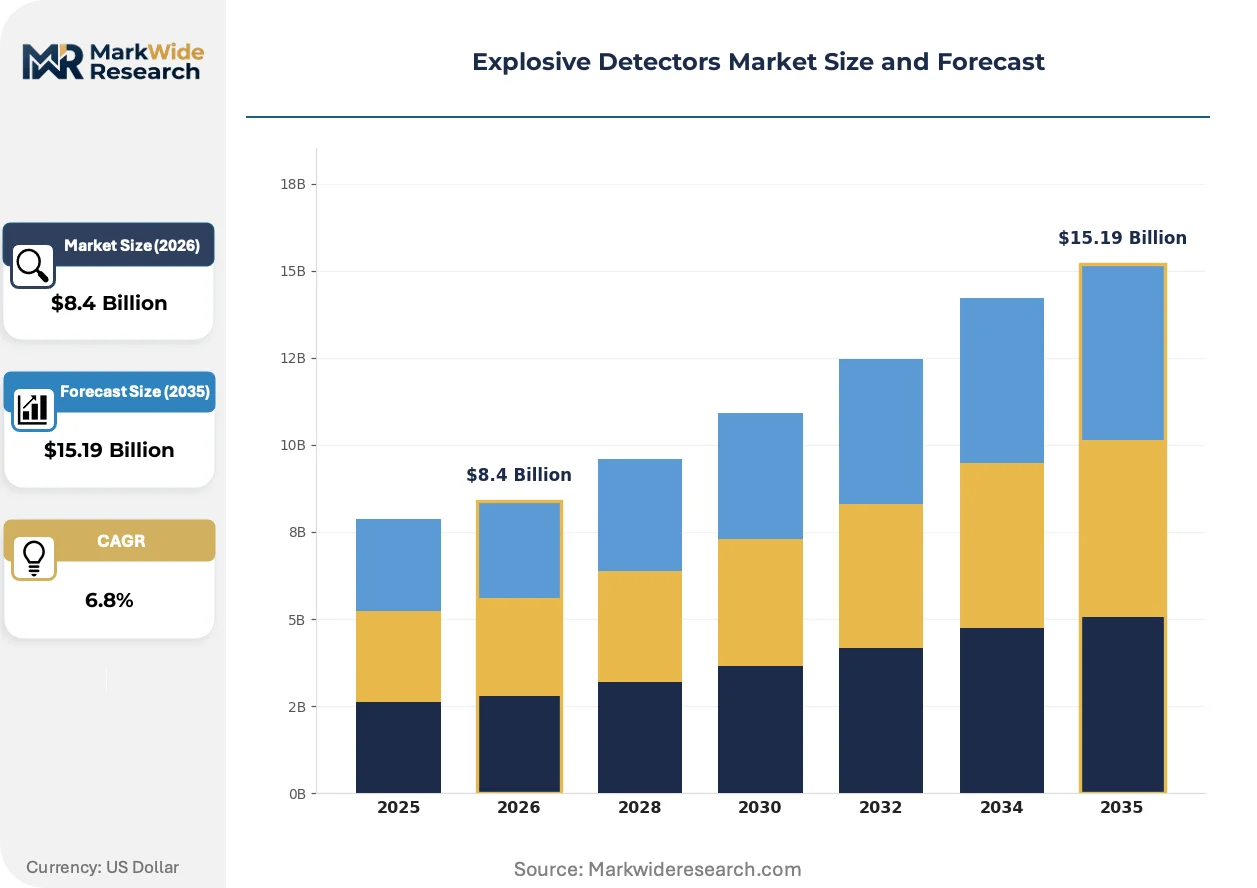
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Detectors, Stationary Detectors, Vehicle-Borne Detectors, Remote Sensing Systems Technology: Infrared Spectroscopy, Ion Mobility Spectrometry, X-ray Imaging, Chemical Sensors End User: Defense, Transportation Security, Commercial Aviation, Public Safety Application: Airport Security, Military Operations, Border Control, Event Security |
| Companies Covered | Smiths Detection, L3Harris Technologies, Rapiscan Systems, OSI Systems, Leidos Holdings, Teledyne FLIR, Chemring Group, Thermo Fisher Scientific, Nuctech Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Detectors Market Emerging Trajectories
Detection technology architectures are converging around multi-modal platforms that fuse complementary sensing modalities to resolve the long-standing sensitivity-specificity trade-off in security screening applications.
Raman spectroscopy is integrating into next-generation handheld and desktop explosive trace detectors as a complementary modality to ion mobility spectrometry. Security agencies in Germany and the United Kingdom are piloting dual-technology units at airport checkpoints and mass transit nodes. This convergence is compressing the addressable market for single-technology suppliers while elevating performance benchmarks for contract awards.
The EU ESR framework is tightening performance baselines for explosive trace detection equipment across member state borders. Manufacturers must now demonstrate detection thresholds and false alarm rates under standardized test protocols before market entry. Aviation security procurement specifications in France, Germany, and the Netherlands are incorporating these harmonized standards ahead of formal enforcement deadlines.
After-sales service contracts are unbundling from initial system sales as airport operators seek predictable operating expenditures over capital-heavy procurement models. Dense installed bases at London Heathrow, Frankfurt, and Amsterdam Schiphol are converting to multi-year performance-based maintenance agreements. This shift is most visible in Western European hub airports where financing constraints favor operational leasing structures over outright purchase.
Explosive Detectors Market Segmentation
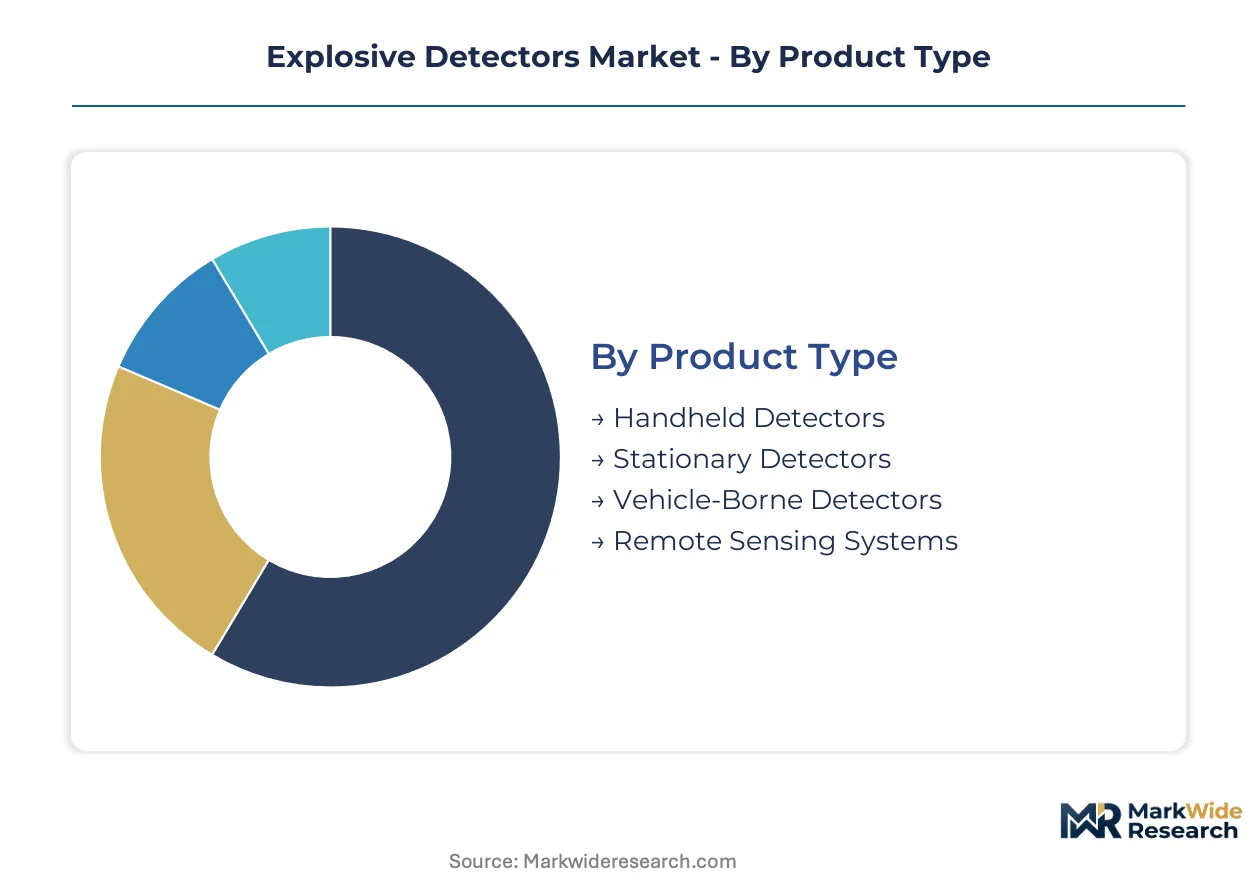
Explosive detector procurement splits sharply between standardized mass-deployed platforms and customized integrated architectures. Transportation security agencies specify certification-grade systems with fixed performance baselines, while defense and critical infrastructure contracts demand modular configurations adapted to threat profiles and operational environments.
Product Type:
Standardization dominates portable and field-deployable formats, whereas stationary installations require extensive customization to integrate with existing checkpoint and baggage handling infrastructure.
- Handheld Detectors:Battery-powered units weighing under 3 kilograms utilize ion mobility spectrometry or Raman spectroscopy for trace particle and vapor detection. Military operations in Germany and the United Kingdom drive procurement volumes, with defense ministries prioritizing interoperability with existing chemical detection networks and reduced logistical footprints.
- Stationary Detectors:Fixed-installation systems integrate into airport checkpoint lanes and checked baggage screening tunnels, achieving throughput rates exceeding 400 passengers per hour. Demand concentrates in UAE terminal expansions at Abu Dhabi and Dubai international hubs, where billion-dollar modernization programs specify unified passenger and baggage screening architectures with centralized monitoring.
- Vehicle-Borne Detectors:Mobile platforms mounted on armored or commercial vehicle chassis for route clearance and convoy protection missions.
- Remote Sensing Systems:Stand-off detection platforms employing laser spectroscopy or millimeter-wave imaging for perimeter monitoring and standoff identification.
Leading the category by volume: Handheld Detectors. Expanding most quickly: Stationary Detectors.
Technology:
Cost tiers separate mature detection modalities with established installed bases from emerging spectroscopic platforms commanding premium pricing for reduced false alarm performance.
- Ion Mobility Spectrometry:Established detection technology measuring ion drift times through electric fields to identify explosive compounds at parts-per-billion vapor concentrations. The largest installed base among core technologies supports replacement cycle acceleration as TSA and EU ESR frameworks tighten certification requirements.
- Infrared Spectroscopy:Fourier-transform infrared platforms analyze molecular absorption spectra to distinguish threat materials from benign interferents with lower false positive rates than IMS equivalents. Germany and the Netherlands incorporate dual-technology specifications into aviation security procurement ahead of formal EU ESR enforcement deadlines.
- X-ray Imaging:Computed tomography and dual-energy systems for bulk explosive detection in checked baggage and cargo screening applications.
- Chemical Sensors:Electrochemical and colorimetric detection platforms for simplified field deployment with reduced calibration requirements.
Commanding the highest volume share: Ion Mobility Spectrometry. Steepest expansion trajectory: Infrared Spectroscopy.
End User:
Customer type determines procurement modality, with defense agencies favoring indefinite-delivery contracts and commercial aviation operators pursuing operational leasing structures.
- Transportation Security:Civilian checkpoint and baggage screening operations at airports, seaports, and mass transit nodes. TSA mandate upgrades across United States airports and EU ESR regulation revisions accelerate replacement timelines for legacy ion mobility systems.
- Defense:Military explosive ordnance disposal, route clearance, and force protection missions requiring ruggedized platforms with battlefield electromagnetic compatibility.
- Commercial Aviation:Airline-operated passenger and cargo screening infrastructure at hub airports and regional terminals.
- Public Safety:Law enforcement and emergency response deployment for event security, critical incident response, and hazardous materials incidents.
Dominating procurement volume: Transportation Security. Gaining share fastest: Defense.
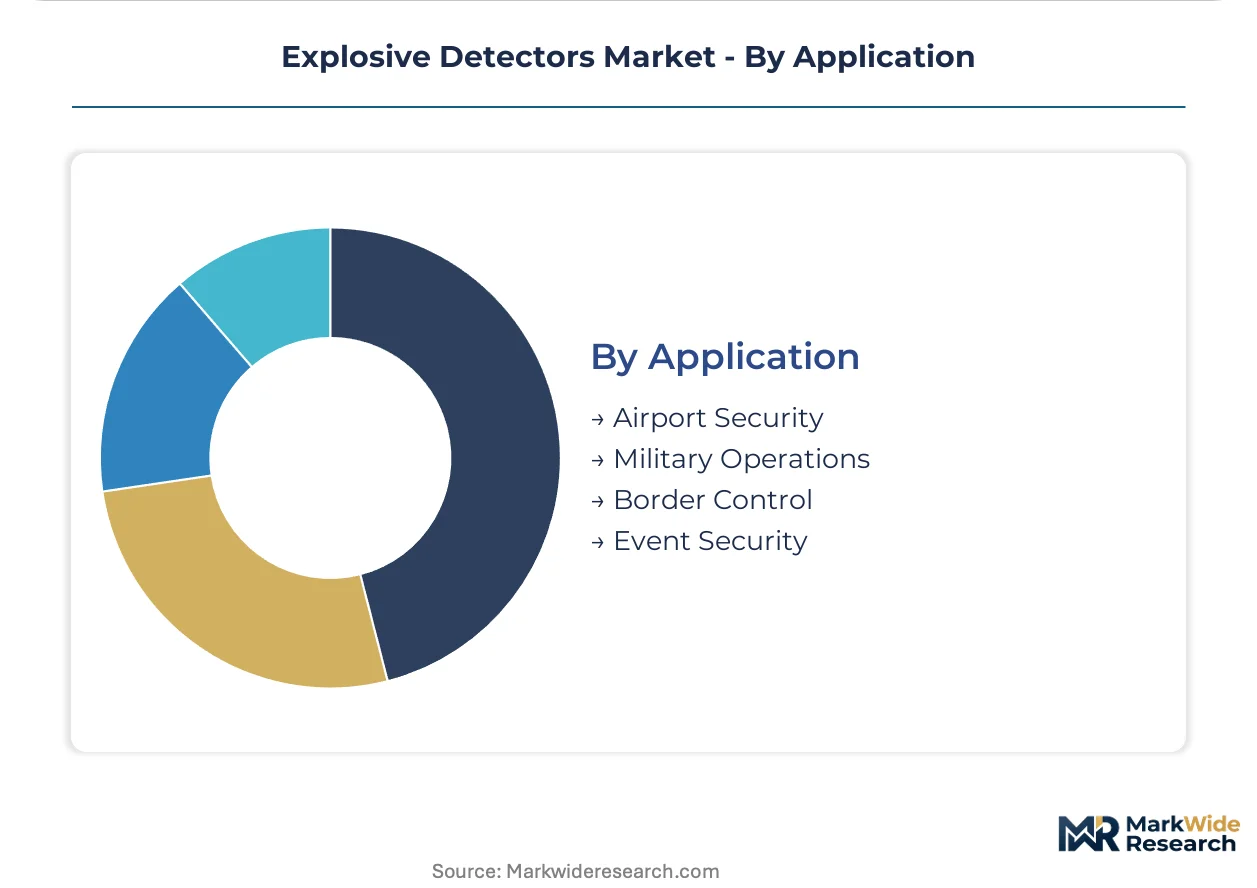
Application:
Geographic concentration of threat incidents and infrastructure investment cycles shapes demand distribution across operational scenarios.
- Airport Security:Passenger checkpoint lanes, checked baggage screening tunnels, and air cargo inspection stations. Germany, the United Kingdom, and the United Arab Emirates execute concurrent modernization programs specifying next-generation integrated checkpoint architectures.
- Military Operations:Forward operating base protection, convoy route clearance, and improvised explosive device neutralization missions.
- Border Control:Land crossing vehicle inspection, maritime container screening, and immigration checkpoint deployment.
- Event Security:Temporary perimeter screening for sporting events, political summits, and public gatherings requiring rapid deployment capabilities.
Generating highest absolute demand: Airport Security. Climbing the fastest: Border Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sensor arrays and signal processing components concentrate in Asian foundry clusters, yet procurement decisions and certification regimes anchor demand across North American and European transportation security agencies. The installed base of ion mobility spectrometry systems drives replacement cycles through regulatory mandate upgrades rather than greenfield expansion.
United States
The Transportation Security Administration mandates certification under 49 CFR for all checked baggage and passenger checkpoint systems deployed at commercial airports. TSA service contracts with established defense contractors sustain multi-year maintenance and calibration revenue streams. Dense installed bases at Atlanta Hartsfield-Jackson, Dallas-Fort Worth, and Chicago O'Hare drive aftermarket conversion to performance-based operational leasing structures.
Germany
Frankfurt Airport and Munich Airport execute concurrent terminal modernization programs specifying next-generation integrated checkpoint architectures with unified passenger and baggage screening. The Federal Ministry of Transport enforces aviation security equipment standards that exceed baseline EU requirements in certain sensitivity parameters. Dual-technology specifications incorporating infrared spectroscopy now dominate procurement tenders ahead of formal EU ESR enforcement deadlines.
United Kingdom
The Department for Transport maintains additional national certification requirements for explosive trace detection equipment beyond EU ESR baselines. London Heathrow and Gatwick airports convert dense legacy installed bases to multi-year service agreements favoring predictable operating expenditures. Border Force procurement for cross-Channel route security accelerates demand for vehicle-borne and handheld detection platforms.
United Arab Emirates
Abu Dhabi and Dubai international hubs drive billion-dollar terminal expansions specifying centralized monitoring architectures for next-generation screening infrastructure. The General Civil Aviation Authority aligns procurement specifications with emerging international standards while accommodating accelerated construction timelines. Emirates airline and Etihad Airways coordinate infrastructure investments at their respective hub airports to capture transit passenger volume growth.
France
Paris Charles de Gaulle and Orly airports modernize checkpoint lanes under EU ESR framework revisions compelling accelerated replacement of legacy ion mobility systems. The national civil aviation authority pilots harmonized test protocols for detection thresholds and false alarm rates before formal border-wide enforcement. Raman spectroscopy integration into handheld units advances through defense ministry procurement for military-civilian dual-use applications.
Explosive Detectors Market Vendor Landscape
Global majors compete with regional champions across certification-grade system supply, creating a tiered structure where TSA and EU ESR approvals serve as primary competitive moats. The vendor landscape separates into three archetypes: integrated checkpoint architects with dense installed bases at international hub airports; defense contractors repurposing field-proven military platforms for civilian security contracts; and specialized spectroscopy firms advancing multi-modal detection technologies. Dominant competitive moves include strategic partnerships with airport operators for long-term service contract unbundling, and technology licensing arrangements to compress multi-year certification timelines.
Within the integrated checkpoint architect tier, Smiths Detection and L3Harris Technologies exemplify vendors sustaining long-term relationships with transportation security agencies through service contract extensions and system upgrade pathways. Rapiscan Systems occupies a position anchored by dense installed bases at major international hub airports. These three entities represent the certification-heavy segment where regulatory compliance investments create barriers to competitive entry and sustain aftermarket revenue capture through captive maintenance and calibration agreements.
| Leading Market Players |
|---|
| Smiths Detection |
| L3Harris Technologies |
| Rapiscan Systems |
| OSI Systems |
| Leidos Holdings |
| Teledyne FLIR |
| Chemring Group |
| Thermo Fisher Scientific |
| Nuctech Company |
| Others |
Supply Flow & Price Mechanics
Defense-contractor-rolled-up specialists with captive service networks anchor pricing discipline through multi-year TSA and EU ESR certification cycles that lock out speculative entrants. Their consolidated ownership structures compress procurement timelines while elevating total cost of ownership thresholds for airport operators seeking predictable operating expenditure models over capital-heavy acquisitions.
Pricing Analysis
Extended warranty and calibration service unbundling now separates hardware acquisition from recurring revenue streams in aviation security procurement. Three-tier pricing structure across certified-premium, standard-compliance, and field-economy levels reflects TSA 49 CFR and EU ESR certification tiers rather than raw performance specifications. Cost compression in standard-tier handheld detectors intensifies as Asian manufacturers achieve CE marking parity, eroding historical brand premiums. Border security agencies exhibit highest price sensitivity due to budget fragmentation across multiple jurisdictions, while UAE hub airports demonstrate lowest sensitivity given billion-dollar terminal expansion budgets.
Supply Chain Analysis
TSA and EU ESR qualification gating restricts component sourcing to pre-approved sensor array and signal processing chip vendors with established certification documentation trails. Specialized semiconductor foundries in Taiwan, South Korea, and Japan anchor production of ion mobility spectrometry drift tubes and Fourier-transform infrared detector arrays. Rare earth magnet supplies for mass spectrometry subsystems draw from concentrated Chinese processing capacity, creating tariff exposure vulnerability under evolving trade restrictions. Distribution runs through authorized system integrators with direct TSA and Department of Homeland Security contracting authority rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where multi-year certification timelines and captive installed bases force capital-constrained spectroscopy specialists toward strategic exit. Regulatory compliance investments function as competitive moats that disproportionately burden smaller players lacking service contract scale.
For Market Incumbents: Acquire dense installed base assets at London Heathrow, Frankfurt, and Amsterdam Schiphol to convert hardware deployments into multi-year performance-based maintenance agreements. Deepen backward integration into specialized infrared detector array production to reduce exposure to Asian foundry concentration risks. Counter emerging dual-technology entrants by accelerating Raman spectroscopy integration timelines ahead of formal EU ESR enforcement deadlines. For New Entrants and Emerging Players: Enter via unbundled software and algorithm licensing to airport operators seeking to upgrade legacy ion mobility spectrometry systems without full platform replacement. Target UAE terminal expansion contracts where accelerated construction timelines favor flexible procurement specifications over entrenched vendor relationships. Pursue defense ministry dual-use certification pathways that permit civilian market entry under streamlined military-civilian technology transfer frameworks. For Investors and Strategic Acquirers: EU ESR framework revision announcements are the leading indicator that certification-grade system valuations will decouple from commodity security hardware multiples. Five-to-ten year viability hinges on aftermarket service revenue capture rather than initial system sale margins. Acquisition target archetype: spectroscopy specialists with pending TSA 49 CFR approvals and established university research partnerships feeding algorithm development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment Acceleration | Compresses multi-year TSA 49 CFR and EU ESR approval timelines ahead of enforcement deadlines. |
| Service Contract Unbundling | Converts dense installed bases at Atlanta Hartsfield-Jackson and Dubai International into recurring revenue streams. |
| Dual-Technology Platform Integration | Fuses ion mobility spectrometry with Raman spectroscopy to resolve sensitivity-specificity trade-offs in checkpoint applications. |
| Backward Integration into Sensor Arrays | Captures supply chain margin and reduces exposure to Taiwan and South Korean foundry concentration risks. |
| UAE Hub Airport Partnership | Secures billion-dollar terminal expansion contracts with centralized monitoring architecture specifications. |
Methodological Framework
Document review covered TSA procurement databases, EU ESR framework revision notices, and airport operator capital expenditure disclosures, complemented by interviews with checkpoint systems procurement officers at major international hubs, spectroscopy engineering directors at defense contractors, and aviation security regulatory affairs leads. Secondary validation drew from Department of Homeland Security contract award announcements, Federal Ministry of Transport equipment standard filings, and General Civil Aviation Authority procurement specifications. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology modality, and end-user vertical dimensions.
Installed base replacement cycle modeling produced volume and value estimates across the projection horizon by correlating regulatory mandate upgrade timelines with equipment depreciation schedules. Segmentation dimensions incorporated handheld versus stationary form factors, ion mobility spectrometry versus infrared spectroscopy technology splits, and transportation security versus defense end-user distinctions. CAGRs derived from regression analysis of historical procurement patterns against TSA and EU ESR enforcement phase-in schedules, with cross-reference to semiconductor component lead time fluctuations and rare earth magnet price indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical supply disruption scenarios affecting Taiwanese foundry capacity or Chinese rare earth export restrictions. Model outputs reflect documented assumptions regarding EU ESR harmonization adoption rates and UAE terminal expansion completion schedules. A model refresh is warranted upon material change in TSA certification backlog processing times or EU member state derogation requests.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Hitoxic Gas Detector Market