
 Global IR Spectroscopy Market | 2026-2036
Global IR Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global IR Spectroscopy Market Outlook
Chinese optical component foundries is restructuring supply chains for interferometer assemblies and detector arrays, tightening availability for mid-tier instrument makers. Bruker Corporation leverages its captive germanium crystal production to sustain margin control across FTIR modules. Thermo Fisher Scientific anchors its position through embedded software ecosystems that lock in pharmaceutical compliance workflows. Agilent Technologies, Inc. competes by specializing in compact NIR platforms for at-line food testing, a segment where bench-top footprint limits rival penetration.
IR spectroscopy measures molecular absorption of infrared radiation across the approximate 780 nm to 1 mm wavelength range, generating vibrational spectra that identify functional groups and chemical bonds within organic and inorganic samples. The technique serves as a non-destructive analytical foundation for quality assurance, forensic identification, and materials characterization across industrial and research settings. Fourier Transform instruments dominate installed base value due to superior signal-to-noise ratios and spectral resolution, while portable units represent the fastest-expanding shipment category as field environmental testing and pharmaceutical raw-material screening decentralize from central laboratories. ATR accessories are capturing disproportionate margin pools by eliminating sample preparation steps, a cost driver that chemical and food producers actively target for reduction.
FDA 21 CFR Part 11 compliance requirements and EMA GMP Annex 15 on qualification and validation shape instrument software architecture and audit trail capabilities, directly influencing R&D procurement criteria in regulated industries. China's NMPA and Japan's PMDA enforce converging pharmacopeial standards that demand interchangeable analytical methods, pushing vendors toward modular platform designs. REACH and RoHS frameworks in Europe restrict certain detector materials and electronics components, adding reformulation costs but also creating replacement demand for compliant successor instruments. Stakeholders must monitor divergence between regional digital data integrity standards, as misalignment between FDA electronic signature protocols and China's GB data localization rules threatens to fragment global product architectures and service delivery models.
Market Dynamics
Pharmaceutical raw-material verification mandates under tightened FDA and EMA pharmacopeial standards are compressing instrument replacement cycles and forcing modular platform architectures that accommodate interchangeable analytical methods across multinational manufacturing networks.
Growth Catalysts
- ATR accessory penetration:Attenuated Total Reflectance modules eliminate solvent-based sample preparation, cutting per-test costs for chemical producers in Germany and Japan. Food safety laboratories in the United States are standardizing these workflows for rapid contaminant screening.
- NMPA GMP annex enforcement:China's updated analytical method validation requirements are accelerating FTIR replacement demand at domestic pharmaceutical manufacturers. The regulator's inspection intensity is disqualifying legacy instruments that lack embedded audit trails.
- Process analytical technology (PAT):Continuous manufacturing adoption in East Asian electronics and specialty chemical clusters is embedding IR spectrometers directly into production lines. Real-time release testing protocols from Osaka to Shanghai are mandating inline verification.
Market Restraints
- Germanium crystal supply concentration:Captive production at dominant component foundries limits second-source availability for interferometer assemblies. Mid-tier instrument makers face allocation constraints during demand spikes.
- Detector material restrictions:REACH and RoHS frameworks in Europe are phasing out mercury-cadmium-telluride and certain lead-based compounds, forcing costly detector redesigns and shortening effective product lifecycles.
- Raman spectroscopy substitution:Water-Raman interference-free detection and superior spatial resolution are displacing IR in some pharmaceutical polymorphism studies and art conservation applications.
Strategic Opportunities
- Portable NIR decentralization:Field environmental testing and at-line food screening in India are bypassing central laboratory bottlenecks. Compact footprint instruments are penetrating facilities where bench space constraints previously blocked adoption.
- Software ecosystem lock-in:Embedded compliance workflows for FDA 21 CFR Part 11 and EMA Annex 15 are creating recurring revenue streams through validation protocol subscriptions and audit trail archiving services.
- Dual carbon alignment in China:MEE emissions monitoring mandates and MIIT green manufacturing incentives are funding IR-based continuous emissions monitoring systems at steel and petrochemical installations.
Industry Challenges
- Spectroscopist talent scarcity:Cross-functional expertise spanning chemometrics, regulatory documentation, and hardware troubleshooting is concentrating at top-tier pharmaceutical employers. Smaller contract laboratories face recruitment bottlenecks.
- Legacy LIMS integration:Pre-2010 laboratory information management systems at United States generics manufacturers lack API compatibility with modern instrument data streams, forcing costly middleware development or full system replacement.
- Multinational data localization conflicts:Divergent FDA electronic signature protocols and China's GB data residency rules are fragmenting global service architectures, complicating centralized instrument fleet management for multinational pharmaceutical companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IR Spectroscopy Market |
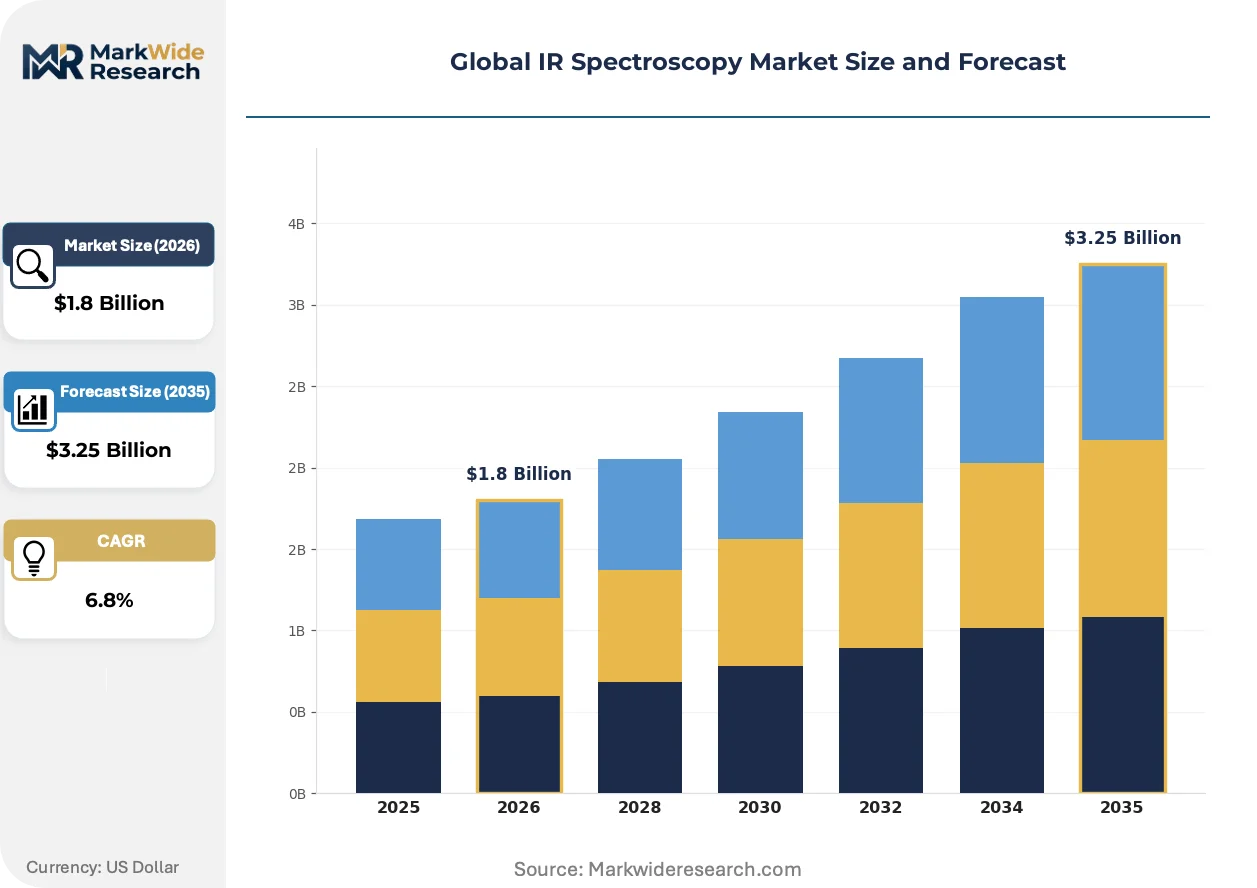
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-Top, Portable, FTIR, Dispersive End User: Pharmaceuticals, Chemicals, Food & Beverage, Environmental Testing Technology: Fourier Transform, NIR, ATR, Raman Application: Quality Control, Research & Development, Material Analysis, Process Monitoring |
| Companies Covered | Shimadzu Corporation, ZEISS, PerkinElmer Inc., Agilent Technologies, Inc., Bruker Corporation, Thermo Fisher Scientific Inc., Horiba, Ltd., Sartorius AG, Hitachi High-Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IR Spectroscopy Market Strategic Shifts
Modular hardware architectures and embedded compliance software are converging to reshape competitive positioning, while field-deployable form factors and AI-assisted spectral interpretation are compressing skill barriers for non-specialist operators.
Quantum cascade laser sources are integrating into mid-IR analyzers for high-brightness, room-temperature operation without liquid nitrogen cooling. Semiconductor fabrication facilities in Japan and South Korea are adopting these systems for real-time effluent monitoring. The technology is integrating process control loops that previously required offline gas chromatography confirmation, shrinking response latencies from hours to seconds.
EMA GMP Annex 15 qualification requirements and FDA process validation guidance are mandating instrument qualification documentation that traces from installation through operational to performance qualification. Pharmaceutical contract manufacturers in Ireland and Switzerland are demanding vendor-managed qualification packages to reduce internal validation burdens. This regulatory convergence is favoring suppliers with pre-validated method libraries and automated qualification execution tools.
Pharmaceutical procurement teams are consolidating analytical instrument vendor relationships to secure enterprise-wide service pricing and harmonized training curricula. Multisite manufacturers in Germany and the United States are replacing site-by-site purchasing with global framework agreements that bundle FTIR, NIR, and Raman platforms under single-source contracts. This consolidation is squeezing regional distributors and favoring direct manufacturer engagement models with dedicated key account management structures.
Global IR Spectroscopy Market Segmentation
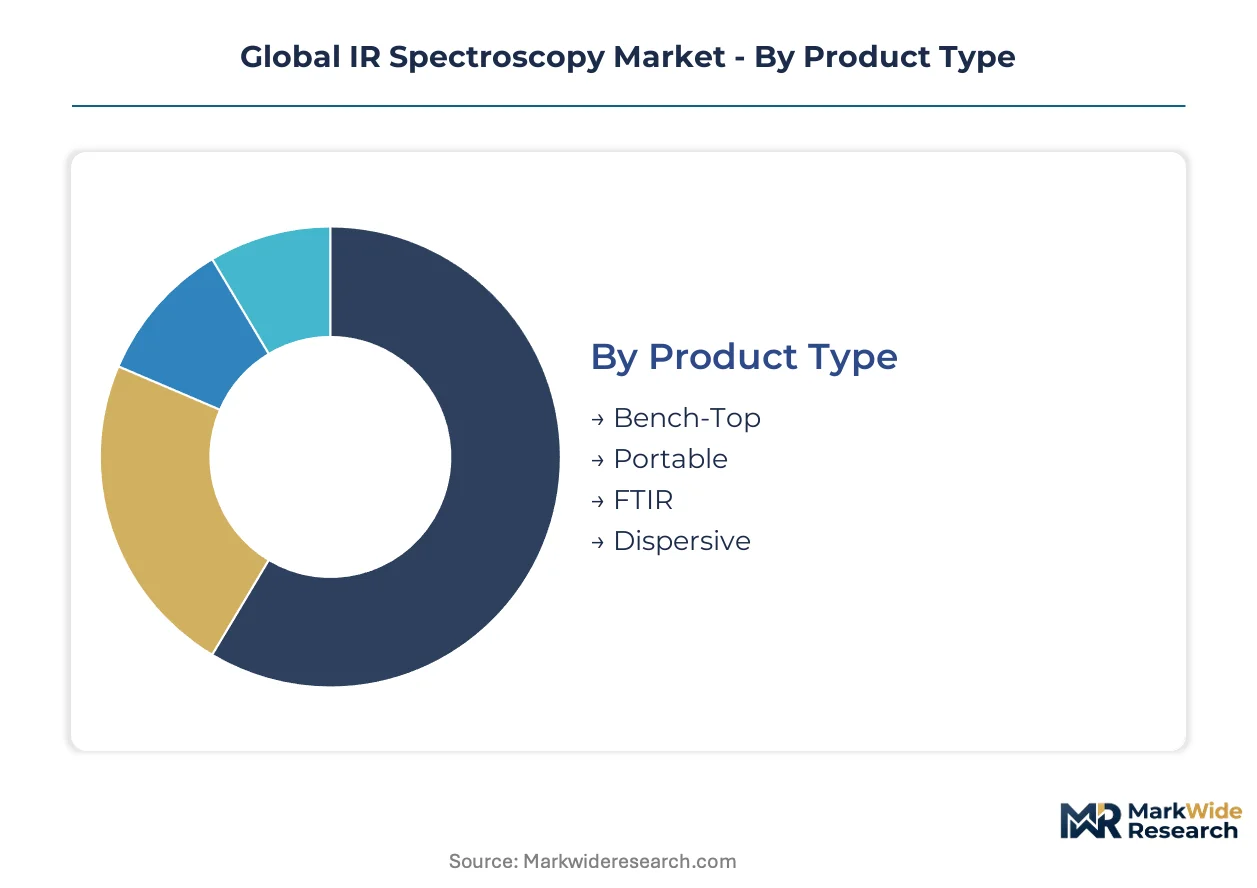
IR spectroscopy market segmentation reflects divergent integration depths across laboratory, production line, and field deployment contexts. Product form factors and technology architectures determine whether instruments operate as standalone analytical workstations or embed directly into continuous manufacturing systems.
Product Type:
Integration depth separates centralized laboratory systems from distributed at-line and inline configurations.
- Bench-Top:High-resolution optical benches with stabilized interferometer assemblies dominate pharmaceutical quality control laboratories in Germany and the United States. These systems anchor centralized analytical workflows where sample throughput justifies dedicated operator staffing and climate-controlled environments.
- Portable:Battery-powered NIR units with solid-state detector arrays are penetrating environmental field testing in India and food safety screening at Chinese agricultural collection points. Compact footprint instruments bypass central laboratory bottlenecks where infrastructure investment is prohibitive.
- FTIR:Fourier Transform platforms with Michelson interferometer designs deliver superior signal-to-noise ratios for complex mixture deconvolution.
- Dispersive:Grating-based scanning instruments serve educational and routine screening applications with lower capital requirements.
Bench-Top systems lead volumes today; Portable configurations are gaining share fastest.
End User:
Regulatory intensity and sample preparation automation requirements segment demand across compliance-driven versus throughput-driven buyers.
- Pharmaceuticals:FDA 21 CFR Part 11 and EMA GMP Annex 15 validation protocols mandate embedded audit trails and electronic signature workflows. Raw material verification at United States and Irish contract manufacturers compresses replacement cycles for instruments lacking pre-validated software packages.
- Chemicals:Continuous production lines in Osaka and Shanghai embed process monitoring spectrometers for real-time release testing. ATR accessories eliminate solvent preparation steps, cutting per-test costs for high-throughput polymer and petrochemical producers.
- Food & Beverage:At-line contaminant screening drives compact NIR adoption where bench space constraints previously blocked instrument deployment.
- Environmental Testing:Field decentralization in India and Southeast Asia favors battery-operated units for water quality and emissions monitoring.
Pharmaceuticals command premium pricing tiers; Chemicals show steepest expansion trajectory through PAT integration.
Technology:
Signal processing architecture and wavelength regime determine compatibility with existing laboratory infrastructure and operator skill levels.
- Fourier Transform:Interferometer-based signal encoding enables rapid spectral acquisition across broad wavelength ranges with exceptional resolution. Pharmaceutical laboratories in Switzerland and Germany standardize on FTIR platforms for pharmacopeial compliance and method transferability across multinational manufacturing networks.
- NIR:Diffuse reflectance and transmission geometries suit intact sample analysis without preparation, penetrating food and agriculture testing where speed outweighs molecular specificity requirements.
- ATR:Surface-sensitive sampling interfaces concentrate margin pools by eliminating consumables and solvent disposal costs.
- Raman:Complementary vibrational spectroscopy with water interference immunity displaces IR in select polymorphism studies and art conservation applications.
Fourier Transform anchors installed base value; NIR configurations are expanding most quickly in field-deployable formats.
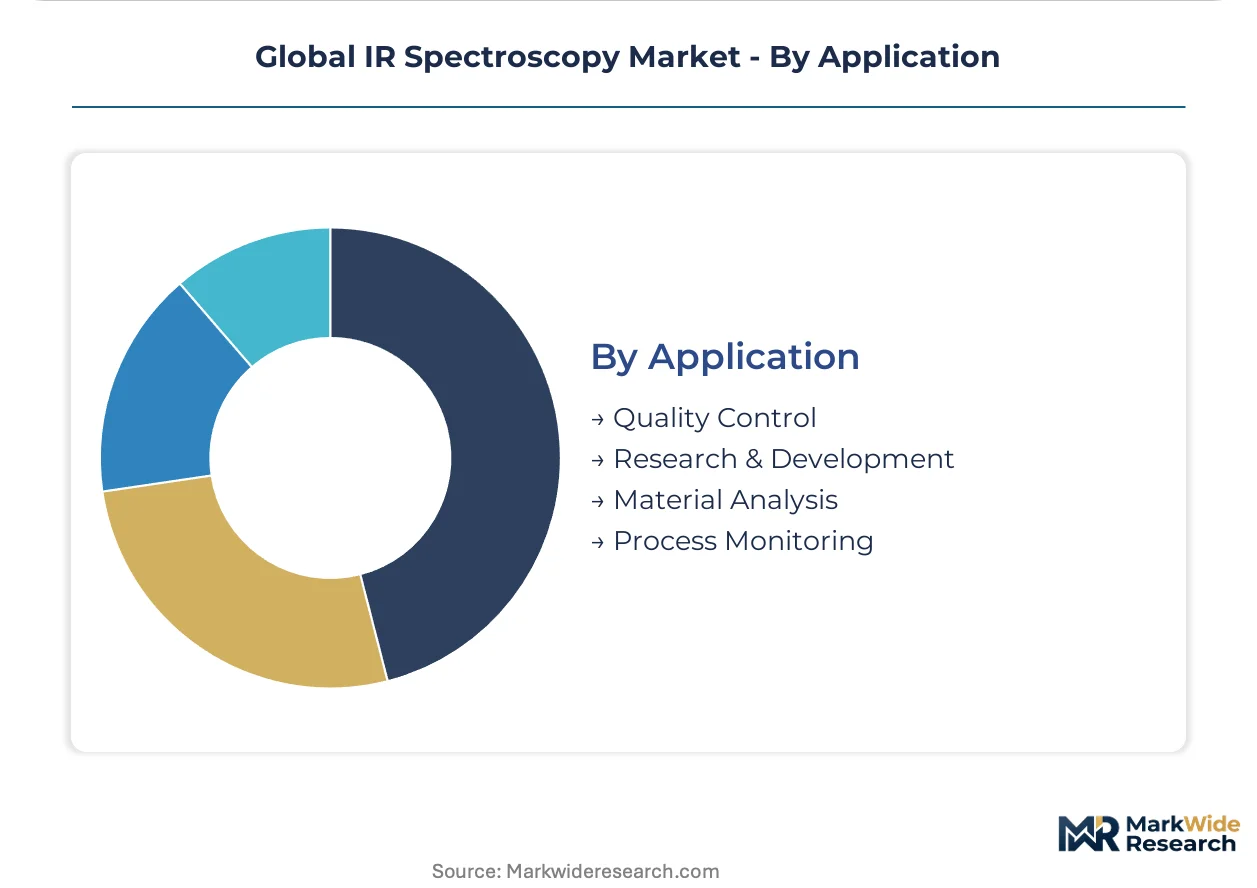
Application:
Decision latency requirements and regulatory documentation burdens differentiate centralized analytical development from production-embedded verification.
- Quality Control:Release testing protocols at FDA-inspected facilities demand instrument qualification documentation spanning installation through operational to performance qualification. Vendor-managed validation packages reduce internal documentation burdens at Irish and Swiss contract manufacturers.
- Process Monitoring:Inline spectrometers in East Asian electronics and specialty chemical clusters enable real-time release testing with response latencies compressed from hours to seconds. Quantum cascade laser sources integrate into mid-IR analyzers for room-temperature operation without liquid nitrogen cooling.
- Research & Development:Method development and polymorphism studies drive high-resolution instrument specifications.
- Material Analysis:Forensic identification and materials characterization support academic and industrial research settings.
Quality Control dominates revenue concentration; Process Monitoring climbs fastest through continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping instrument procurement patterns as pharmaceutical manufacturers migrate validation-intensive operations toward jurisdictions with harmonized pharmacopeial standards. Cost-of-compliance gaps between FDA and EMA jurisdictions versus emerging regulatory regimes are accelerating facility investment decisions.
United States
FDA 21 CFR Part 11 enforcement drives replacement demand at generics manufacturers lacking embedded audit trails. The regulator's inspection intensity disqualifies legacy instruments without electronic signature capabilities. Greater Boston and Research Triangle Park clusters concentrate contract manufacturing organizations upgrading to pre-validated FTIR platforms.
Germany
REACH and RoHS frameworks force detector material redesigns while creating replacement demand for compliant successor instruments. EMA GMP Annex 15 qualification requirements shape vendor selection criteria. The Rhine-Main and Upper Bavaria pharmaceutical corridors anchor centralized analytical workflows with climate-controlled laboratory infrastructure.
China
NMPA GMP annex enforcement accelerates domestic pharmaceutical manufacturer replacement cycles. MIIT green manufacturing incentives fund IR-based continuous emissions monitoring at steel installations. The Yangtze River Delta around Shanghai concentrates chemical producers integrating process monitoring spectrometers into continuous production lines.
Japan
PMDA pharmacopeial standards demand interchangeable analytical methods across multinational manufacturing networks. METI industrial policy supports quantum cascade laser adoption for semiconductor fabrication effluent monitoring. The Osaka-Kobe manufacturing belt embeds inline verification systems for real-time release testing protocols.
India
CDSCO tightening of analytical method validation requirements compresses instrument replacement cycles at domestic formulation facilities. FSSAI food safety mandates drive portable NIR adoption at agricultural collection points. The Hyderabad-Bengaluru pharmaceutical corridor expands contract research organization capacity with harmonized validation documentation.
Global IR Spectroscopy Market Competitive Environment
German and Swiss producers anchor the premium instrumentation tier; Japanese specialists hold positions in optical component precision manufacturing. The vendor base concentrates around three strategic archetypes: diversified analytical conglomerates with captive supply chains, pure-play spectroscopy specialists with modular platform architectures, and regional system integrators serving compliance-driven replacement markets. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure germanium crystal allocations and software ecosystem lock-in.
Among diversified analytical conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. exemplify the embedded software ecosystem approach, while Bruker Corporation represents captive vertical integration into optical component production. These three anchors occupy positions spanning pharmaceutical compliance workflows to compact at-line testing platforms, with each sitting within distinct competitive vectors shaped by regulatory convergence and manufacturing decentralization trends.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| ZEISS |
| PerkinElmer Inc. |
| Agilent Technologies, Inc. |
| Bruker Corporation |
| Thermo Fisher Scientific Inc. |
| Horiba, Ltd. |
| Sartorius AG |
| Hitachi High-Tech Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH and RoHS frameworks gate qualified supply for European pharmaceutical and chemical buyers, reserving premium-tier pricing access to vendors with compliant detector materials and reformulated electronics. Manufacturers lacking certified component streams face exclusion from EMA-regulated procurement channels while absorbing redesign costs that compress mid-tier margins.
Pricing Analysis
Distributor margins concentrate value capture in the 15-25% range for FTIR platforms sold through regional life science channels. Three-tier pricing structure across premium, standard, and economy levels separates pre-validated pharmaceutical compliance systems from basic educational units. Pricing pressure stems from Raman spectroscopy substitution in polymorphism applications, forcing IR vendors to bundle software validation services. Contract research organizations in India exhibit highest price sensitivity; Swiss and Irish pharmaceutical manufacturers prioritize qualification documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with germanium crystal production concentrated in China and the United States, constraining interferometer assembly availability during demand spikes. Detector arrays draw from specialized foundries in Japan and South Korea, with mercury-cadmium-telluride phase-outs under REACH forcing material transitions. Tariff exposure on optical-grade substrates threatens margin stability for mid-tier instrument makers. Distribution runs through manufacturer-direct key account management for multinational pharmaceutical consolidators, supplemented by regional distributors serving replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IR Spectroscopy Market compounds steadily as regulatory compliance mandates compress instrument replacement cycles across pharmaceutical manufacturing networks. Continuous manufacturing adoption in East Asian chemical and electronics clusters embeds spectroscopic verification as non-discretionary capital equipment.
For Market Incumbents: Anticipate Raman displacement in pharmaceutical polymorphism studies by accelerating AI-assisted spectral interpretation development and embedding predictive maintenance algorithms into service contracts. Deepen backward integration into optical component production to secure germanium crystal allocations against supply shocks. Prioritize pre-validated software ecosystems that lock in FDA and EMA compliance workflows.
For New Entrants and Emerging Players: Begin with portable NIR platforms for Indian environmental field testing and Chinese agricultural collection points where bench space constraints previously blocked centralized laboratory adoption. Target food safety screening applications with compact footprint instruments priced below established pharmaceutical tiers. Pursue distribution partnerships with regional system integrators possessing existing compliance documentation capabilities.
For Investors and Strategic Acquirers: Roll-up economics work for modular platform specialists because pharmaceutical procurement consolidation favors vendors with interchangeable analytical methods across multinational manufacturing networks. Five-to-ten year viability rests on software subscription revenue streams from validation protocol archives and audit trail services. Monitor NMPA inspection intensity as inflection signal for Chinese replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Bruker's captive germanium crystal production sustains margin control against allocation constraints. |
| Pre-Validated Software Ecosystem Deployment | Thermo Fisher's embedded compliance workflows lock in pharmaceutical procurement at Irish contract manufacturers. |
| Portable NIR Platform Launch | Agilent's compact footprint instruments penetrate Indian field testing where central laboratory infrastructure is absent. |
| Quantum Cascade Laser Integration | Japanese semiconductor fabrication facilities adopt room-temperature mid-IR analyzers for real-time effluent monitoring. |
| Vendor-Managed Qualification Packaging | Swiss and Irish contract manufacturers outsource validation documentation burdens to instrument suppliers. |
Study Parameters
Bottom-up pharmaceutical and chemical end-use modeling reconciled against top-down instrument shipment tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at contract manufacturers, procurement directors at multinational pharmaceutical companies, plant engineers at East Asian chemical facilities, and service heads at regional distributors informed demand-side assumptions. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 15 qualification requirements, NMPA GMP annex enforcement notices, and customs trade data on optical component flows.
Input-output matrices mapped FTIR, NIR, and portable platform volumes against end-user replacement cycles, regulatory inspection intensities, and continuous manufacturing adoption curves across the analysis window. Segmentation dimensions included product form factor, technology architecture, application context, and regional regulatory cluster. CAGRs were derived from instrument replacement frequency modeling and process analytical technology penetration rates, with cross-checks against vendor-reported order backlogs and qualification service contract renewals.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between FDA electronic signature protocols and China's GB data localization rules, abrupt detector material substitutions under accelerated REACH timelines, and Raman spectroscopy cost reductions that could accelerate displacement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Network Analyzers Market