
 Contour Measuring Machines Market | 2026-2036
Contour Measuring Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Contour Measuring Machines Market Outlook
Capital-intensity divergence between sensor-integrated platform builders and standalone probe suppliers is rotating competitive advantage toward vertically resourced metrology houses. Mitutoyo Corporation leverages its captive optical component foundries to compress lead times on hybrid contact-non-contact systems. Hexagon AB anchors its position through software-defined inspection workflows that lock in recurring calibration revenue. Carl Zeiss AG dominates ultra-high-precision optical benches where semiconductor wafer manufacturers demand sub-micron repeatability.
Contour measuring machines are dimensional inspection instruments that trace surface profiles through stylus contact, laser triangulation, or chromatic confocal methods to quantify deviations from nominal geometry against ISO 1101 tolerances. These systems serve primarily as gatekeeping tools in quality control loops where aerospace turbine blades, orthopedic implants, and electric motor laminations must certify form error before downstream assembly. Optical and laser segments are pulling ahead as non-contact methods displace mechanical styli in soft-material and high-throughput electronics inspection, while contact technology retains its grip on roughness-critical automotive powertrain verification where diamond-tip probing remains the reference method. Hybrid architectures that fuse tactile and optical modalities in single platforms are capturing the fastest expansion as manufacturers seek to collapse multi-station inspection into unified cells.
FDA device-quality regulations in the United States and EU MDR conformity requirements in Europe mandate validated traceability chains for contour data in orthopedic and cardiovascular implant production, directly elevating demand for ISO 17025-calibrated systems. China's GB standards and NMPA medical device rules enforce comparable metrology rigor for domestic manufacturers targeting export certification. Stakeholders must monitor how AI-driven inline inspection modules from Keyence Corporation and Renishaw plc reshape the boundary between shop-floor rough screening and laboratory-grade contour analysis.
Market Dynamics
Automotive and aerospace manufacturers are consolidating multi-station inspection workflows into unified hybrid platforms, compressing capital deployment cycles and elevating software-defined calibration services above hardware margins.
Growth Catalysts
- ISO 1101 tolerance verification:Tightening geometric dimensioning standards across German and Japanese automotive supply chains mandate sub-micron contour validation for powertrain components.
- FDA device-quality traceability:United States orthopedic implant manufacturers must maintain validated measurement chains under 21 CFR Part 820, directly elevating demand for ISO 17025-calibrated systems.
- Laser triangulation advancement:Non-contact optical methods now penetrate soft-material electronics inspection where mechanical styli risk surface damage.
Market Restraints
- Optical component supply concentration:Precision interferometer sources and chromatic confocal objectives concentrate among Japanese and German specialty foundries, exposing lead time volatility.
- EU MDR conformity timelines:Extended notified body certification cycles for cardiovascular implant metrology systems delay revenue recognition for equipment vendors.
- AI-driven inline modules:Shop-floor rough screening systems from industrial automation suppliers erode the boundary between production-line gauging and laboratory-grade contour analysis.
Strategic Opportunities
- China domestic medical device export certification:NMPA enforcement of GB standards for metrology rigor creates captive demand among domestic manufacturers seeking European market access.
- Semiconductor wafer sub-micron benches:Advanced packaging nodes below 7nm require optical benches with repeatability thresholds unattainable by conventional stylus systems.
- Electric vehicle motor lamination inspection:Stator core geometric verification for high-speed traction motors represents an emerging volume application with distinct throughput requirements.
Industry Challenges
- Multi-sensor fusion expertise:Hybrid contact-non-contact platforms demand rare cross-functional competence in tactile probing physics, optical system alignment, and correlated software compensation algorithms.
- Legacy CMM integration:Brownfield manufacturing cells require complex retrofitting of contour modules into existing quality management software architectures without disrupting serialized traceability chains.
- Calibration technician certification:ISO 17025 laboratory accreditation depends on scarce personnel holding dimensional metrology credentials from national standards bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contour Measuring Machines Market |
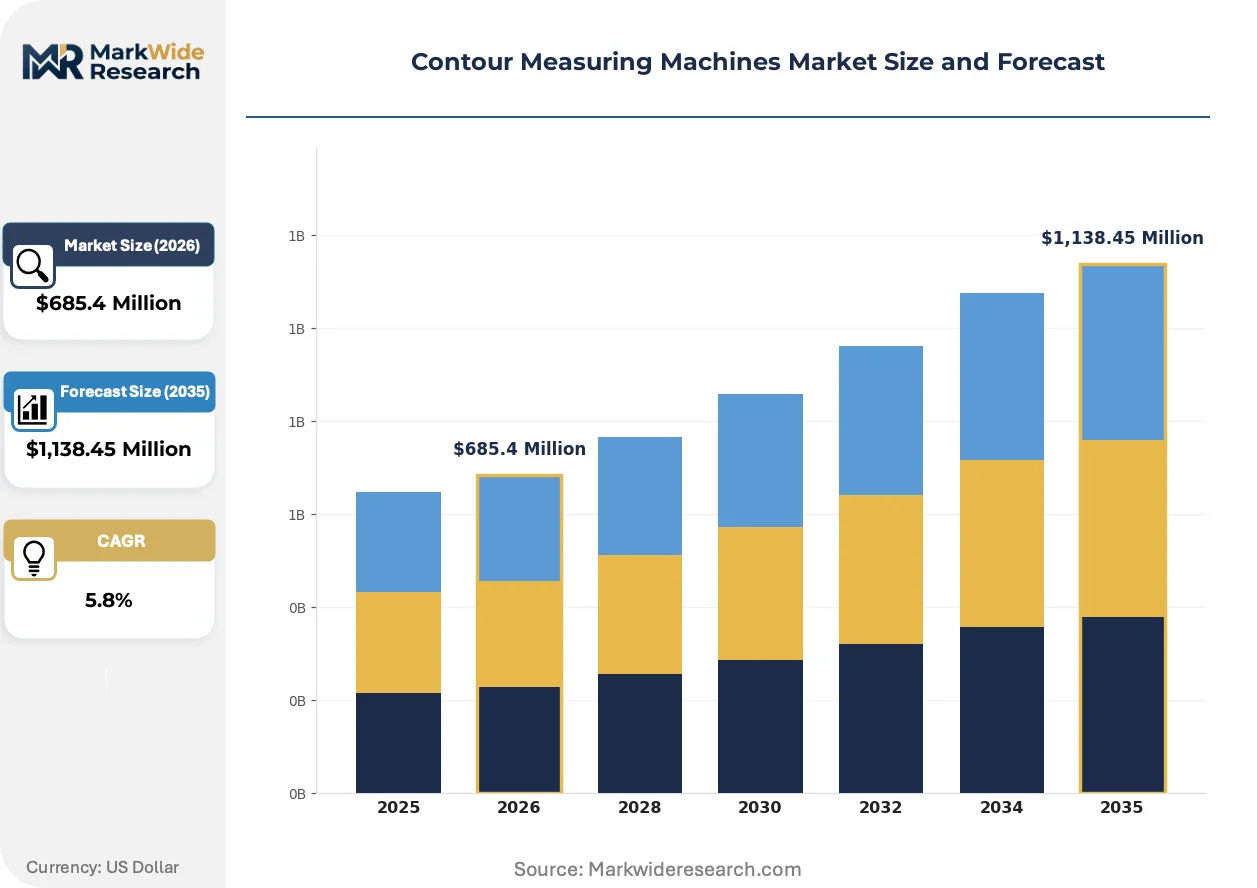
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
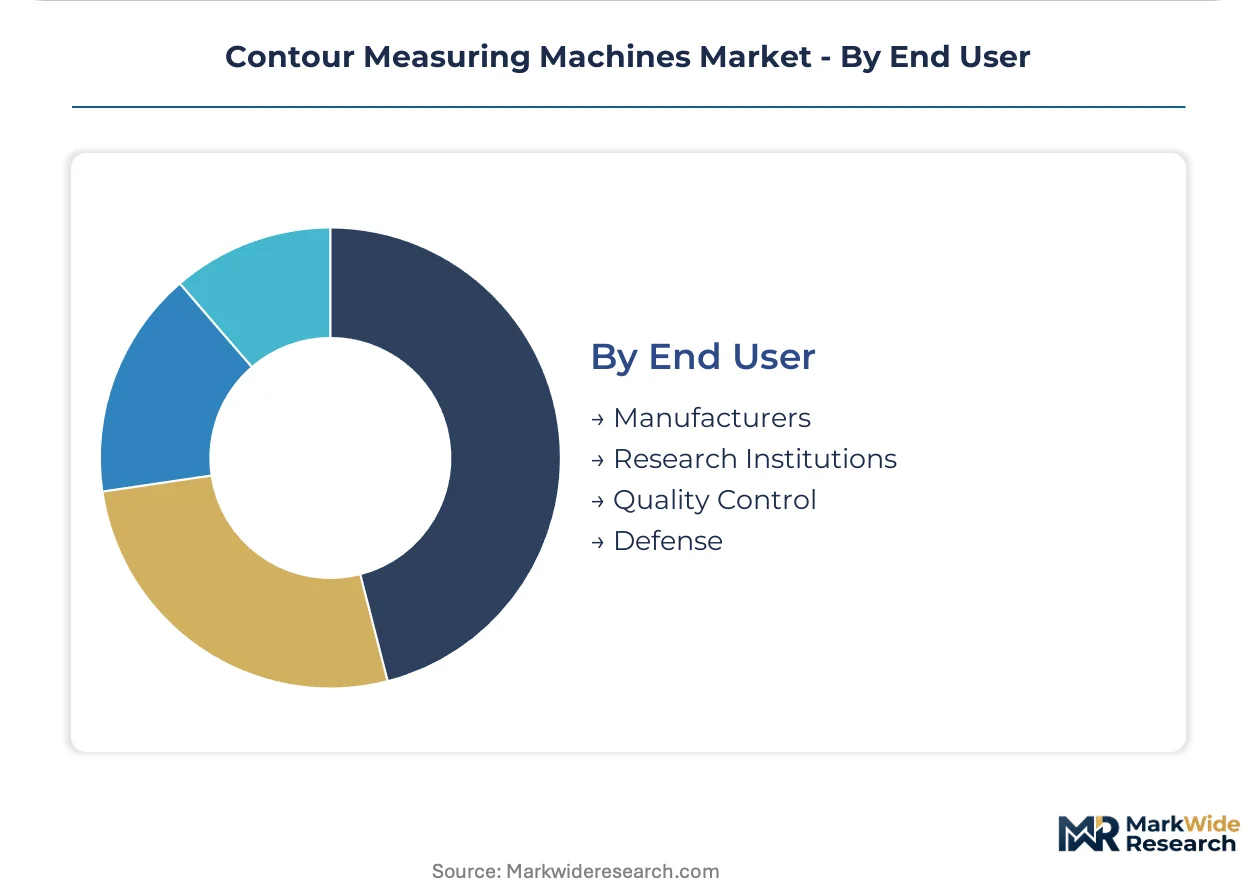
| Segmentation | Product Type: CMM, Optical, Laser, Handheld Application: Aerospace, Automotive, Electronics, Medical Technology: Contact, Non-Contact, Hybrid, Advanced Imaging End User: Manufacturers, Research Institutions, Quality Control, Defense |
| Companies Covered | Mitutoyo Corporation, Hexagon AB, Carl Zeiss AG, Keyence Corporation, Nikon Metrology, Renishaw plc, Faro Technologies, Wenzel Group, Taylor Hobson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contour Measuring Machines Market Strategic Shifts
Sensor convergence and software-defined inspection architectures are collapsing the traditional separation between shop-floor rough gauging and laboratory-grade contour analysis, redistributing value toward calibration services and data analytics layers.
Chromatic confocal microscopy is miniaturizing into compact probe heads that mount directly on multi-axis CMM gantries, enabling simultaneous surface finish and form measurement without workpiece reclamping. Medical device manufacturers in Switzerland and Germany are piloting these integrated heads for orthopedic implant thread verification. The technology is miniaturizing inspection cell footprints by eliminating separate roughness stations.
EU MDR conformity requirements now mandate design dossier traceability for active implantable devices, forcing cardiovascular stent manufacturers to document contour measurement uncertainty budgets in regulatory submissions. French and German notified bodies are rejecting submissions lacking ISO 14253-1-compliant uncertainty statements. This elevates demand for systems with embedded GUM-compliant calculation engines.
Buyers are unbundling after-sales calibration contracts from initial equipment purchases, treating metrology service providers as distinct procurement categories. Tier-one automotive suppliers in Bavaria and Michigan now source calibration from third-party laboratories even when original equipment warranties remain active. The shift compresses vendor service margins while expanding independent laboratory market entry.
Contour Measuring Machines Market Segmentation
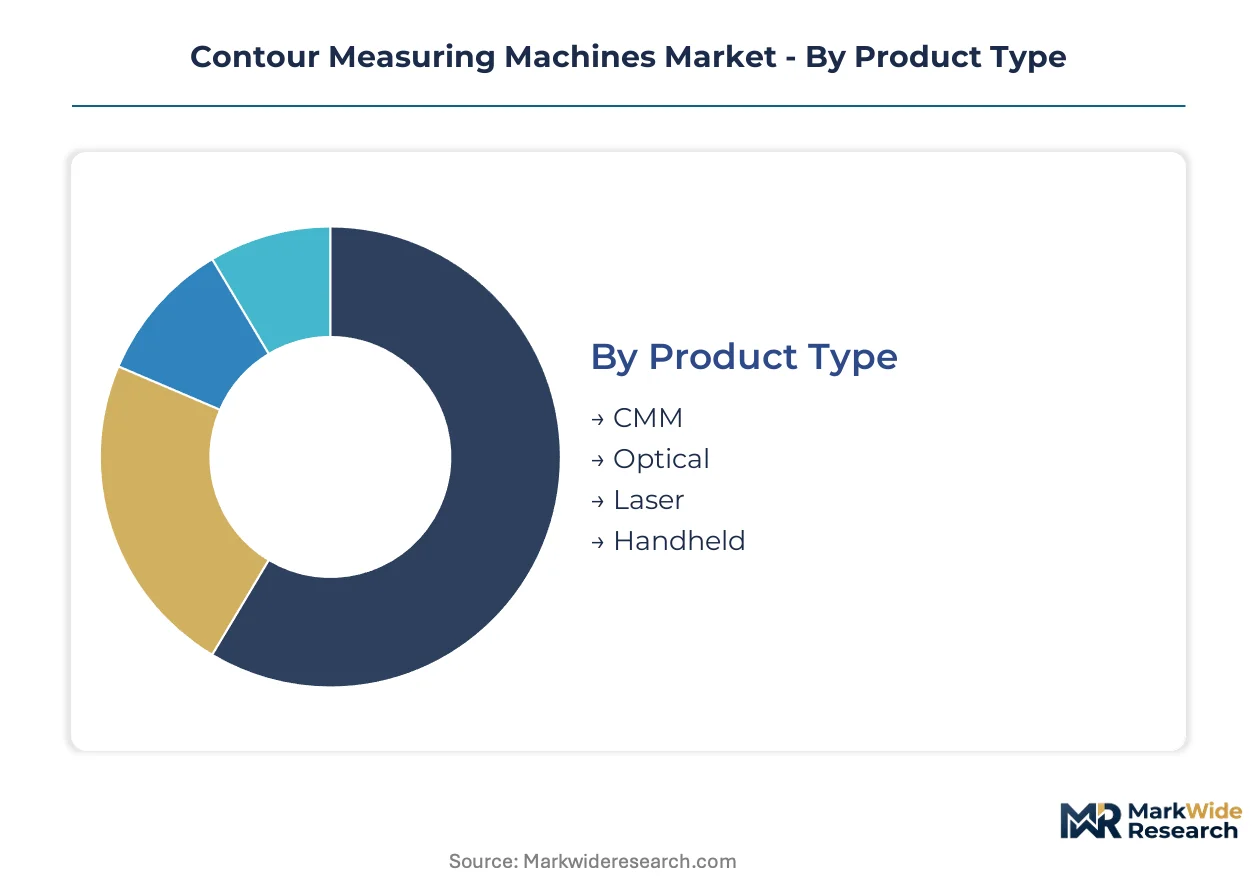
Contour measuring machines serve distinct inspection protocols across manufacturing verticals, with regulatory requirements from FDA, EU MDR, and China's NMPA dictating calibration standards and traceability chains for each segment. Understanding how product architectures, application environments, and end-user capabilities intersect reveals where capital deployment concentrates and where technology transitions accelerate.
Product Type:
ISO 17025 calibration requirements and FDA 21 CFR Part 820 traceability mandates create tiered compliance burdens that separate laboratory-grade systems from shop-floor portable units.
- CMM:Bridge and gantry coordinate measuring machines anchor automotive powertrain verification in Germany and Japan, where ISO 1101 tolerance protocols demand sub-micron repeatability for crankshaft and camshaft form analysis. German automotive suppliers in Bavaria deploy these as centralized metrology laboratory anchors, with calibration contracts often exceeding initial hardware depreciation cycles.
- Optical:Vision-based contour systems leverage chromatic confocal and white-light interferometry for semiconductor wafer inspection below 7nm packaging nodes, with Swiss and German medical device manufacturers piloting integrated heads for orthopedic implant thread verification. The technology eliminates separate roughness stations and compresses inspection cell footprints.
- Laser:Triangulation and confocal laser systems penetrate soft-material electronics inspection where mechanical styli risk surface damage on flexible PCBs and display laminates.
- Handheld:Portable articulated-arm systems serve brownfield aerospace maintenance facilities requiring wing-skin contour verification without workpiece transport to fixed metrology labs.
CMM platforms handle the majority of throughput in centralized quality laboratories; laser systems are gaining share fastest as non-contact methods displace mechanical styli in high-throughput electronics corridors.
Application:
End-use concentration in precision manufacturing corridors across China, Germany, and the United States determines regional specification requirements and service network density.
- Aerospace:Turbine blade form verification for jet engines demands hybrid contact-non-contact platforms capable of resolving cooling hole geometries and airfoil profiles in single setups. US and French suppliers face FAA and EASA certification chains that mandate serialized traceability for every measured feature.
- Automotive:Powertrain component inspection—cylinder block deck flatness, transmission gear tooth form, electric motor stator lamination geometry—drives volume demand in German, Japanese, and US manufacturing clusters. EU MDR and FDA device-quality regulations do not directly govern this segment, but IATF 16949 quality management systems impose comparable metrology rigor.
- Electronics:Miniaturized optical systems inspect micro-connector pin arrays and flexible circuit contours where mechanical probing risks damage. China's PCB manufacturing corridors in Guangdong and Jiangsu provinces concentrate demand for high-throughput non-contact platforms.
- Medical:Orthopedic implant thread verification and cardiovascular stent geometry certification face the strictest regulatory overlay—FDA 21 CFR Part 820 in the United States, EU MDR in Europe, and NMPA rules in China all mandate validated measurement uncertainty budgets in design dossiers.
Automotive applications absorb the largest equipment volume; medical represents the steepest expansion trajectory as regulatory compliance elevates system specifications and calibration service attach rates.
Technology:
Physics-based performance ceilings and cost structures stratify adoption across roughness-critical automotive verification and damage-sensitive electronics inspection.
- Contact:Diamond-tip stylus probing remains the reference method for ISO 4287 surface roughness parameters and automotive powertrain form verification, with German and Japanese supply chains treating mechanical measurement as the arbitration standard for supplier disputes.
- Non-Contact:Laser triangulation and chromatic confocal methods now penetrate electronics and soft-material inspection where stylus loading risks surface deformation, with throughput advantages in high-volume PCB and display manufacturing.
- Hybrid:Single-platform fusion of tactile and optical modalities captures the fastest adoption as manufacturers collapse multi-station inspection into unified cells, though cross-functional expertise in probing physics and optical alignment remains scarce.
- Advanced Imaging:Computed tomography and structured-light systems enable internal geometry capture for additive-manufactured lattice structures and complex cooling channels inaccessible to line-of-sight methods.
Contact technology retains the installed base majority; hybrid architectures are climbing fastest as capital efficiency pressures consolidate inspection workflows.
End User:
Procurement sophistication and in-house metrology capability separate captive calibration laboratories from outsourced third-party service relationships.
- Manufacturers:Tier-one automotive suppliers in Michigan and Bavaria increasingly unbundle calibration contracts from initial equipment purchases, treating metrology service providers as distinct procurement categories even under active warranties.
- Research Institutions:National standards laboratories and university metrology centers anchor traceability chains for industrial calibration, with NIST in the United States, PTB in Germany, and NIM in China maintaining primary realizations of dimensional standards.
- Quality Control:Independent testing laboratories gain share as outsourced inspection destinations for small and mid-sized manufacturers lacking ISO 17025 accreditation in-house.
- Defense:Military aerospace and munitions contractors face distinct cybersecurity and supply-chain security protocols that restrict cloud-connected inspection systems and foreign-sourced sensor components.
Manufacturers dominate equipment procurement volume; quality control laboratories are expanding most quickly as independent calibration services capture unbundled contract flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers command premium pricing for ISO 1101-certified systems, while Chinese manufacturers in Guangdong and Jiangsu provinces compress margins through high-volume non-contact platform production.
Germany
Bavarian powertrain clusters in Munich and Ingolstadt drive concentrated demand for hybrid contact-non-contact systems serving crankshaft and camshaft verification. KBA enforcement of tighter geometric tolerances under EU automotive directives elevates calibration service attach rates. Stuttgart-based metrology houses anchor centralized quality laboratories for tier-one suppliers.
United States
Michigan automotive corridors and Greater Boston medical device clusters generate divergent specification requirements for electric motor laminations and orthopedic implants. FDA 21 CFR Part 820 mandates validated measurement chains for cardiovascular stent manufacturers, directly elevating ISO 17025 system demand. Aerospace turbine blade inspection in Connecticut and South Carolina sustains hybrid platform procurement.
China
Guangdong and Jiangsu PCB manufacturing corridors concentrate high-throughput laser triangulation demand for flexible circuit inspection. NMPA enforcement of GB standards for medical device export certification creates captive demand among domestic manufacturers targeting European market access. Shanghai and Beijing anchor national standards traceability through NIM laboratories.
Japan
Nagoya automotive supply chains and Tokyo-Yokohama electronics clusters sustain dual technology tracks for powertrain roughness verification and soft-material display inspection. METI industrial standards harmonization with ISO protocols accelerates non-contact method adoption. Precision optical component foundries in Osaka and Kyoto expose lead time volatility for chromatic confocal objectives.
Switzerland
Swiss orthopedic implant manufacturers in Solothurn and Vaud pilot chromatic confocal probe heads for thread verification under Swissmedic quality oversight. EU MDR conformity requirements for active implantable devices elevate demand for GUM-compliant uncertainty calculation engines. Precision machining valleys around Biel and La Chaux-de-Fonds concentrate high-value metrology procurement.
Contour Measuring Machines Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the value chain. Vertically integrated metrology houses with captive optical component supply command premium positioning in sub-micron repeatability segments, while modular platform assemblers compete on deployment speed and software flexibility. Two strategic archetypes dominate: sensor-integrated platform builders leveraging backward integration into optical foundries, and software-defined workflow providers capturing recurring calibration revenue. Consolidation pressure intensifies through strategic partnerships bridging tactile probing physics with optical system alignment expertise.
Within the vertically integrated tier, Mitutoyo Corporation and Carl Zeiss AG exemplify archetypes combining captive manufacturing depth with laboratory-grade certification authority. Hexagon AB occupies a position emphasizing software-defined inspection architectures that embed recurring service relationships. These three anchors illustrate how competitive advantage rotates toward entities controlling both hardware production and calibration infrastructure rather than standalone probe supply.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Hexagon AB |
| Carl Zeiss AG |
| Keyence Corporation |
| Nikon Metrology |
| Renishaw plc |
| Faro Technologies |
| Wenzel Group |
| Taylor Hobson |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-week lead times for chromatic confocal objectives from Japanese and German specialty foundries compress inventory buffers and amplify pricing power for vertically integrated metrology houses. Buyers face stark trade-offs between expedited delivery premiums and extended procurement cycles.
Pricing Analysis
Configured-to-order hybrid platforms command 40-60 percent premiums over standard CMM configurations due to cross-functional engineering demands. Three-tier pricing structure across ISO 17025-certified laboratory systems, shop-floor production units, and portable audit equipment reflects calibration-grade differentiation. Cost compression in high-volume laser triangulation segments stems from Chinese PCB corridor procurement at scale. Tier-one automotive suppliers exhibit lowest price sensitivity given traceability mandates; mid-tier electronics assemblers face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of precision interferometer sources dominates inventory strategy among German and Japanese metrology houses, while modular assemblers maintain lean just-in-time flows. Optical component supply concentrates in Japan, Germany, and Switzerland. Production draws from specialty glass substrates, precision motion stages, and embedded sensor arrays. Single-source vulnerability for sub-micron repeatability optics exposes lead time volatility. Distribution runs through direct OEM relationships and certified distributor networks serving medical device and aerospace verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 1101 tolerance tightening and EU MDR conformity expansion are accelerating technology turnover in contour metrology, compressing replacement cycles and elevating service revenue capture.
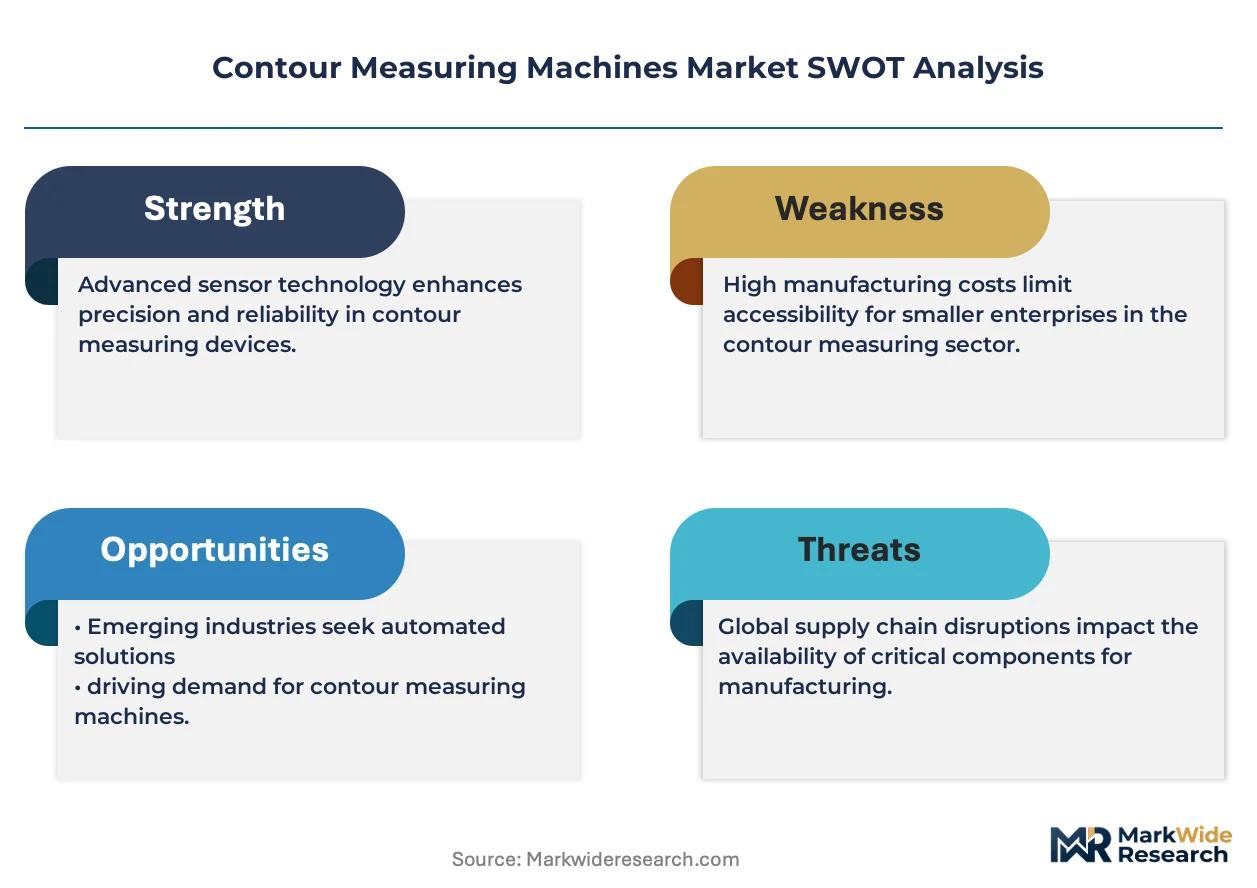
For Market Incumbents: Consolidate optical component supply through captive foundry investments or exclusive sourcing agreements to defend against lead time volatility. Deepen software-defined inspection architectures that embed recurring calibration revenue streams, neutralizing modular platform assemblers competing on deployment speed.
For New Entrants and Emerging Players: ISO 17025 fast-track accreditation for independent calibration laboratories captures unbundled contract flows from tier-one automotive suppliers. Target electric vehicle motor lamination inspection as the most penetrable volume application. Lead with subscription-based metrology-as-a-service models that circumvent capital procurement barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized metrology divisions lacking software layer investment. Long-term viability hinges on calibration infrastructure ownership rather than hardware shipment volumes. Watch AI-driven inline inspection module adoption rates as the signal distinguishing laboratory-grade from shop-floor displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Foundries | Mitutoyo's captive component production compresses lead times on hybrid systems. |
| Software-Defined Inspection Architecture | Hexagon embeds recurring calibration revenue through workflow lock-in. |
| ISO 17025 Laboratory Accreditation | Independent labs capture unbundled contracts from Bavarian automotive suppliers. |
| Chromatic Confocal Probe Miniaturization | Swiss orthopedic manufacturers pilot integrated heads for thread verification. |
| AI-Driven Inline Module Development | Keyence and Renishaw reshape boundaries between shop-floor and laboratory analysis. |
Study Parameters
The analysis maps contact, non-contact, hybrid, and advanced imaging technology segments, each validated through primary interviews with quality engineering directors, metrology laboratory managers, biomedical device regulatory leads, and automotive tier-one procurement officers. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, NMPA registration databases, and ISO 17025 accreditation records. Bottom-up equipment shipment estimates triangulate against top-down manufacturing value-added projections.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology type, application vertical, end-user capability tier, and regional regulatory cluster. CAGRs derive from segment-level growth rate synthesis calibrated to capital expenditure cycle timing. Forecast inputs include semiconductor packaging node advancement rates and electric vehicle motor production ramp schedules.
Underlying assumptions cover ISO standard harmonization trajectories, with deviation risk concentrated in EU MDR notified body capacity constraints and optical component supply disruptions. Revision becomes warranted when AI-driven inline inspection accuracy crosses laboratory-grade uncertainty thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
UV Conveyor Systems Market