
 Fingerprint Identification Chip Market | 2026-2036
Fingerprint Identification Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Fingerprint Identification Chip Market Foresight
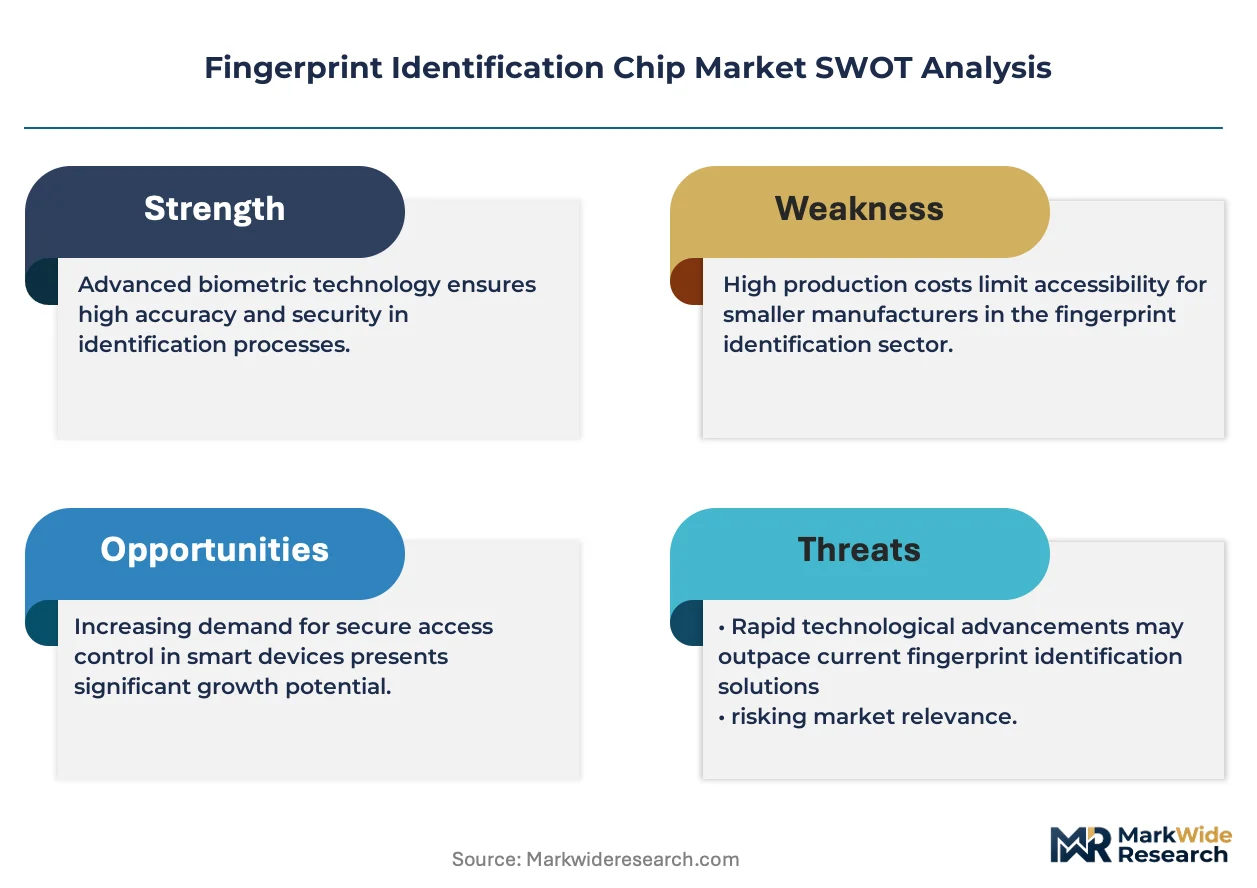
The EU AI Act is hardening compliance requirements for biometric authentication systems across consumer devices and enterprise security infrastructure. Goodix Technology Co., Ltd. leverages its capacitive sensor portfolio to dominate smartphone integration volumes in Asia. Fingerprint Cards AB anchors European design-in relationships with tier-one handset OEMs through its ultra-thin sensor modules. Synaptics Incorporated competes by extending its touch controller expertise into under-display ultrasonic architectures.
A fingerprint identification chip is a semiconductor device that captures, processes, and matches ridge patterns from human fingertips using arrays of sensing elements typically fabricated on CMOS wafers with pixel densities exceeding 500 dots per inch. These chips authenticate identity in mobile devices, payment terminals, and access control systems by converting analog capacitive or ultrasonic signals into encrypted digital templates. Capacitive sensors occupy the highest volume tier due to mature cost curves and smartphone penetration, while ultrasonic variants capture premium positioning through under-display compatibility and spoof resistance. The government agencies end user segment sustains above-average margins driven by FIPS certification requirements and long procurement cycles.
The US FDA and FCC regulate biometric data handling in healthcare and wireless-enabled devices respectively, with state-level privacy laws such as Illinois BIPA creating patchwork compliance obligations for fingerprint data storage. EMA frameworks indirectly shape healthcare authentication standards through medical device cybersecurity guidance. China's SAMR enforces national biometric data localization mandates that constrain cross-border template processing. Stakeholders must monitor divergence between regional privacy regimes and sensor certification standards when configuring global product roadmaps.
Market Dynamics
The Fingerprint Identification Chip Market is undergoing structural compression as under-display ultrasonic architectures displace capacitive dominance in premium smartphone tiers, forcing sensor vendors to reconfigure die geometries and packaging approaches.
Growth Catalysts
- EU AI Act compliance mandates:Biometric authentication systems in consumer devices must meet algorithmic transparency requirements, creating replacement demand for certified sensor modules across European handset deployments.
- China's consumer electronics manufacturing corridor:Shenzhen and Dongguan production clusters are integrating fingerprint sensors into mid-tier smartphones, payment terminals, and IoT access control devices at scale.
- Capacitive-to-ultrasonic technology migration:Under-display compatibility requirements in flagship smartphone designs are pulling ultrasonic sensor architectures into higher volume tiers previously served by capacitive alternatives.
Market Restraints
- Silicon wafer input cost volatility:CMOS wafer pricing fluctuations compress margins for sensor die fabrication, particularly affecting capacitive sensor producers with mature but thin cost curves.
- South Korea and Taiwan foundry concentration:Advanced BCD process nodes for mixed-signal biometric chips rely on a concentrated foundry base, creating supply vulnerability during capacity tightness.
- Facial recognition substitution threat:Structured light and time-of-flight face authentication systems in flagship devices are displacing fingerprint sensors in certain premium smartphone price bands.
Strategic Opportunities
- India's biometric payment infrastructure:The country's national identity-linked payment systems are creating demand for low-cost fingerprint sensors in point-of-sale terminals and micro-ATMs.
- Automotive cabin authentication:Driver identification for personalized seat, mirror, and infotainment settings represents an emerging application with distinct automotive qualification requirements.
- Healthcare device cybersecurity convergence:FDA medical device cybersecurity guidance is creating regulatory tailwind for biometric authentication in clinical workstations and medication dispensing systems.
Industry Challenges
- FIPS 201 certification timeline compression:Government agency procurement cycles require PIV-compliant sensor modules, extending product development schedules and validation costs for vendors targeting federal segments.
- Spoof detection algorithm integration complexity:Liveness detection requirements under ISO/IEC 30107-3 are forcing sensor vendors to acquire or partner for machine learning-based presentation attack detection capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingerprint Identification Chip Market |
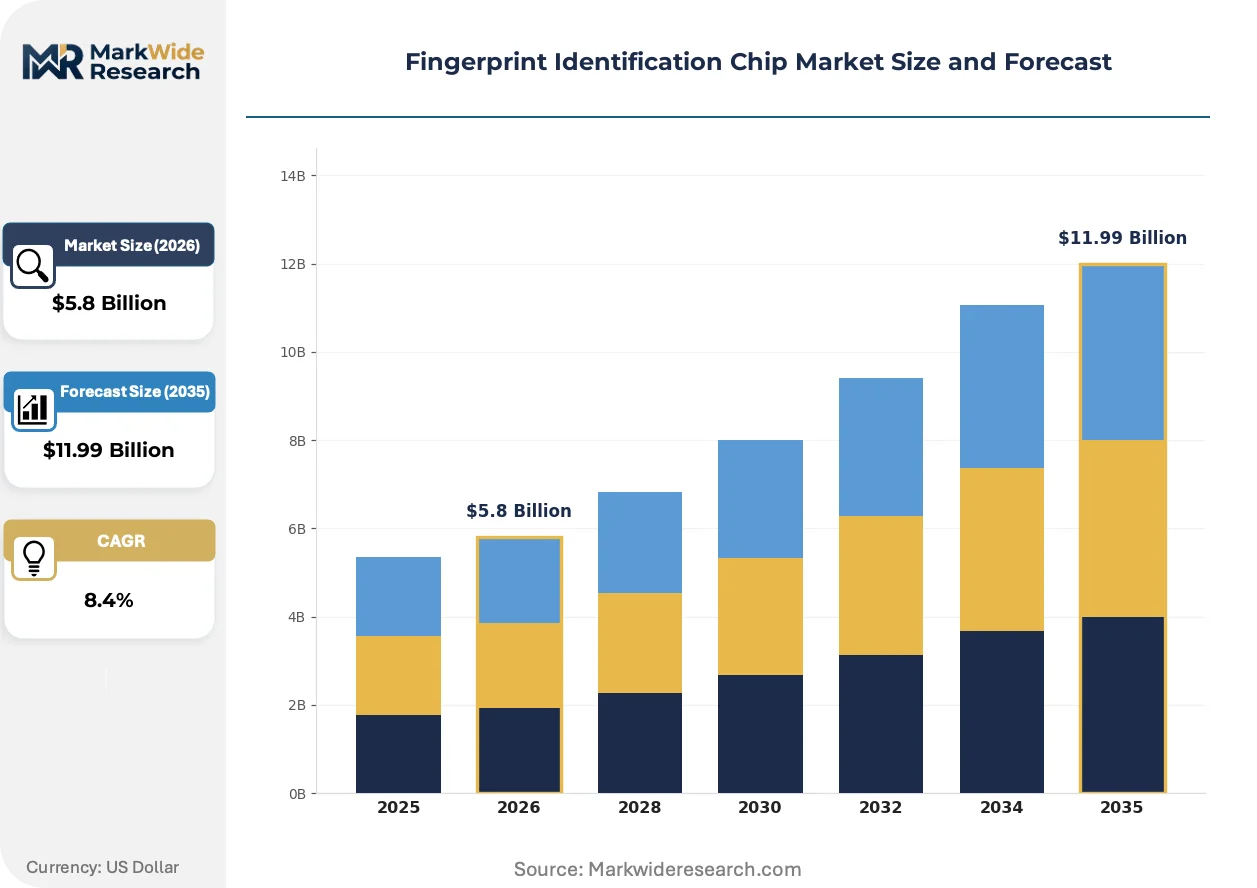
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Capacitive Sensors, Ultrasonic Sensors, Thermal Sensors End User: Consumer Electronics, BFSI, Healthcare, Government Agencies Installation: Integrated, Standalone, Embedded, External Technology: Basic Fingerprint Recognition, Multi-Factor Authentication, 3D Mapping, Anti-Spoofing |
| Companies Covered | Goodix Technology Co., Ltd., Fingerprint Cards AB, Synaptics Incorporated, Egis Technology Inc., Qualcomm Technologies, Inc., SecuGen Corporation, Nitgen Co., Ltd., NEXT Biometrics Group ASA, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingerprint Identification Chip Market Shifts & Advancements
Sensor architecture is fragmenting across multiple physical integration approaches as smartphone OEMs demand thinner modules, larger sensing areas, and compatibility with flexible display stacks.
Ultrasonic fingerprint sensing is modularizing across die-stacking configurations that separate the piezoelectric transducer array from the CMOS readout circuitry. Samsung Display and BOE Technology are qualifying these split-die modules for foldable phone implementations. The structural consequence is that sensor vendors can now mix-and-match transducer materials with standard CMOS nodes, compressing development cycles for custom form factors.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic coatings used in capacitive sensor surface treatments. The industrial consequence is that European-bound sensor modules must qualify alternative oleophobic materials without degrading moisture resistance or fingerprint acquisition speed. Automotive and industrial biometric applications are most affected, with suppliers accelerating coating validation timelines to maintain CE marking continuity.
Enterprise security buyers are consolidating vendor relationships around integrated biometric platform providers rather than discrete sensor suppliers. Channel disintermediation is visible most acutely in North American physical access control deployments, where systems integrators now demand firmware-to-cloud authentication stacks from single vendors. This compression is favoring sensor manufacturers with in-house template processing, encryption, and identity management software capabilities.
Fingerprint Identification Chip Market Segmentation
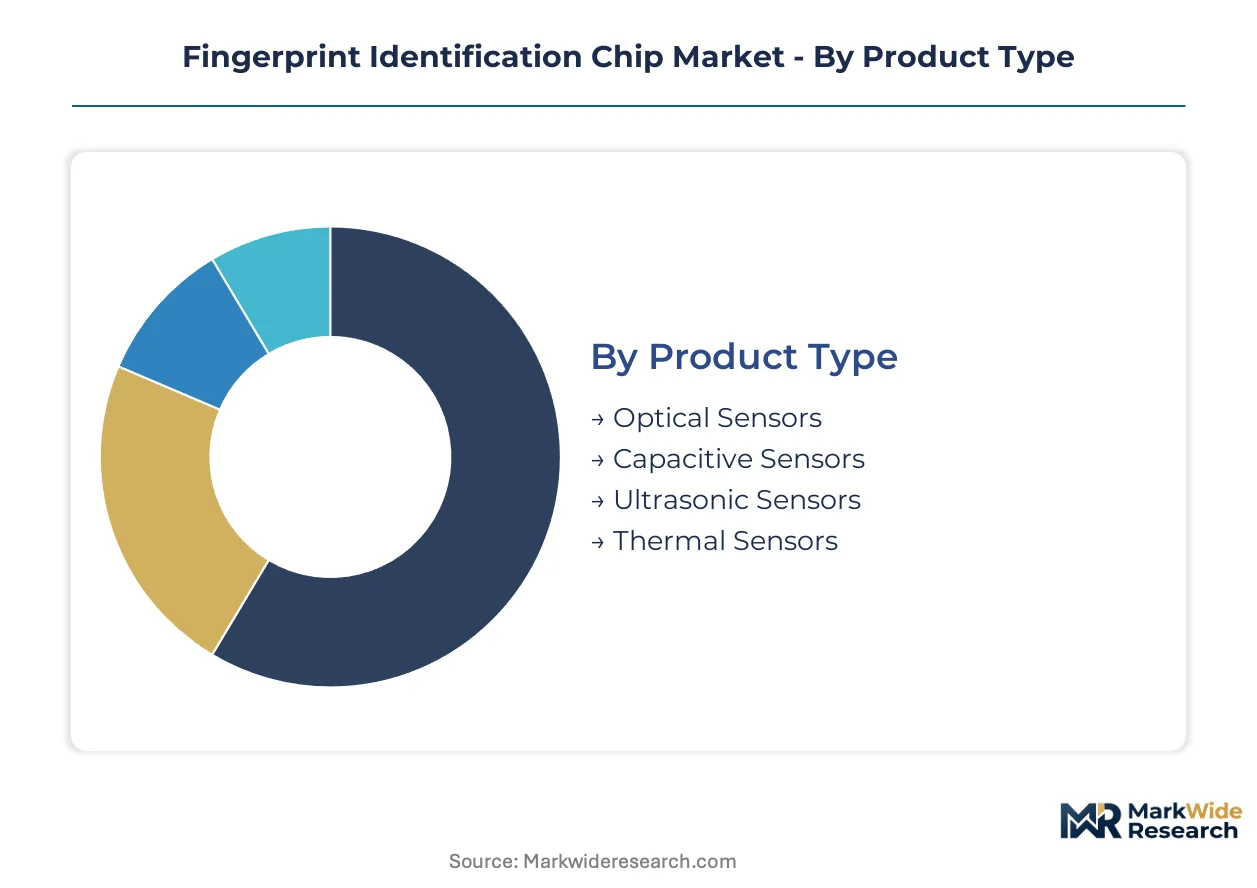
Segmentation in the Fingerprint Identification Chip Market reveals how certification burdens, die geometries, and integration complexity concentrate value capture across distinct technical tiers. Understanding these divides exposes where margin pressure and procurement leverage shift between sensor vendors and device OEMs.
Product Type:
FIPS 201 PIV compliance and ISO/IEC 30107-3 liveness certification requirements fall unevenly across sensor architectures, with government and financial segments driving divergence in validation investment.
- Capacitive Sensors:These CMOS-based arrays detect ridge patterns through electrical field distortion at pixel densities exceeding 500 dots per inch. Demand concentrates in China's Shenzhen and Dongguan manufacturing corridors for mid-tier smartphones and payment terminals, where mature cost curves support high-volume procurement despite REACH-driven coating reformulation costs.
- Ultrasonic Sensors:Piezoelectric transducers emit acoustic pulses to capture sub-dermal ridge structures, enabling under-display integration without optical transparency requirements. Samsung Display and BOE Technology are qualifying split-die modules for foldable implementations, pulling this architecture into premium smartphone tiers previously served by capacitive alternatives.
- Optical Sensors:Image-based acquisition using prisms or CMOS imagers dominates legacy access control and low-cost peripheral applications where thin form factors are secondary.
- Thermal Sensors:Temperature differential detection across fingerprint ridges serves niche industrial and outdoor deployments requiring moisture insensitivity.
Leading the category by volume: Capacitive Sensors. Expanding most quickly: Ultrasonic Sensors.
End User:
Margin structures diverge sharply across end-use segments, with procurement cycle length and certification stringency creating distinct pricing tiers.
- Consumer Electronics:Smartphone OEMs in Asia-Pacific drive the highest unit volumes, with Goodix Technology and Fingerprint Cards AB competing through die-size optimization and packaging integration. EU AI Act algorithmic transparency mandates are forcing sensor replacement cycles in European handset deployments.
- Government Agencies:FIPS 201 certification and PIV compliance requirements sustain above-average margins through extended validation timelines and limited vendor pools. US federal procurement concentrates around modules with integrated template encryption and liveness detection.
- BFSI:Banking and payment infrastructure demands ISO 9564 PIN management compatibility and PCI-DSS alignment for terminal-integrated sensors.
- Healthcare:FDA medical device cybersecurity guidance and HIPAA biometric data handling rules shape authentication requirements for clinical workstations and medication dispensing systems.
Highest margin concentration: Government Agencies. Steepest volume trajectory: Consumer Electronics.
Installation:
Physical integration approach determines supply chain configuration, with embedded and integrated formats commanding premium positioning through firmware-to-cloud stack requirements.
- Integrated:Sensors fused directly into SoC or display controller subsystems dominate flagship smartphone implementations, requiring deep vendor-OEM co-development relationships.
- Embedded:Discrete modules with standardized interfaces serve tier-two handset makers and IoT device manufacturers seeking reduced design complexity.
- Standalone:Self-contained units with onboard processing and storage address physical access control and legacy system retrofit applications.
- External:Peripheral-connected devices via USB or Bluetooth serve consumer aftermarket and enterprise mobility scenarios with minimal integration overhead.
Dominant by unit volume: Embedded. Gaining share fastest: Integrated.
Technology:
Anti-spoofing and multi-factor capabilities are concentrating R&D investment as presentation attack detection becomes a procurement discriminator across regulated segments.
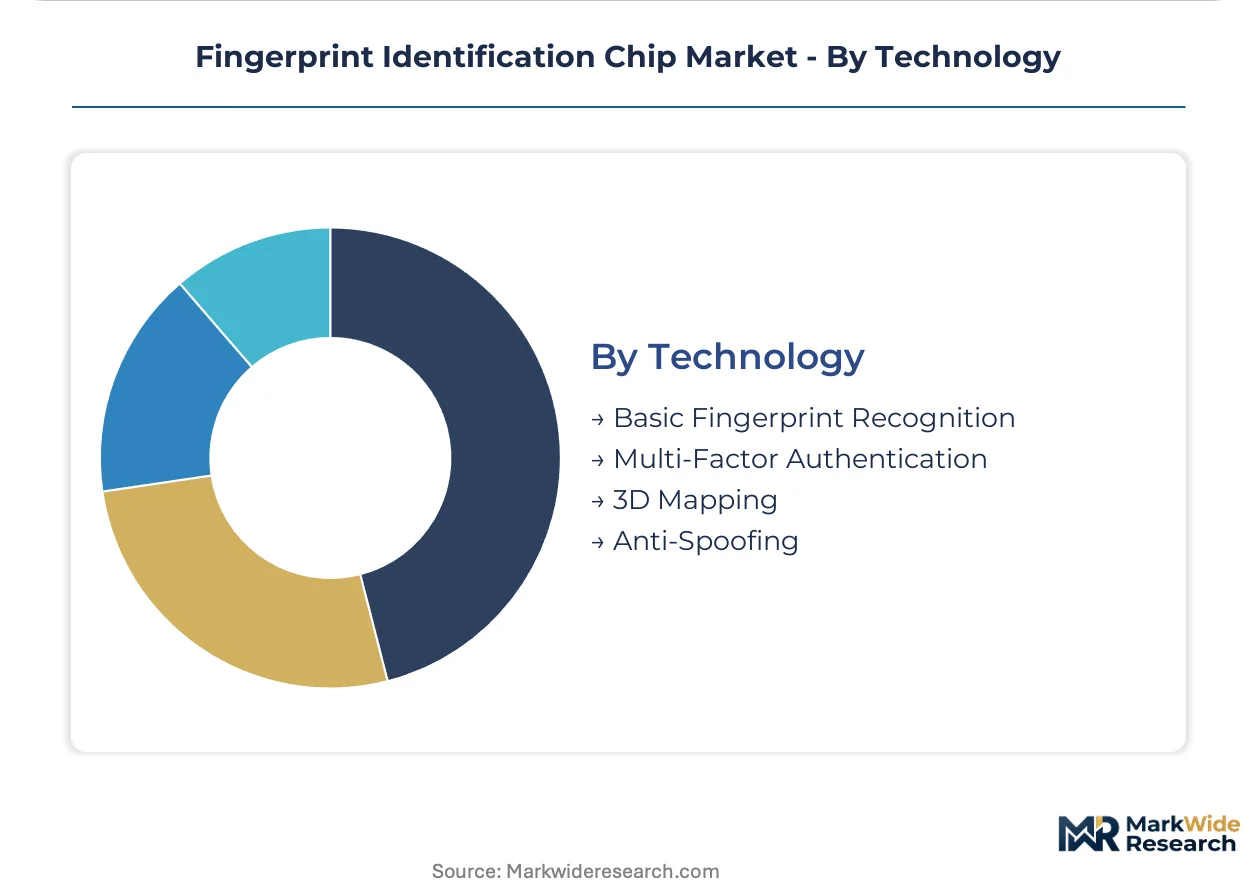
- Anti-Spoofing:Machine learning-based liveness detection algorithms integrated at the sensor-firmware layer address ISO/IEC 30107-3 requirements. Spoof detection complexity is forcing partnership and acquisition activity among sensor vendors seeking in-house PAD capabilities.
- Multi-Factor Authentication:Fingerprint templates combined with PIN, token, or behavioral biometrics serve high-assurance government and financial applications where single-factor risk is unacceptable.
- 3D Mapping:Ultrasonic and structured light depth capture enables sub-dermal ridge reconstruction for enhanced spoof resistance in premium device tiers.
- Basic Fingerprint Recognition:Template matching without supplemental authentication persists in cost-constrained consumer and low-security access applications.
Widest deployment: Basic Fingerprint Recognition. Climbing fastest: Anti-Spoofing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors semiconductor packaging and sensor module assembly for consumer electronics, with Dongguan corridors feeding component flows into smartphone OEM supply chains across Asia.
United States
Federal procurement sustains demand for FIPS 201-certified sensor modules across government agencies and defense contractors. FDA cybersecurity guidance for medical devices shapes authentication requirements in healthcare IT infrastructure. Austin and Boston corridors concentrate R&D activity for biometric algorithm development and liveness detection systems.
China
Shenzhen and Dongguan manufacturing clusters integrate capacitive sensors into mid-tier smartphones and payment terminals at scale. SAMR enforces national biometric data localization mandates that constrain cross-border template processing. Shanghai and Beijing house design centers for under-display ultrasonic architectures targeting domestic handset OEMs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg pilot fingerprint authentication for driver identification and cabin personalization systems. EU AI Act algorithmic transparency requirements tighten compliance burdens for biometric systems deployed across European markets. Munich and Stuttgart engineering centers focus on automotive qualification standards for sensor durability.
South Korea
Seoul-based display manufacturers qualify split-die ultrasonic modules for foldable smartphone implementations. MFDS medical device frameworks indirectly shape healthcare authentication standards through cybersecurity guidance. Suwon and Pyeongtaek corridors concentrate advanced BCD foundry capacity for mixed-signal biometric chip fabrication.
India
National identity-linked payment systems create demand for low-cost fingerprint sensors in point-of-sale terminals and micro-ATMs. RBI guidelines on biometric data handling in financial infrastructure shape procurement specifications for banking deployments. Bengaluru and Hyderabad clusters concentrate systems integration capability for Aadhaar-authenticated payment networks.
Fingerprint Identification Chip Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration depth, with government-grade FIPS compliance separating high-assurance vendors from consumer-volume suppliers. The vendor base organizes into three strategic archetypes: capacitive specialists serving high-volume handset markets, ultrasonic innovators targeting under-display premium tiers, and platform integrators bundling firmware-to-cloud authentication stacks. M&A activity concentrates around liveness detection algorithm acquisition, while capacity partnerships with Taiwan and South Korea foundries address BCD process node access.
Within the premium-tier vector, Qualcomm Technologies, Inc. and Synaptics Incorporated exemplify sensor-architecture convergence with display and touch controller ecosystems. Among Asia-Pacific module integrators, Goodix Technology Co., Ltd. occupies a position representing high-volume capacitive deployment across China's consumer electronics manufacturing corridor.
| Leading Market Players |
|---|
| Goodix Technology Co., Ltd. |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| Egis Technology Inc. |
| Qualcomm Technologies, Inc. |
| SecuGen Corporation |
| Nitgen Co., Ltd. |
| NEXT Biometrics Group ASA |
| HID Global Corporation |
| Others |
Supply & Pricing Matrix
Ultrasonic sensor die-stacking architectures are fragmenting production economics across CMOS foundry and piezoelectric transducer supply bases, compressing margins for capacitive specialists while concentrating premium pricing power among vendors with split-die packaging capabilities.
Pricing Analysis
Value-based pricing anchored to FIPS 201 certification outcomes separates government-grade modules from consumer-volume alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO/IEC 30107-3 liveness validation commanding substantial premiums. Cost compression in capacitive tiers is intensifying because REACH-driven coating reformulation adds non-recurring engineering burdens. Smartphone OEMs in China's manufacturing corridor exhibit highest price sensitivity, while federal procurement cycles tolerate extended validation costs for PIV-compliant architectures.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Dongguan consolidate sensor module assembly for Asia-Pacific handset OEMs, feeding component flows through hub-and-spoke patterns into tier-one and tier-two manufacturer supply chains. Taiwan and South Korea foundries anchor advanced BCD process capacity for mixed-signal biometric chips, drawing from silicon wafer inputs and specialized piezoelectric materials. Single-source vulnerability concentrates in South Korean display-integrated ultrasonic packaging. Distribution runs through direct OEM partnerships for integrated formats, while embedded and standalone modules flow through electronics distributors serving industrial and access control channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fingerprint identification chip market sits in a capacitive-to-ultrasonic technology transition, with under-display architectures displacing legacy surface-mounted sensors across premium smartphone tiers and forcing vendor repositioning.
For Market Incumbents: Deepen backward integration into piezoelectric transducer materials and CMOS foundry partnerships to secure split-die packaging capacity before capacity tightness intensifies. Acquire machine learning-based liveness detection capabilities to meet ISO/IEC 30107-3 requirements without partnership dependency. Defend government segment positioning through accelerated FIPS 201 PIV certification timelines. For New Entrants and Emerging Players: Automotive cabin authentication systems represent a technology-first wedge into an underpenetrated segment with distinct qualification requirements separate from smartphone procurement cycles. India's Aadhaar-linked payment infrastructure offers white-space access for low-cost capacitive modules in point-of-sale terminals. Pursue systems integrator relationships rather than direct OEM engagement to bypass entrenched vendor consolidation in enterprise physical access control. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integrators bundling firmware-to-cloud authentication stacks, as channel disintermediation favors vendors with in-house template processing and encryption capabilities. Long-term viability hinges on liveness detection algorithm ownership and automotive qualification expertise. Watch for inflection signals in foldable smartphone volume ramp rates, as split-die ultrasonic module adoption curves will reshape competitive tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Liveness Detection Specialist | Machine learning-based PAD capabilities address ISO/IEC 30107-3 mandates without partnership friction. |
| Automotive Qualification Investment | AEC-Q100 compliance opens driver identification applications in Bavaria and Stuttgart OEM supply chains. |
| Split-Die Packaging Partnership | BOE Technology and Samsung Display qualification paths enable foldable phone sensor integration. |
| EU AI Act Certification Pre-Positioning | Algorithmic transparency documentation accelerates European handset replacement cycles. |
| India Distribution Channel Expansion | RBI-compliant biometric terminal networks in Bengaluru and Hyderabad clusters capture Aadhaar-authenticated payment infrastructure growth. |
Research Methodology
Independent corroboration across sensor vendor engineering directors, smartphone OEM procurement leads, and government agency biometric program managers underwrites the qualitative findings in this study. Primary interviews with foundry operations specialists, automotive Tier 1 supplier quality engineers, and enterprise systems integrators were cross-referenced against secondary validation from SEC filings, customs trade data, and FIPS 201 certification databases. Bottom-up unit shipment estimates by sensor architecture and end-use segment were reconciled with top-down market value reconstructions.
Comparable-period anchoring to historical capacitive sensor penetration curves and ultrasonic adoption trajectories in flagship devices shaped the projection horizon. The analytical framework modeled volume and value across product type, end user, installation format, and technology tier dimensions, with regional regulatory cluster effects layered as adoption modifiers. CAGRs were derived from segment-specific growth rate distributions weighted by procurement cycle visibility and certification timeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry capacity allocation shifts or accelerated facial recognition substitution in premium smartphones. Periodic stress-testing of base assumptions is recommended, particularly around EU AI Act implementation timelines and China's SAMR data localization enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market