

Superconducting Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Superconducting Detector Market Insights
Project finance for dilution refrigerators and cryogenic infrastructure is fragmenting competitive access across the superconducting detector value chain. Single Quantum leverages captive European supply chains for superconducting nanowire fabrication. ID Quantique sustains R&D intensity across Geneva-based quantum cryptography labs. Scontel anchors volume production of transition edge sensors for astrophysics instruments.
Superconducting detectors are cryogenic sensors that exploit zero-resistance states to resolve single-photon events with timing precision below 100 picoseconds and quantum efficiency exceeding 90% at near-infrared wavelengths, serving applications where classical photodetectors fail due to dark count limitations. Transition edge sensors dominate medical imaging and x-ray spectroscopy where energy resolution drives purchasing decisions, while superconducting nanowire single photon detectors capture the fastest expansion in quantum computing interconnects. Low temperature cryogenics remains the largest technology category by installed base, though magnesium diboride architectures are gaining share in systems targeting operational temperatures above 20 Kelvin.
ISO standards for cryogenic vessel safety and IEC frameworks for superconducting device qualification shape product certification pathways in Europe and Asia-Pacific markets. The US FDA regulates medical imaging subsystems incorporating superconducting detectors through device-specific premarket pathways, while NIST traceability requirements influence procurement specifications for defense laboratories. Stakeholders must monitor how emerging export controls on cryogenic technologies redirect supply chain investments toward domestic niobium refining and dilution refrigerator manufacturing capabilities.
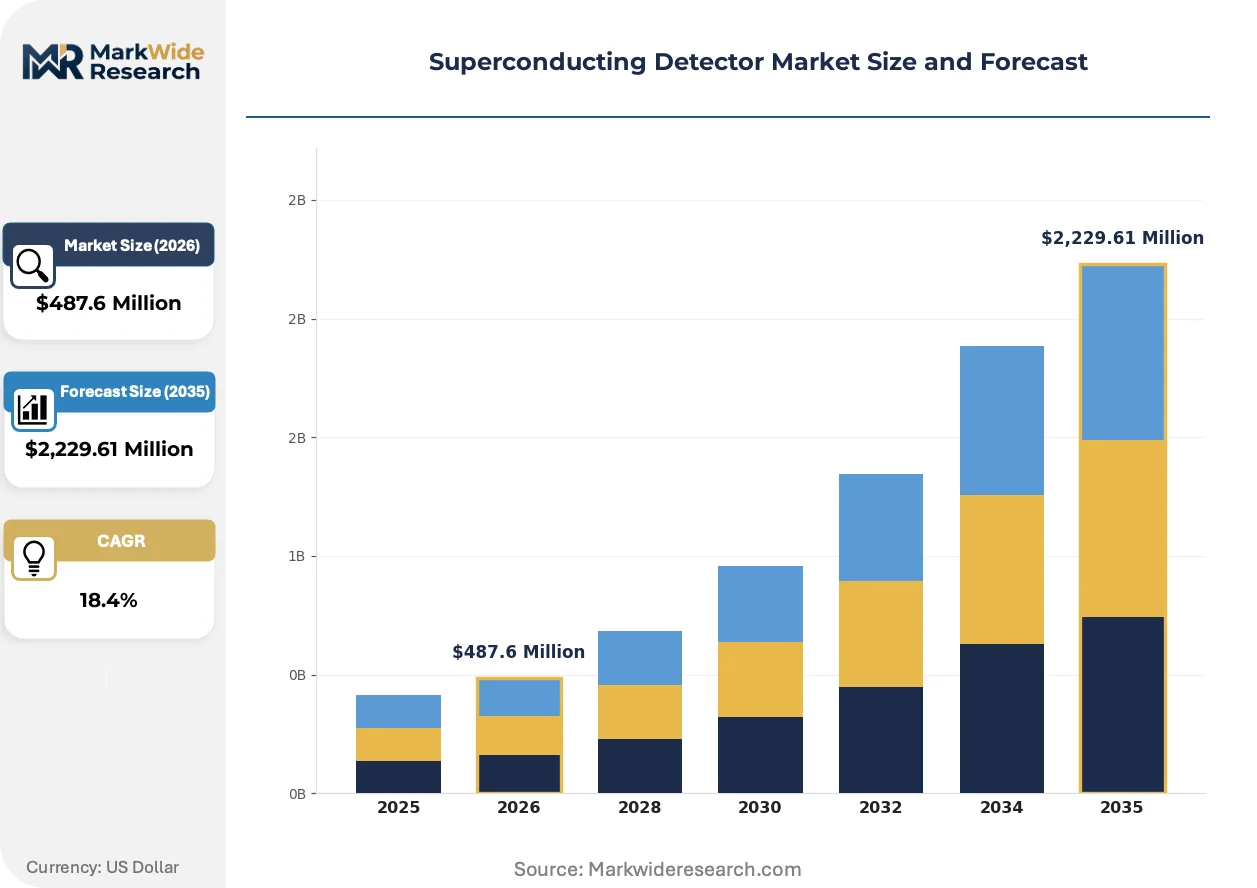
Market Dynamics
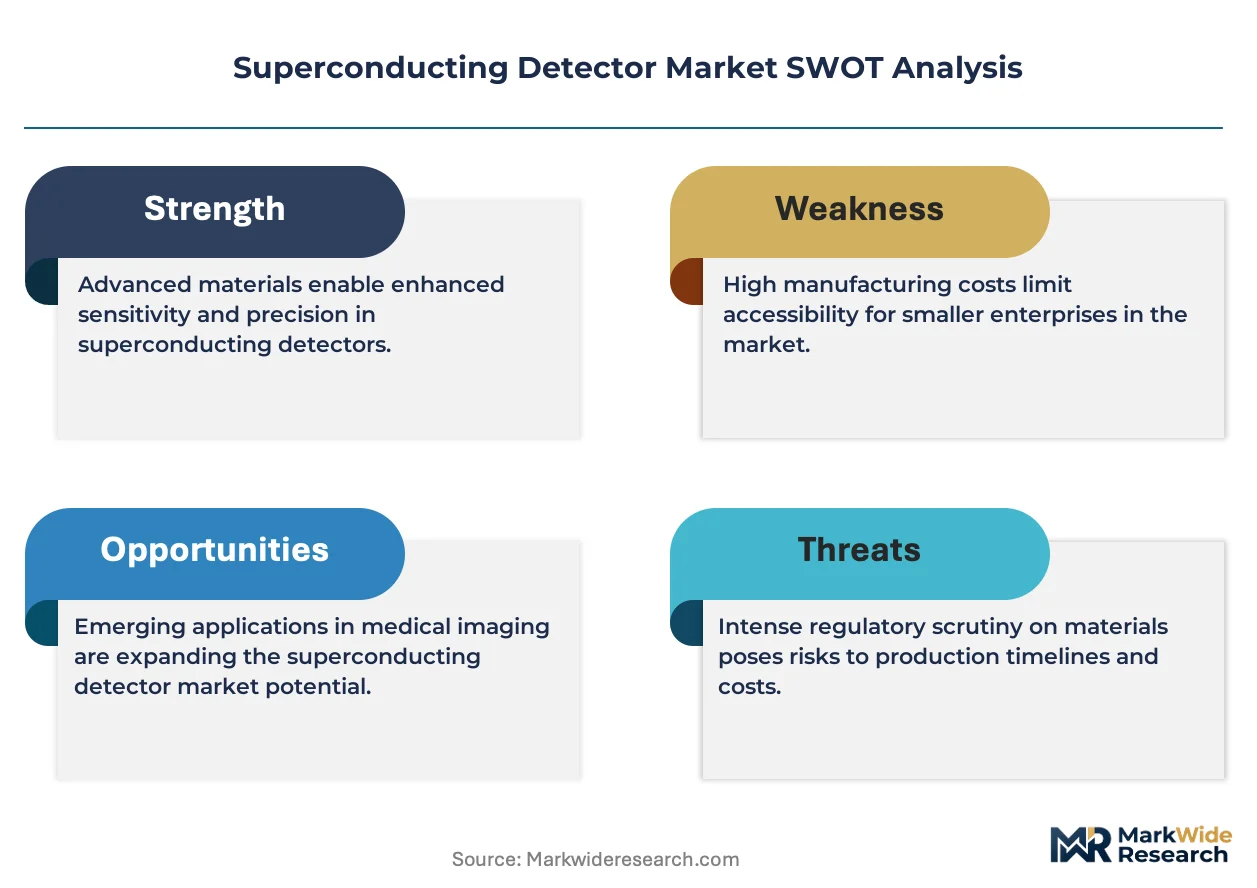
High-purity niobium supply concentration and cryogenic cooling infrastructure bottlenecks are compressing competitive access across the superconducting detector value chain, forcing buyers into long-term offtake agreements with limited qualified suppliers.
Growth Catalysts
- Quantum computing interconnect demand:Scientific research institutes are accelerating procurement timelines for single-photon detection systems to support fault-tolerant quantum processor architectures.
- ISO cryogenic vessel standards:Harmonized safety certification frameworks across Europe and Asia-Pacific are reducing cross-border deployment friction for dilution refrigerator-integrated systems.
- Magnesium diboride material advances:Operational temperature thresholds above 20 Kelvin are expanding addressable applications in defense laboratory environments with constrained liquid helium access.
Market Restraints
- Liquid helium cost volatility:Cryogenic cooling input prices fluctuate with global helium refining capacity concentrated in Qatar and the United States.
- Niobium supply geographic concentration:Over 80% of high-purity superconducting-grade niobium originates from Brazilian mining operations and Russian refining complexes.
- FDA premarket pathway duration:Medical imaging subsystem approvals require 18-36 month device-specific review cycles that delay revenue recognition.
Strategic Opportunities
- German astrophysics observatory anchor contracts:Long-term instrument procurement from Max Planck Institute facilities creates predictable demand baselines for transition edge sensor manufacturers.
- Japan METI quantum technology roadmap:National funding mandates for domestic dilution refrigerator production are redirecting supply chain investments toward captive cryogenic infrastructure.
- X-ray spectroscopy-CT convergence:Medical imaging OEMs are integrating energy-resolving detectors into next-generation diagnostic platforms requiring superconducting sensor architectures.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized microwave engineering and sub-Kelvin thermometry expertise concentrates within national laboratory systems and select university programs.
- NIST traceability certification timelines:Defense laboratory procurement specifications require extended metrological validation cycles that compress commercial deployment windows.
- Legacy semiconductor photodetector integration:System architects face firmware and signal processing incompatibility when retrofitting superconducting sensors into existing instrument platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconducting Detector Market Trends and Innovations
Materials science breakthroughs and regulatory harmonization efforts are compressing technology lifecycles across superconducting detector architectures. Three developments are restructuring competitive positioning.
Superconducting nanowire single-photon detectors with niobium nitride active layers are rendering obsolete germanium avalanche photodiodes in quantum key distribution systems. Financial services and defense communication networks in Switzerland and Singapore are deploying these sensors for metropolitan-scale quantum cryptography backbones. The structural consequence is a demand bifurcation between scientific research grade and telecom-hardened industrial variants.
The EU F-Gas Regulation phase-down mandates are accelerating substitution toward closed-cycle cryocooler architectures that eliminate helium venting. European superconducting detector OEMs are redesigning dilution refrigerator interfaces to accommodate pulse-tube pre-cooling stages. Medical imaging and spectroscopy instrument segments face the steepest compliance cost adjustments through 2030.
Buyers are consolidating vendor relationships around integrated cryogenic system suppliers rather than discrete detector component sources. Japanese and German astrophysics consortia now specify turnkey dilution refrigerator-detector packages with unified warranty terms. This pattern is most pronounced in observatory procurement where operational risk transfer outweighs component-level cost optimization.
Superconducting Detector Market Segmentation
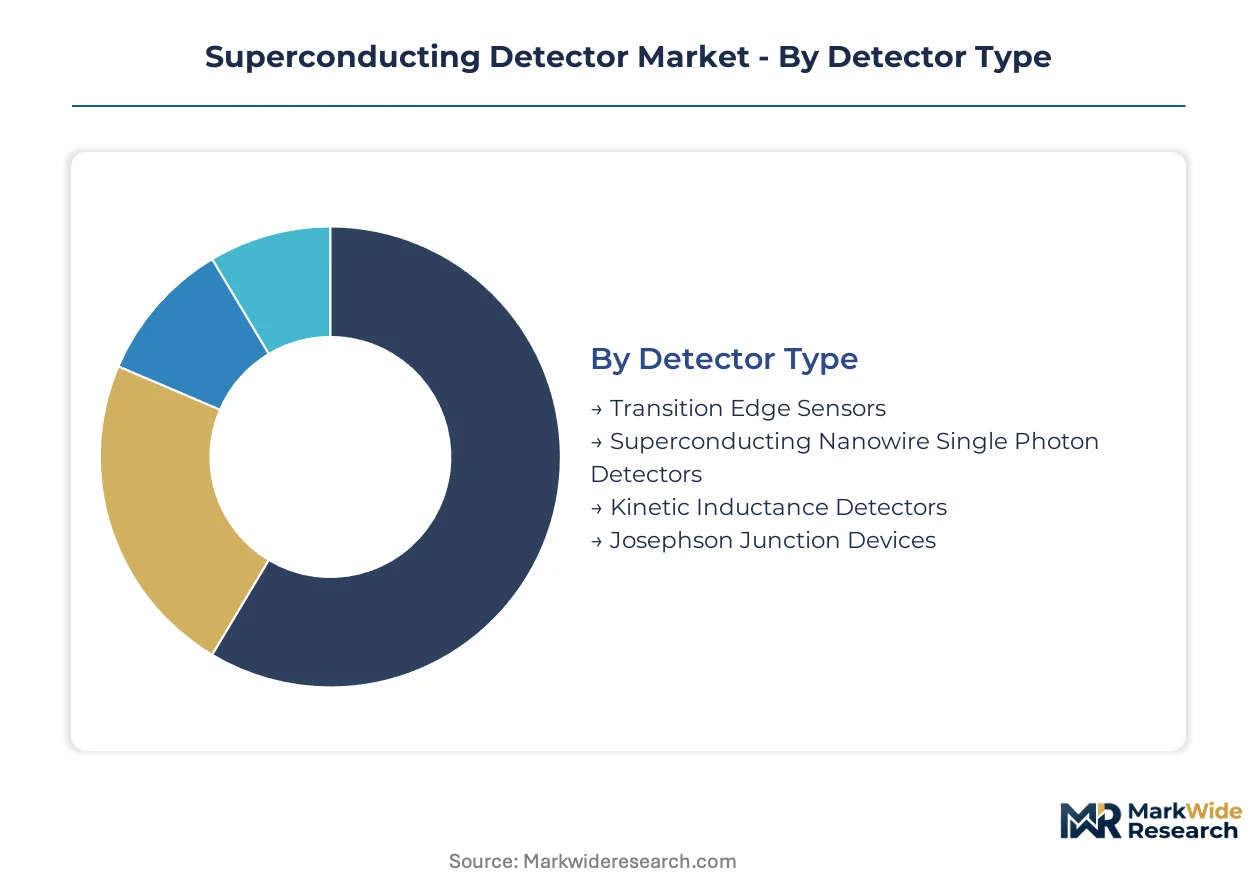
Superconducting detector procurement varies sharply by technical specification and cooling infrastructure requirements. Buyers segment purchases around detector physics, material platform, and end-use environment rather than commoditized performance metrics.
Detector Type:
Cost tier stratification separates precision spectroscopy instruments from high-speed photon counting systems.
- Transition Edge Sensors:These devices operate at the superconducting-to-normal phase transition, delivering energy resolution below 10 eV for x-ray spectroscopy. Max Planck Institute astrophysics facilities anchor long-term procurement contracts for focal plane arrays. FDA premarket pathways for medical imaging subsystems extend sales cycles to 24-36 months.
- Superconducting Nanowire Single Photon Detectors:Niobium nitride nanowires achieve timing jitter below 50 picoseconds with detection efficiency exceeding 90% at 1550 nm wavelengths. Quantum computing interconnect demand from IBM and Google processor development programs is accelerating volume procurement timelines. Cryogenic packaging complexity limits supplier qualification to fewer than ten global vendors.
- Kinetic Inductance Detectors:Microwave resonator arrays enable multiplexed readout for large-format focal planes.
- Josephson Junction Devices:Quantum interference effects support ultra-sensitive magnetometry for brain imaging applications.
Transition Edge Sensors command the established base. The steepest expansion runs through Superconducting Nanowire Single Photon Detectors.
Technology:
Application temperature thresholds determine material selection and cooling system architecture.
- Low Temperature Cryogenics:Dilution refrigerator systems operating below 100 millikelvin enable the highest performance superconducting detectors. United States defense laboratories specify these platforms for quantum sensing applications where thermal noise suppression is critical. Liquid helium supply concentration in Qatar and the United States creates input cost volatility that compresses procurement budgets.
- High Purity Niobium:Residual resistance ratios above 300 characterize superconducting-grade material for cavity and thin-film applications. Brazilian mining operations and Russian refining complexes supply over 80% of global high-purity niobium, forcing buyers into long-term offtake agreements. Thin-film deposition expertise concentrates within national laboratory systems and select European suppliers.
- Yttrium Barium Copper Oxide:High-temperature superconducting properties above 77 Kelvin reduce cooling infrastructure requirements.
- Magnesium Diboride:Operational thresholds above 20 Kelvin expand addressable applications in constrained helium environments.
Low Temperature Cryogenics retains the dominant installed position. Magnesium Diboride is climbing the fastest as defense laboratories seek to reduce helium dependency.
Application:
Customer type and funding source create divergent procurement patterns across use cases.
- Quantum Computing:Fault-tolerant processor architectures require single-photon detection for error correction and interconnect synchronization. Scientific research institutes in Japan, Germany, and the United States are accelerating capital expenditure timelines for cryogenic measurement systems. METI quantum technology roadmap funding mandates are redirecting supply chain investments toward domestic Japanese dilution refrigerator production.
- Astrophysics Instruments:Energy-resolving focal planes for x-ray observatories demand large-format Transition Edge Sensor arrays. European Space Agency mission planning creates predictable multi-year demand baselines for qualified suppliers. ISO cryogenic vessel safety standards harmonize cross-border deployment requirements.
- Medical Imaging:Energy-resolving CT detectors require superconducting sensor architectures for material decomposition.
- Particle Physics Research:CERN and Fermilab facilities anchor procurement for ultra-low background detection systems.
Astrophysics Instruments command the established base. Quantum Computing is gaining share fastest as commercial processor development accelerates.
End User:
Volume concentration and technical sophistication separate institutional buyer categories.
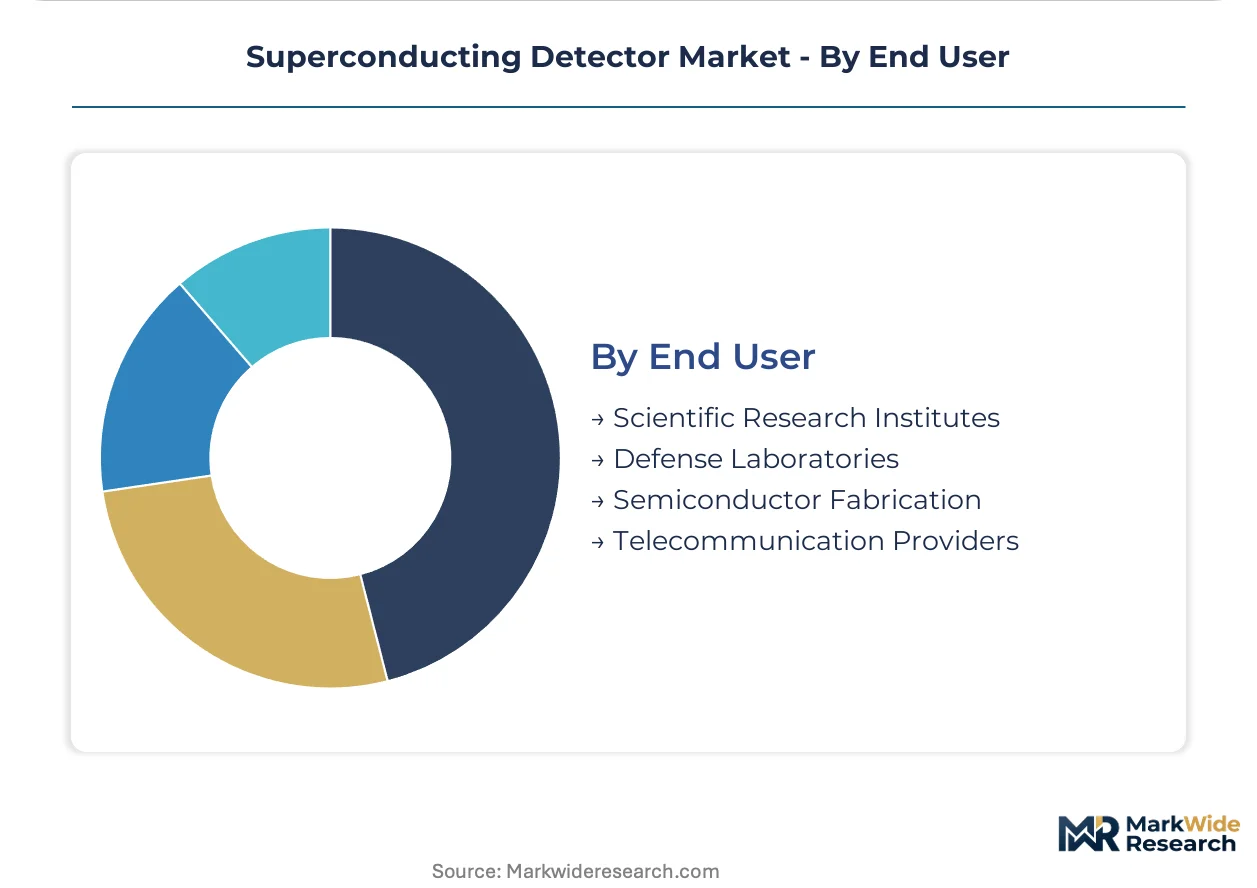
- Scientific Research Institutes:University and national laboratory systems drive fundamental detector physics development and prototype procurement. NIST traceability requirements for defense-related contracts extend metrological validation timelines. Cryogenic engineering talent scarcity concentrates specialized expertise within select programs.
- Defense Laboratories:Classified quantum sensing and secure communication programs specify hardened cryogenic systems with domestic supply chain requirements. United States export controls on dilution refrigerator technologies are redirecting investments toward captive niobium refining capabilities. Procurement specifications prioritize operational risk transfer over component-level cost optimization.
- Semiconductor Fabrication:Metrology and inspection applications require compact cryogenic packaging for fab integration.
- Telecommunication Providers:Metropolitan quantum key distribution backbones in Switzerland and Singapore deploy telecom-hardened detector variants.
Scientific Research Institutes command the established base. Defense Laboratories represent the steepest expansion trajectory as national security funding priorities shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export controls on cryogenic technologies are redirecting supply chain investments toward domestic niobium refining and dilution refrigerator manufacturing capabilities, compressing competitive access for importers while creating captive production clusters in select economies.
United States
NIST traceability requirements and defense laboratory procurement specifications anchor demand for ultra-low temperature systems. The FDA regulates medical imaging subsystems through device-specific premarket pathways extending 18-36 months. Greater Boston and the San Francisco Bay Area concentrate quantum computing research programs driving single-photon detection procurement.
Germany
Max Planck Institute astrophysics facilities and European Space Agency mission planning create predictable multi-year demand baselines for focal plane arrays. The EU F-Gas Regulation phase-down mandates accelerate substitution toward closed-cycle cryocooler architectures. Munich and Garching anchor the transition edge sensor supply chain with integrated dilution refrigerator manufacturing.
Japan
METI quantum technology roadmap funding mandates redirect supply chain investments toward domestic dilution refrigerator production. JIS standards govern superconducting device qualification pathways. Tokyo and Tsukuba concentrate cryogenic engineering talent within national laboratory systems and select university programs.
Switzerland
Geneva-based quantum cryptography labs sustain R&D intensity for metropolitan-scale quantum key distribution backbones. Swissmedic and federal procurement frameworks shape medical and defense application certification. The Lake Geneva region anchors superconducting nanowire fabrication expertise for telecom-hardened detector variants.
China
National superconducting materials programs and domestic quantum processor development accelerate capital expenditure timelines for cryogenic measurement systems. GB standards and MIIT directives govern superconducting device manufacturing certification. Hefei and Shanghai concentrate niobium thin-film deposition expertise within national laboratory systems.
Superconducting Detector Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure fragmented across cryogenic packaging, thin-film fabrication, and readout electronics domains. The vendor base separates into three strategic archetypes: captive research-laboratory spinouts with government anchor contracts, industrial photonics conglomerates leveraging semiconductor manufacturing scale, and pure-play cryogenic specialists controlling niche niobium nitride deposition expertise. Competitive moves concentrate on backward integration into high-purity niobium refining and strategic partnerships for unified dilution refrigerator-detector warranty terms.
Among European pure-play specialists, Single Quantum and ID Quantique exemplify the research-laboratory spinout archetype with Geneva-based and Delft-anchored operations respectively. Scontel occupies a position within the cryogenic packaging tier, representing the Russian-German fabrication cluster for transition edge sensor volume production. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Single Quantum |
| ID Quantique |
| Scontel |
| Quantum Opus |
| Photon Spot |
| Thorlabs |
| AUREA Technology |
| Photec |
| Hamamatsu Photonics |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European dilution refrigerator manufacturing is compressing supplier margins while amplifying pricing power for qualified vendors serving defense laboratories and astrophysics consortia. Buyers face extended lead times that force acceptance of premium pricing tiers for cryogenic-integrated detector packages.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for high-purity niobium and dilution refrigerator systems. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable defense specifications from research-grade instruments and educational prototypes. Cost compression in standard-tier medical imaging subsystems is intensifying because FDA premarket pathway durations extend sales cycles without corresponding price premiums. Academic research institutes exhibit highest price sensitivity due to grant-funded procurement constraints, while classified defense programs demonstrate lowest sensitivity given operational risk transfer priorities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for cryogenic component sourcing. High-purity niobium concentrates in Brazilian mining operations and Russian refining complexes, with thin-film deposition expertise clustering in German and Japanese national laboratory systems. The supply chain draws from liquid helium refining capacity in Qatar and the United States, creating single-source vulnerability for sub-Kelvin cooling infrastructure. Distribution runs through integrated cryogenic system suppliers rather than discrete component vendors, with turnkey warranty packages displacing piecemeal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Japanese and German astrophysics consortia specifying unified dilution refrigerator-detector packages, fragmenting competitive access for component-only suppliers.
For Market Incumbents: Build captive niobium nitride deposition expertise as a technical moat against emerging thin-film specialists. Secure long-term offtake agreements with Brazilian mining operations to hedge against export control expansion. Anchor volume production contracts with Max Planck Institute facilities to create predictable demand baselines that deter challenger entry. For New Entrants and Emerging Players: Southeast Asian quantum computing research clusters present underpenetration relative to installed cryogenic infrastructure capacity. Target white-space opportunities in magnesium diboride detector architectures for defense laboratories with constrained helium access. Pursue partnership-based go-to-market positioning with established dilution refrigerator OEMs to bypass standalone qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across superconducting nanowire fabrication as cleanroom requirements tighten. Long-term viability favors platform integrators controlling captive cryogenic packaging capabilities over pure-play component suppliers. Monitor METI funding disbursement velocity as an inflection signal for Japanese domestic supply chain redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Niobium Refining | Captive supply from Brazilian mining operations mitigates tariff exposure and export control risk. |
| Long-term Supply Agreement with Astrophysics Consortia | Max Planck Institute anchor contracts create predictable demand baselines for transition edge sensor volume production. |
| Strategic Partnership for Unified Warranty Terms | Turnkey dilution refrigerator-detector packages align with Japanese and German observatory procurement specifications. |
| Acquisition of Specialist Cryogenic Packaging Firm | Sub-Kelvin thermometry expertise concentrates within national laboratory spinouts with limited external availability. |
| Geographic Expansion into Domestic Japanese Production | METI quantum technology roadmap funding mandates redirect supply chain investments toward captive infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from cryogenic engineering directors, defense laboratory procurement officers, astrophysics instrument scientists, niobium thin-film deposition specialists, and medical imaging OEM product managers and refined through secondary validation. Sources included ISO cryogenic vessel certification records, IEC superconducting device qualification frameworks, SEC filings from listed photonics conglomerates, customs data on high-purity niobium trade flows, and ESA mission planning documents. Bottom-up volume estimates from detector unit shipments were triangulated against top-down cryogenic infrastructure investment disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmented forecasting incorporating detector physics type, operational temperature threshold, end-use environment, and regional regulatory cluster. CAGRs were derived from growth rate convergence modeling applied to procurement timelines from quantum computing research programs and astrophysics mission planning cycles. Forecast inputs included METI funding mandate disbursement schedules, FDA premarket pathway duration distributions, and liquid helium spot price volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese superconducting materials programs would shift outcomes through accelerated domestic niobium refining investment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.