
 Amorphous Polyethylene Terephthalate (APET) Market | 2026-2036
Amorphous Polyethylene Terephthalate (APET) Market Size, Share, and Industry Trends Forecast 2026-2036
Amorphous Polyethylene Terephthalate (APET) Market Outlook
Asian PET resin producers is consolidating capacity around integrated PTA-PET complexes to secure feedstock economics. Indorama Ventures leverages its Thai and Indian manufacturing bases to anchor regional supply for APET sheet exports. Reliance Industries sustains cost leadership through backward integration into purified terephthalic acid at its Jamnagar complex. Alpek S.A.B. de C.V. competes across the Americas with dedicated APET lines serving Mexican and U.S. thermoformers.
Amorphous polyethylene terephthalate is a non-crystalline copolyester produced by rapid quenching of molten PET, yielding optical clarity above 85 percent light transmission and glass transition temperatures near 75 degrees Celsius for thermoforming precision. APET Films leads product type demand in electronics display and pharmaceutical blister lidding where barrier clarity commands premium positioning. APET Sheets occupies the fastest-growing structural slot as European fresh-protein trays convert from polystyrene under extended producer responsibility mandates. Rigid form dominates packaging type volume in clamshells and containers where dimensional stability replaces PVC in retail produce.
FDA food contact regulations and EPA recycled content guidelines in the United States shape virgin-to-recycled blend ratios and migration testing protocols for APET food packaging. EFSA and EU Green Deal circular economy action plans in Europe enforce recycled content thresholds and restrict certain additive packages in food-contact applications. Stakeholders must monitor evolving recyclability certifications and sortation infrastructure investments that will determine which APET grades retain market access across major economies.
Market Dynamics
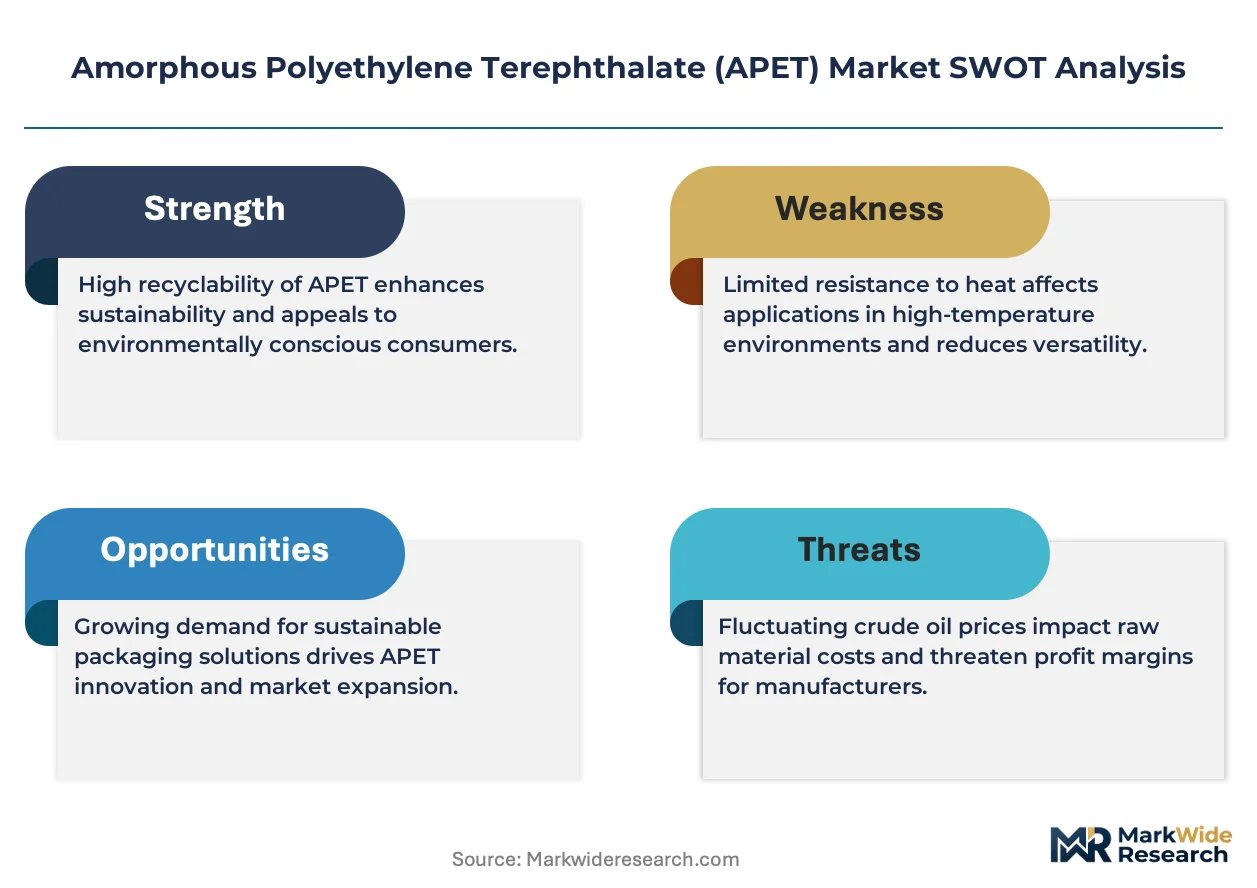
Substitution pressure from EU Green Deal mandates is restructuring APET demand as thermoformers abandon PVC and polystyrene for recyclable copolyesters in fresh-food packaging.
Growth Catalysts
- REACH chemical restrictions:European bans on phthalate plasticizers in PVC food contact are redirecting tray production toward APET sheet with virgin-quality clarity.
- Fresh-protein packaging:Central European retail chains are converting deli and meat tray formats to APET under extended producer responsibility frameworks.
- Optical-grade film demand:Pharmaceutical blister lidding specifications above 85 percent light transmission are pulling premium APET resin into medical packaging supply chains.
Market Restraints
- PTA feedstock volatility:Purified terephthalic acid price swings from naphtha-cracker economics compress APET sheet margins for independent thermoformers.
- Thai-Indian supply concentration:Integrated PTA-PET complexes in Southeast Asia create geographic single-point vulnerability for European sheet importers.
- Glass transition ceiling:APET's 75°C thermal limit blocks hot-fill applications where crystallized PET or polypropylene retain structural integrity.
Strategic Opportunities
- German thermoforming clusters:Munich and Hamburg production hubs serve as launch points for recycled-content APET penetration into Benelux and Scandinavian retail networks.
- EU Green Deal circular economy mandates:Recycled content thresholds for food-contact plastics create certified-rPET-APET blend premiums for early compliance.
- Digital print compatibility:APET sheet surface energy characteristics enable direct-to-tray inkjet decoration, bypassing adhesive label applications in premium produce.
Industry Challenges
- EFSA migration testing timelines:Novel recycled-content APET grades face 18-24 month food-contact approval cycles that delay commercial launch.
- Thermoformer capex reconfiguration:Converting polystyrene lines to APET requires infrared oven retrofits and tool steel upgrades for crystallization control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous Polyethylene Terephthalate (APET) Market |
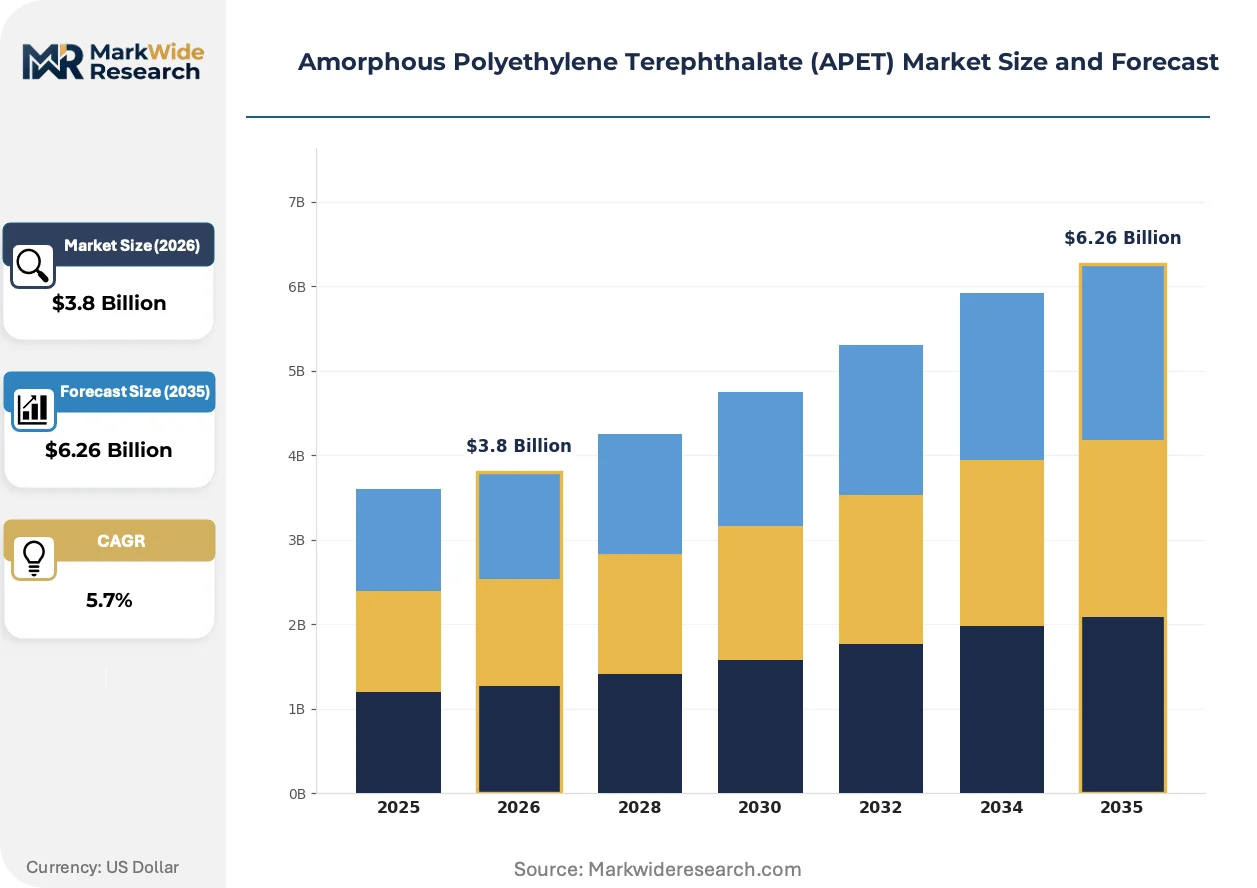
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: APET Films, APET Sheets, APET Bottles, APET Trays End Use Industry: Food Packaging, Consumer Goods, Electronics, Pharmaceutical Form: Rigid, Flexible, Blister, Laminated Packaging Type: Containers, Pouches, Labels, Clamshells |
| Companies Covered | Indorama Ventures Public Company Limited, Reliance Industries Limited, Alpek S.A.B. de C.V., Jiangsu Sanfangxiang Group Co., Ltd., DAK Americas, Covestro AG, Far Eastern New Century Corporation, LOTTE Chemical CORPORATION, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous Polyethylene Terephthalate (APET) Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reposition APET as the default clear packaging substrate across European fresh-food retail.
Multi-layer coextrusion with ethylene vinyl alcohol barrier layers is consolidating oxygen transmission performance in APET sheet for modified-atmosphere protein trays. German retail chains are specifying these structures for private-label meat and fish packaging. The technology is consolidating specification control among integrated resin producers who can compound barrier adhesives in-house.
REACH authorization requirements for di(2-ethylhexyl) phthalate in PVC compounds are accelerating food-contact substitution timelines across EU member states. Thermoformers in the Netherlands and Belgium are advancing APET conversion projects originally scheduled for 2027-2028. Fresh-protein tray manufacturers face compressed reformulation windows as ECHA sunset dates approach.
Retail procurement consolidation around centralized sustainability scorecards is elevating recyclability certification requirements for packaging suppliers. French and UK supermarket chains are unbundling traditional price-volume negotiations to insert rPET content verification and sortation infrastructure proof. This pattern concentrates volume with APET sheet producers who have secured RecyClass or equivalent third-party approvals.
Amorphous Polyethylene Terephthalate (APET) Market Segmentation
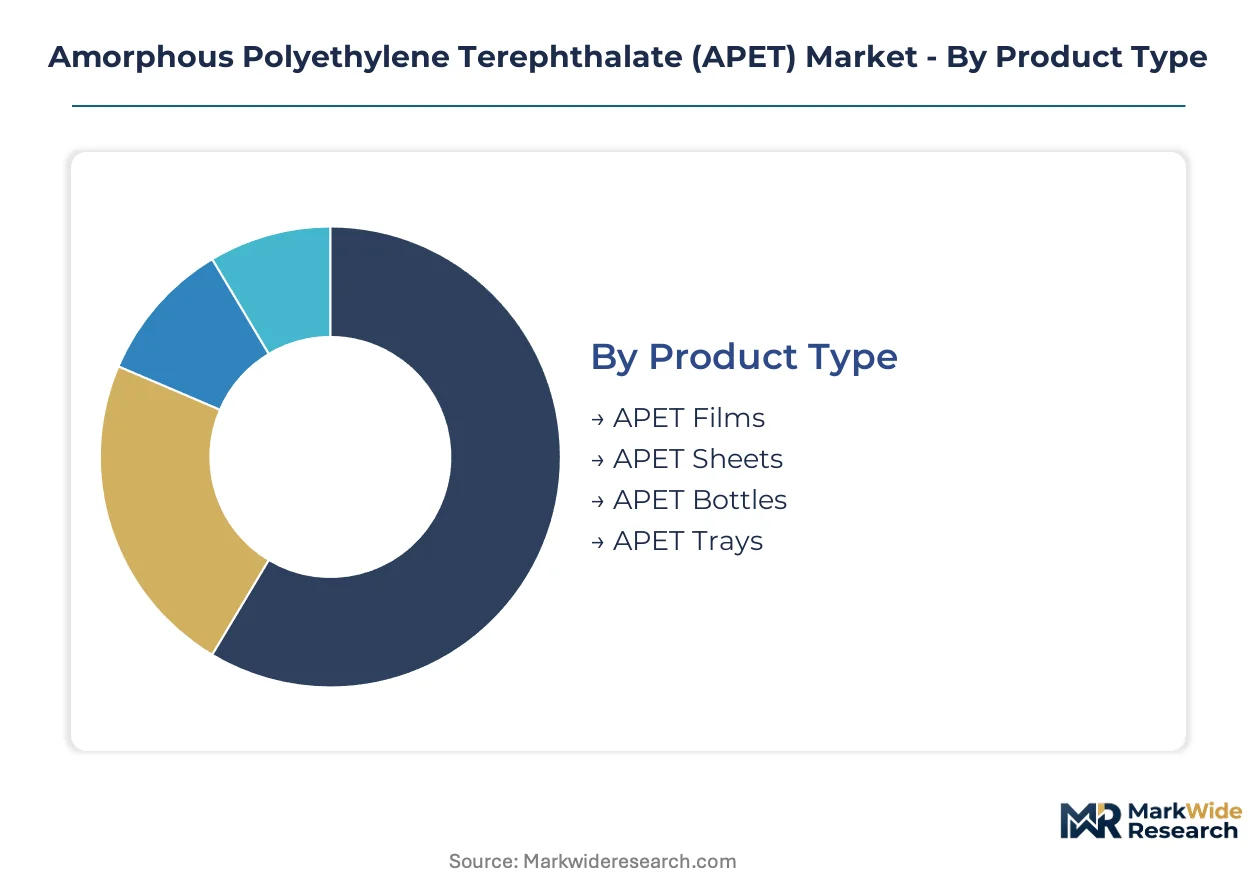
APET market segmentation reveals how material properties align with distinct performance requirements across packaging formats. Each product type and end-use pairing demands specific optical clarity, thermal stability, and barrier specifications that drive formulation differentiation.
Product Type:
Equipment upgrade cycles in thermoforming and extrusion lines determine conversion economics between sheet and film formats as processors replace legacy PVC and polystyrene assets.
- APET Films:Thin-gauge extruded or cast films deliver optical transmission above 85 percent for pharmaceutical blister lidding and electronics display protection. Demand concentrates in German and Swiss pharmaceutical packaging corridors where EFSA migration testing protocols favor established resin grades.
- APET Sheets:Extruded sheet stock ranging from 0.2 to 2.0 millimeters serves thermoformed fresh-protein trays across Benelux retail networks. Central European supermarket chains specify these structures under extended producer responsibility frameworks that penalize non-recyclable alternatives.
- APET Bottles:Stretch blow-molded containers compete with crystallized PET in cosmetic and personal care segments where amorphous clarity differentiates shelf presentation.
- APET Trays:Pre-formed rigid containers target ready-meal and deli applications requiring dimensional stability through cold-chain distribution.
Volume placements concentrate in APET Sheets; the faster expansion belongs to APET Films.
End Use Industry:
Customer procurement patterns split between compliance-driven food contact mandates and performance-specified medical and electronics applications.
- Food Packaging:Fresh-protein, produce, and ready-meal formats dominate tonnage as EU Green Deal circular economy mandates displace polystyrene and PVC. REACH authorization deadlines for phthalate plasticizers compress substitution timelines across Netherlands and Belgium thermoforming clusters.
- Pharmaceutical:Blister lidding and medical device packaging command premium positioning where EFSA food-contact approvals and US FDA migration testing create multi-year qualification barriers for new resin entrants.
- Consumer Goods:Cosmetic bottles and personal care containers leverage APET's glass-like clarity for premium shelf differentiation.
- Electronics:Display protection films and device packaging utilize optical-grade clarity specifications above standard packaging resin grades.
Food Packaging anchors absolute volume; Pharmaceutical generates the steepest margin expansion trajectory.
Form:
Structural requirements in downstream converting equipment dictate form selection based on thermoforming temperature windows and barrier performance needs.
- Rigid:Thermoformed clamshells and containers provide dimensional stability for retail produce and electronics where 75°C glass transition temperatures suffice for ambient distribution. German retail chains specify rigid APET for private-label meat and fish packaging under centralized sustainability scorecards.
- Flexible:Thin-gauge films conform to irregular product geometries in pouch and wrap applications where optical clarity replaces metallized films.
- Blister:Form-fill-seal compatibility positions APET against PVC in pharmaceutical unit-dose packaging where ECHA sunset dates accelerate conversion.
- Laminated:Multi-layer coextrusion with ethylene vinyl alcohol barrier layers consolidates oxygen transmission performance for modified-atmosphere protein trays.
Rigid form commands the largest installed base; Blister structures are climbing the fastest as pharmaceutical substitution accelerates.
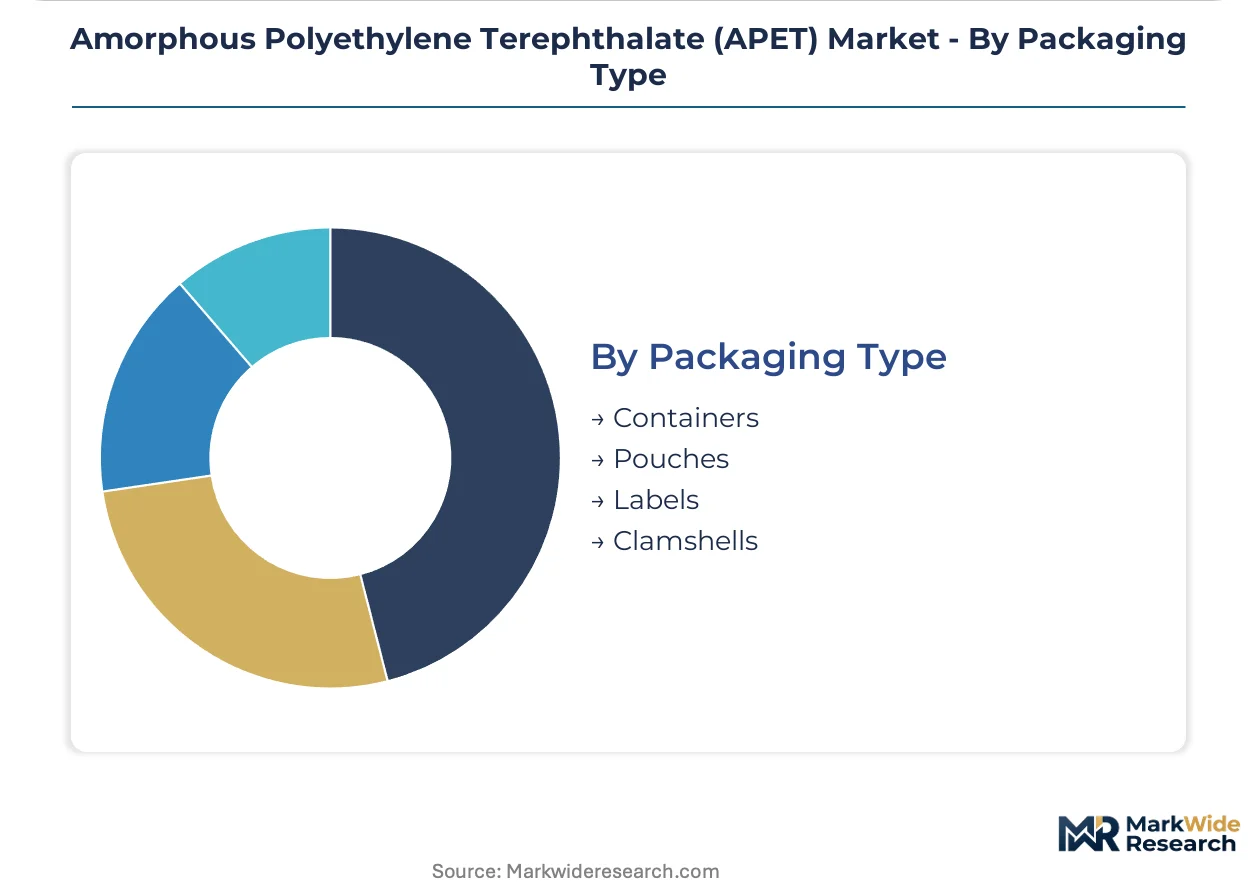
Packaging Type:
Retail format specifications and shelf-display requirements drive container geometry selection across fresh-food and consumer goods segments.
- Containers:Lidded tubs and cups serve yogurt, deli salads, and prepared meals where APET replaces polystyrene under French and UK supermarket recyclability mandates.
- Clamshells:Hinged rigid structures dominate produce and bakery retail where point-of-sale visibility and crush resistance outperform flexible alternatives.
- Pouches:Stand-up and flat pouch formats leverage APET film clarity for premium snack and confectionery positioning.
- Labels:Pressure-sensitive and in-mold label substrates exploit surface energy characteristics for direct inkjet decoration compatibility.
Containers absorb the heaviest volume flows; Clamshells gain share fastest as produce retail converts from PVC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Purified terephthalic acid feedstock economics anchor APET production geography around integrated petrochemical complexes in Thailand, India, and the United States. Resin flows from these hubs supply thermoforming clusters in Germany, fresh-food packaging converters in the Netherlands, and pharmaceutical blister manufacturers in Switzerland.
Germany
Thermoforming clusters around Munich and Hamburg convert APET sheet into fresh-protein trays for central European retail chains. EU Green Deal circular economy mandates enforce recycled content thresholds that favor virgin-quality rPET-APET blends. Bavarian converters are upgrading infrared oven lines to handle higher crystallization control requirements.
Thailand
Integrated PTA-PET complexes near Bangkok anchor Southeast Asian resin supply for export-oriented APET sheet production. Indorama Ventures leverages captive feedstock economics to serve European thermoformer demand. The country's petrochemical corridor faces geographic single-point vulnerability concerns among importers.
United States
FDA food contact regulations and EPA recycled content guidelines shape virgin-to-recycled blend ratios for domestic food packaging applications. DAK Americas operates integrated production serving North American thermoformers converting from PVC clamshells. Gulf Coast PTA supply chains expose sheet margins to naphtha-cracker volatility.
India
Reliance Industries sustains cost leadership through backward integration into purified terephthalic acid at its Jamnagar complex. Domestic demand for pharmaceutical blister lidding pulls optical-grade APET resin into medical packaging supply chains. Gujarat's petrochemical infrastructure supports regional sheet exports to Middle Eastern markets.
Netherlands
REACH authorization deadlines for phthalate plasticizers are compressing PVC substitution timelines across Dutch thermoforming operations. Retail procurement consolidation around sustainability scorecards elevates RecyClass certification requirements for packaging suppliers. Rotterdam-area converters are advancing APET conversion projects originally scheduled for 2027-2028.
Amorphous Polyethylene Terephthalate (APET) Market Competitive Environment
Global majors compete with regional champions across integrated feedstock economics and thermoforming customer proximity. The vendor base spans petrochemical conglomerates with captive PTA supply, mid-scale sheet specialists serving single-country retail networks, and diversified polymer players cross-selling into packaging applications. Three archetypes dominate: integrated resin producers controlling upstream feedstock, independent thermoformers reliant on merchant resin supply, and multi-material converters hedging across polymer portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure EFSA food-contact approvals and sortation infrastructure certifications.
Among integrated resin producers, Indorama Ventures Public Company Limited, Reliance Industries Limited, and Alpek S.A.B. de C.V. exemplify the feedstock-anchored archetype. Indorama Ventures occupies a position leveraging Thai and Indian manufacturing bases for regional APET sheet export supply. Reliance Industries sits within the cost-leadership tier through its Jamnagar PTA integration. Alpek S.A.B. de C.V. anchors Americas-focused competition with dedicated APET lines serving Mexican and United States thermoformers. These three represent how geographic feedstock concentration translates into packaging resin market positioning.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Reliance Industries Limited |
| Alpek S.A.B. de C.V. |
| Jiangsu Sanfangxiang Group Co., Ltd. |
| DAK Americas |
| Covestro AG |
| Far Eastern New Century Corporation |
| LOTTE Chemical CORPORATION |
| Teijin Limited |
| Others |
Value Chain & Pricing Dynamics
Skilled thermoforming technicians concentrated in Bavaria and Hamburg drive labor-cost differentials that widen pricing-tier spreads between premium certified-grade APET sheet and standard merchant resin offerings.
Pricing Analysis
Warranty-backed EFSA food-contact certification bundled with virgin-quality rPET-APET blends commands premium positioning against unbundled standard-grade sheet. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade pharmaceutical film from fresh-protein tray sheet and commodity blow-molding resin. Price differentiation hinges on RecyClass certification status and volume scale, with independent thermoformers facing cost compression from PTA feedstock volatility. Buyer price sensitivity peaks among small-format Dutch converters converting polystyrene lines, while pharmaceutical blister manufacturers exhibit lowest sensitivity due to multi-year qualification barriers.
Supply Chain Analysis
Single-source vulnerability sits with Thai PTA-PET complexes that anchor Southeast Asian resin exports to European thermoformers. Feedstock economics concentrate production gravity in Thailand, India, and the United States, where integrated petrochemical infrastructure controls purified terephthalic acid supply. Raw material dependencies rest on naphtha-cracker outputs, ethylene glycol availability, and catalyst systems for copolyester modification. Tariff exposure on Asian resin imports threatens margin stability for Benelux sheet converters. Distribution runs through Rotterdam port terminals and Hamburg hinterland logistics corridors serving central European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive PTA supply and EFSA certification timelines determine competitive survival. Players are pursuing backward integration into purified terephthalic acid to lock in feedstock economics.
For Market Incumbents: Deepen captive feedstock control through PTA complex investments in Thailand or India to outflank merchant resin competitors facing margin compression. Accelerate EFSA pre-submission programs for novel rPET-APET grades to compress 18-24 month approval timelines before REACH sunset dates tighten. Secure RecyClass certifications ahead of French and UK supermarket sustainability scorecard requirements to defend volume positions against emerging certified competitors. For New Entrants and Emerging Players: Mid-sized pharmaceutical blister converters underserved by established resin producers present white-space entry points for optical-grade APET film supply. Target Dutch thermoforming clusters facing compressed PVC substitution timelines under ECHA phthalate authorization deadlines. Pursue toll-manufacturing partnerships with German sheet extruders to bypass capital-intensive PTA integration requirements. For Investors and Strategic Acquirers: The window for entry favors integrated resin producers with captive feedstock and existing EFSA approvals. Long-term viability centers on assets positioned at the nexus of EU Green Deal recycled content mandates and Asian export logistics. Watch EFSA novel food-contact approval velocity as the inflection indicator for recycled-content APET grade commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA | Captive purified terephthalic acid supply shields Indorama Ventures and Reliance Industries from naphtha-cracker volatility. |
| EFSA Certification Investment | Early food-contact approval for rPET-APET blends secures premium positioning under EU Green Deal recycled content thresholds. |
| Thermoforming Cluster Partnership | Long-term offtake agreements with Munich and Hamburg converters anchor volume through ECHA substitution deadlines. |
| RecyClass Accreditation Program | Third-party recyclability verification unlocks French and UK supermarket procurement under centralized sustainability scorecards. |
| Infrared Oven Retrofit Services | Equipment upgrade partnerships with polystyrene converters accelerate APET adoption timelines in Netherlands and Belgium. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at integrated PTA-PET complexes, procurement leads at German retail chains, technical R&D directors at sheet extruders, and regulatory affairs specialists at pharmaceutical packaging firms combined with secondary validation. Secondary sources included EFSA food-contact guidance documents, ECHA REACH authorization timelines, Cefic plastics industry reports, and SEC 10-K disclosures from petrochemical conglomerates. Bottom-up resin production estimates and top-down packaging demand assessments underwent triangulation.
Reconciliation of production volume data from Thai and Indian PTA complexes against European import statistics and thermoformer consumption surveys shaped the analytical framework. Segmentation dimensions modeled encompassed product type, end-use industry, form rigidity, and packaging format across the projection horizon. CAGRs derived from regression analysis of historical resin pricing against naphtha cost curves and regulatory substitution elasticities. Industry-specific inputs included EFSA migration testing pipeline data and supermarket sustainability scorecard adoption rates.
Revisions become necessary when EFSA accelerates or delays novel recycled-content approval timelines, when PTA feedstock economics shift dramatically due to naphtha-cracker margin compression, or when EU Green Deal recycled content thresholds tighten beyond current specifications. Forecasts reflect documented assumptions about regulatory enforcement consistency and sortation infrastructure deployment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
North America Polymer Emulsion Market