
 Bakelite Market | 2026-2036
Bakelite Market Size, Share, and Industry Trends Forecast 2026-2036
Bakelite Market Intelligence
The capital-intensity divergence between integrated resin producers and downstream molders is collapsing as phenol-formaldehyde feedstock volatility squeezes compounder margins. Sumitomo Bakelite Co., Ltd. leverages captive cresol supply chains in Japan to sustain pricing power across Asian electrical laminate markets. Hexion Inc. anchors North American distribution through controlled toll-manufacturing partnerships with regional press operators. DIC Corporation competes on specialized color-stable grades for Japanese consumer appliance OEMs.
Bakelite denotes phenol-formaldehyde thermosetting resin systems cured under heat and pressure to form irreversibly cross-linked networks with dielectric strength exceeding 10 kV/mm and thermal stability above 150°C, serving primarily as structural and insulating materials where flame retardance and dimensional rigidity outweigh recyclability concerns. Thermosetting plastics occupy the dominant value share as legacy compression and transfer molding infrastructure across Asia-Pacific and Eastern Europe continues to absorb bulk phenolic compound volumes. Electrical components within the application dimension represent the fastest-expanding consumption node, driven by motor insulation and power distribution hardware requirements in electrified vehicle platforms and renewable energy switchgear.
EPA formaldehyde emission standards under TSCA Title VI constrain North American resin formulation practices, while REACH Annex XVII restrictions on phenol derivatives shape product registration and substitution economics for European compounders. China's GB standards for indoor air quality and the MIIT-led push toward higher-grade electrical insulation materials in new energy infrastructure are tightening compliance thresholds for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions as classification thresholds for formaldehyde-releasing articles harden, since dual-certification burdens will determine which compounders retain access to cross-border automotive and electronics supply chains.
Market Dynamics
REACH Annex XVII restrictions on formaldehyde-releasing articles are forcing European compounders into costly reformulation cycles while phenol feedstock volatility erodes margin buffers across the value chain.
Growth Catalysts
- Electrified vehicle thermal management:Motor insulation and battery housing applications in EV platforms are pulling phenolic laminates into powertrain architectures as operating temperatures climb.
- MIIT electrical insulation mandates:China's Ministry of Industry and Information Technology is tightening GB standards for new energy infrastructure, compelling domestic molders toward higher-grade phenolic compounds.
- Renewable energy switchgear deployment:Wind and solar grid interconnection projects across East China's manufacturing corridor are consuming flame-retardant structural components for transformer housings and distribution hardware.
Market Restraints
- Phenol-formaldehyde feedstock volatility:Benzene and methanol price swings transmit directly to resin production costs, squeezing compounder margins when contract pricing lags spot movements.
- Asian supply concentration:Captive cresol supply chains in Japan and phenol refining clusters in South Korea create dependency risks for non-integrated molders in Southeast Asia.
- Thermoset recyclability limitations:Irreversible cross-linking prevents mechanical reprocessing, exposing Bakelite to substitution pressure from engineering thermoplastics in circular-economy-sensitive applications.
Strategic Opportunities
- Indian electrical infrastructure buildout:The country's national electrical regulator and state distribution utilities are expanding transformer capacity under grid modernization programs, opening import substitution potential for phenolic laminate suppliers.
- Formaldehyde-free bio-phenolic development:Lignin-derived phenolic precursors are reaching pilot-scale viability, offering pathway to REACH-compliant formulations without petrochemical feedstock exposure.
- Direct OEM contracting models:Appliance and automotive manufacturers in East China are bypassing traditional distributor tiers, creating margin capture potential for compounders with in-house compounding and color-matching capabilities.
Industry Challenges
- Compression molding technician scarcity:Skilled press operators capable of managing multi-cavity mold configurations and cure cycle optimization are retiring faster than vocational programs replenish the workforce across Eastern European manufacturing zones.
- Dual-certification timeline compression:Compounders serving cross-border automotive supply chains must simultaneously satisfy EPA TSCA Title VI and REACH Annex XVII testing protocols, extending product qualification cycles.
- Legacy press fleet integration:Transfer molding equipment dating to the 1990s lacks precision temperature control required for next-generation thin-wall electrical components, forcing capital allocation decisions between retrofit and replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakelite Market |
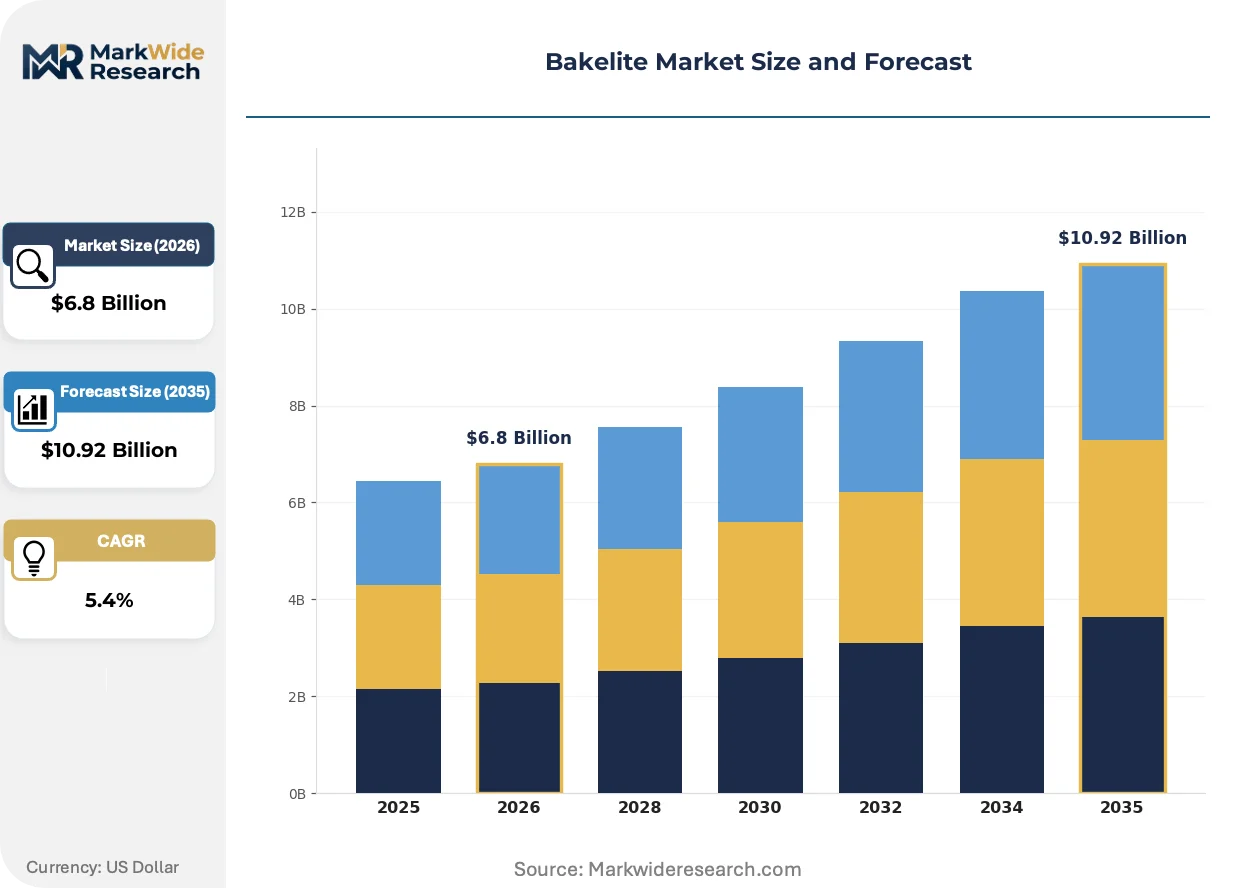
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Plastics, Composite Materials, Electrical Insulators, Industrial Parts End User: Automotive, Electronics, Consumer Goods, Construction Form: Granules, Sheets, Molds, Liquid Application: Insulation, Adhesives, Coatings, Electrical Components |
| Companies Covered | DIC Corporation, SABIC, Sumitomo Bakelite Co., Ltd., Kolon Industries, Inc., Chang Chun Group, Hexion Inc., Mitsui Chemicals, Inc., Plenco, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakelite Market Strategic Shifts & Innovations
Formulation chemistry, regulatory compliance architecture, and procurement pattern evolution are concurrently restructuring how phenolic resin systems reach end-use applications across electrical and transportation verticals.
Water-based phenolic resin technology is fragmenting traditional solvent-borne formulation dominance in electrical laminate production. Tier-2 laminate manufacturers in South Korea and Taiwan are adopting aqueous systems to reduce volatile organic compound emissions and simplify workplace safety protocols. The shift is fragmenting established supply relationships as water-compatible hardeners and accelerators require different procurement channels than conventional alcohol-soluble resins.
ECHA's tightening formaldehyde emission classification thresholds under REACH are compelling compounders to invest in low-emission resin curing technologies. The industrial consequence is accelerated substitution of conventional acid catalysts with latent curing systems that suppress free formaldehyde release during processing. European automotive under-the-hood applications are most affected, with German OEMs now requiring third-party emission testing documentation for all phenolic-based heat shield components.
Consolidated procurement by appliance OEMs is compressing supplier bases and demanding integrated material-plus-molding service bundles. Chinese white-goods manufacturers in the Yangtze River Delta are awarding multi-year contracts to compounders with captive press capacity rather than purchasing raw material separately. The pattern is most visible in color-stable consumer appliance housings, where molders must manage pigment dispersion, flame-retardant loading, and surface finish consistency under single-source accountability.
Bakelite Market Segmentation
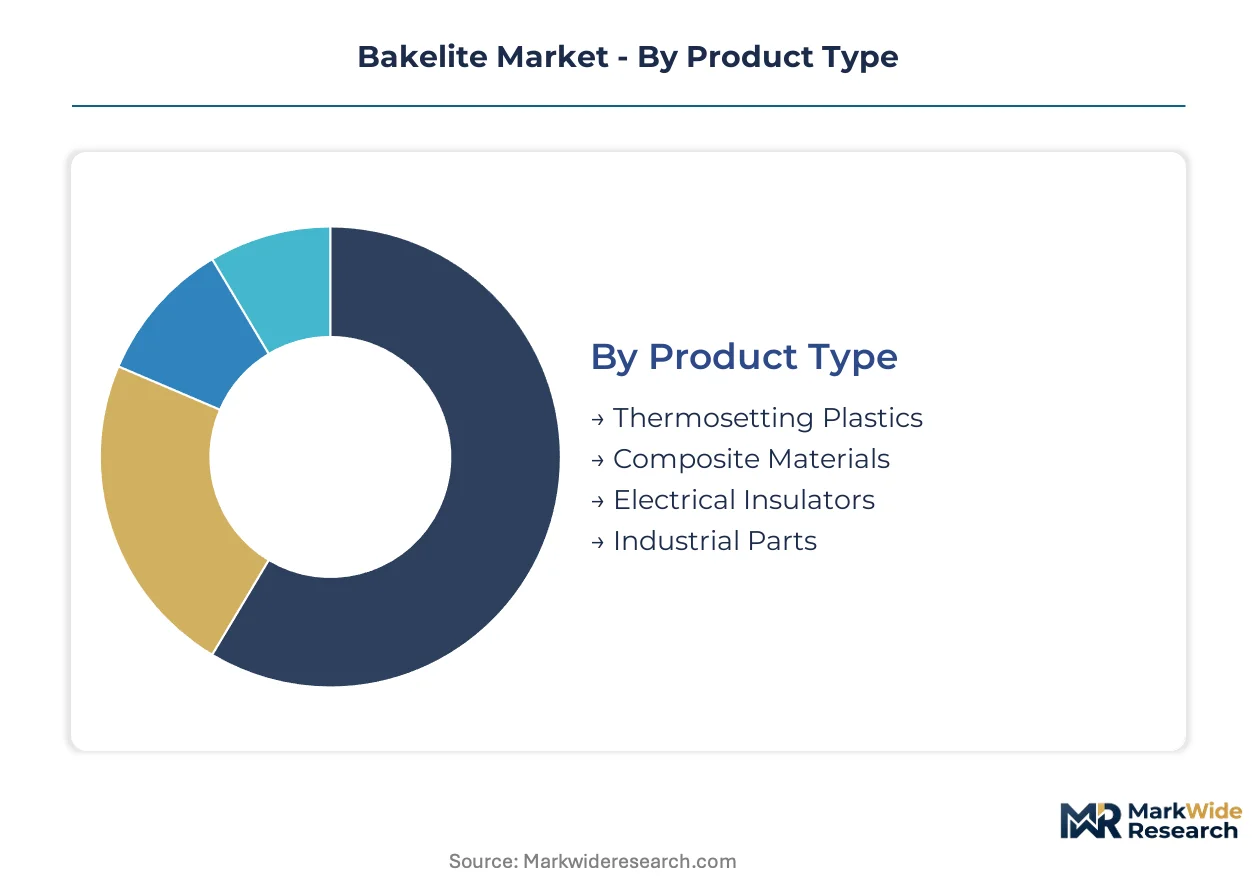
Bakelite's irreversible cross-linking chemistry creates rigid performance boundaries that segment the market by thermal tolerance and dielectric specifications rather than price elasticity. Compounders configure resin systems around these technical constraints, with margin capture varying sharply across molding complexity and certification burdens.
Product Type:
Thermosetting plastics concentrate the deepest margin pools due to legacy press infrastructure lock-in and formulation IP barriers that resist commoditization.
- Thermosetting Plastics:Phenol-formaldehyde resin systems cure into irreversibly cross-linked networks with dielectric strength exceeding 10 kV/mm. Automotive under-the-hood heat shield procurement in Germany and China pulls volume as engine bay temperatures climb past 150°C tolerance thresholds of engineering thermoplastics.
- Composite Materials:Fiber-reinforced phenolic laminates combine dimensional rigidity with flame retardance for aerospace interior panels and railway rolling stock. MIIT-mandated electrical insulation upgrades across China's new energy infrastructure are accelerating substitution for thermoplastic composites in transformer housings.
- Electrical Insulators:High-purity grades for motor slot wedges and busbar supports.
- Industrial Parts:Mechanical components where wear resistance outweighs weight considerations.
Thermosetting plastics hold installed capacity. Composite materials is rotating up the share rankings.
End User:
Customer concentration patterns split the market between specification-driven OEMs with captive technical staff and price-sensitive distributors serving fragmented fabrication shops.
- Automotive:Battery housing and motor insulation applications in electrified platforms demand flame-retardant structural materials with thermal cycling stability. German OEMs now require third-party formaldehyde emission documentation for all phenolic-based heat shield components under REACH Annex XVII tightening.
- Electronics:Printed circuit board substrates and connector housings require precision-moldable grades with consistent dielectric properties. East China's manufacturing corridor serves both domestic appliance brands and export electronics assemblers, with molders managing pigment dispersion and surface finish under single-source accountability.
- Consumer Goods:Color-stable appliance housings and cookware handles.
- Construction:Laminate panels and adhesive binders for engineered wood products.
Automotive commands specification premiums. Electronics is expanding most quickly on EV and renewable energy switchgear pull-through.
Form:
Physical configuration determines processing capital requirements, with liquid resins enabling spray application but demanding sophisticated ventilation systems.
- Granules:Free-flowing molding compounds for high-speed compression and transfer presses. South Korean and Taiwanese laminate manufacturers are adopting aqueous-compatible granule formulations to reduce volatile organic compound emissions and simplify workplace safety protocols.
- Sheets:Pre-impregnated laminates for electrical insulation and structural panels. Indian grid modernization programs under the national electrical regulator are expanding transformer capacity, opening import substitution potential for phenolic sheet suppliers.
- Molds:Custom-configured preforms for complex geometry components.
- Liquid:Low-viscosity resins for adhesive and coating applications.
Granules dominate volume throughput. Sheets is climbing the fastest on electrical infrastructure buildout.
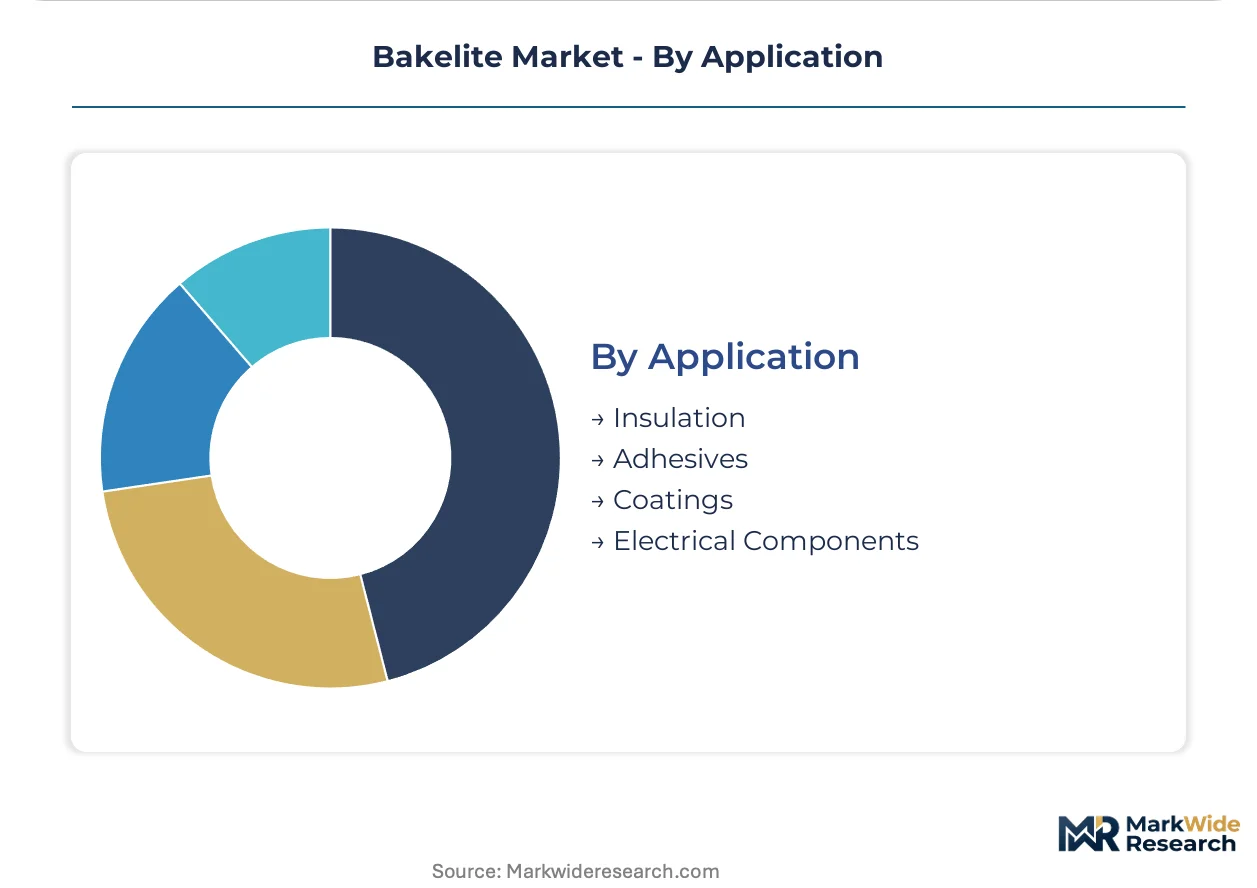
Application:
Functional end-use requirements impose divergent certification regimes, with electrical applications facing the most stringent material traceability mandates.
- Insulation:Motor slot liners, transformer barriers, and cable terminations requiring dielectric strength above 10 kV/mm. GB standards tightening under China's MIIT for new energy infrastructure compel domestic molders toward higher-grade phenolic compounds with documented thermal aging performance.
- Adhesives:Structural bonding for plywood, particleboard, and friction materials. Lignin-derived phenolic precursors are reaching pilot-scale viability, offering a pathway to REACH-compliant formulations without petrochemical feedstock exposure.
- Coatings:Protective and decorative finishes with chemical resistance.
- Electrical Components:Housings, connectors, and switchgear hardware.
Insulation anchors revenue concentration. Electrical components is gaining share fastest on renewable energy deployment and vehicle electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan's captive cresol supply chains contrasts sharply with margin compression facing non-integrated molders in Southeast Asia. German automotive OEMs enforce REACH Annex XVII emission documentation that Chinese exporters struggle to match. India's grid buildout and East China's manufacturing corridor concentrate demand growth.
China
MIIT-mandated GB standards for electrical insulation are compelling domestic molders toward higher-grade phenolic compounds. The Ministry of Industry and Information Technology enforces thermal aging documentation for new energy infrastructure components. The Yangtze River Delta hosts white-goods manufacturers awarding multi-year contracts to compounders with captive press capacity.
Germany
Automotive under-the-hood heat shield procurement accelerates as engine bay temperatures exceed thermoplastic tolerance thresholds. ECHA's REACH Annex XVII tightening requires third-party formaldehyde emission testing for all phenolic-based components. Bavaria's OEM technical centers specify low-emission resin curing technologies for supplier qualification.
Japan
Electrical laminate markets sustain premium pricing through captive cresol supply chain control. METI oversees industrial standards for motor insulation materials in electrified vehicle platforms. Kanto region resin producers leverage backward integration into phenol derivatives to buffer feedstock volatility.
India
National electrical regulator mandates expand transformer capacity under grid modernization programs. CEA guidelines tighten insulation material specifications for state distribution utilities. Maharashtra and Gujarat industrial corridors present import substitution openings for phenolic sheet suppliers serving domestic infrastructure buildout.
South Korea
Tier-2 laminate manufacturers adopt aqueous phenolic systems to reduce volatile organic compound emissions. MFDS workplace safety protocols accelerate water-compatible hardener procurement shifts. Busan-Ulsan chemical clusters fragment established supply relationships as formulation chemistry requirements diverge.
Bakelite Market Key Industry Players
Concentration sits with integrated resin producers possessing captive feedstock positions, while downstream molders face margin erosion from phenol-formaldehyde volatility. The market structures around three archetypes: petrochemical-backed compounders with upstream phenol control, specialized electrical laminate specialists with formulation IP, and regional press operators serving appliance OEMs. Competitive moves center on toll-manufacturing partnerships for distribution anchoring and direct OEM contracting to bypass distributor tiers.
Within the integrated compounder tier, Sumitomo Bakelite Co., Ltd. exemplifies captive supply chain advantages, while Hexion Inc. anchors North American positioning through controlled manufacturing relationships. DIC Corporation represents the specialization vector for color-stable consumer appliance grades. These three occupy positions that reflect divergent strategic bets on geographic coverage versus technical segmentation.
| Leading Market Players |
|---|
| DIC Corporation |
| SABIC |
| Sumitomo Bakelite Co., Ltd. |
| Kolon Industries, Inc. |
| Chang Chun Group |
| Hexion Inc. |
| Mitsui Chemicals, Inc. |
| Plenco |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day phenol inventory cycles in Japan's captive cresol supply chains grant Sumitomo Bakelite and Mitsui Chemicals pricing power that Southeast Asian molders cannot match, while European compounders absorb REACH-driven reformulation costs that compress their margin buffers against Asian imports.
Pricing Analysis
Configured-to-order pricing for color-stable appliance grades commands spreads of 15-25% above standard electrical laminate quotations, with premium-mid-economy pricing differentiation anchored in UL certification tiers and MIIT thermal aging documentation. Price differentiation stems from REACH Annex XVII compliance burden and captive feedstock integration, with German automotive OEMs least sensitive due to specification lock-in while Southeast Asian distributors face severe cost compression. Pricing pressure intensifies from benzene-methanol feedstock volatility transmitting directly to resin production costs.
Supply Chain Analysis
Strategic stockpiling of phenol and formaldehyde feedstocks dominates integrated producer behavior, contrasting with just-in-time resin procurement among non-integrated molders. Supply concentrates in Japan, South Korea, and Germany, with raw material dependencies on benzene, methanol, and cresol derivatives. Single-source vulnerability from Japan's captive cresol chains creates dependency risk for Asian electrical laminate manufacturers. Distribution runs through toll-manufacturing partnerships and direct OEM contracting tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for cure-cycle optimization and color-matching support are expanding faster than base compound sales, creating recurring-revenue layers that compounders with captive press capacity can attach to multi-year appliance OEM agreements.
For Market Incumbents: Consolidate backward integration into phenol derivatives and cresol supply chains to buffer feedstock volatility, while acquiring regional press operators in India's Maharashtra-Gujarat corridor to capture grid modernization procurement. Engineering thermoplastics substitution in circular-economy-sensitive applications poses the central threat requiring defensive formulation R&D investment. For New Entrants and Emerging Players: UL certification fast-track programs for electrical laminate grades open immediate access to East China's export electronics assemblers, with India's transformer insulation segment presenting the most penetrable white-space target. Direct contracting with Yangtze River Delta white-goods manufacturers bypasses entrenched distributor tiers. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors seeking to divest non-core phenolic resin divisions, particularly European assets facing REACH compliance cost escalation. Long-term viability hinges on bio-phenolic pilot-scale progression toward commercial lignin-derived formulations. The signal to watch is ECHA formaldehyde emission threshold tightening accelerating substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cresol Supply | Captive phenol derivative production insulates Sumitomo Bakelite and Mitsui Chemicals from benzene price volatility. |
| REACH-Compliant Bio-Phenolic Development | Lignin-derived precursors offer European compounders pathway to formaldehyde-free formulations under tightening ECHA thresholds. |
| Direct OEM Contracting Models | East China's appliance manufacturers bypass distributor tiers, awarding multi-year agreements to compounders with captive press capacity. |
| Indian Grid Infrastructure Localization | CEA-mandated transformer capacity expansion creates import substitution openings for phenolic sheet suppliers in Maharashtra and Gujarat. |
| Aqueous Resin System Adoption | South Korean and Taiwanese laminate manufacturers shift to water-based phenolics under MFDS workplace safety protocols. |
Research Approach
A standing panel of phenolic resin plant managers, automotive Tier 1 procurement leads, electrical laminate technical directors, and appliance OEM supply chain heads provided ongoing calibration against secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MIIT standardization notices. Primary fieldwork combined with bottom-up and top-down triangulation anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon, with segmentation modeling across thermoset grade tier, end-use vertical, physical form factor, and regional production hub. CAGRs derived from weighted average of demand elasticity coefficients and capacity expansion schedules, incorporating EV thermal management content-per-vehicle trajectories and renewable energy switchgear deployment pipelines as industry-specific inputs.
Underlying assumptions cover phenol-formaldehyde feedstock price stability and REACH Annex XVII implementation timelines, with deviation risk concentrated in ECHA formaldehyde emission reclassification and lignin-derived precursor commercialization rates. Revision becomes warranted when bio-phenolic pilot-scale yields cross commercial viability thresholds or when Indian electrical infrastructure procurement localization mandates accelerate beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Soft PVC Sealing Strip Market