
 Polyamide Precursors Market | 2026-2036
Polyamide Precursors Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide Precursors Market Outlook
Buyer concentration among automotive OEMs is rebalancing procurement volumes toward specialized polyamide grades with lower emissions profiles. BASF SE leverages its integrated caprolactam-adipic acid chain to sustain margin capture across nylon 6 and nylon 6,6 value streams. Ascend Performance Materials anchors North American supply through its Houston-area hexamethylenediamine operations. Evonik Industries AG differentiates via high-purity specialty amines for electrical and consumer applications.
Polyamide precursors encompass the monomeric and intermediate chemical building blocks—principally caprolactam, hexamethylenediamine, and adipic acid—that undergo condensation or ring-opening polymerization to form nylon resins with melt temperatures ranging from 220°C to 265°C and tensile strengths exceeding 80 MPa in finished fiber or engineering plastic form. These intermediates serve primarily as feedstocks for synthetic fibers, engineering thermoplastics, and film applications where thermal stability and chemical resistance are critical. Caprolactam occupies the largest volume share as the dominant feedstock for nylon 6 textile and industrial yarn production, while adipic acid paired with hexamethylenediamine commands premium positioning in automotive under-hood and electrical connector applications where nylon 6,6 heat performance is non-negotiable. Granules and fiber forms concentrate margin pools in compounder and textile mill channels, whereas liquid formulations remain confined to niche coating and adhesive segments with limited growth velocity.
EPA regulations in the United States govern adipic acid plant nitrous oxide emissions, while REACH and the EU F-Gas Regulation in Europe constrain fluorinated process aids and mandate lifecycle chemical assessments for imported polyamide articles. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for caprolactam and HMDA manufacturing clusters in Zhejiang and Jiangsu provinces. Stakeholders must monitor how carbon border adjustment mechanisms and evolving biobased monomer certifications reshape feedstock qualification criteria and plant location decisions across integrated nylon value chains.
Market Dynamics
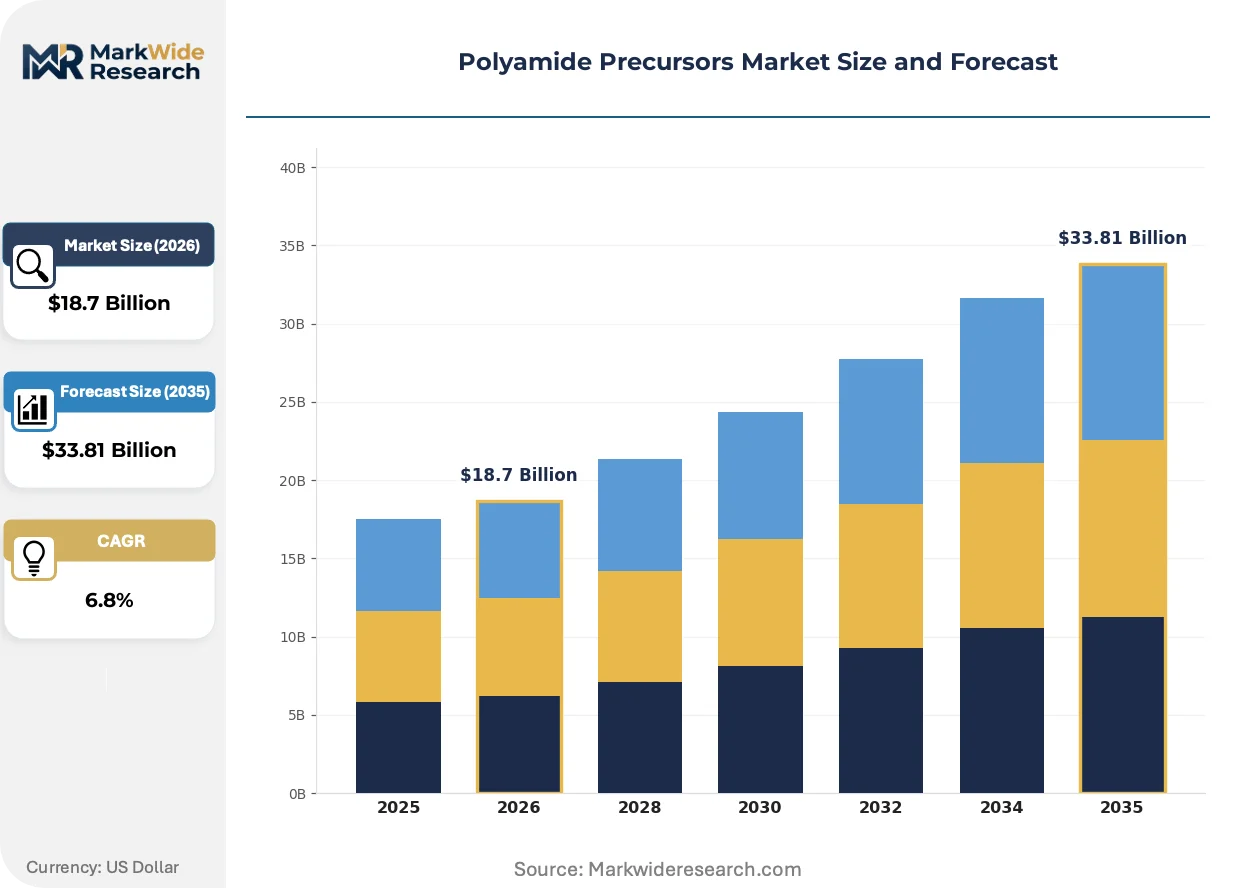
Automotive OEM procurement rebalancing toward specialized polyamide grades with lower emissions profiles is compressing margins for commodity caprolactam while elevating premiums for bio-based adipic acid and high-purity hexamethylenediamine streams.
Growth Catalysts
- EU Green Deal compliance mandates:REACH specifications for lifecycle chemical assessments are accelerating qualification of low-nitrous-oxide adipic acid pathways among European compounders serving automotive under-hood applications.
- China dual carbon targets:MEE energy intensity benchmarks for Zhejiang and Jiangsu manufacturing clusters are forcing efficiency upgrades that reduce per-unit production costs for domestic caprolactam supply.
- Nylon 6,6 thermal performance requirements:Electrical connector and powertrain component specifications exceeding 250°C service temperatures are cementing hexamethylenediamine-adipic acid pairing as non-substitutable in automotive engineering plastics.
Market Restraints
- Benzene feedstock volatility:Cyclohexane oxidation routes to adipic acid remain exposed to crude oil derivative pricing swings that compress cyclical margins for non-integrated producers.
- Zhejiang supply concentration:Caprolactam manufacturing clusters in eastern China account for disproportionate global nameplate capacity, creating single-point vulnerability to regional power rationing or environmental enforcement actions.
- Biobased monomer certification gaps:Absence of harmonized ISO standards for renewable content verification slows qualification timelines for sugar-derived adipic acid in automotive OEM supply chains.
Strategic Opportunities
- India textile manufacturing expansion:PLI scheme incentives for technical textiles are attracting caprolactam downstream investment to Gujarat and Tamil Nadu industrial corridors.
- Recycled nylon feedstock integration:Chemical depolymerization of post-industrial carpet and fishing net waste is expanding into closed-loop caprolactam regeneration with virgin-equivalent purity specifications.
- US IRA clean manufacturing credits:Section 45X advanced manufacturing production credits are offsetting capital intensity for greenfield hexamethylenediamine facilities with carbon capture integration.
Industry Challenges
- Process safety expertise scarcity:Nitric acid oxidation and cyclohexanone oximation operations require specialized chemical engineering talent that competes with semiconductor and battery material sectors for limited graduates.
- Multi-jurisdiction certification timelines:Simultaneous EPA New Source Review, ECHA REACH registration, and MEE environmental impact assessment processes extend project commissioning by 18-24 months for integrated adipic acid-caprolactam complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide Precursors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caprolactam, Hexamethylenediamine, Adipic Acid, Others Application: Textiles, Automotive, Electrical, Consumer Goods Form: Granules, Powder, Liquid, Fibers End User: Manufacturers, OEMs, Retailers, Distributors |
| Companies Covered | Toray Industries, Inc., Ascend Performance Materials, BASF SE, Huafon Group Co. Ltd., DuPont de Nemours, Inc, Asahi Kasei Corporation, Evonik Industries AG, Invista S.à r.l, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide Precursors Market Strategic Shifts
Process intensification and feedstock diversification are fragmenting the traditional petrochemical nylon value chain into parallel bio-based, recycled-content, and carbon-captured production pathways with diverging cost structures.
Enzymatic oxidation of cyclohexane to adipic acid is expanding into commercial-scale demonstration at select European and North American pilot facilities. BASF and Genomatica engineering biology platforms achieve higher selectivity than traditional nitric acid routes while eliminating nitrous oxide byproduct formation. Specialty automotive and consumer electronics buyers are qualifying these outputs for Scope 3 emissions reporting compliance.
REACH authorization requirements for fluorinated process aids under the EU F-Gas Regulation are forcing adipic acid producers to retrofit purification trains with membrane separation or crystallization alternatives. German and Dutch manufacturing sites face the most compressed compliance timelines due to earlier national transposition of the delegated acts. Capital allocation is prioritizing hexamethylenediamine purification over adipic acid expansion in European asset portfolios.
Automotive OEMs are consolidating nylon 6,6 compound purchases through direct long-term offtake agreements with integrated hexamethylenediamine producers, bypassing traditional distributor and compounder intermediaries. Tier-1 suppliers in Germany and Japan report contract durations extending from 12-month spot frameworks to 36-60 month volume commitments with price collars. This concentration is visible most acutely in electric vehicle thermal management component categories where material qualification cycles exceed 24 months.
Polyamide Precursors Market Segmentation
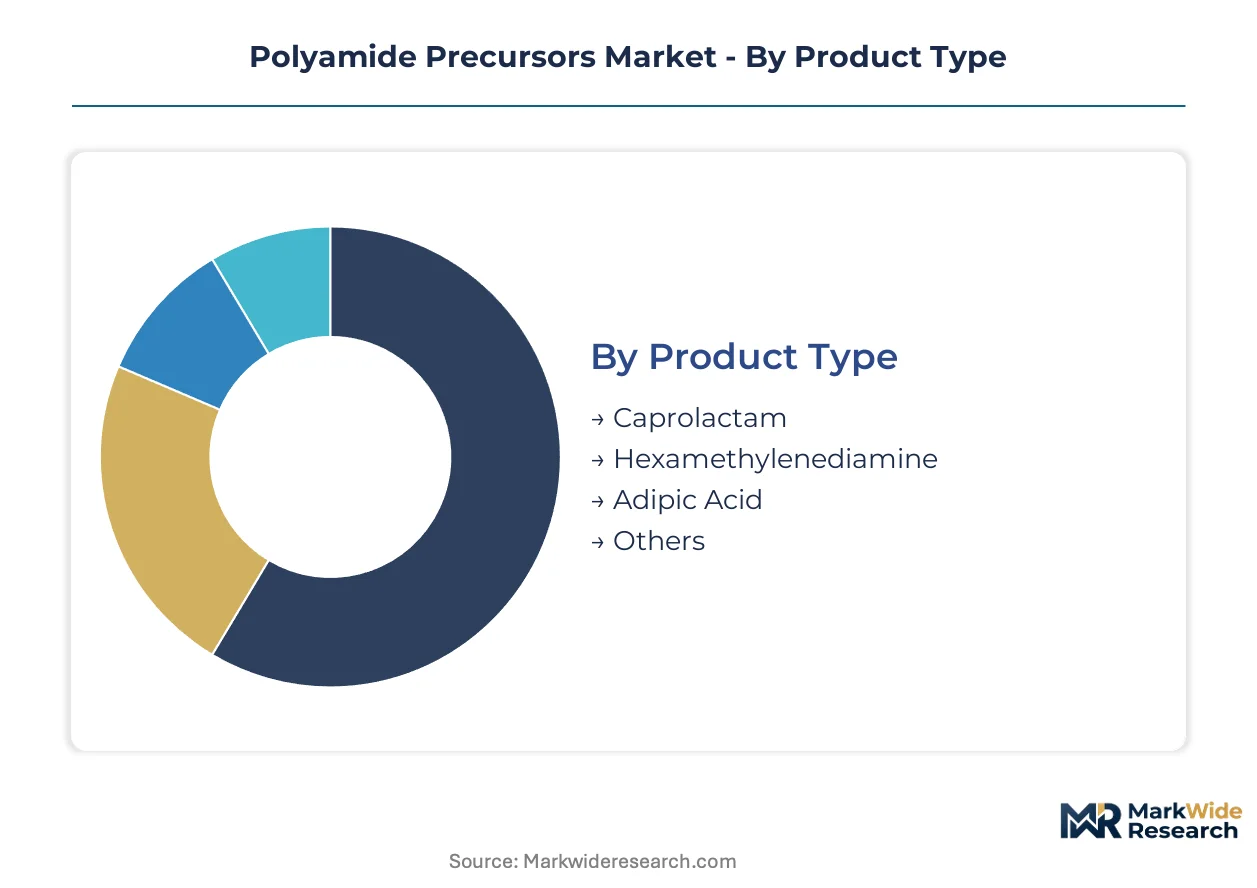
Polyamide precursor supply chains fragment along technical specifications, conversion pathways, and customer integration depth. Understanding how procurement concentrates across these dimensions reveals where margin pools accumulate and where substitution risks emerge.
Product Type:
Caprolactam manufacturing clusters in Zhejiang province anchor global nameplate capacity, while adipic acid production routes diverge between petrochemical and emerging bio-based pathways.
- Caprolactam:Cyclohexanone oximation produces this seven-membered lactam with 99.9% purity specifications for textile-grade polymerization. Demand concentrates in China where Huafon Group and domestic textile manufacturers anchor regional consumption; MEE energy intensity benchmarks force continuous efficiency upgrades that reduce per-unit production costs.
- Adipic Acid:Nitric acid oxidation of cyclohexane yields this dicarboxylic acid with melt temperatures at 152°C, serving as the essential co-monomer for nylon 6,6. REACH lifecycle chemical assessments and EU Green Deal compliance requirements are tightening specifications for production pathways with lower nitrous oxide emissions profiles.
- Hexamethylenediamine:Ammoniation of adiponitrile generates this diamine with stringent moisture specifications below 0.1% for automotive under-hood applications.
- Others:Specialty amines including dodecanedioic acid and sebacic acid serve niche high-temperature and bio-based polymer formulations.
Today's leader: Caprolactam. Tomorrow's challenger: Adipic acid.
Application:
End-use demand stratifies by thermal performance requirements, with automotive specifications cementing nylon 6,6 positioning while textile applications drive caprolactam volume.
- Textiles:Nylon 6 fiber production for apparel, carpet, and industrial yarn consumes the majority of caprolactam throughput. India's PLI scheme incentives for technical textiles are attracting downstream investment to Gujarat and Tamil Nadu industrial corridors.
- Automotive:Under-hood components, powertrain parts, and thermal management systems require service temperatures exceeding 250°C. OEM procurement rebalancing toward specialized grades with lower emissions profiles compresses commodity margins while elevating premiums for high-purity streams.
- Electrical:Connectors, circuit breakers, and switch housings leverage nylon 6,6 dielectric properties and flame retardancy.
- Consumer Goods:Sporting equipment, kitchen utensils, and personal care packaging utilize nylon resins for durability and chemical resistance.
Textile applications currently dominate volume; automotive applications command the steepest expansion trajectory as electrification intensifies thermal management material specifications.
Form:
Physical presentation determines downstream handling infrastructure and margin capture position in the value chain.
- Granules:Pelletized resin with controlled moisture content below 0.08% serves compounders and injection molders. This form concentrates margin pools in automotive and electrical channels where material qualification cycles exceed 24 months.
- Fibers:Continuous filament and staple forms feed textile mill spinning operations with denier specifications from 20D to 2000D. Chemical depolymerization of post-industrial carpet and fishing net waste is expanding into closed-loop regeneration with virgin-equivalent purity.
- Powder:Micronized particles for rotational molding and coating applications with particle size distributions below 150 microns.
- Liquid:Monomer and oligomer formulations for reactive injection molding and coating segments with limited growth velocity.
Granules and fiber forms capture the dominant share of value-add; liquid formulations remain confined to specialty coating niches.
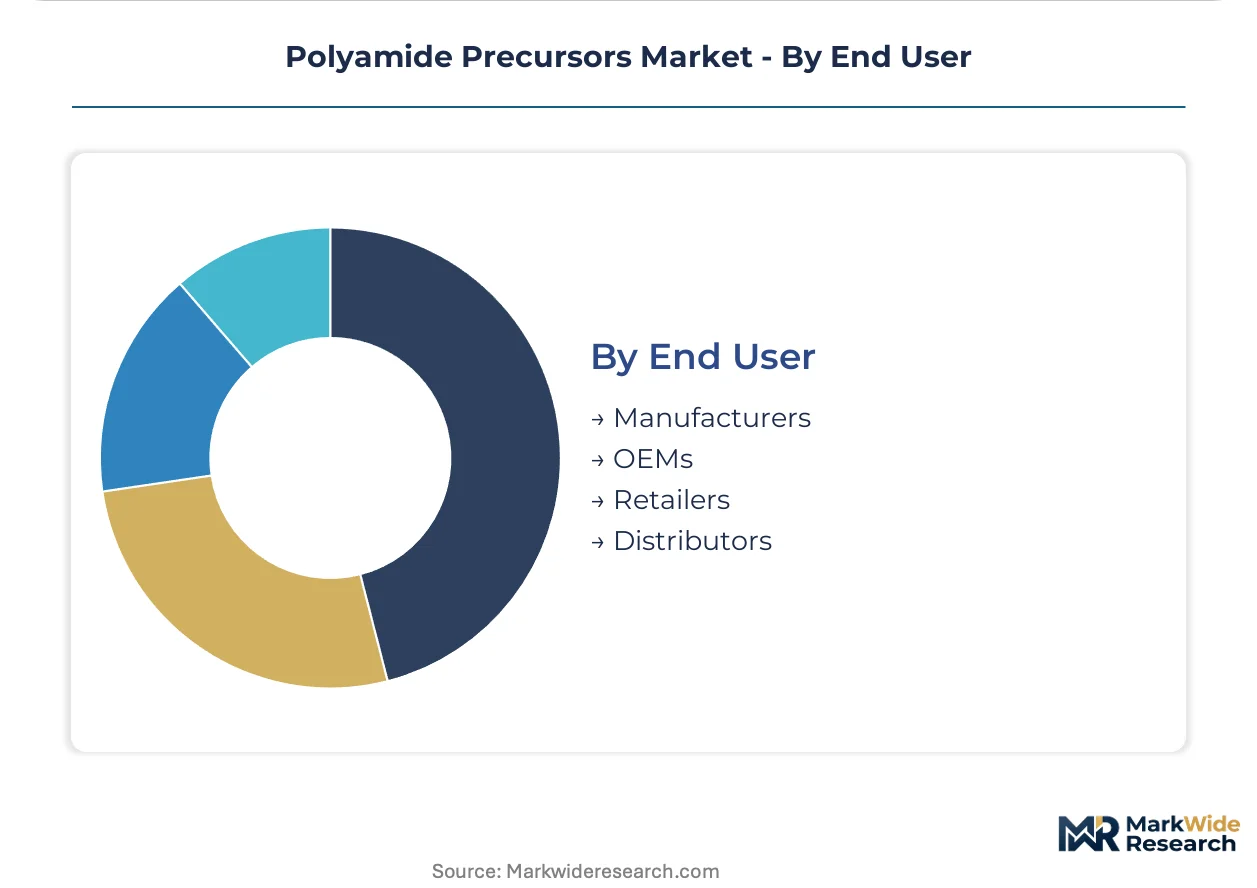
End User:
Customer type determines contract structure, with direct OEM relationships displacing traditional distributor intermediaries in automotive channels.
- OEMs:Automotive and electrical equipment manufacturers are consolidating nylon 6,6 compound purchases through direct long-term offtake agreements with integrated producers, bypassing traditional intermediaries. Contract durations are extending from 12-month spot frameworks to 36-60 month volume commitments with price collars.
- Manufacturers:Textile mills, compounders, and film processors purchase feedstocks for conversion into finished articles. China's domestic textile manufacturers anchor regional consumption of caprolactam feedstocks.
- Distributors:Regional chemical distributors serve smaller compounders and processors with inventory management and technical service.
- Retailers:Limited direct participation; primarily indirect through private-label consumer goods specifications.
OEM direct procurement is gaining share fastest; distributor channels face compression as qualification timelines lengthen and volume commitments consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent clusters in Zhejiang province and the Houston metropolitan area anchor integrated nylon precursor production networks.
China
Huafon Group and domestic textile manufacturers drive caprolactam consumption through Zhejiang province manufacturing clusters. MEE dual carbon goals enforce energy intensity benchmarks that accelerate efficiency upgrades across Jiangsu chemical corridors. Shaoxing and Hangzhou industrial zones concentrate global nameplate capacity for cyclohexanone oximation operations.
United States
Automotive OEM thermal management specifications spur hexamethylenediamine demand for nylon 6,6 engineering plastics. EPA nitrous oxide emission standards govern adipic acid plant operations in Texas and Louisiana chemical corridors. Houston-area manufacturing complexes anchor North American supply through integrated adiponitrile-ammoniation infrastructure.
Germany
REACH lifecycle chemical assessments and EU F-Gas Regulation compliance reshape adipic acid purification technology choices. Ludwigshafen chemical complexes sustain integrated caprolactam-adipic acid chain operations serving automotive under-hood applications. ECHA authorization timelines for fluorinated process aids compress retrofit investment windows.
India
PLI scheme incentives for technical textiles attract caprolactam downstream investment to Gujarat and Tamil Nadu industrial corridors. BIS quality specifications govern nylon fiber imports for domestic apparel and carpet manufacturing. Surat textile clusters expand spinning capacity for industrial yarn applications.
Japan
METI carbon neutrality roadmaps guide engineering plastics manufacturers toward low-emissions precursor sourcing. Nagoya and Osaka industrial zones concentrate automotive Tier-1 compounder operations with extended material qualification cycles. JIS standards for electrical connector applications cement nylon 6,6 thermal performance requirements.
Polyamide Precursors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across polyamide precursor value streams. The market structure consolidates around integrated producers controlling multiple monomer stages versus specialized manufacturers concentrating on single intermediates. Three archetypes dominate: petrochemical majors with backward integration into benzene derivatives, regional champions serving domestic textile mills, and technology licensors commercializing bio-based oxidation pathways. Competitive dynamics center on capacity expansion in low-cost manufacturing zones and strategic partnerships for recycled feedstock qualification.
Within the integrated petrochemical tier, BASF SE and Ascend Performance Materials exemplify archetypes of value chain control. BASF SE occupies a position representing European chemical conglomerate diversification across caprolactam and adipic acid production stages. Ascend Performance Materials anchors North American positioning through Houston-area hexamethylenediamine operations. Huafon Group Co. Ltd. represents Chinese regional champion concentration serving domestic textile demand clusters.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Ascend Performance Materials |
| BASF SE |
| Huafon Group Co. Ltd. |
| DuPont de Nemours, Inc |
| Asahi Kasei Corporation |
| Evonik Industries AG |
| Invista S.à r.l |
| Lanxess AG |
| Others |
Value Chain & Pricing Dynamics
Enzymatic oxidation pathways for adipic acid production are fragmenting cost structures while concentrating supply leverage among integrated producers controlling both bio-based and conventional routes. This technological bifurcation simultaneously elevates premiums for low-nitrous-oxide certified grades and compresses spot-market margins for commodity cyclohexane-derived material.
Pricing Analysis
Contract-based long-term offtake agreements dominate automotive OEM procurement, separating integrated producers with backward control over hexamethylenediamine from distributors serving spot-market textile buyers. Price differentiation hinges on ISO 14001 environmental certification tier and volume scale commitments exceeding 10,000 metric tons annually. Cost compression in standard-grade caprolactam is intensifying because MEE-mandated efficiency upgrades in Zhejiang are flooding regional spot markets. Textile mills in Surat and Shaoxing exhibit the highest price sensitivity, while automotive Tier-1 suppliers in Germany and Japan accept premium collars for qualified material.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns serving compounders with 30-60 day inventory buffers. Manufacturing concentrates in China, the United States, and Germany, with Zhejiang province hosting disproportionate cyclohexanone oximation capacity. Feedstock chains draw from benzene derivatives, ammonia, and nitric acid, resting on cyclohexane oxidation economics tethered to crude oil volatility. Single-source vulnerability pervades hexamethylenediamine supply, where adiponitrile hydrogenation technology is controlled by a handful of integrated complexes. Distribution runs through direct mill relationships in textile channels and compounder networks in automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive electrification forces thermal management specifications beyond 250°C service temperatures, cementing demand for premium nylon 6,6 grades with extended qualification cycles.
For Market Incumbents: Anchor margin position through captive adipic acid-hexamethylenediamine integration and accelerated bio-based pathway certification to meet Scope 3 reporting requirements. Defend against specialty amine entrants by locking 36-60 month offtake agreements with EV thermal management suppliers before qualification windows close. Prioritize retrofit investment in membrane separation purification trains ahead of EU F-Gas Regulation enforcement timelines. For New Entrants and Emerging Players: Begin with chemical depolymerization of post-industrial carpet waste for closed-loop caprolactam regeneration, where virgin-equivalent purity specifications command specialty premiums. India's PLI scheme corridors in Gujarat offer the most penetrable geography, with technical textile demand outpacing domestic supply. Pursue toll-manufacturing partnerships with Zhejiang producers to bypass 18-24 month greenfield permitting timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional textile-focused caprolactam specialists lacking automotive qualification infrastructure. Long-term viability favors integrated producers with dual carbon compliance capabilities and carbon capture integration. Watch for MEE enforcement actions in Jiangsu as an inflection signal for supply disruption premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive hexamethylenediamine supply secures automotive OEM qualification timelines against distributor competition. |
| Green Manufacturing Transition | Enzymatic oxidation platforms eliminate nitrous oxide byproduct formation for REACH compliance. |
| Long-term Supply Agreement | Direct OEM offtake contracts bypass traditional compounder intermediaries in thermal management applications. |
| Joint Venture | Technology licensors partner with Indian textile mills to localize caprolactam production under PLI incentives. |
| Capacity Expansion | Houston-area hexamethylenediamine buildout leverages Section 45X credits for carbon-captured production. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Zhejiang manufacturing complexes, procurement leads at German automotive Tier-1 suppliers, distribution channel partners in Rotterdam and Singapore, and technical R&D directors at integrated petrochemical majors. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Historical reference periods spanning 2019-2025 established baseline growth trajectories against which projection scenarios were stress-tested. The analytical framework modeled segmentation across grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from slope-intercept regression against normalized capacity utilization rates and named demand shifts in EV thermal management. Industry-specific forecast inputs included MEE energy intensity benchmark compliance curves and REACH authorization timelines for fluorinated process aids.
Caveats apply where benzene feedstock volatility, regional power rationing in eastern China, or delays in biobased monomer ISO standard harmonization could materially shift the outlook. Forecasts reflect documented assumptions around automotive electrification penetration and dual carbon enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market