
 Autonomous Trains Components Market | 2026-2036
Autonomous Trains Components Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Trains Components Market Analysis
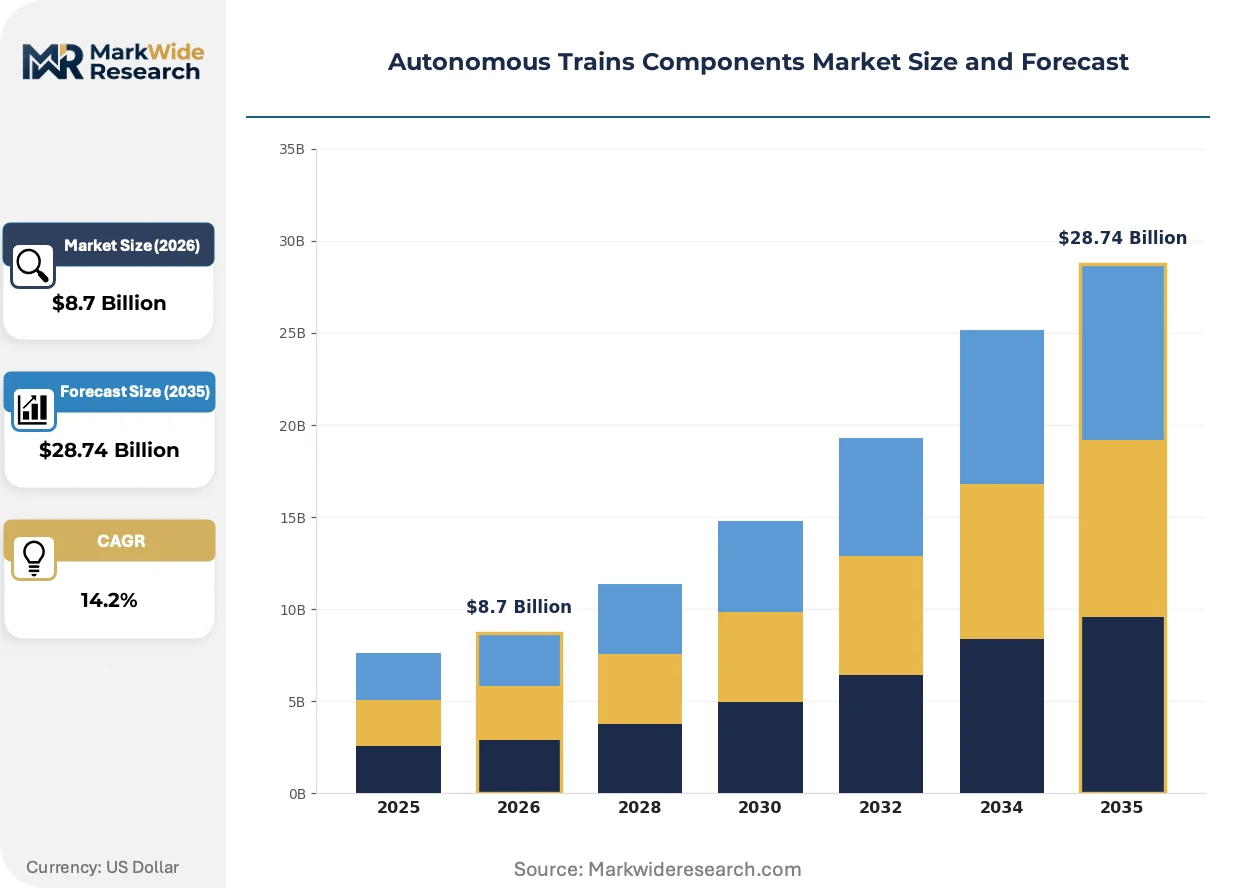
Sil-4 safety certification is collapsing from a premium tier into a baseline procurement requirement across European and Asian rail networks. Siemens AG leverages its signaling heritage to sustain engineering margins on autonomous control modules. Alstom SA anchors its competitive stance through integrated platform-level automation systems spanning rolling stock and infrastructure.
Autonomous trains components comprise the electromechanical and electronic subsystems that enable self-directed rail vehicle operation without continuous human intervention, incorporating radar and lidar sensors with millimeter-wave precision, programmable logic controllers executing real-time decision algorithms, and vehicle-to-infrastructure communication nodes operating at sub-50-millisecond latency. These assemblies serve the primary purpose of maintaining safe headways, platform alignment, and emergency braking independent of onboard operators. Navigation functionality within the functionality dimension leads current procurement volumes as operators retrofit legacy lines for grade-of-automation upgrades, while safety systems command the deepest margin pools due to validation-intensive development cycles and recertification barriers. Sensors dominate the component type category by unit volume, though communication systems capture disproportionate value per trainset as 5G-ready backhaul requirements multiply.
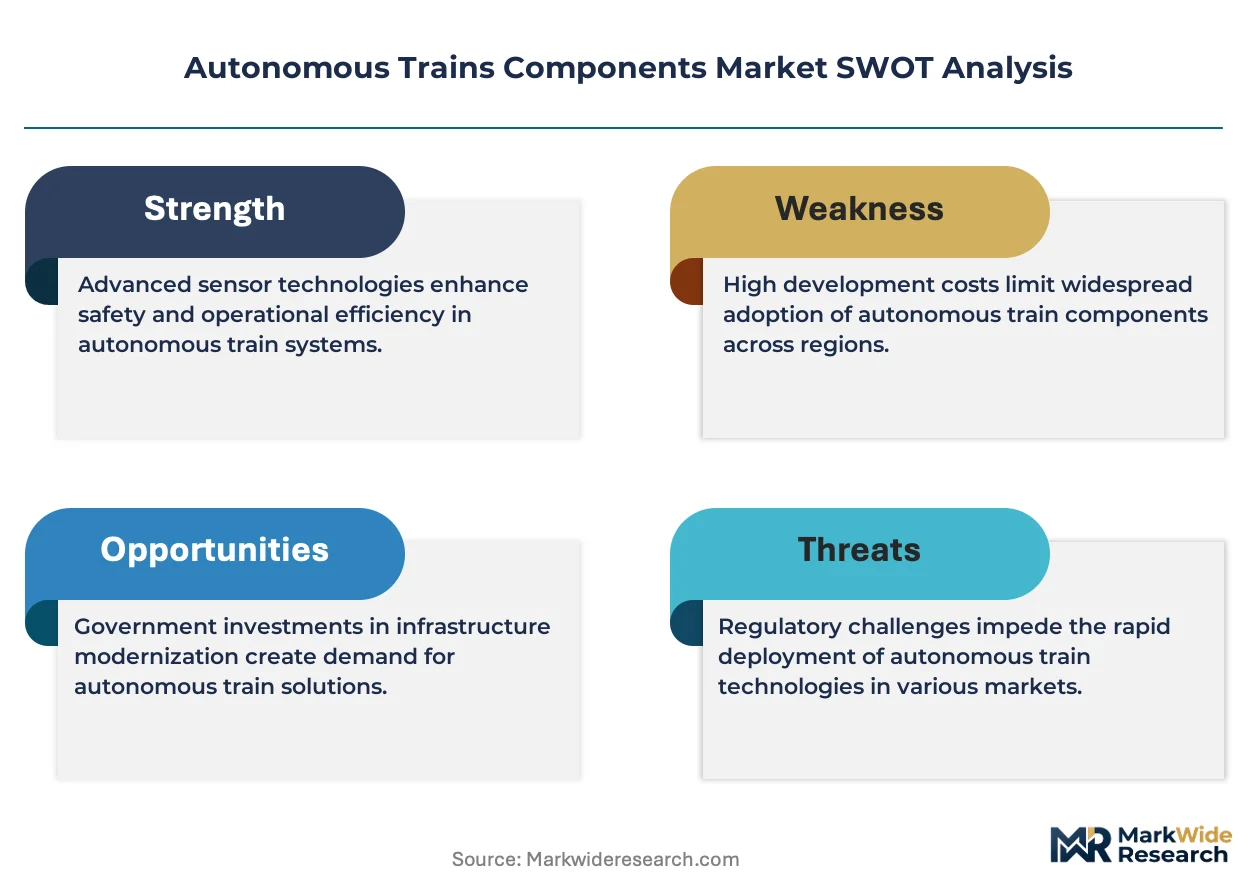
The European Union Agency for Railways enforces harmonized safety standards through the Common Safety Method regulation, compelling component vendors to maintain dual certification frameworks for EU and non-European deployments. China's NMPA-aligned railway regulator and Japan's METI both mandate domestic testing protocols that extend market access timelines for foreign suppliers. India's CEA and BIS are formulating localized electromagnetic compatibility standards for metro automation retrofits. Stakeholders must weigh certification jurisdiction against production scale economics when situating final assembly capacity.
Market Dynamics
The migration from Grade of Automation 2 to Grade of Automation 4 systems is compressing supplier qualification timelines while expanding validation scope for sensor fusion architectures. ETSI harmonization mandates are forcing component vendors to redesign communication modules for cross-border interoperability.
Growth Catalysts
- Urban metro densification:China's high-speed rail corridors are retrofitting legacy signaling for driverless operation, triggering bulk sensor procurement cycles.
- REACH compliance spillover:European rolling stock operators are replacing legacy electromagnetic components with RoHS-aligned alternatives, opening replacement demand.
- 5G-Advanced rail backhaul:Japan's commuter networks are deploying millimeter-wave vehicle-to-infrastructure nodes, accelerating communication system upgrades.
Market Restraints
- Sil-4 certification cost structure:Validation-intensive development cycles for safety-critical PLCs consume 18-24 month timelines before revenue recognition.
- Gallium nitride supply concentration:Millimeter-wave radar substrate fabrication depends on a concentrated supplier base in East Asian foundries.
- Legacy copper signaling persistence:Brownfield rail corridors retain analog track circuits that resist digital overlay integration without full infrastructure replacement.
Strategic Opportunities
- India metro automation retrofits:CEA and BIS electromagnetic compatibility standard formulation creates first-mover positioning for compliant component vendors.
- Digital twin convergence:Physics-based simulation platforms fused with real-time sensor telemetry enable predictive maintenance contracts.
- EU AI Act rail carve-out:Automated decision systems in safety-critical applications face distinct conformity assessment pathways, favoring established certification holders.
Industry Challenges
- Functional safety engineering scarcity:Sil-4 software verification expertise concentrates among specialists with rail-specific TÜV certification.
- Multi-jurisdiction recertification burden:Component vendors must maintain parallel validation frameworks for EU Common Safety Method, China's NMPA-aligned protocols, and Japan's METI testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Trains Components Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Sensors, Controllers, Power Supply, Communication Systems Functionality: Navigation, Monitoring, Control, Safety Systems Material: Metal, Composite, Plastic, Electronic Components End User: Rail Operators, Manufacturers, Maintenance Providers, Research Institutions |
| Companies Covered | Alstom SA, Thales Group, Siemens AG, Hitachi Ltd., Wabtec Corporation, CRRC Corporation Limited, Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Knorr-Bremse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Trains Components Market Emerging Trajectories
Solid-state lidar architectures are collapsing the cost curve for high-precision obstacle detection while ETSI standardization is locking in communication protocols that will govern procurement specifications for the next decade.
Frequency-modulated continuous-wave lidar is supplanting mechanical scanning units in platform-edge detection systems. Japanese commuter operators are deploying solid-state units at scale for GoA4 platform screen door alignment. The technology is supplanting legacy ultrasonic sensors in precision-critical applications, compressing the addressable market for electromechanical alternatives.
The EU AI Act's high-risk system classification places automated train operation algorithms under mandatory conformity assessment. Vendors must document training data provenance and decision traceability for safety-critical AI components. European signaling suppliers are restructuring development workflows to embed technical documentation from initial architecture design.
Chinese state rail operators are unbundling component procurement from rolling stock OEM contracts, creating direct vendor relationships for sensor and communication module suppliers. This disintermediation shifts pricing power toward operators with volume consolidation. The pattern is most visible in Shanghai and Beijing metro modernization programs.
Autonomous Trains Components Market Segmentation
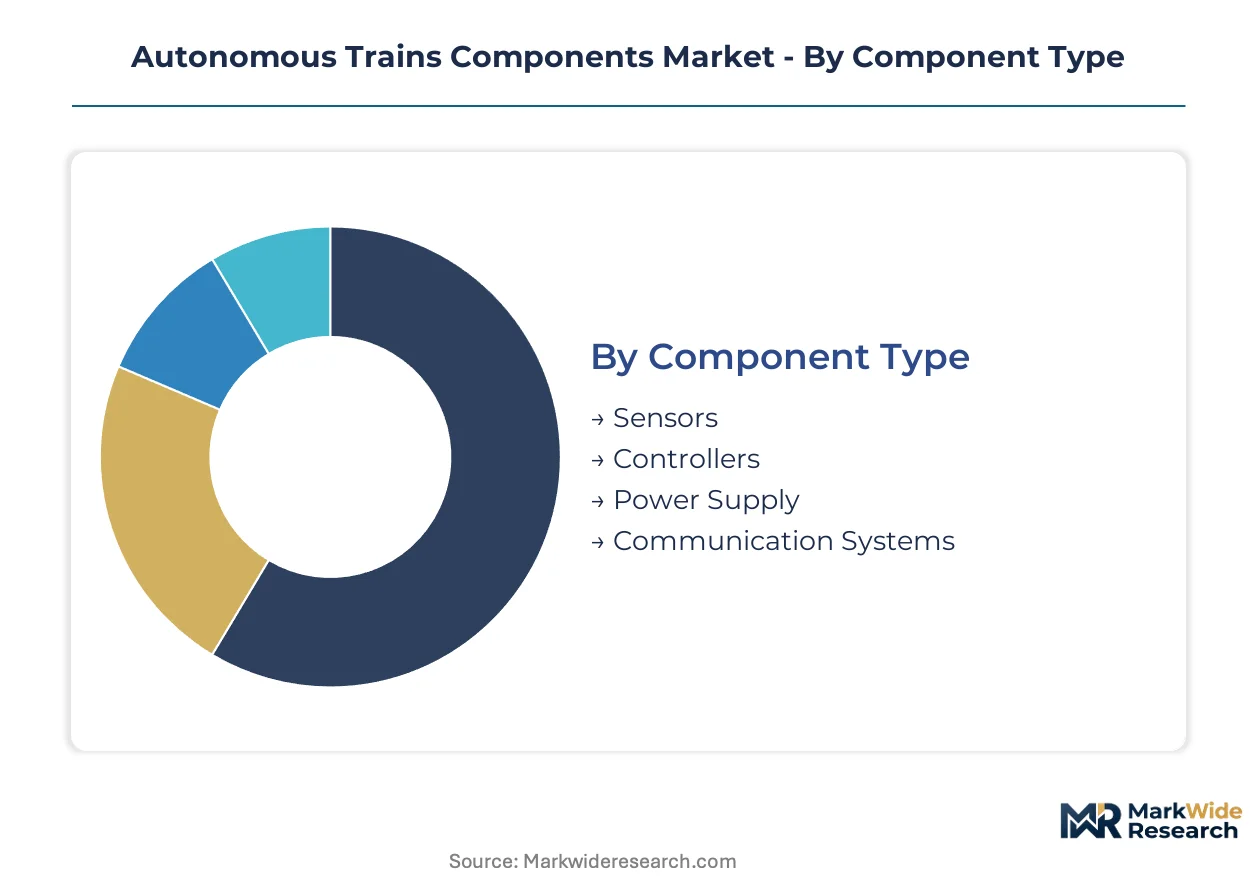
Procurement patterns for autonomous train components diverge sharply across technical specifications and buyer types. Component vendors must align certification pathways with the specific operational demands of each segment cluster.
Component Type:
Domestic production dominates sensors and controllers in China and Japan, while European networks import communication systems from specialized vendors.
- Sensors:Radar and lidar units with millimeter-wave precision form the perceptual backbone of obstacle detection. China's high-speed rail corridors and Japan's commuter networks are retrofitting legacy lines, triggering bulk procurement cycles for solid-state architectures.
- Communication Systems:Vehicle-to-infrastructure nodes operating at sub-50-millisecond latency govern train-to-track data exchange. ETSI harmonization mandates are forcing redesigns for cross-border interoperability, expanding validation scope and extending supplier qualification timelines.
- Controllers:Programmable logic controllers execute real-time decision algorithms for speed regulation and braking.
- Power Supply:Electrification subsystems deliver conditioned voltage to onboard automation electronics.
Sensors hold the largest share; momentum sits with communication systems.
Functionality:
Cost tiers separate navigation retrofits from safety system upgrades, with the latter commanding premium pricing due to Sil-4 certification requirements.
- Navigation:Positioning and route optimization modules enable grade-of-automation upgrades on brownfield infrastructure. Demand concentrates in Asia-Pacific metro densification projects where operators retrofit legacy lines without full corridor replacement.
- Safety Systems:Emergency braking and obstacle response mechanisms operate under the strictest functional safety standards. Validation-intensive development cycles consume 18-24 month timelines before revenue recognition, deepening margin pools for certified suppliers.
- Monitoring:Telemetry aggregation platforms feed predictive maintenance algorithms.
- Control:Speed regulation and traction management systems interface with propulsion hardware.
Safety systems command the deepest margins; navigation is climbing the fastest as retrofit demand accelerates.
Material:
Volume applications favor metal and plastic housings, while composite and electronic materials concentrate in high-performance subsystems.
- Metal:Structural enclosures and heat-dissipating chassis for onboard electronics. REACH compliance spillover in Europe is replacing legacy electromagnetic components with RoHS-aligned alternatives, opening replacement demand for compliant fabricators.
- Electronic Components:Gallium nitride substrates and silicon carbide power modules enable millimeter-wave radar and efficient power conversion. East Asian foundry concentration creates supply vulnerability for substrate fabrication.
- Composite:Lightweight housings for exterior-mounted sensor arrays.
- Plastic:Insulating enclosures and connector bodies for interior electronics.
Metal holds the largest share; electronic components are gaining share fastest.
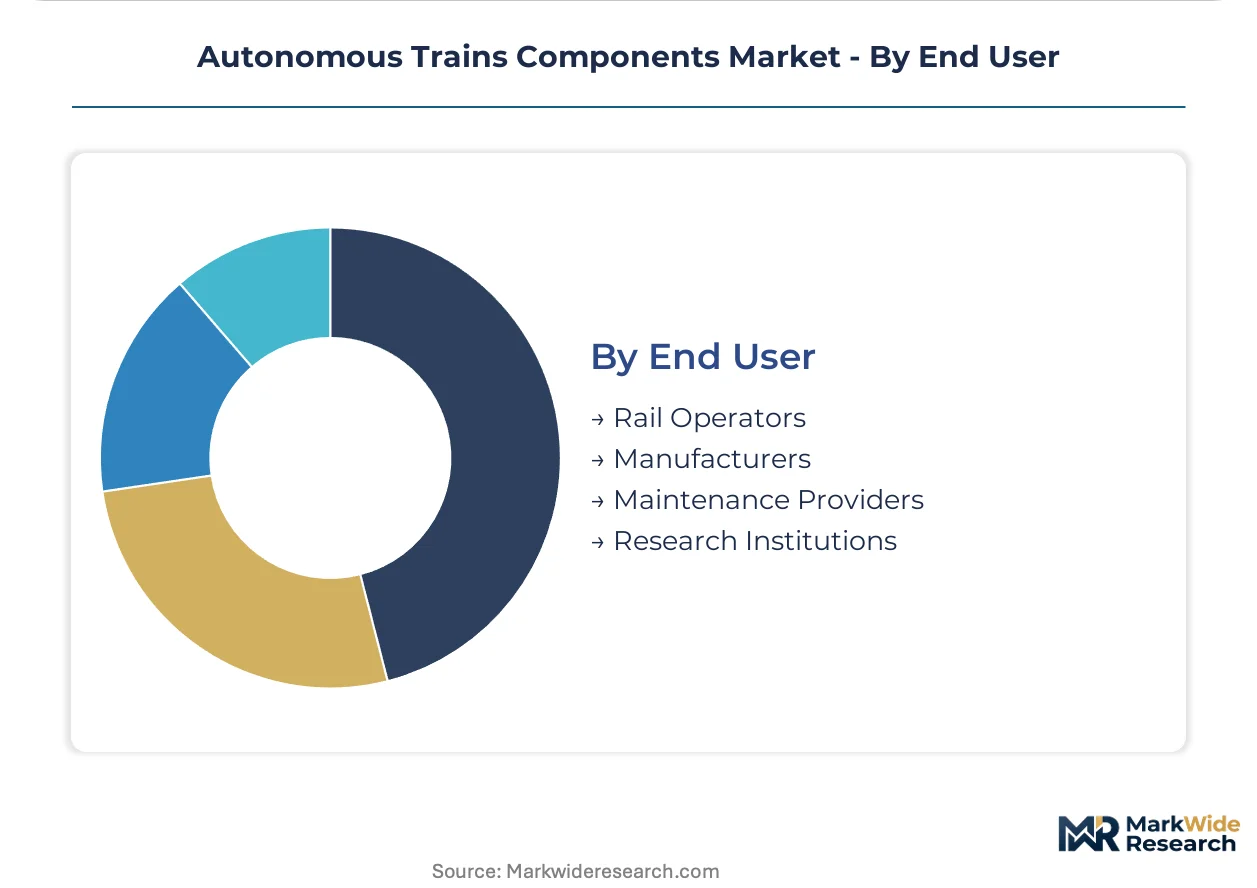
End User:
Rail operators and manufacturers split procurement authority, with maintenance providers emerging as a discrete channel for aftermarket sensor replacement.
- Rail Operators:Shanghai and Beijing metro modernization programs are unbundling component procurement from rolling stock OEM contracts, creating direct vendor relationships for sensor and communication module suppliers.
- Manufacturers:Rolling stock OEMs integrate automation subsystems during initial trainset assembly. Chinese state rail operators are shifting pricing power toward volume-consolidated operators through disintermediation.
- Maintenance Providers:Aftermarket service contractors replace degraded sensors and update firmware.
- Research Institutions:Testbed operators validate next-generation algorithms in controlled environments.
Rail operators hold the largest share; momentum sits with maintenance providers as installed base ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for gallium nitride substrates concentrates in Taiwan and South Korea, while rolling stock final assembly clusters in Germany, Japan, and China. Component vendors face divergent certification timelines across these jurisdictions. Procurement authority is shifting toward state rail operators in Asia and infrastructure managers in Europe.
Germany
Deutsche Bahn's Stuttgart-Ulm corridor and Munich S-Bahn modernization drive demand for Sil-4 certified controllers. The Common Safety Method regulation enforces harmonized EU safety standards through the European Union Agency for Railways. Siemens AG anchors engineering activity in Munich and Nuremberg, sustaining premium positioning on autonomous control modules.
China
High-speed rail corridors between Beijing, Shanghai, and Guangzhou are retrofitting legacy signaling for GoA4 operation. The NMPA-aligned railway regulator mandates domestic testing protocols that extend market access timelines for foreign suppliers. CRRC Corporation Limited and state metro operators in Shanghai and Beijing are unbundling component procurement from rolling stock contracts.
Japan
Tokyo Metro and JR East commuter networks deploy millimeter-wave vehicle-to-infrastructure nodes for 5G-Advanced backhaul. METI testing requirements govern market access for automation subsystems. Mitsubishi Electric Corporation and Kawasaki Heavy Industries concentrate development in Kanto and Kansai industrial corridors.
India
Mumbai Metro and Delhi MMRDA projects accelerate procurement of driverless train kits for brownfield retrofits. The CEA and BIS are formulating localized electromagnetic compatibility standards for metro automation. Siemens AG and Alstom SA compete for positioning as first-mover compliant vendors in the expanding South Asian market.
United States
Amtrak's Northeast Corridor and California High-Speed Rail Authority evaluate GoA2-to-GoA4 upgrade pathways. The Federal Railroad Administration oversees safety certification without mandating Sil-4 equivalence. Wabtec Corporation anchors signaling technology development in Pittsburgh and Chicago industrial clusters.
Autonomous Trains Components Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the autonomous trains components market. European incumbents command premium positioning on safety-certified controllers and signaling systems, while Asian fabricators dominate sensor volume production through scale-driven manufacturing. Three strategic archetypes define competitive positioning: integrated platform providers spanning rolling stock and infrastructure, specialized communication module vendors, and component suppliers disintermediated by operator direct procurement. Dominant competitive moves include backward integration into gallium nitride substrate sourcing and strategic partnerships with state rail operators for long-term maintenance contracts.
Within the integrated platform tier, Alstom SA and Siemens AG exemplify archetypes combining rolling stock heritage with automation subsystem development. Hitachi Ltd. occupies a position bridging Japanese domestic market density with international project execution. These three entities represent contrasting geographic anchors—French, German, and Japanese regulatory compliance expertise—while competing for GoA4 upgrade contracts across Asia-Pacific and European corridors. Thales Group and Mitsubishi Electric Corporation sit within the specialized signaling and electrical equipment tier, differentiated by TÜV certification depth versus cost-optimized volume production.
| Leading Market Players |
|---|
| Alstom SA |
| Thales Group |
| Siemens AG |
| Hitachi Ltd. |
| Wabtec Corporation |
| CRRC Corporation Limited |
| Mitsubishi Electric Corporation |
| Kawasaki Heavy Industries |
| Knorr-Bremse |
| Others |
Supply Flow & Price Mechanics
Solid-state lidar substitution for electromechanical scanning units is redrawing procurement geography toward East Asian foundries while compressing sensor pricing bands and elevating communication module premiums. This displacement concentrates margin capture among vendors with captive gallium nitride substrate access.
Pricing Analysis
SIL-4 certification dictates the pricing tier structure across autonomous train components, separating validated safety-critical controllers from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, volume scale, and after-sales service bundling. Pricing pressure stems from Chinese state rail operators unbundling procurement from rolling stock OEMs. Maintenance providers exhibit highest price sensitivity; integrated platform vendors face lowest.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates dominates inventory strategy given Taiwan and South Korea foundry concentration. East Asian fabrication draws from concentrated wafer supply, silicon carbide power modules, and millimeter-wave radar substrates. Single-source vulnerability pervades substrate tier. Distribution runs through rolling stock OEM channels and direct operator procurement in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates multi-year certification barriers that protect incumbent positions.
For Market Incumbents: Fortify certification portfolios through dual-framework maintenance for EU Common Safety Method and China's NMPA-aligned protocols. Deepen backward integration into gallium nitride substrate sourcing to offset East Asian foundry concentration. Expand predictive maintenance contract coverage to lock in recurring revenue streams. For New Entrants and Emerging Players: Differentiate on India metro automation retrofits where CEA and BIS electromagnetic compatibility standards remain under formulation. Target maintenance provider channels for aftermarket sensor replacement as installed base ages. Pursue digital twin convergence partnerships with physics-based simulation platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform providers with cross-border certification depth. Long-term viability hinges on regulatory jurisdiction breadth and captive substrate access. Watch for EU AI Act conformity assessment pathway clarifications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Sourcing | Captive gallium nitride supply insulates margin pressure from Taiwan foundry concentration. |
| Dual Certification Framework Investment | Parallel EU Common Safety Method and China NMPA validation accelerates multi-jurisdiction revenue. |
| Predictive Maintenance Platform Launch | Physics-based simulation fused with sensor telemetry creates recurring service contracts. |
| Direct Operator Procurement Partnership | Shanghai and Beijing metro disintermediation shifts pricing power toward volume-consolidated vendors. |
| Digital Twin Technology Acquisition | Real-time sensor telemetry integration enables condition-based monitoring contracts. |
Methodological Framework
A standing panel of signaling engineering directors, metro procurement officers, rail regulator technical leads, and component vendor product managers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against ETSI harmonization mandates, EU Agency for Railways safety directives, and national regulatory filings. Bottom-up component procurement data triangulated against top-down rolling stock delivery schedules.
External benchmark consistency checks validated volume and value outputs against rolling stock OEM production disclosures and state rail operator modernization program announcements. Segmentation modeling spanned component type, functionality dimension, grade-of-automation tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed procurement timelines and infrastructure investment pipelines.
The analysis sits within stated boundaries; outcomes outside sustained state rail capital expenditure commitments would require recalibration. Forecasts reflect assumptions regarding ETSI standardization adherence and substrate supply continuity. Revision becomes warranted when gallium nitride foundry utilization or certification timeline harmonization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
EV Connectors Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
EGR Coolers Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market