
 Steering Column Cowls Market | 2026-2036
Steering Column Cowls Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Column Cowls Market Analytics
Fleet operators and specialty vehicle modifiers are collapsing legacy procurement patterns toward modular, serviceable cowl designs. Thyssenkrupp AG sustains forged aluminum dominance through captive metallurgy capabilities in German production hubs. Johnson Controls International plc leverages polymer science partnerships to supply insulated cowl variants for electric vehicle thermal management. Adient plc anchors North American seating and cockpit integration through direct OEM channel control.
Steering column cowls are protective housings that enclose the upper steering shaft, ignition lock assembly, and column-mounted control stalks, typically injection-molded from glass-filled polypropylene or stamped from cold-rolled steel with corrosion-resistant coatings to meet 15-year durability cycles. Their primary purpose is to shield internal mechanisms from debris intrusion, absorb column-end impact energy, and provide aesthetic closure within the instrument panel architecture. Ribbed cowls dominate OEM fitments due to structural rigidity and mold-flow efficiency, while insulated cowls represent the fastest-expanding material segment as battery-electric platforms demand thermal isolation between cabin and power electronics. Composite materials are displacing conventional steel in premium applications where mass reduction targets intersect with NVH performance requirements.
NHTSA enforces FMVSS 114 steering lock and column displacement standards that dictate crush behavior and housing retention forces, while EPA material content rules affect recycled polymer sourcing for plastic cowl production. The EU Green Deal's circular economy mandates are beginning to shape export-bound supplier qualification criteria even for US-focused manufacturers. Stakeholders must monitor how FMVSS revision timelines and state-level right-to-repair legislation interact to determine whether aftermarket cowl demand shifts toward certified remanufactured units or unbranded replacement channels.
Market Dynamics
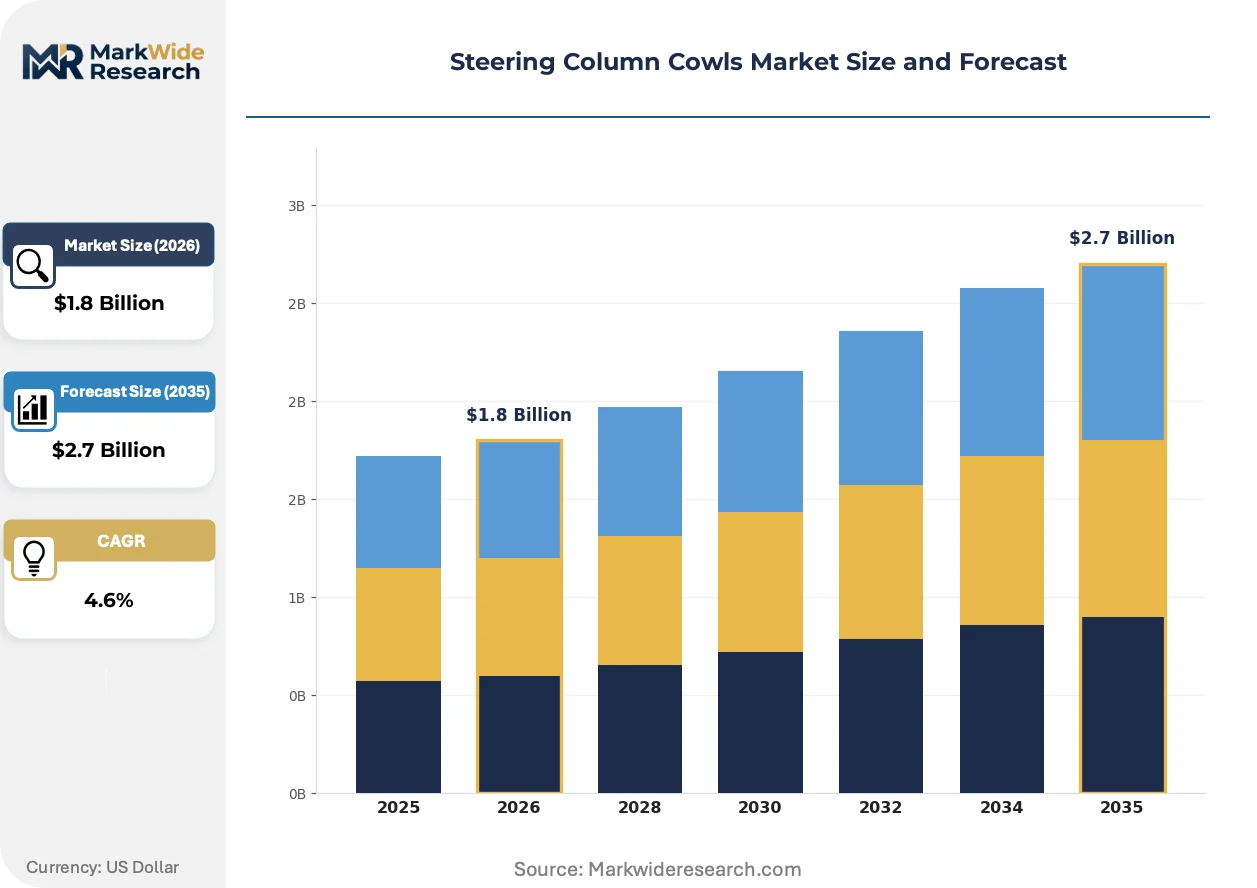
Fleet operators and specialty vehicle modifiers are collapsing legacy procurement patterns toward modular, serviceable cowl designs. NHTSA pedestrian safety standards and FMVSS 114 steering column integrity rules are tightening material specifications across all supply tiers.
Growth Catalysts
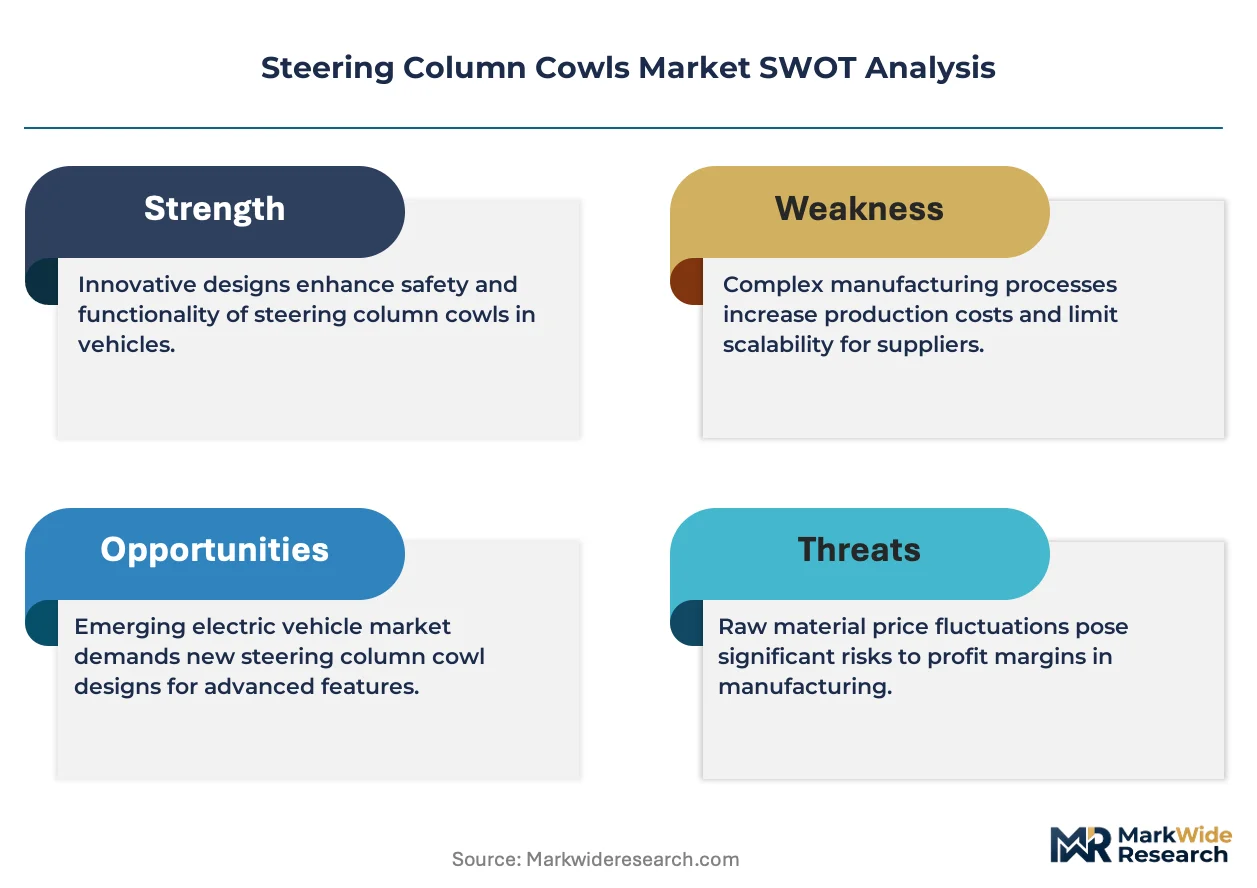
- FMVSS 114 Compliance:NHTSA mandates for steering column displacement and lock integrity are forcing OEMs to upgrade housing retention systems, creating sustained replacement demand across domestic vehicle platforms.
- Glass-Filled Polypropylene:Injection-molded ribbed cowls achieve 15-year durability cycles at lower mass than stamped steel, accelerating adoption in mass-market electric vehicle architectures.
- Detroit Supplier Cluster:Proximity to Ford, GM, and Stellantis engineering centers compresses prototype-to-production timelines for tier-1 cowl suppliers.
Market Restraints
- Resin Price Volatility:Polypropylene feedstock costs fluctuate with propylene monomer availability, squeezing margin structures for injection-molded cowl producers.
- German Metallurgy Concentration:Forged aluminum supply chains concentrate in Thyssenkrupp's captive Ruhr Valley facilities, creating single-source vulnerability for premium insulated variants.
- Thermal Management Complexity:Battery-electric platforms demand thermal isolation between cabin and power electronics, adding engineering validation cycles that extend time-to-revenue.
Strategic Opportunities
- California Specialty Corridor:Los Angeles and Bay Area vehicle modification shops generate unmet demand for certified remanufactured cowls compatible with vintage restoration projects.
- Right-to-Repair Legislation:State-level mandates in Massachusetts and expanding jurisdictions legitimize aftermarket channels, reducing OEM channel lock-in for replacement units.
- Polymer-Steel Hybrid Bonding:Advanced adhesive joining of composite shells to metal reinforcement structures enables NVH performance targets previously achievable only with monolithic steel stampings.
Industry Challenges
- Cross-Functional Talent Scarcity:Engineers possessing simultaneous expertise in polymer rheology, crash simulation, and thermal modeling command premium compensation that strains mid-tier supplier payrolls.
- Tooling Amortization Pressure:Multi-cavity injection molds for ribbed cowl variants require seven-figure capital commitments with payback periods extending across multiple vehicle generations.
- Dual Certification Burden:Suppliers serving both OEM and aftermarket channels must maintain parallel quality systems for ISO/TS 16949 and EPA recycled content verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Column Cowls Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ribbed Cowls, Smooth Cowls, Insulated Cowls, High-Temperature Cowls Material: Plastic, Aluminum, Steel, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Type: Fixed Mount, Adjustable Mount, Integrated Design, Standalone Unit |
| Companies Covered | SC Parts Group, DS Smith, Moss Motors, Brown and Gammons, Allon White Sports Cars, Adient plc, Johnson Controls International plc, Thyssenkrupp AG, DURA Automotive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Column Cowls Market Evolving Landscape
Steering column cowl architecture is converging around thermal management integration and modular serviceability. Three developments are compressing traditional design paradigms.
Multi-layer insulated cowl assemblies are miniaturizing thermal barrier thickness while maintaining R-value performance. Battery-electric vehicle manufacturers in Michigan and California are specifying these variants for 2027 platform launches. The technology is miniaturizing packaging envelopes previously reserved for HVAC ducting, freeing instrument panel volume for display integration.
EPA material content rules are tightening recycled polymer sourcing requirements for plastic cowl production. Suppliers must now document post-consumer resin percentages through chain-of-custody certification. Tier-1 manufacturers serving Detroit's OEM cluster are responding by qualifying domestic reprocessors capable of glass-filled polypropylene with consistent melt-flow indices.
Aftermarket procurement is fragmenting toward direct-to-modifier channels. Specialty vehicle shops in Texas and Arizona are bypassing traditional distributors to source cowl assemblies through manufacturer portals. This behavioral shift is most visible in the vintage truck restoration segment, where buyers prioritize specification transparency over brand affiliation.
Steering Column Cowls Market Segmentation
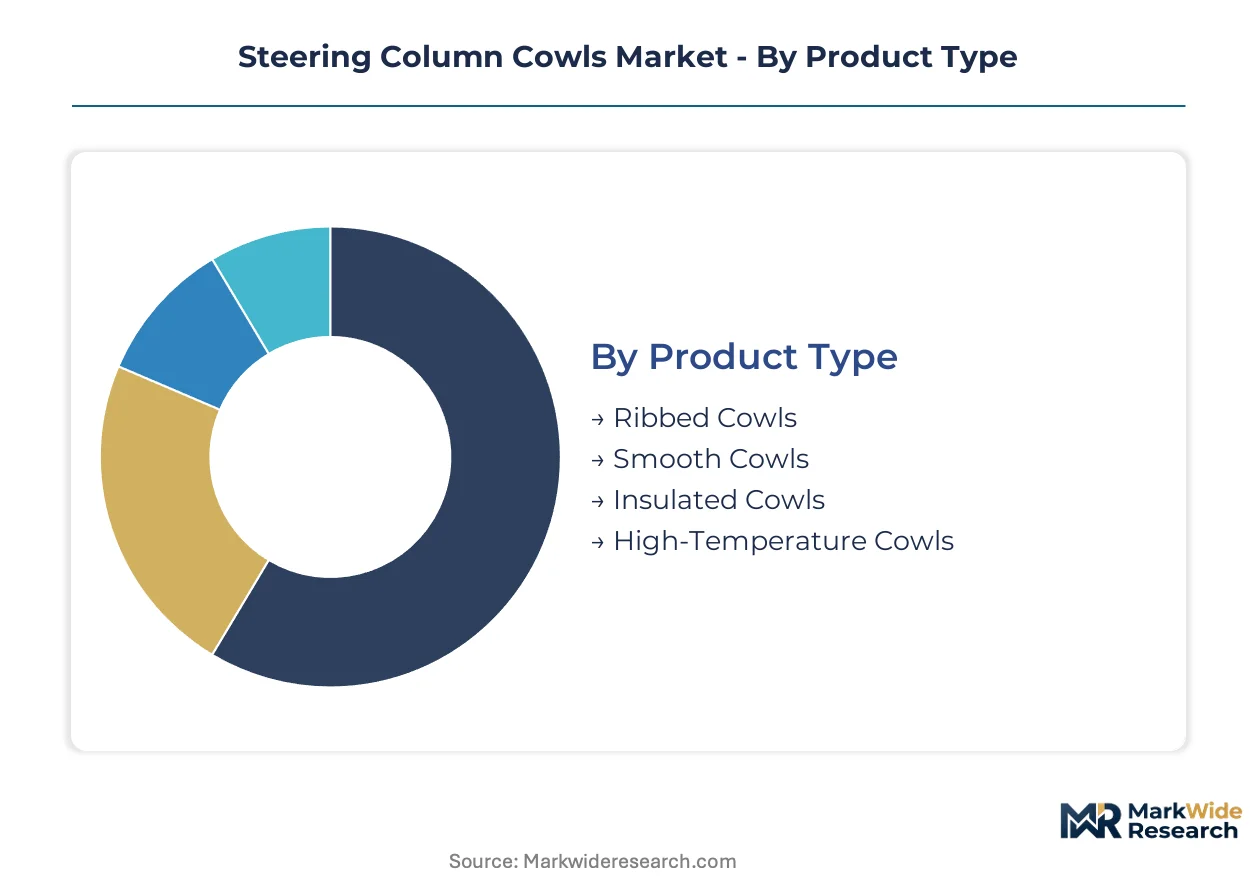
Steering column cowl procurement splits across thermal performance tiers and regulatory compliance grades, with material selection and installation geometry determining channel access. Fleet buyers prioritize serviceable designs while specialty modifiers demand specification transparency over brand affiliation.
Product Type:
Domestic OEM procurement concentrates on ribbed and insulated variants for FMVSS 114 compliance, while export demand tilts toward high-temperature cowls for tropical climate specifications.
- Ribbed Cowls:Injection-molded glass-filled polypropylene shells deliver structural rigidity through geometric reinforcement ribs. Detroit's supplier cluster dominates volume production for Ford, GM, and Stellantis platforms where 15-year durability cycles are mandatory. NHTSA pedestrian safety standards are tightening crush behavior specifications for these variants.
- Insulated Cowls:Multi-layer thermal barrier assemblies isolate cabin environments from battery-electric power electronics. California specialty vehicle corridors and Michigan EV engineering centers are specifying these for 2027 platform launches where packaging envelope reduction is critical. The segment is climbing the fastest as thermal management complexity spreads across electric architectures.
- Smooth Cowls:Aesthetic-focused variants prioritize instrument panel visual integration over structural optimization.
- High-Temperature Cowls:Heat-resistant formulations serve Middle Eastern and Southeast Asian export markets with extreme ambient operating conditions.
Ribbed cowls hold the largest share; momentum sits with insulated cowls.
Material:
Cost tiers separate mass-market polymer solutions from premium metallurgy, with composite hybrids occupying a narrowing middle ground.
- Plastic:Glass-filled polypropylene dominates mass-market production through lower mass and mold-flow efficiency. EPA recycled content rules are forcing domestic reprocessor qualification for post-consumer resin documentation.
- Aluminum:Forged variants from German metallurgy hubs supply premium insulated cowls where thermal conductivity control is paramount.
- Steel:Cold-rolled stampings with corrosion-resistant coatings retain share in heavy-duty commercial applications.
- Composite:Polymer-steel hybrid bonding enables NVH targets previously requiring monolithic steel, though tooling amortization pressures constrain mid-tier supplier adoption.
Plastic commands volume leadership; aluminum is gaining share fastest in premium thermal management applications.
End User:
Channel control patterns diverge between captive OEM supply and fragmented aftermarket procurement.
- OEMs:Direct engineering relationships with tier-1 suppliers compress prototype-to-production timelines. FMVSS 114 compliance mandates create sustained replacement demand across domestic vehicle platforms.
- Aftermarket Providers:Restoration specialists and specialty modifiers are collapsing legacy distributor relationships toward manufacturer-direct portals. California and Texas vintage truck segments prioritize specification transparency.
- Tier-1 Suppliers:Channel intermediaries maintain ISO/TS 16949 quality systems for OEM-facing production.
- Vehicle Assemblers:Contract manufacturers source cowl assemblies as part of integrated cockpit modules.
OEMs retain the largest share; aftermarket providers are expanding most quickly through right-to-repair legislation.
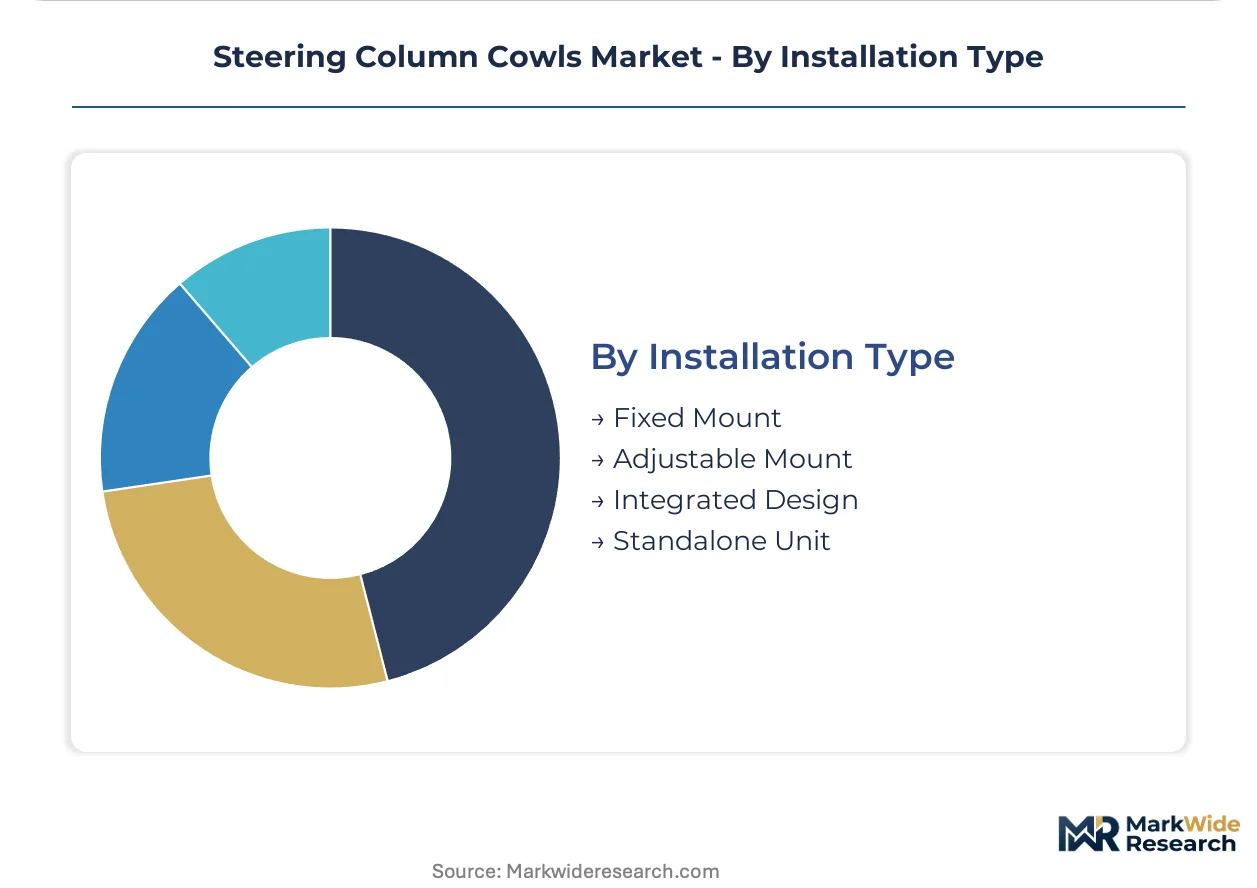
Installation Type:
Serviceability requirements are shifting procurement toward modular geometries that reduce labor time.
- Fixed Mount:Permanent attachment structures dominate legacy platforms where column replacement frequency is low.
- Adjustable Mount:Position-flexible designs accommodate steering column tilt and telescoping functions.
- Integrated Design:Cowl-instrument panel fusion reduces part count and assembly labor for high-volume production.
- Standalone Unit:Serviceable modular assemblies enable rapid replacement without dashboard disassembly, appealing to fleet operators.
Integrated design holds the largest share; standalone unit configurations are gaining share fastest among fleet and commercial operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor rail tunnel and Ambassador Bridge corridor underwrites North American automotive supplier integration, while German metallurgy clusters leverage Rhine-Ruhr barge networks for raw material throughput. These infrastructure assets anchor continental production gravity for steering column cowl manufacturing.
United States
Ford, GM, and Stellantis engineering centers in Michigan generate concentrated OEM demand for FMVSS 114-compliant ribbed variants. NHTSA pedestrian safety standards are tightening crush behavior specifications for 2027 platform launches. The Detroit supplier cluster compresses prototype-to-production timelines through direct tier-1 relationships.
Germany
Ruhr Valley captive metallurgy capabilities supply forged aluminum for premium insulated cowl architectures. REACH chemical registration requirements constrain polymer formulation choices for export-bound production. Thyssenkrupp's Essen and Dortmund facilities maintain single-source dominance for thermal conductivity-controlled variants.
China
Yangtze River Delta EV manufacturers are specifying multi-layer insulated cowls for 2028 battery-electric platforms. MIIT new energy vehicle mandates accelerate thermal management component localization. Shanghai and Ningbo injection molding clusters are qualifying domestic glass-filled polypropylene reprocessors.
Japan
Kansai region precision polymer processors serve Toyota and Honda cockpit integration programs. METI carbon neutrality roadmaps are pressuring resin sourcing toward bio-based feedstocks. Osaka-based moldmakers are shrinking thermal barrier thickness while maintaining R-value performance targets.
Mexico
Bajío Region assembly plants for export-bound US platforms generate pull-through demand for stamped steel cowl variants. USMCA rules of origin compliance shapes supplier qualification criteria for cross-border tier-1 relationships. Querétaro and Guanajuato logistics corridors enable just-in-sequence delivery to Texas and California modification shops.
Steering Column Cowls Market Competitive Landscape
Concentration sits with diversified automotive component conglomerates and captive metallurgy specialists. The vendor base stratifies across three tiers: global tier-1 integrators with direct OEM channel control, regional polymer processors serving aftermarket modification corridors, and specialty restoration suppliers targeting vintage vehicle refurbishment. Dominant competitive moves include backward integration into resin compounding capabilities and strategic partnerships with domestic reprocessors for EPA recycled content compliance.
Among diversified automotive suppliers, Thyssenkrupp AG exemplifies the captive metallurgy archetype through Ruhr Valley production concentration. Johnson Controls International plc and Adient plc occupy positions within the tier-1 integrator tier, leveraging polymer science partnerships and direct OEM engineering relationships respectively. These three entities anchor the competitive structure through differentiated material capabilities and channel control patterns.
| Leading Market Players |
|---|
| SC Parts Group |
| DS Smith |
| Moss Motors |
| Brown and Gammons |
| Allon White Sports Cars |
| Adient plc |
| Johnson Controls International plc |
| Thyssenkrupp AG |
| DURA Automotive Systems |
| Others |
Value Network & Pricing Analysis
Glass-filled polypropylene substitution for cold-rolled steel stampings is redrawing procurement geography toward Yangtze River Delta injection molding clusters while compressing per-unit economics for mass-market ribbed variants. This material migration simultaneously elevates resin price volatility exposure and fragments legacy metallurgy-dependent supply relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FMVSS 114-certified OEM supply from aftermarket remanufactured units and unbranded replacement channels. Price differentiation hinges on certification grade and volume scale, with fleet procurement commanding favorable terms through multi-year offtake commitments. Pricing pressure stems from propylene monomer cost swings squeezing margin structures for injection-molded producers. Aftermarket modifiers exhibit highest price sensitivity, while captive OEM channels absorb premium positioning for integrated cockpit modules.
Supply Chain Analysis
Ruhr Valley captive aluminum smelting capacity constitutes a chokepoint for premium insulated cowl architectures serving battery-electric thermal management applications. Raw material flows draw from German metallurgy hubs, Michigan polymer compounding facilities, and Shanghai glass-filled polypropylene reprocessors. Single-source vulnerability concentrates in Thyssenkrupp's Essen-Dortmund corridor for forged aluminum variants. Distribution runs through Detroit-Windsor rail tunnel corridors for just-in-sequence OEM delivery and direct-to-modifier portals for aftermarket fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation and specialty vehicle modifier direct-procurement behavior are shifting buyer power toward volume aggregators and specification-transparent channels.
For Market Incumbents: Fortify backward integration into domestic resin compounding capabilities to buffer propylene monomer volatility and satisfy EPA recycled content documentation requirements. Deepen captive metallurgy control over Ruhr Valley aluminum supply relationships to defend premium insulated cowl positioning against emerging polymer-steel hybrid challengers. Prioritize ISO/TS 16949 certification maintenance for dual OEM-aftermarket channel access. For New Entrants and Emerging Players: Differentiate on California specialty vehicle corridor access by qualifying certified remanufactured cowl production for vintage restoration demand. Target Texas and Arizona modification shops with manufacturer-direct portal capabilities that bypass legacy distributor markups. Penetrate the standalone unit installation segment through modular serviceable designs appealing to commercial fleet operators. For Investors and Strategic Acquirers: The market sits at a compliance-driven upgrade phase that favors polymer science specialists with EPA chain-of-custody certification and thermal management engineering depth. Long-term viability over a multi-year horizon rests on electric vehicle platform thermal isolation content expansion. Signal to monitor: NHTSA FMVSS 114 revision timelines and state-level right-to-repair legislative momentum as aftermarket channel legitimacy inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene formulation control buffers Thyssenkrupp-dependent aluminum supply vulnerability for tier-1 suppliers. |
| Direct-to-Modifier Portal Development | Bypassing traditional distributors captures margin from California and Texas vintage truck restoration procurement shifts. |
| Multi-Layer Thermal Barrier Miniaturization | R-value maintenance at reduced thickness opens instrument panel volume for display integration in Michigan EV platforms. |
| EPA Recycled Content Certification Investment | Chain-of-custody documentation unlocks OEM qualification for Detroit cluster glass-filled polypropylene demand. |
| Polymer-Steel Hybrid Bonding Capability | Advanced adhesive joining enables NVH targets previously requiring monolithic steel stampings in premium applications. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and specialty vehicle modification shop owners provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation through NHTSA FMVSS documentation, EPA material content rulemakings, vehicle production databases, and customs trade records. Bottom-up segment sizing triangulated against top-down market boundary checks.
Consistency checks validated volume and value outputs against external automotive component production benchmarks and regional registration data. The analytical framework modeled segmentation across propulsion architecture, thermal performance tier, material grade, and channel structure throughout the forecast period. CAGRs derived from installed base replacement cycles, platform launch schedules, and regulatory compliance mandate timelines. Industry-specific inputs included glass-filled polypropylene durability testing protocols and FMVSS 114 crush behavior specification evolution.
The analysis sits within stated boundaries; outcomes outside NHTSA regulatory revision timelines or propylene monomer supply stability would require recalibration. Forecasts reflect assumptions around electric vehicle platform thermal management content expansion and state-level right-to-repair legislative adoption patterns. Practitioners should keep alternative scenarios live as resin price volatility and German metallurgy concentration risk evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Anchorage Connector Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Global Motorcycle Chain Sprocket Market