
 Automotive Sensors Market | 2026-2036
Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sensors Market Analysis
Electric vehicle powertrain architectures is restructuring demand across the Automotive Sensors Market as thermal management and battery monitoring multiply sensor node requirements. Robert Bosch GmbH leverages its manufacturing scale to dominate pressure and temperature sensor supply for European OEMs. Continental AG anchors its position through in-house MEMS fabrication and radar module integration. Denso Corporation specializes in powertrain-specific speed and position sensors for hybrid platforms.
Automotive sensors are electromechanical or solid-state transducers that convert physical variables—pressure, temperature, proximity, acceleration, or rotational speed—into electrical signals with specified accuracy ranges, typically operating across temperature extremes from minus forty to one hundred fifty degrees Celsius for underhood deployment. These devices enable closed-loop control of engine combustion, occupant protection triggering, and environmental perception for assisted driving. Pressure sensors occupy mature, high-volume positions in engine management and tire monitoring, while radar and optical technologies capture expanding margin pools in safety systems. MEMS fabrication processes now underpin cost reduction across proximity and speed sensor categories, displacing legacy electromechanical designs in new vehicle programs.
NHTSA mandates in the United States, ECE regulations administered by UNECE in Europe, and China's GB standards enforced by MIIT collectively dictate functional safety thresholds, electromagnetic compatibility, and environmental durability for sensor certification. These frameworks elevate R&D barriers for entrants while creating specification premiums for suppliers achieving ASIL-D ratings under ISO 26262. Stakeholders must monitor how software-defined vehicle architectures shift value from discrete hardware toward sensor fusion platforms and embedded AI inference.
Market Dynamics
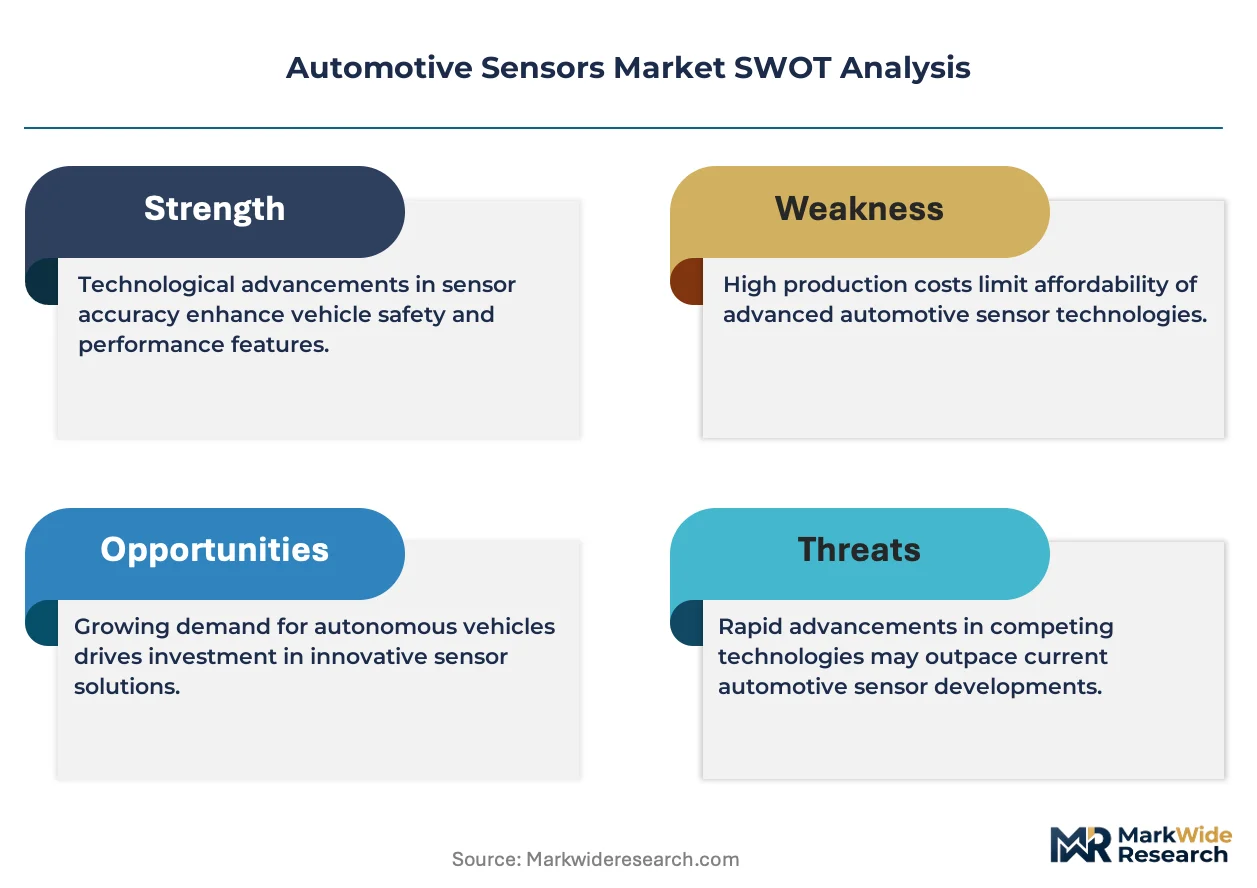
Sensor fusion architectures are compressing hardware margins while elevating software and calibration value in the Automotive Sensors Market. Tier-1 suppliers now compete on algorithm integration rather than discrete component specifications alone.
Growth Catalysts
- UN R155 cybersecurity mandates:Vehicle-type approval now requires intrusion detection sensors and secure over-the-air update mechanisms, expanding sensor counts per platform.
- Battery electric vehicle thermal runaway prevention:Cell-level temperature and pressure monitoring adds 15-40 additional sensor nodes per high-voltage pack.
- Silicon carbide power electronics:Wide-bandgap semiconductors operate at higher temperatures, demanding upgraded temperature sensing with faster response loops.
Market Restraints
- MEMS foundry concentration:Taiwan and Germany host the majority of automotive-grade MEMS capacity, creating geographic supply risk during regional disruptions.
- Raw material cost volatility:Palladium and rhodium price swings in exhaust gas sensors compress margin predictability for oxygen sensor manufacturers.
- Functional safety certification burden:ISO 26262 ASIL-D validation timelines extend 18-24 months, delaying new entrant market access.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle component localization create captive demand for domestic sensor assembly.
- Lidar-vision fusion platforms:Converging optical and time-of-flight technologies enable redundant perception stacks without full sensor duplication.
- Direct-to-OEM sensor module supply:Bypassing traditional Tier-1 integrators through software-defined vehicle architectures opens margin capture for specialized vendors.
Industry Challenges
- Embedded systems cybersecurity expertise:Shortage of engineers qualified in both hardware design and secure coding practices delays product release cycles.
- Legacy vehicle bus integration:CAN-FD and Ethernet coexistence requirements complicate backward compatibility for new sensor generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sensors Market |
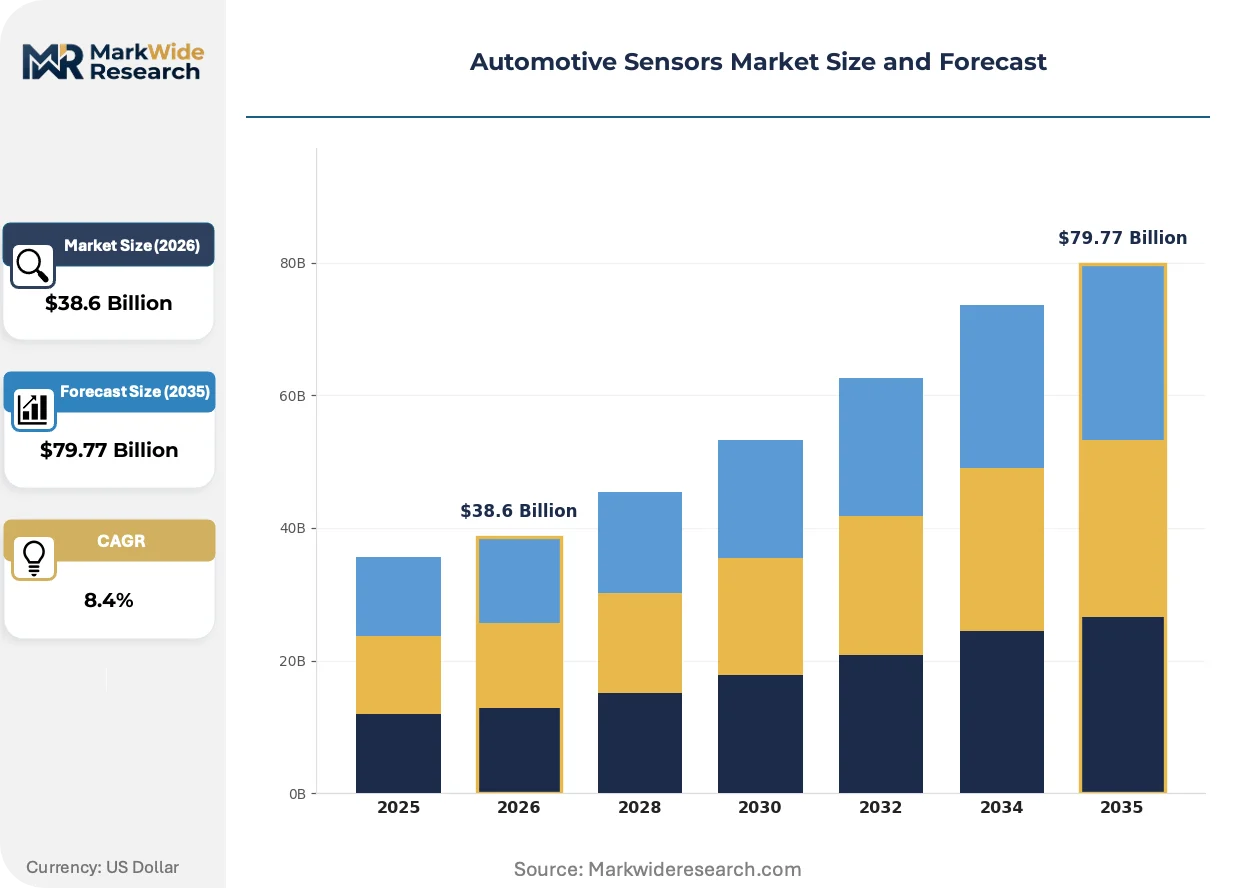
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Speed Sensors Technology: MEMS, Optical, Radar, Ultrasonic Application: Engine Management, Safety Systems, Navigation, Infotainment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, TE Connectivity, Sensata Technologies, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sensors Market Emerging Trajectories
Software-defined vehicle platforms are decoupling sensor hardware from control logic, enabling over-the-air performance updates and subscription-based feature activation.
Solid-state LiDAR is automating environmental perception for highway pilot systems. OEMs in Germany and the United States are qualifying these devices for SAE Level 3 conditional automation. The technology is automating the transition from mechanical scanning to chip-scale photonic integration, collapsing unit costs toward mass-market viability.
REACH substance restrictions are phasing cadmium and lead from certain sensor housings and solder applications. European suppliers must reformulate material compositions and revalidate thermal cycling performance. Pressure sensor manufacturers serving brake and HVAC applications face the most aggressive substitution timelines under the 2024 delegated act amendments.
Fleet operators and mobility service providers now specify sensor durability and calibration intervals in total-cost-of-ownership contracts rather than upfront hardware pricing. This procurement model shift favors suppliers offering predictive maintenance analytics and remote diagnostic capabilities. The transformation is most visible in North American commercial vehicle and ride-hail vehicle segments where uptime guarantees dominate sourcing decisions.
Automotive Sensors Market Segmentation
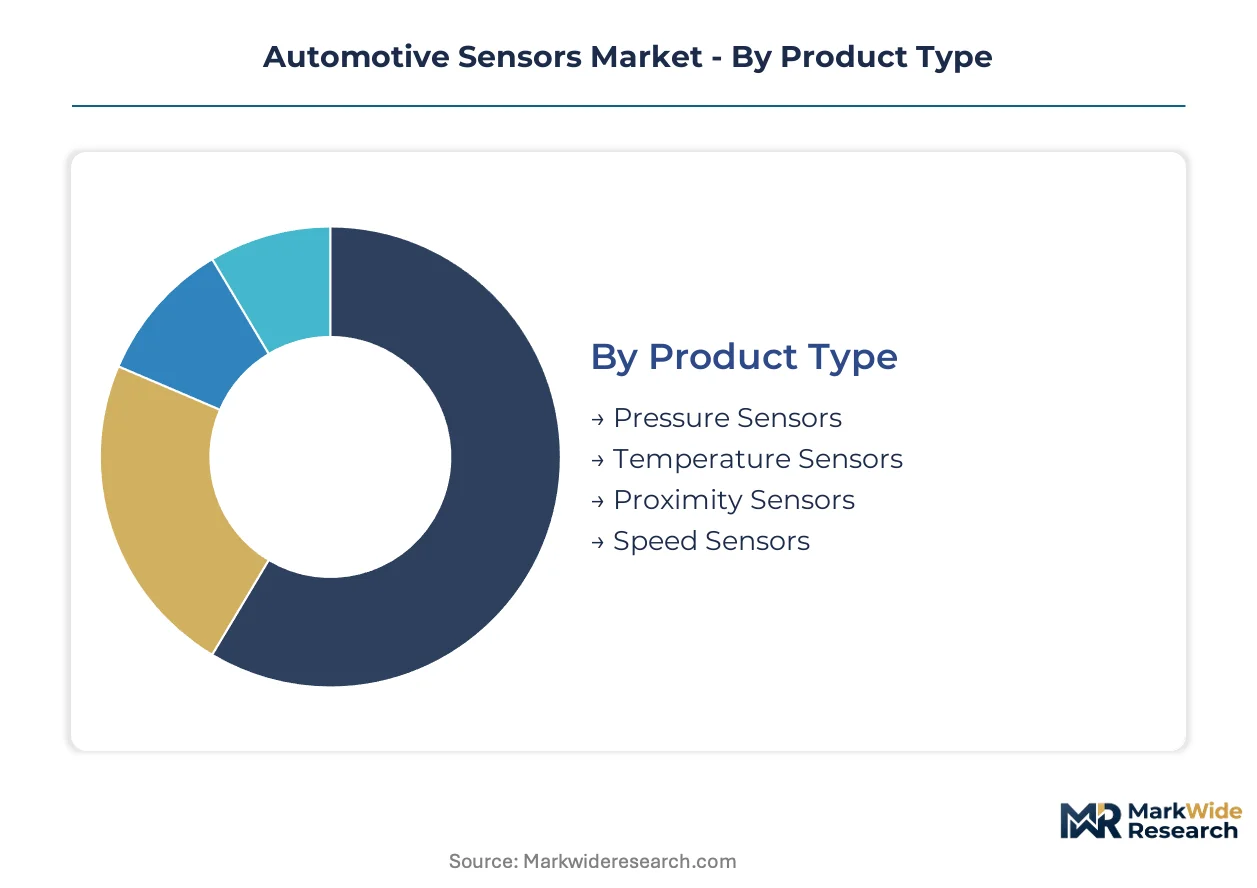
Automotive sensor procurement diverges sharply across buyer types, with OEMs prioritizing ASIL-D certification and Tier-1 integrators optimizing for fusion-platform compatibility. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization pressures bite hardest.
Product Type:
Buyers in this category separate by thermal exposure tolerance and signal accuracy requirements rather than unit economics alone.
- Pressure Sensors:Piezoresistive or capacitive transducers measure fluid and gas pressure across engine intake, brake hydraulic, and tire monitoring systems. Mature MEMS fabrication in Germany and Taiwan supplies high-volume programs for combustion engine management, though electric vehicle thermal management is opening new specification tiers.
- Temperature Sensors:Thermistors, RTDs, and thermocouples track thermal states from battery cells to exhaust streams. Demand concentrates in battery electric vehicle battery management systems where cell-level monitoring adds 15-40 nodes per pack, with NTC thermistors dominating cost-sensitive applications.
- Proximity Sensors:Capacitive and inductive devices detect object presence for parking assistance and gesture control interfaces.
- Speed Sensors:Hall-effect and magnetoresistive variants measure rotational velocity for powertrain control and anti-lock braking systems.
Volume sits with pressure sensors; growth tilts toward temperature sensors.
Technology:
Technology selection tracks the trade-off between unit cost and environmental perception fidelity demanded by target automation levels.
- MEMS:Microelectromechanical systems integrate mechanical elements with electronics on silicon substrates, enabling miniaturized accelerometers, gyroscopes, and pressure transducers. Taiwan Semiconductor Manufacturing and Robert Bosch operate the dominant automotive-grade foundry capacity, with supply concentration creating geographic risk during regional disruptions.
- Optical:CMOS image sensors and time-of-flight cameras capture visual data for lane keeping and traffic sign recognition. Solid-state LiDAR variants are collapsing unit costs toward mass-market viability as German and United States OEMs qualify devices for SAE Level 3 conditional automation.
- Radar:Frequency-modulated continuous-wave and pulse-Doppler systems provide all-weather velocity and range detection for adaptive cruise control.
- Ultrasonic:Piezoelectric transducers emit high-frequency sound pulses for short-range parking assistance and blind-spot monitoring.
MEMS dominates unit shipments; optical climbs the fastest on autonomous driving sensor fusion requirements.
Application:
Application segmentation reflects the migration from mechanical control systems toward software-defined vehicle architectures.
- Engine Management:Sensors monitor combustion parameters, air-fuel ratios, and exhaust composition for powertrain optimization. Demand is shifting toward hybrid and range-extender platforms where thermal cycling durability requirements exceed conventional internal combustion specifications.
- Safety Systems:Crash detection, occupant classification, and autonomous emergency braking rely on redundant sensor arrays. NHTSA and Euro NCAP protocols now mandate redundant sensing architectures, expanding node counts per vehicle platform.
- Navigation:GNSS receivers, magnetometers, and inertial measurement units enable positioning and heading determination.
- Infotainment:Touch, gesture, and ambient light sensors enhance human-machine interface responsiveness.
Engine management holds installed base; safety systems gain share fastest on regulatory mandate expansion.
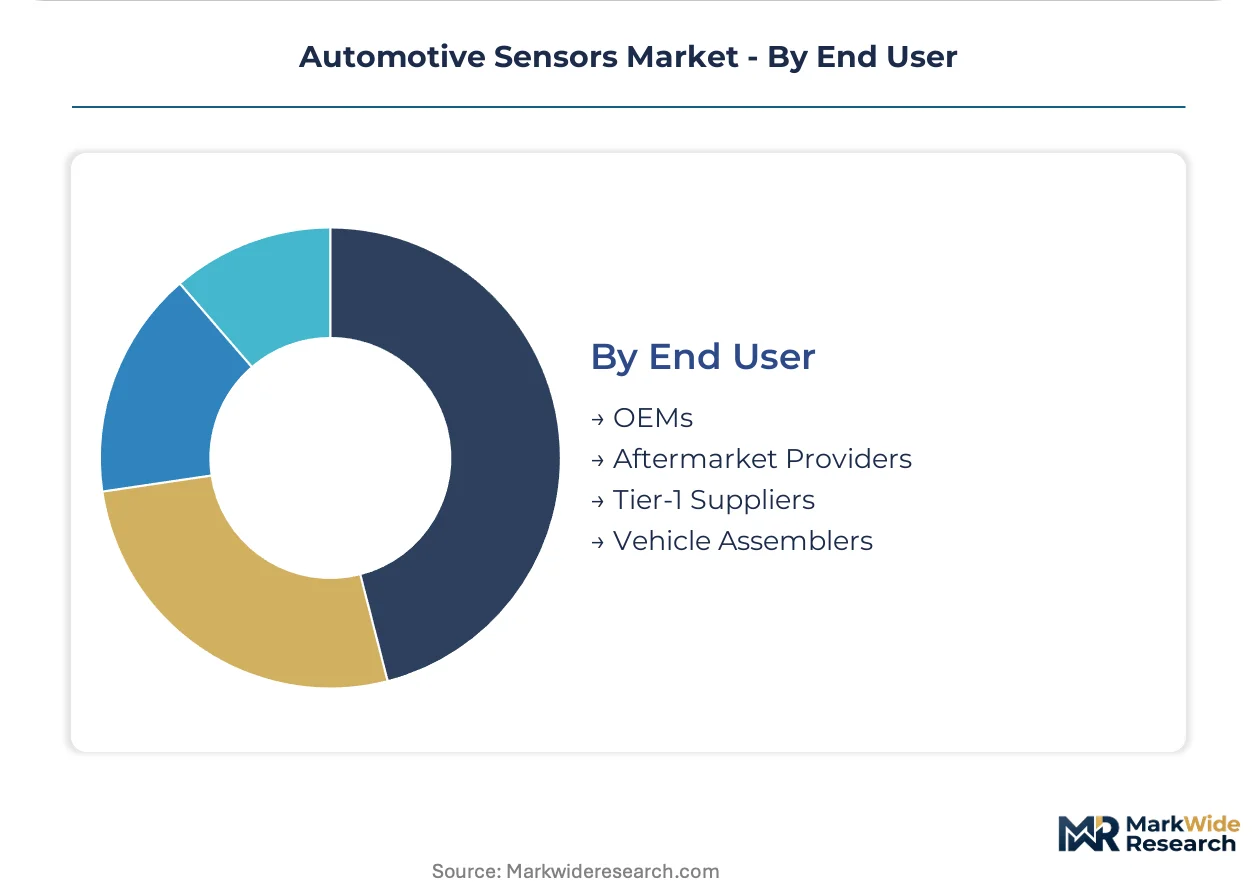
End User:
End-user differentiation centers on integration depth, with direct OEM relationships commanding specification influence that Tier-1 intermediaries cannot match.
- OEMs:Vehicle manufacturers source strategic sensor categories directly, particularly for software-defined vehicle architectures where hardware-software decoupling enables over-the-air performance updates. Direct procurement is expanding for LiDAR and radar modules as OEMs internalize perception stack development.
- Aftermarket Providers:Independent distributors and service networks supply replacement sensors for collision repair and performance upgrades. Fleet operators in North American commercial vehicle segments now specify durability and calibration intervals in total-cost-of-ownership contracts.
- Tier-1 Suppliers:System integrators combine discrete sensors into module-level solutions for OEM customers.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure sensor modules for localized production programs.
Volume flows through Tier-1 suppliers; margin capture is shifting toward OEM direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Lingang New Area in Shanghai concentrates LiDAR module fabrication capacity through tax holidays and customs duty exemptions for imported photonics equipment. This special economic zone anchors the highest density of automotive sensor foundry investments globally.
China
Domestic electric vehicle brands drive cell-level temperature sensor procurement for battery management systems. MIIT enforces GB standards for functional safety certification that elevate ASIL-D compliance costs for foreign entrants. Shenzhen and Suzhou industrial clusters host MEMS fabrication facilities serving both local OEMs and export markets.
Germany
Premium OEM platform architectures demand redundant radar and optical sensor arrays for SAE Level 3 automation. KBA administers UNECE ECE regulations that mandate electromagnetic compatibility testing for all active safety sensors. Stuttgart and Ingolstadt anchor radar module integration facilities supplying Volkswagen Group and BMW production networks.
United States
Commercial fleet operators specify predictive maintenance analytics in total-cost-of-ownership contracts for sensor durability. NHTSA crash-testing protocols now require redundant sensing architectures for autonomous emergency braking compliance. Michigan and Tennessee production corridors concentrate Tier-1 module assembly operations serving Detroit Three OEMs.
Japan
Hybrid powertrain platforms sustain demand for precision speed and position sensors with extended thermal cycling durability. METI coordinates JIS standards alignment with ISO 26262 for automotive semiconductor certification. Aichi Prefecture hosts integrated MEMS fabrication and powertrain sensor assembly serving Toyota and Honda supply chains.
India
PLI scheme incentives for electric vehicle component localization create captive demand for domestic sensor module assembly. BIS mandates country-specific testing protocols that extend certification timelines for imported devices. Tamil Nadu and Gujarat automotive corridors attract foreign sensor vendors establishing captive assembly operations for export to Southeast Asian markets.
Automotive Sensors Market Vendor Landscape
Top-tier vendors anchor high-volume MEMS and radar supply, while mid-scale specialists occupy niche calibration and fusion-platform segments. The market exhibits tiered concentration with three to five integrated conglomerates commanding pressure and temperature sensor categories. Strategic archetypes include diversified industrial conglomerates with captive semiconductor fabrication, pure-play sensor specialists with deep OEM relationships, and fabless design houses licensing fusion algorithms. Capacity expansion in Taiwan and Germany MEMS foundries dominates competitive moves, alongside strategic partnerships between LiDAR developers and Tier-1 integrators.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify integrated players with in-house MEMS fabrication capabilities. Denso Corporation occupies a position representing Japanese keiretsu-affiliated suppliers with deep powertrain sensor specialization. These three entities anchor distinct geographic supply strategies while competing on ASIL-D certification breadth and OEM direct relationship depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| TE Connectivity |
| Sensata Technologies |
| Analog Devices |
| Others |
Supply Flow & Price Mechanics
Palladium and rhodium feedstock costs cascade through exhaust gas sensor pricing tiers, with ASIL-D certified modules commanding premiums over standard-grade equivalents as OEMs absorb certification-driven margin compression. Contract manufacturers in Taiwan and Germany transmit foundry capacity constraints into tiered quotations that separate long-term offtake agreements from spot-market transactions.
Pricing Analysis
Lead-time-driven pricing stratification separates premium-quoted expedited delivery from discounted spot inventory releases when MEMS foundry capacity loosens. Three-tier pricing structure across premium, standard, and economy levels tracks ASIL-D certification breadth and thermal cycling durability specifications. Cost compression in proximity sensor categories intensifies as MEMS fabrication displaces legacy electromechanical designs. Fleet operators in North American commercial vehicle segments exhibit lowest price sensitivity due to total-cost-of-ownership contracting models.
Supply Chain Analysis
Dual-sourcing requirements mandated by German KBA and United States NHTSA protocols force OEMs to qualify secondary MEMS foundries alongside primary Taiwan Semiconductor Manufacturing and Robert Bosch fabrication lines. Taiwan, Germany, and Japan anchor automotive-grade MEMS capacity while China concentrates LiDAR module integration. Supply chains draw from palladium, rhodium, and silicon carbide substrates with single-source vulnerability concentrated in specialty photonics equipment. Tariff exposure on imported photonics equipment shapes Lingang New Area investment decisions. Distribution runs through Tier-1 integrators for volume programs while OEM direct procurement expands for software-defined vehicle architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive sensor market consolidation accelerates as ISO 26262 ASIL-D certification timelines extend 18-24 months, forcing capital-constrained specialists toward acquisition or exit.
For Market Incumbents: Anchor market position through captive MEMS fabrication expansion in Taiwan and Germany while deepening OEM direct relationships for LiDAR and radar module supply. Threat from fabless design houses licensing fusion algorithms demands accelerated software-embedded AI investment. Certification breadth serves as the defensive lever against emerging entrants lacking validation infrastructure. For New Entrants and Emerging Players: Tier-1 integrators seeking second-source qualification represent the most penetrable channel pathway for specialized temperature sensor vendors targeting battery electric vehicle thermal management. White-space concentrates in India PLI scheme localization requirements and solid-state LiDAR calibration services for SAE Level 3 platforms. Direct-to-OEM sensor module supply bypassing traditional integrators offers margin capture in software-defined vehicle architectures. For Investors and Strategic Acquirers: ASIL-D certification backlog expansion is the leading indicator that valuation premiums will concentrate among validated suppliers with OEM direct relationships. Five-to-ten year viability favors acquisition targets possessing in-house MEMS fabrication and redundant customer qualification across multiple OEM platforms. Watch for Tier-1 supplier margin compression signals as software-defined architectures shift value toward sensor fusion platforms.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Taiwan and Germany investments by Robert Bosch and TSMC secure supply for electric vehicle sensor node proliferation. |
| Software-Defined Vehicle Investment | OEM internalization of perception stack development bypasses Tier-1 integrators for LiDAR and radar procurement. |
| ASIL-D Certification Acceleration | ISO 26262 validation timeline compression creates competitive moat against capital-constrained entrants. |
| Battery Supply Agreement | Cell-level temperature sensor contracts with electric vehicle OEMs lock in 15-40 node per pack specifications. |
| Geographic Manufacturing Footprint | India PLI scheme and China Lingang tax incentives localize assembly for regional market access. |
Methodological Framework
Document review covered SEC 10-K filings, vehicle production databases, and IHS Markit registration data, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and MEMS foundry operations managers. Secondary validation drew from NHTSA rulemaking dockets, UNECE ECE regulatory texts, and MIIT GB standard publications. Bottom-up sensor shipment modeling triangulated against top-down vehicle production forecasts across propulsion architecture and automation level segmentations.
Cross-referencing historical capacity utilization patterns against panel input from foundry operations and OEM sourcing committees shaped the analytical framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, with silicon carbide power electronics adoption and solid-state LiDAR cost curves as primary industry-specific forecast inputs.
Caveats apply where MEMS foundry regional disruption, palladium price volatility, or NHTSA regulatory timeline acceleration could materially shift the outlook. Deviation in electric vehicle penetration rates or autonomous vehicle deployment schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
HCV Axles Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Car Modification Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
Limited Slip Differential (LSD) Market