
 Mining Equipment Market | 2026-2036
Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Equipment Market Intelligence
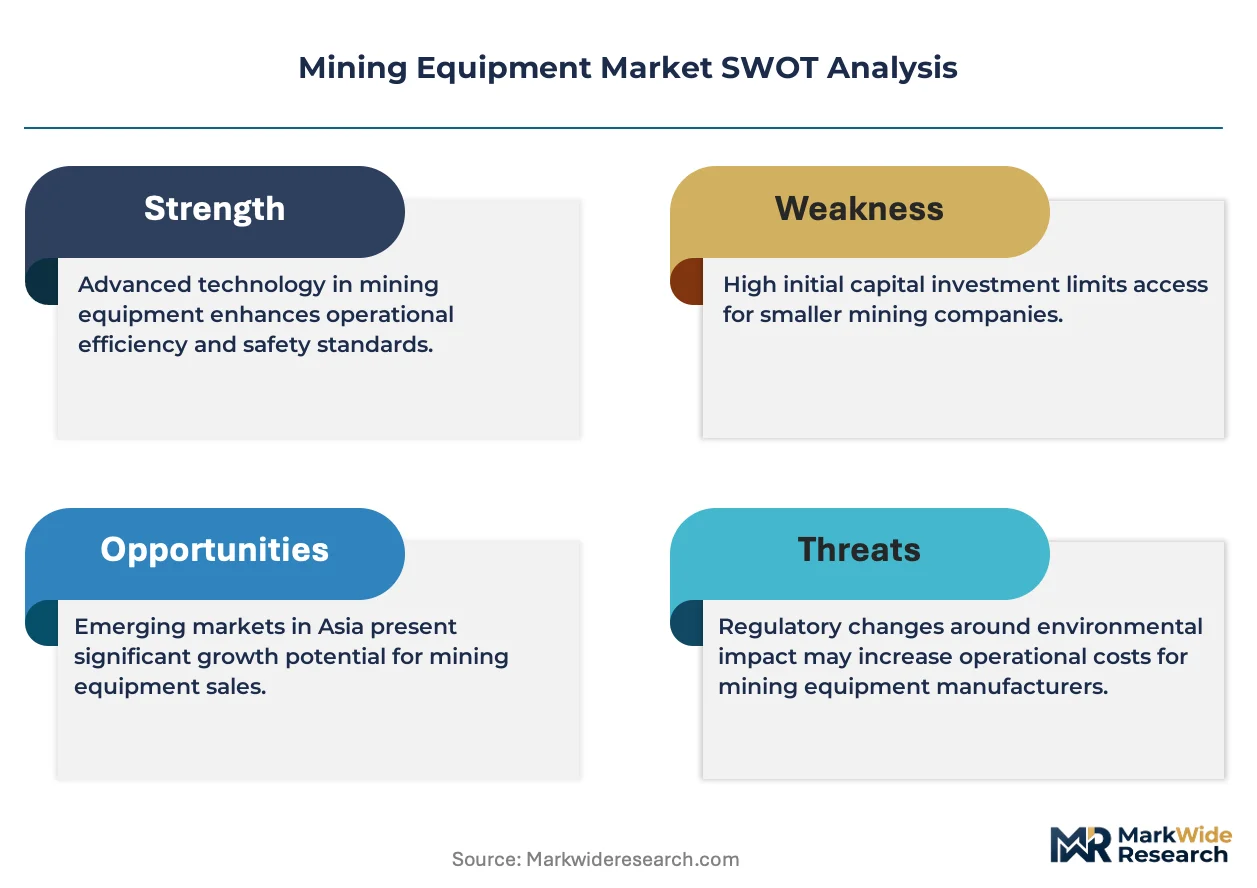
The EU Green Deal's embedded carbon border requirements is consolidating demand for lower-emission mining machinery across European extraction operations. Caterpillar Inc. leverages its integrated powertrain architecture to sustain competitive positioning in electrified haulers. Komatsu Ltd. anchors its underground portfolio through advanced bolter-driller integration. Sandvik AB differentiates via remote-controlled narrow-vein equipment purpose-built for declining ore grades.
Mining equipment encompasses heavy machinery engineered for mineral extraction, earthmoving, and material transport, typically operating at power ratings exceeding 250 kW and designed for continuous duty cycles in abrasive environments. Its primary purpose is enabling safe, productive access to ore bodies while minimizing unit extraction costs. Excavators and haulers command the largest installed base, though automation technology captures disproportionate margin pools as retrofit demand outpaces new-build penetration. Electrification shifts are accelerating fastest in underground applications where ventilation constraints amplify diesel cost penalties.
EPA emissions tiers in the US, REACH substance restrictions in Europe, and Australia's state-based mining safety codes collectively force equipment redesign cycles and aftermarket compliance spending. China's GB standards for non-road mobile machinery add a parallel certification burden for suppliers serving domestic miners. Stakeholders must weigh captive electrification investment against modular retrofit architectures as regulatory thresholds tighten without harmonization across jurisdictions.
Market Dynamics
Autonomous haulage deployment in Western Australia's Pilbara iron ore belt is compressing replacement cycles and forcing capital reallocation toward retrofit-ready platforms over purpose-built greenfield fleets.
Growth Catalysts
- REACH substance restrictions:European extraction operations face embedded carbon border requirements under the EU Green Deal, consolidating demand for lower-emission machinery retrofits.
- Underground ventilation constraints:Australia's state-based mining safety codes tighten diesel particulate exposure limits, accelerating electrification investment in captive fleets.
- Pilbara autonomous deployment:Western Australia's iron ore majors expand contractor fleets with automation-ready haulers, pulling forward equipment refresh timelines.
Market Restraints
- High-grade steel input volatility:Abrasion-resistant plate and specialty alloys for bucket liners and undercarriage components face concentrated supply from integrated mills in China and Japan.
- China's GB certification burden:Non-road mobile machinery standards create parallel compliance tracks for suppliers serving domestic miners, fragmenting engineering resources.
- Technical limitation in battery energy density:Underground load-haul-dump equipment above 14-tonne payload class lacks viable electrification paths without operational range penalties.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic manufacturing incentives for heavy machinery components open localization pathways for underground bolter-driller assemblies.
- Remote-controlled narrow-vein convergence:Teleoperation platforms merge with real-time ore sensing to unlock declining-grade deposits previously abandoned as subeconomic.
- Aftermarket service unbundling:Predictive maintenance contracts decoupled from original equipment sales create recurring revenue pools in Chile's copper belt operations.
Industry Challenges
- Automation systems integration:Retrofitting legacy hauler fleets with perception and control stacks demands scarce embedded software engineers familiar with mining duty cycles.
- Multi-jurisdiction certification timelines:EPA Tier 4 Final, EU Stage V, and Australia's state-based codes lack harmonized test protocols, extending type-approval cycles for new powertrain architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Equipment Market |
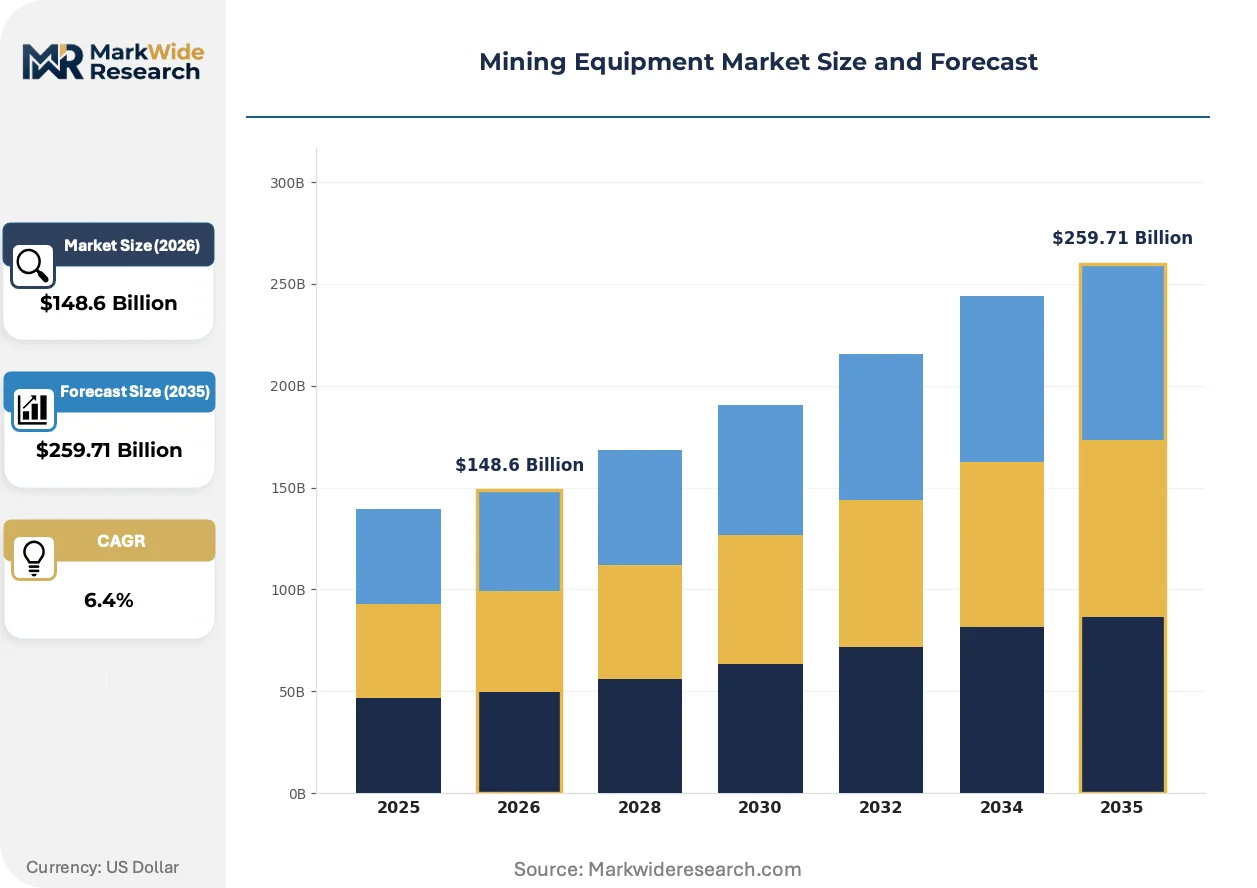
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $259.71 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bolters, Drills, Haulers Technology: Automation, Electrification, Remote Control, Advanced Analytics Application: Surface Mining, Underground Mining, Exploration, Material Handling End User: Contractors, Mining Companies, Aggregate Producers, Government Agencies |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Sandvik AB, Liebherr-International AG, Epiroc AB, AB Volvo, Hitachi Construction Machinery Co., Ltd., Atlas Copco AB, Zoomlion Heavy Industry Science & Technology Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Equipment Market Strategic Shifts & Innovations
Electrification and automation are converging to reshape equipment architecture, with powertrain design choices now predetermining a machine's upgrade path toward full autonomy.
Battery-electric powertrains are consolidating underground equipment portfolios. Load-haul-dump machines and underground trucks now standardize on modular battery pack architectures that enable 8-hour shift coverage without mid-cycle charging. Tier-1 contractors in Canada's potash belt and Sweden's iron ore districts specify electric-first procurement templates, compressing the addressable market for diesel-electric hybrids. This technology is consolidating supplier R&D budgets around integrated thermal management and fast-swap battery interfaces.
EPA emissions tiers force redesign cycles across US surface mining operations. Tier 4 Final compliance for engines above 560 kW requires selective catalytic reduction and diesel particulate filter integration that adds weight and cooling load. Open-pit coal operators in Wyoming's Powder River Basin and copper miners in Arizona's Morenci district absorb higher upfront capital while negotiating extended depreciation schedules. Equipment lessors respond with certified pre-owned programs that internalize compliance retrofit costs.
Equipment-as-a-service models are displacing traditional ownership in capital-constrained segments. Junior miners and contract operators in Brazil's Carajás province and South Africa's platinum belt prefer availability-based contracts that transfer residual value risk to OEM balance sheets. Sandvik and Epiroc pilot outcome-based agreements tied to tonnes moved rather than machine hours, compressing sales cycles but demanding real-time telemetry infrastructure. Chile's Codelco and BHP's Escondida operation serve as reference sites for this procurement evolution.
Mining Equipment Market Segmentation
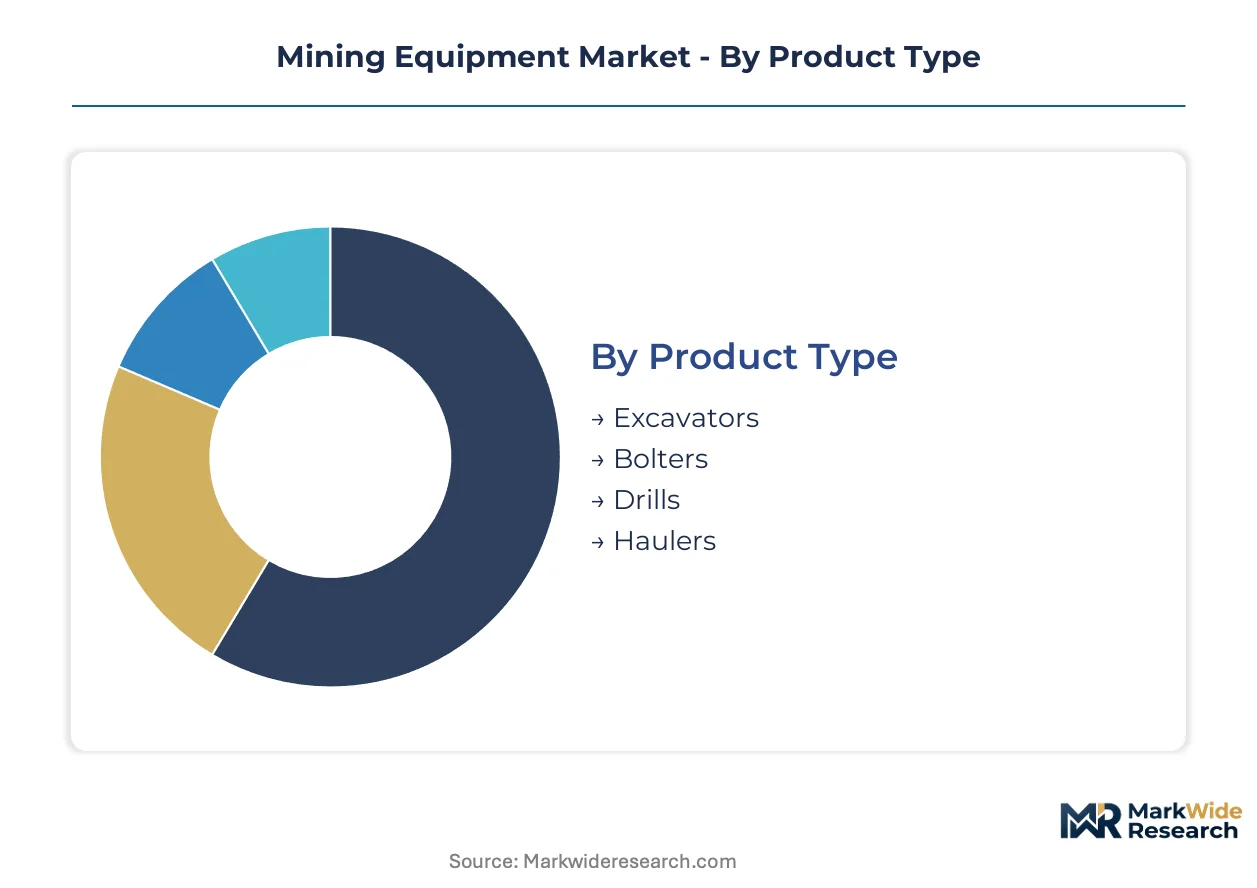
Equipment segmentation in mining machinery determines upgrade pathways and residual value trajectories. Procurement templates increasingly favor platforms that accommodate automation retrofits and powertrain conversions without frame-level modifications.
Product Type:
Replacement-cycle timing varies sharply across equipment categories, with automation-ready platforms commanding premium placement even in secondary markets.
- Excavators:These machines integrate hydraulic powertrains rated above 250 kW with reinforced undercarriages for abrasive conditions. Demand clusters in Western Australia's Pilbara iron ore belt where autonomous retrofit compatibility dictates procurement specifications.
- Haulers:Articulated and rigid-frame trucks above 100-tonne payload class anchor surface mining productivity metrics. Australia's state-based mining safety codes accelerate replacement of legacy diesel fleets with electrification-capable chassis in captive contractor operations.
- Bolters:Roof support equipment for underground metalliferous operations.
- Drills:Rotary and percussive rigs for blasthole preparation and exploration.
Volume placements concentrate in haulers; the faster expansion belongs to excavators configured for autonomous retrofit.
Technology:
Cost tier separation between proven automation stacks and emerging electrification architectures reshapes supplier R&D allocation.
- Automation:Perception and control stacks for haulage and drilling operations integrate LiDAR, radar, and machine vision with fleet management systems. Western Australia's Pilbara operations deploy these systems at scale, compressing replacement cycles for non-compatible legacy fleets.
- Electrification:Battery-electric and trolley-assist powertrains eliminate diesel particulate emissions in ventilation-constrained environments. Canada's potash belt and Sweden's iron ore districts specify electric-first procurement, marginalizing diesel-electric hybrid alternatives.
- Remote Control:Teleoperation platforms for narrow-vein and hazardous access applications.
- Advanced Analytics:Predictive maintenance and throughput optimization algorithms layered on telemetry infrastructure.
Procurement volumes favor automation; electrification gains share fastest in underground specifications.
Application:
Geography-driven demand concentration in iron ore and copper systems determines equipment specification priorities across application modes.
- Surface Mining:Open-pit extraction systems for coal, copper, and iron ore deploy the largest equipment footprints. Wyoming's Powder River Basin coal operators and Arizona's Morenci copper district absorb EPA Tier 4 Final compliance costs through extended depreciation schedules.
- Underground Mining:Narrow-vein and bulk mining methods face ventilation constraints that amplify diesel cost penalties. Australia's tightening particulate exposure limits force electrification investment in load-haul-dump and truck fleets.
- Exploration:Drill rigs and support equipment for greenfield and brownfield resource definition.
- Material Handling:Conveyors, stackers, and reclaimers for processing and port infrastructure.
Equipment shipments concentrate in surface mining; underground applications expand most quickly on regulatory pressure.
End User:
Customer-type segmentation reveals divergent procurement models, with availability-based contracting displacing traditional ownership among capital-constrained operators.
- Contractors:Fleet operators serving multiple mining clients prioritize equipment flexibility and residual value protection. Brazil's Carajás province and South Africa's platinum belt contractors favor outcome-based agreements tied to tonnes moved rather than machine hours.
- Mining Companies:Integrated producers with captive maintenance infrastructure specify automation-ready platforms for long-horizon depreciation. Chile's Codelco and BHP's Escondida operation serve as reference sites for equipment-as-a-service procurement evolution.
- Aggregate Producers:Quarries and construction materials operations with intermittent duty cycles.
- Government Agencies:State-owned mining enterprises and geological survey operations.
Contractor fleet placements dominate volume; mining company direct procurement climbs fastest on autonomous deployment mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara iron ore belt anchors global mining equipment deployment intensity, with autonomous haulage corridors compressing replacement cycles across the world's largest surface mining concentration.
Australia
Underground contractors expand captive fleets as the national mining safety regulator tightens diesel particulate exposure limits. Western Australia's state-based codes force electrification investment in load-haul-dump equipment. The Pilbara's autonomous haulage deployment accelerates refresh timelines for automation-ready chassis.
Chile
Copper majors in the Atacama Desert absorb EPA Tier 4 Final compliance costs through extended depreciation schedules. The country's national mining regulator enforces progressive dust and emissions standards. Escondida and Codelco operations serve as reference sites for equipment-as-a-service procurement evolution.
Canada
Potash belt operators in Saskatchewan specify electric-first procurement templates, marginalizing diesel-electric hybrid alternatives. Environment and Climate Change Canada enforces non-road diesel emissions regulations aligned with US EPA tiers. Sudbury's nickel district and Quebec's lithium projects concentrate underground electrification demand.
Sweden
Iron ore districts in Norrbotten standardize on battery-electric powertrains for 8-hour shift coverage without mid-cycle charging. The Swedish Work Environment Authority enforces strict ventilation and exposure limits in underground operations. LKAB's Kiruna and Malmberget mines anchor European demand for narrow-vein remote-controlled equipment.
United States
Powder River Basin coal operators and Arizona's Morenci copper district absorb Tier 4 Final compliance costs through certified pre-owned programs. EPA emissions tiers force redesign cycles for engines above 560 kW. Wyoming's surface coal corridors and Nevada's gold districts concentrate hauler replacement demand.
Mining Equipment Market Key Industry Players
The competitive structure tilts toward integrated powertrain architects with captive electrification roadmaps. Tier-1 OEMs consolidate around automation-ready platform architectures that accommodate retrofit upgrades without frame-level modifications. Three archetypes dominate: full-line powertrain integrators, narrow-vein specialization houses, and automation stack licensors. Geographic expansion through outcome-based contracting and strategic partnerships for battery supply security represent the dominant competitive vectors.
Among North American-integrated manufacturers, Caterpillar Inc. and Liebherr-International AG exemplify the full-line powertrain archetype with captive engine and drivetrain architectures. Komatsu Ltd. occupies a position within the automation-first tier, while Sandvik AB and Epiroc AB represent the narrow-vein specialization cluster purpose-built for declining ore grades. Hitachi Construction Machinery Co., Ltd. and AB Volvo sit within the diversified industrial conglomerate tier, leveraging cross-sector technology transfer. Atlas Copco AB exemplifies the compressor and underground tooling heritage that feeds into integrated bolter-driller portfolios.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Sandvik AB |
| Liebherr-International AG |
| Epiroc AB |
| AB Volvo |
| Hitachi Construction Machinery Co., Ltd. |
| Atlas Copco AB |
| Zoomlion Heavy Industry Science & Technology Co. |
| Others |
Cost & Logistics Intelligence
EU Green Deal embedded carbon border requirements gate both qualified supply and premium-tier pricing access, forcing OEMs to certify low-emission powertrain architectures before bidding into European extraction contracts. Tier-1 suppliers absorb compliance engineering costs upfront, recovering margins through outcome-based contracting tied to tonnes moved rather than equipment units sold.
Pricing Analysis
Availability-based pricing anchors mining equipment procurement, with contractors in Brazil's Carajás province and South Africa's platinum belt preferring contracts that transfer residual value risk to OEM balance sheets. Premium-mid-economy pricing differentiation separates automation-ready platforms with retrofit compatibility from legacy chassis requiring frame-level modifications. Cost compression in standard-tier haulers is intensifying because certified pre-owned programs internalize EPA Tier 4 Final compliance retrofits. Junior miners and contract operators exhibit highest price sensitivity; integrated producers with captive maintenance infrastructure show lowest.
Supply Chain Analysis
Skilled welder and embedded software engineer shortages in Germany, Japan, and the US Midwest constrain fabrication capacity for automation-ready platforms. Abrasion-resistant plate and specialty alloys for bucket liners draw from integrated mills in China and Japan, while battery cell supply rests on South Korean and Chinese cathode chemistry. Single-source vulnerability in high-grade steel inputs threatens production schedules for 14-tonne payload class underground equipment. Distribution runs through OEM-owned service depots and authorized dealer networks concentrated in Western Australia's Pilbara and Chile's Atacama Desert.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining equipment procurement is transitioning from ownership models to electrified, autonomous-ready platforms. Battery-electric powertrains are displacing diesel-electric hybrids in underground specifications across Canada's potash belt and Sweden's iron ore districts.
For Market Incumbents: Anchor competitive positioning through captive battery supply agreements and fast-swap interface standardization. Automation stack integration demands scarce embedded software engineers familiar with mining duty cycles; internalize this capability through targeted hiring in Sweden's mining technology corridor. Defend against equipment-as-a-service disintermediation by piloting outcome-based contracts at reference sites like Chile's Codelco and BHP's Escondida. For New Entrants and Emerging Players: Launch via narrow-vein remote-controlled equipment purpose-built for declining ore grades in Australia's metalliferous underground operations. India's PLI scheme for capital goods manufacturing opens localization pathways for underground bolter-driller assemblies with domestic content requirements. Target aftermarket predictive maintenance contracts decoupled from original equipment sales in Chile's copper belt, where telemetry infrastructure investments create recurring revenue pools. For Investors and Strategic Acquirers: Australia's state-based mining safety code tightening is the leading indicator that electrification investment will accelerate replacement cycles in captive contractor fleets. Long-term viability over the next decade favors suppliers with integrated powertrain architectures and automation-ready platform designs. Watch for inflection in battery energy density breakthroughs above 300 Wh/kg that would unlock viable electrification paths for 14-tonne payload class load-haul-dump equipment without operational range penalties.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Secures cathode chemistry access for 8-hour shift coverage in underground electric fleets. |
| Automation Stack Licensing Partnership | Accelerates retrofit deployment for legacy hauler fleets in Western Australia's Pilbara corridor. |
| Fast-Swap Battery Interface Standardization | Enables interoperability across OEM platforms in Sweden's Kiruna and Malmberget mines. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from Chile's Codelco and Escondida telemetry infrastructure investments. |
| PLI Scheme Localization Compliance | Qualifies for India's domestic manufacturing incentives in underground bolter-driller assemblies. |
Research Approach
Document review covered SEC 10-K filings, EPA emissions certification databases, EU ETS registry disclosures, and Australia's state mining safety code amendments, complemented by interviews with maintenance directors at Pilbara iron ore operations, OEM procurement teams in Germany and Japan, aftermarket service heads in Chile's copper belt, and plant engineers at Saskatchewan potash facilities. Secondary validation drew from customs trade data for abrasion-resistant steel plate, IEA critical minerals tracking, and equipment registration databases. Bottom-up unit shipment estimates triangulated against top-down mining capital expenditure projections.
Historical fleet replacement patterns cross-referenced against panel input from mining contractor fleet managers and OEM sales executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, powertrain architecture, automation readiness tier, application mode, and end-user procurement structure. CAGRs were derived from equipment shipment trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated EPA Tier 4 Final compliance cost absorption rates and Australia's diesel particulate exposure limit phase-in schedules.
Regulatory harmonization failure, battery energy density stagnation, and high-grade steel supply disruption are the dominant revision risks to modeled equipment demand. Forecasts reflect assumptions around automation retrofit penetration rates and electrification capex allocation priorities. Material deviation in named triggers warrants pause and re-evaluation of replacement cycle timing and premium-tier pricing sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mining Shovel Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
DTH Drill Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Global Automated Mining Equipment Market