
 Smart Mining Technologies Market | 2026-2036
Smart Mining Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mining Technologies Market Analytics
ISO 19434 safety classification for autonomous mining equipment is collapsing the vendor landscape into a narrow qualified tier. Rio Tinto leverages its Pilbara autonomous haulage network to sustain operating cost advantages across iron ore deposits. KoBold Metals differentiates through AI-driven exploration targeting, positioning its proprietary algorithms ahead of conventional survey methods. Weir Group anchors aftermarket service revenue through vertical integration into wear-component manufacturing for comminution circuits.
Smart mining technologies integrate sensor networks, autonomous vehicle systems, and real-time analytics platforms to optimize extraction efficiency while reducing human exposure to hazardous underground conditions. These systems typically operate on sub-meter GPS correction, 5G mesh connectivity, and edge computing nodes processing ore-grade data within 50 milliseconds for immediate fleet routing decisions. The automation technology segment leads capital deployment as open-pit operators prioritize truck and shovel autonomy, while the AI segment captures expanding margin pools in predictive maintenance and ore-body modeling. Among product types, haulers dominate unit volumes through retrofit programs, yet crushers command premium pricing due to integration complexity with downstream processing lines.
The US Mine Safety and Health Administration and Australia's Work Health and Safety Act impose stringent autonomous equipment certification protocols that shape R&D budgets and vendor qualification timelines. The EU Green Deal and REACH chemical compliance frameworks further constrain hydraulic fluid formulations and battery chemistries permitted in underground deployments. Stakeholders must monitor how interoperability standards between OEM platforms evolve, as proprietary data architectures risk locking operators into single-vendor ecosystems that limit competitive sourcing flexibility.
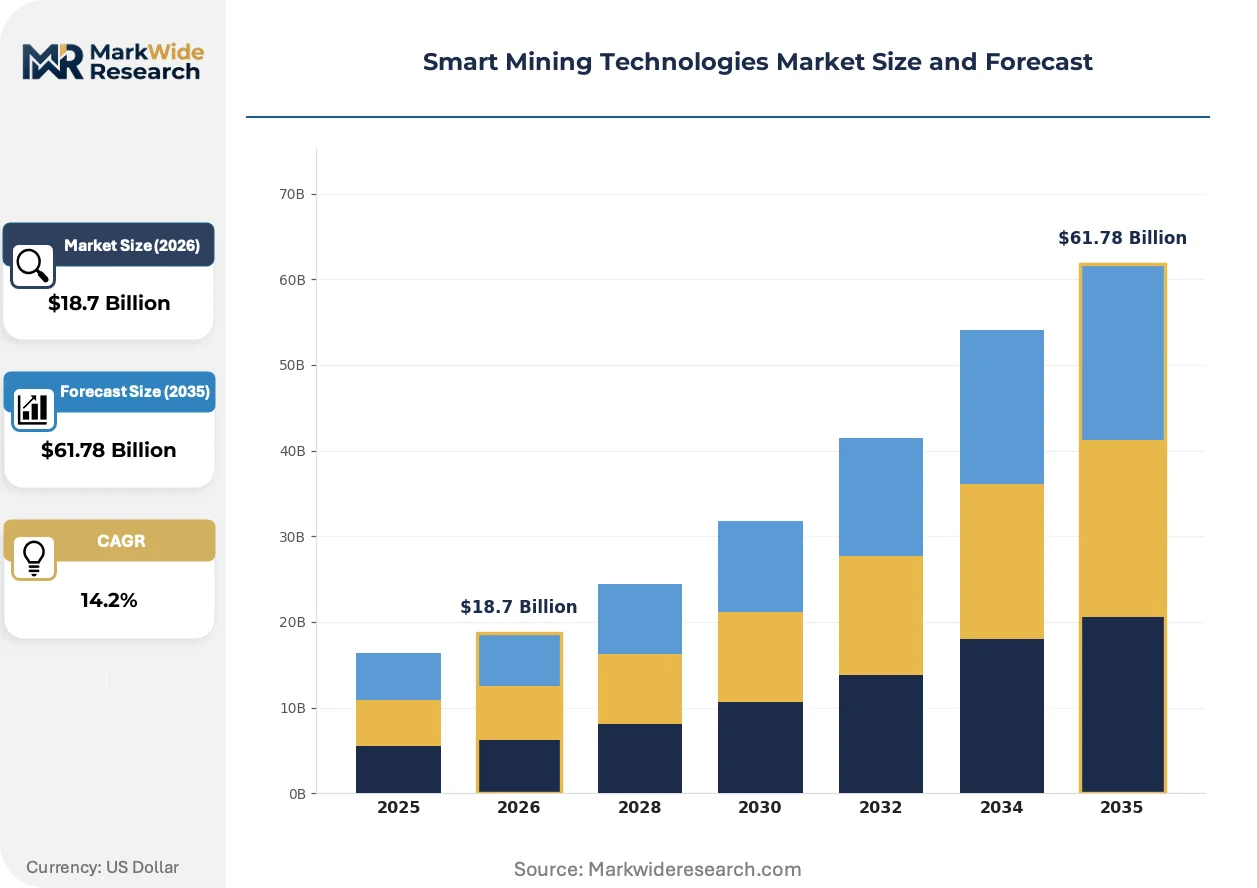
Market Dynamics
Autonomous haulage systems are compressing operating margins for conventional fleet operators, forcing tier-two miners to accelerate retrofit timelines or exit high-cost deposits. The collision between ISO 19434 safety mandates and proprietary OEM data architectures is reshaping vendor selection criteria across open-pit and underground operations.
Growth Catalysts
- EU F-Gas Regulation:Emissions thresholds for surface extraction equipment are accelerating electric drivetrain adoption in European copper and iron ore operations.
- Chile copper belt concentration:Tier-one miners are retrofitting legacy pits with sensor networks, creating dense demand clusters for real-time ore-grade analytics.
- 5G mesh deployment:Sub-50 millisecond latency requirements for fleet routing decisions are pulling private network infrastructure investment into Australian and Canadian mine sites.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity clusters in China, creating geopolitical exposure for underground electric fleet operators in North America and Australia.
- ISO 19434 certification timelines:Eighteen-month qualification protocols for autonomous equipment are stretching vendor R&D amortization periods and limiting new entrant viability.
- Hydraulic fluid formulation constraints:REACH compliance frameworks are eliminating legacy mineral oil bases, forcing reformulation costs across European underground deployments.
Strategic Opportunities
- AI-driven exploration targeting:Proprietary algorithms trained on multi-sensor geophysical data are compressing survey timelines in underexplored jurisdictions including Kazakhstan and Mongolia.
- Aftermarket service unbundling:Wear-component manufacturing captive to comminution circuit OEMs is opening third-party entry points for independent maintenance providers.
- Interoperability standards emergence:Cross-OEM data protocols under development at ISO and IEC are threatening to unlock multi-vendor sourcing flexibility currently blocked by proprietary architectures.
Industry Challenges
- Autonomous systems integration:Legacy pit infrastructure designed for human-operated fleets requires expensive retrofitting of haul roads, loading zones, and maintenance bays to accommodate machine-only operations.
- Edge computing talent scarcity:Mine sites in remote geographies struggle to recruit personnel capable of maintaining on-site data processing nodes and 5G mesh networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mining Technologies Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automation, AI, IoT, Robotics Product Type: Drilling Equipment, Loaders, Haulers, Crushers End User: Coal Mining, Metal Mining, Mineral Mining, Quarrying Application: Exploration, Extraction, Processing, Waste Management |
| Companies Covered | Weir Group, KoBold Metals, BHP Group, Zijin Mining, CATL Mining Division, Rio Tinto, Chrysos Corporation, Panmure Liberum, Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mining Technologies Market Evolving Landscape
Digital twin architectures are collapsing the gap between physical extraction operations and simulated optimization environments, enabling real-time parameter adjustment without production interruption. This convergence of sensor density, cloud compute, and physics-based modeling is restructuring how operators manage ore variability and equipment degradation.
Optical ore-sorting sensors integrated at the crusher feed are supplanting traditional bulk sampling methods for grade control. Tier-one copper operators in Chile and Peru are deploying these systems across retrofit programs, compressing assay turnaround from hours to seconds and enabling immediate diversion of sub-economic material to waste streams.
REACH chemical compliance frameworks are eliminating per- and polyfluoroalkyl substances from hydraulic fluid formulations used in European underground equipment. This regulatory pressure is forcing lubricant suppliers to accelerate bio-based alternatives through accelerated wear-testing protocols, with German and Polish coal operators bearing the highest reformulation transition costs.
Buyer concentration among tier-one miners is compressing vendor negotiation cycles and unbundling after-sales service contracts from initial equipment procurement. Australian iron ore operators now separately tender maintenance services for autonomous haul fleets, eroding the captive revenue streams that historically subsidized OEM pricing on primary equipment sales.
Smart Mining Technologies Market Segmentation
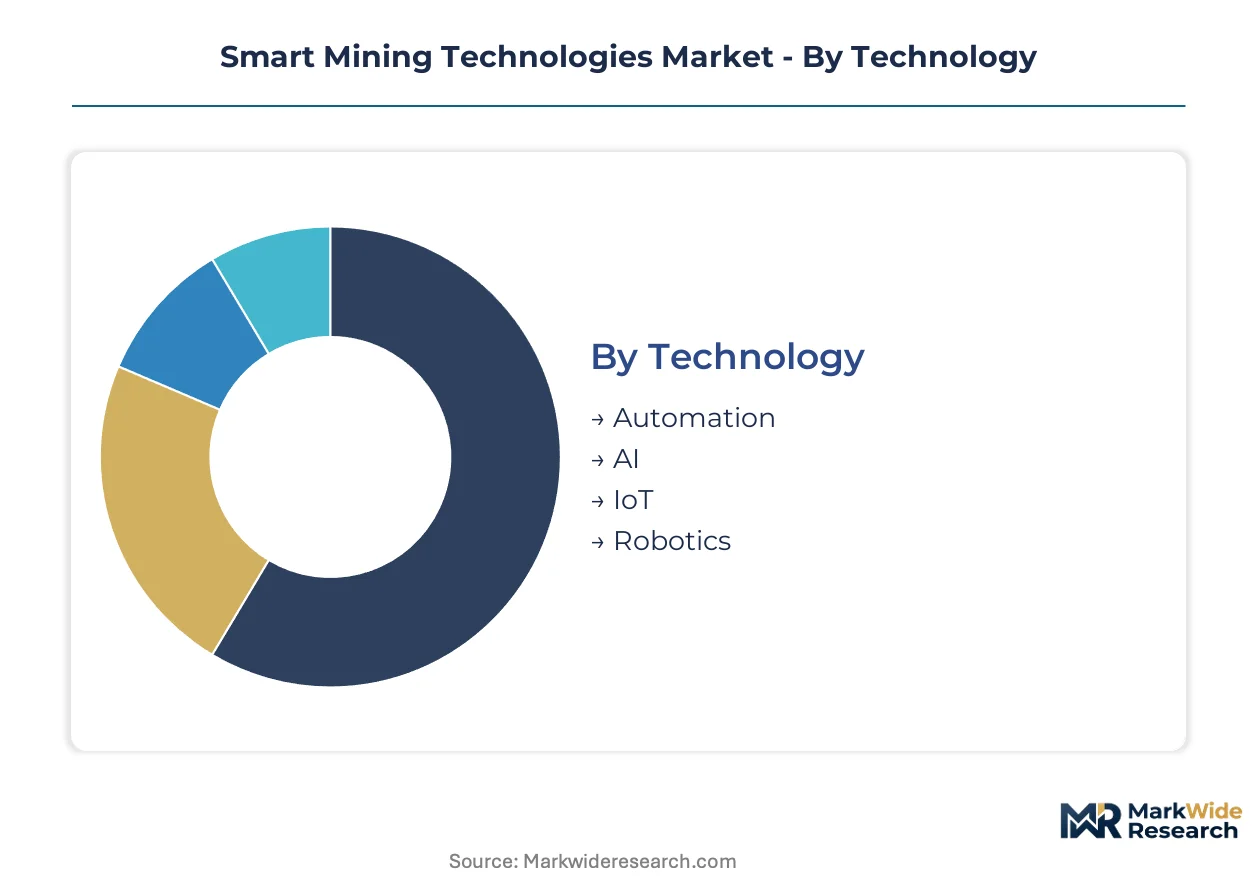
Smart mining technologies fragment across four distinct classification axes. Technology and product type determine capital deployment patterns, while end user and application shape operational requirements and regulatory exposure.
Technology:
Automation systems flow through direct OEM channels with embedded service contracts, while AI and IoT platforms increasingly route through independent software vendors and systems integrators.
- Automation:Autonomous haulage and drilling systems integrate sub-meter GPS correction with collision-avoidance protocols. Australian iron ore operators deploy these at scale across Pilbara operations, compressing labor costs while meeting ISO 19434 safety mandates.
- AI:Predictive maintenance algorithms and ore-body modeling tools process geophysical data through proprietary machine learning architectures. Chilean copper miners leverage these for real-time grade control, diverting sub-economic material before downstream processing.
- IoT:Sensor networks enable condition monitoring across distributed equipment fleets. These systems require 5G mesh infrastructure investment at remote mine sites.
- Robotics:Remote-operated and semi-autonomous units handle hazardous underground tasks. Deployment concentrates in narrow-vein metal mining where human access risks exceed operational thresholds.
Automation dominates installed base. AI is where expansion concentrates.
Product Type:
Cost tier differentiation separates premium integrated systems from retrofit-compatible modules, with mid-tier solutions capturing volume in emerging mining jurisdictions.
- Drilling Equipment:Autonomous blasthole rigs integrate real-time rock hardness sensing with drill pattern optimization. Tier-one miners in Kazakhstan deploy these across greenfield copper developments.
- Loaders:Electric and diesel-electric underground loaders incorporate proximity detection and remote operation capabilities. Battery-electric variants face supply chain constraints from cathode material processing concentration.
- Haulers:Ultra-class autonomous trucks operate on dedicated haul roads with centralized fleet management. Retrofit programs dominate unit volumes as open-pit operators phase out manned fleets.
- Crushers:High-throughput comminution equipment with integrated optical sorting commands premium pricing. Chilean and Peruvian copper operations deploy these for immediate waste diversion based on real-time assay data.
Haulers capture the largest unit volumes. Crushers generate the highest margin per installation.
End User:
Application intensity varies sharply across extraction methods, with underground operations demanding higher technology penetration per ton extracted than surface methods.
- Coal Mining:Underground longwall operations deploy autonomous shearers and armored face conveyors with methane monitoring integration. Australian and Polish operators face REACH-compliant hydraulic fluid reformulation costs.
- Metal Mining:Copper, gold, and iron ore extraction drives the largest absolute technology investment. Sensor networks and autonomous fleets concentrate in Chile, Australia, and Canada.
- Mineral Mining:Potash, lithium, and rare earth operations require specialized handling equipment with dust suppression and environmental monitoring. Lithium brine extraction in Argentina deploys IoT-enabled evaporation pond management.
- Quarrying:Aggregate and dimension stone operations adopt retrofit automation for loading and hauling. Margins constrain adoption to larger consolidated operators.
Metal mining dominates technology expenditure. Coal mining is where regulatory compliance costs are climbing fastest.
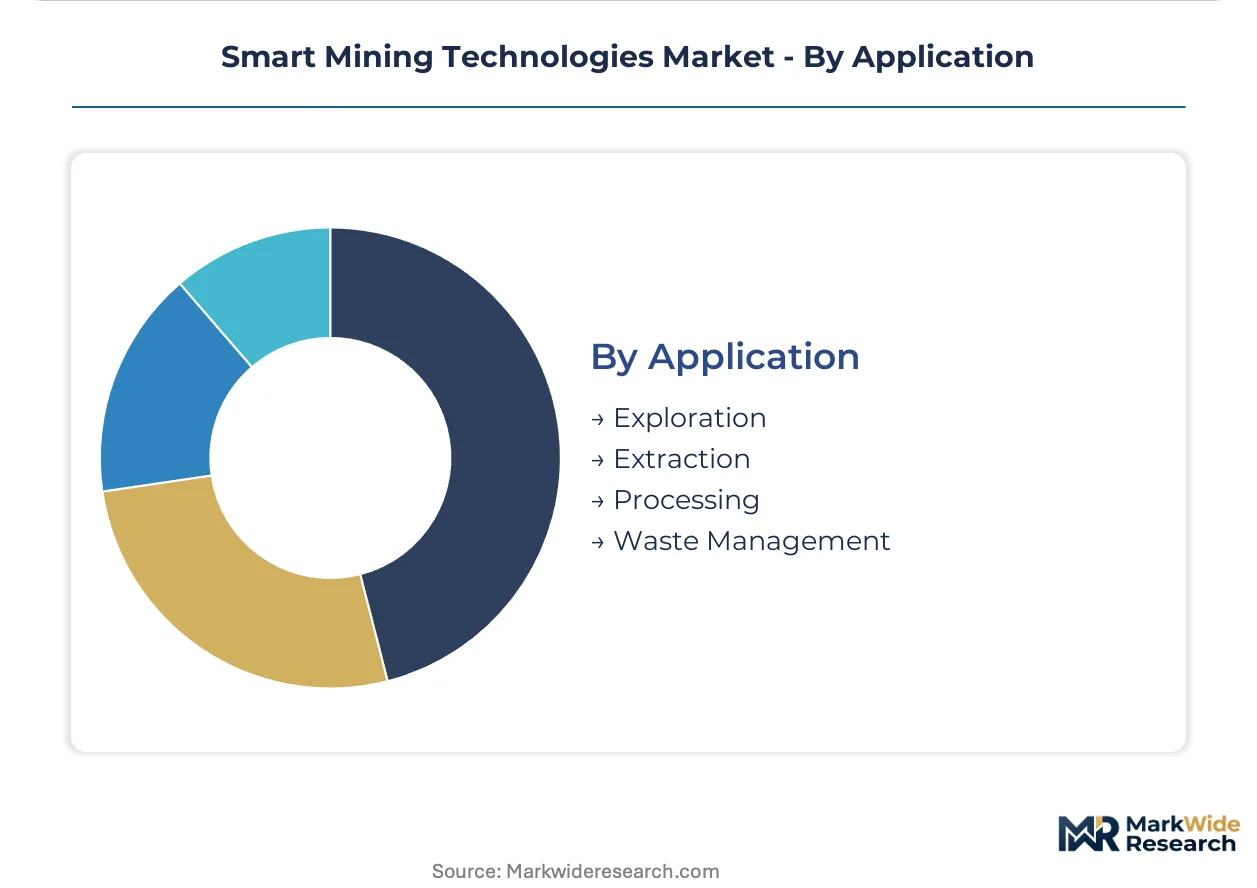
Application:
Customer type stratification separates integrated majors with captive technology development from mid-tier miners dependent on vendor solutions.
- Exploration:AI-driven targeting algorithms and drone-based geophysical surveys compress survey timelines. KoBold Metals and similar specialists deploy proprietary multi-sensor data fusion in underexplored jurisdictions.
- Extraction:Autonomous drilling, loading, and hauling systems optimize fleet utilization and labor exposure. Real-time ore-grade analytics enable selective mining and immediate routing decisions.
- Processing:Digital twin architectures and predictive maintenance platforms minimize comminution circuit downtime. Optical sorting at crusher feeds replaces traditional bulk sampling methods.
- Waste Management:Autonomous dozers and water trucks manage tailings facilities and haul road maintenance. Environmental monitoring integration tracks dust, water quality, and slope stability.
Extraction commands the largest capital allocation. Exploration is gaining share fastest as AI-enabled targeting reduces discovery risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and national decarbonization incentives are redirecting capital toward electrified extraction infrastructure. Chile's copper belt and Australia's Pilbara region anchor autonomous fleet deployment. Underground safety mandates in Poland and Canada are accelerating sensor network retrofits.
Australia
Autonomous haulage networks across Western Australia's Pilbara iron ore deposits compress operating costs while satisfying Work Health and Safety Act certification requirements. The country's national mining regulator enforces stringent autonomous equipment protocols that shape vendor qualification timelines. Underground coal operators in New South Wales and Queensland are expanding battery-electric loader fleets amid methane monitoring integration mandates.
Chile
Tier-one miners retrofit legacy open-pit copper operations with real-time ore-grade sensor networks to enable selective mining and immediate waste diversion. The national mining regulator imposes environmental compliance frameworks that accelerate optical sorting adoption at crusher feeds. Antofagasta and Calama anchor dense technology clusters where 5G mesh infrastructure supports sub-50 millisecond fleet routing decisions.
Canada
Underground hard-rock operations in Ontario and Quebec deploy remote-operated drilling systems to reduce human exposure in narrow-vein metal extraction. Health Canada and provincial workplace safety authorities mandate collision-avoidance protocols for autonomous equipment in Saskatchewan potash mines. The Abitibi gold belt concentrates digital twin architecture investment for predictive maintenance across comminution circuits.
Poland
Underground longwall coal operators face REACH-compliant hydraulic fluid reformulation costs that eliminate legacy mineral oil bases from armored face conveyor systems. The EU Green Deal emissions thresholds accelerate electric drivetrain adoption in Silesian Basin operations. Katowice anchors regional technology procurement clusters where vendors navigate eighteen-month ISO 19434 certification protocols.
United States
Nevada gold operations integrate AI-driven exploration targeting with drone-based geophysical surveys to compress discovery timelines in underexplored jurisdictions. The Mine Safety and Health Administration enforces autonomous equipment certification protocols that stretch vendor R&D amortization periods. Arizona's copper porphyry deposits concentrate sensor network investment for real-time grade control and selective routing decisions.
Smart Mining Technologies Market Competitive Landscape
Player mix skews toward diversified mining conglomerates with captive technology development capabilities alongside specialized autonomous equipment vendors. Market structure exhibits tiered concentration where integrated majors internalize fleet management software while mid-tier miners depend on OEM-embedded service contracts. Two strategic archetypes dominate: full-stack autonomy providers controlling hardware-software integration and aftermarket service specialists capturing wear-component manufacturing. Competitive moves center on multi-vendor interoperability lobbying and unbundled maintenance tendering.
Among diversified mining conglomerates with captive technology platforms, Rio Tinto and BHP Group exemplify the integrated-major archetype where autonomous haulage networks generate operating cost advantages. KoBold Metals occupies a distinct position within the AI-driven exploration specialist tier, representing proprietary algorithm development without legacy asset encumbrance. Weir Group anchors the aftermarket service provider segment through in-house production of wear components for comminution circuits.
| Leading Market Players |
|---|
| Weir Group |
| KoBold Metals |
| BHP Group |
| Zijin Mining |
| CATL Mining Division |
| Rio Tinto |
| Chrysos Corporation |
| Panmure Liberum |
| Glencore |
| Others |
Value Network & Pricing Analysis
Battery-electric drivetrain substitution for diesel-electric systems is rerouting procurement toward cathode material processing hubs while compressing margin structures for legacy fleet suppliers. This displacement simultaneously concentrates supply geography in East Asian battery chemistry clusters and intensifies price competition among autonomous equipment vendors competing for retrofit contracts.
Pricing Analysis
Certification level under ISO 19434 creates the primary spread between premium autonomous systems and standard retrofit modules. Three-tier pricing structure across OEM-embedded, third-party integrated, and aftermarket-only solutions stratifies by after-sales bundling intensity and software lock-in duration. Cost compression in mid-tier hauler retrofits is intensifying because tier-two miners now unbundle maintenance contracts from initial procurement. Quarrying operators exhibit highest price sensitivity due to margin constraints, while tier-one copper miners in Chile demonstrate lowest sensitivity given operational risk reduction priorities.
Supply Chain Analysis
China anchors cathode material processing and lithium-ion cell manufacturing for underground electric fleets. South Korea and Japan feed advanced sensor components and precision GPS modules into autonomous haulage systems. The supply chain draws from cobalt concentrates in the DRC and rare earth processing in China, creating single-source vulnerability for permanent magnet motors in electric loaders. Distribution runs through OEM-direct channels for integrated majors and systems integrators for mid-tier miners seeking multi-vendor flexibility.
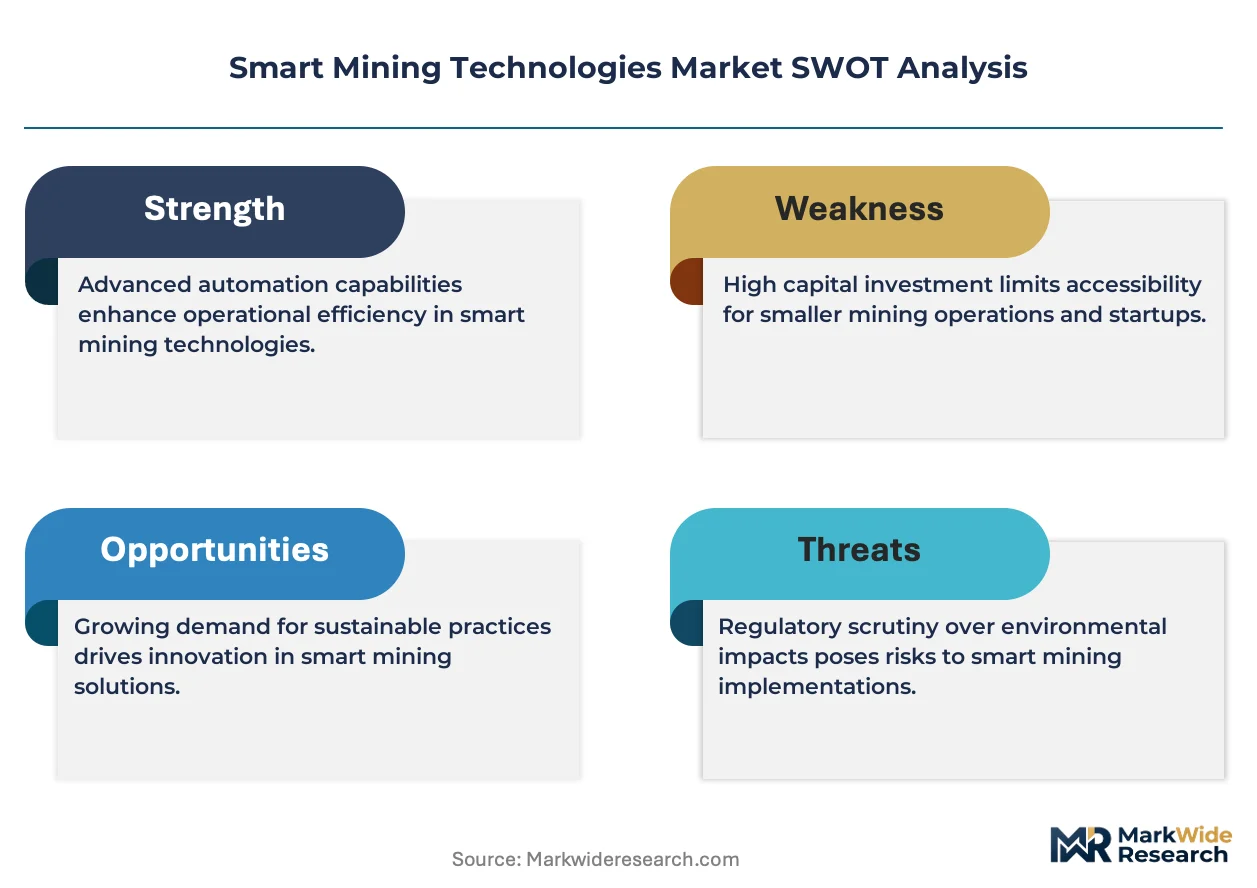
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one mining conglomerates with captive technology development capabilities, fragmenting the vendor landscape into specialized service providers dependent on unbundled maintenance tenders.
For Market Incumbents: Secure backward integration into battery pack assembly to offset cathode material cost volatility from Chinese processing concentration. Lock in ISO 19434 certification timelines ahead of competitor qualification cycles to extend R&D amortization advantages. Prioritize interoperability lobbying at ISO and IEC to defend against cross-OEM data protocols that threaten proprietary architecture lock-in. For New Entrants and Emerging Players: Aftermarket service gaps in wear-component manufacturing for comminution circuits offer immediate white-space entry beneath OEM captive pricing. Target Kazakh and Mongolian greenfield copper developments where autonomous drilling demand outpaces established vendor qualification capacity. Pursue independent software vendor positioning through AI-driven ore-grade analytics rather than hardware-integrated automation systems. For Investors and Strategic Acquirers: Capital is best deployed toward AI-driven exploration specialists with proprietary geophysical data fusion capabilities and no legacy asset encumbrance. Long-term viability hinges on algorithmic differentiation in underexplored jurisdictions rather than equipment manufacturing scale. Watch for inflection when tier-one miners begin unbundling fleet management software from autonomous haulage hardware procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captures margin from Chinese cathode processing concentration for electric underground fleets. |
| ISO 19434 Certification Acceleration | Compresses competitor qualification timelines and extends amortization windows for autonomous equipment vendors. |
| AI-Driven Exploration Platform Launch | Positions proprietary algorithms ahead of conventional survey methods in Kazakh copper greenfields. |
| Interoperability Standards Lobbying | Threatens to unlock multi-vendor sourcing flexibility currently blocked by OEM proprietary data architectures. |
| Aftermarket Service Unbundling | Erodes captive revenue streams that historically subsidized primary equipment pricing for comminution circuits. |
Research Methodology
A spread of perspectives from autonomous fleet operators, mining technology procurement directors, aftermarket service heads, and regulatory compliance officers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC filings of diversified mining conglomerates, customs data on autonomous equipment imports, and ISO certification registries. Bottom-up equipment deployment tallies triangulated against top-down capital expenditure disclosures from tier-one miners across the analysis window.
Technology type, product category, end-use application, and geographic deployment cluster formed the segmentation dimensions modeled. CAGRs derived from equipment unit deployment trajectories and average selling price trends across automation, AI, IoT, and robotics platforms. Forecast inputs incorporated 5G mesh infrastructure investment cycles and REACH-compliant hydraulic fluid reformulation cost pass-through assumptions.
Forecasts assume regulatory continuity in EU F-Gas Regulation thresholds and Australia's Work Health and Safety Act certification protocols; material policy shifts would require re-modeling. Specific risks include lithium-ion supply disruption from cathode processing concentration and ISO 19434 timeline extensions stretching vendor viability. Recalibration cycles align with material shifts in autonomous equipment certification standards and interoperability protocol developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market