
 Latin America Mining Equipment Market | 2026-2036
Latin America Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Mining Equipment Market Foresight
Chile's updated tailings storage facility regulations under its national mining service is broadening the addressable market for safer, higher-capacity earthmoving and materials handling systems. Caterpillar Inc. leverages its extensive dealer network across the Andean ridge to sustain aftermarket parts revenue. Komatsu Ltd. anchors its regional position through integrated autonomous haulage technology deployed at major copper operations. Sandvik AB differentiates via specialized underground drilling rigs optimized for the narrow vein geometries common in Peruvian polymetallic mines.
Latin America mining equipment encompasses heavy machinery engineered for mineral extraction, earthmoving, and ore processing, typically featuring hardened steel undercarriages, pressurized cabs rated for dusty altitudes above 3,000 meters, and engines calibrated for low-oxygen combustion efficiency. Its primary purpose is to fracture, lift, transport, and process rock and mineral bearing ores at scale in open-pit and underground settings. Excavators and loaders together constitute the dominant product category, reflecting the region's dependence on bulk surface mining for copper and iron ore. Automation technology represents the fastest-expanding segment, driven by labor cost pressures and safety mandates at remote high-altitude sites. Electric drives are gaining traction in underground metal mining applications where ventilation cost reduction and diesel particulate exposure limits create dual incentives for fleet conversion.
Brazil's National Mining Agency enforces progressive decommissioning bonds and closure plans that shape capital allocation toward longer-life, more efficient equipment platforms. Peru's Ministry of Energy and Mines coordinates with environmental certification bodies to restrict machinery imports that fail updated emissions thresholds, tightening market access for non-compliant suppliers. Chile's environmental impact assessment system requires detailed equipment noise and dust mitigation plans before project approval. Stakeholders must weigh the capital intensity of electrified fleets against the operational flexibility of hybrid platforms as regulatory timelines for diesel phase-outs crystallize across Andean jurisdictions.
Market Dynamics
Chile's tailings dam safety overhaul and Peru's emissions compliance mandates are compressing equipment replacement cycles while forcing suppliers to recalibrate product portfolios for high-altitude, low-oxygen operating environments.
Growth Catalysts
- Autonomous haulage systems:Copper majors in Chile's Atacama are retrofitting open-pit fleets with driverless truck technology to offset labor shortages at remote elevations above 4,000 meters.
- Brazil's ANM closure bond requirements:The National Mining Agency's progressive decommissioning rules compel operators to invest in longer-life excavators and haulers with verified durability metrics.
- Lithium brine extraction expansion:Argentina's Salta and Jujuy provinces are deploying specialized evaporation pond equipment and selective extraction pumps for battery-grade lithium carbonate production.
Market Restraints
- Import emissions thresholds:Peru's Ministry of Energy and Mines restricts machinery entry for non-compliant diesel engines, creating certification bottlenecks for second-tier suppliers.
- Steel and component volatility:Hardened undercarriage steel and high-pressure hydraulic systems face input cost swings tied to global metallurgical commodity markets.
- Concentrated dealer networks:Aftermarket parts and service capacity clusters in Santiago and Lima, leaving remote Brazilian iron ore corridors and Colombian coal regions underserved.
Strategic Opportunities
- Underground electrification:Narrow-vein polymetallic operations in Peru's Andean cordillera present white space for battery-electric drilling rigs that cut ventilation costs and diesel particulate exposure.
- Hybrid platform adoption:Brazilian iron ore miners are piloting dual-power excavators that switch between grid electricity and diesel, hedging against diesel phase-out timelines in the National Mining Agency's regulatory roadmap.
- Remote monitoring services:Telematics-enabled predictive maintenance contracts are penetrating Chile's copper belt as operators seek to minimize unplanned downtime at single-access mine sites.
Industry Challenges
- Autonomous systems integration:Legacy fleet interoperability with new command-and-control infrastructure demands specialized commissioning teams scarce in Andean labor markets.
- High-altitude certification timelines:Pressurized cab and engine recalibration testing for 3,000-plus-meter operation extends equipment approval cycles by 8-14 months.
- Electrification capex intensity:Battery-electric underground loaders require charging infrastructure and power distribution upgrades that strain capital allocation at mid-tier polymetallic operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Mining Equipment Market |
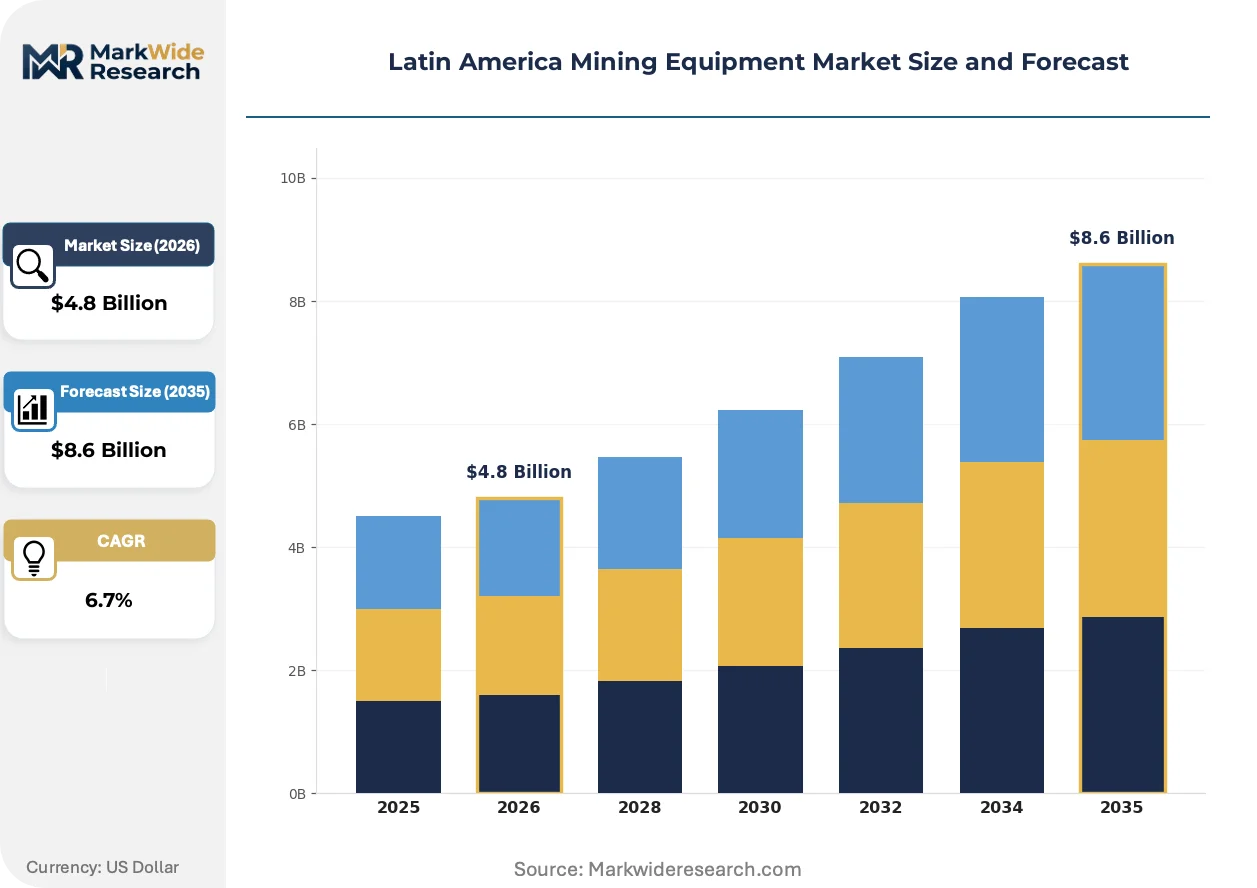
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Drills, Loaders Technology: Automation, Remote Monitoring, Hydraulics, Electric Drives End User: Coal Mining, Metal Mining, Quarrying, Mineral Exploration Application: Extraction, Transportation, Processing, Site Preparation |
| Companies Covered | Hitachi Construction Machinery, Atlas Copco, Caterpillar Inc., Volvo Construction Equipment, Epiroc AB, Komatsu Ltd., Liebherr Group, Metso Corporation, Sandvik AB, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Mining Equipment Market Shifts & Advancements
Equipment intelligence and powertrain diversification are restructuring competitive advantage in Latin American mining, with automation and electrification becoming baseline requirements rather than differentiators.
Teleoperation and autonomous haulage technology is converging with real-time terrain mapping to enable single-operator supervision of multi-truck fleets in Chile's deep open-pit copper operations. Codelco and Antofagasta Minerals are deploying these systems at Escondida and Los Pelambres, compressing labor requirements while raising throughput consistency. The technology is converging with 5G private networks to eliminate latency barriers that previously limited remote operation distances.
Brazil's ANM tailings dam safety protocols now mandate independent stability audits and real-time monitoring instrumentation for all upstream structures. This regulatory architecture forces equipment suppliers to integrate sensor packages and data transmission capabilities directly into earthmoving and materials handling systems. The policy most affects hydraulic mining shovels and articulated trucks operating in Minas Gerais iron ore districts, where operators are specifying factory-integrated monitoring as a procurement prerequisite.
Service contract unbundling is fragmenting traditional full-maintenance lease structures across Andean copper operations. Major miners now separate component rebuilds, fluid analysis, and field labor into competitively tendered work packages, pressuring OEM captive service margins. Chile's Escondida and Peru's Cerro Verde have adopted this model, driving independent service providers to build regional parts depots and certified technician pools.
Latin America Mining Equipment Market Segmentation
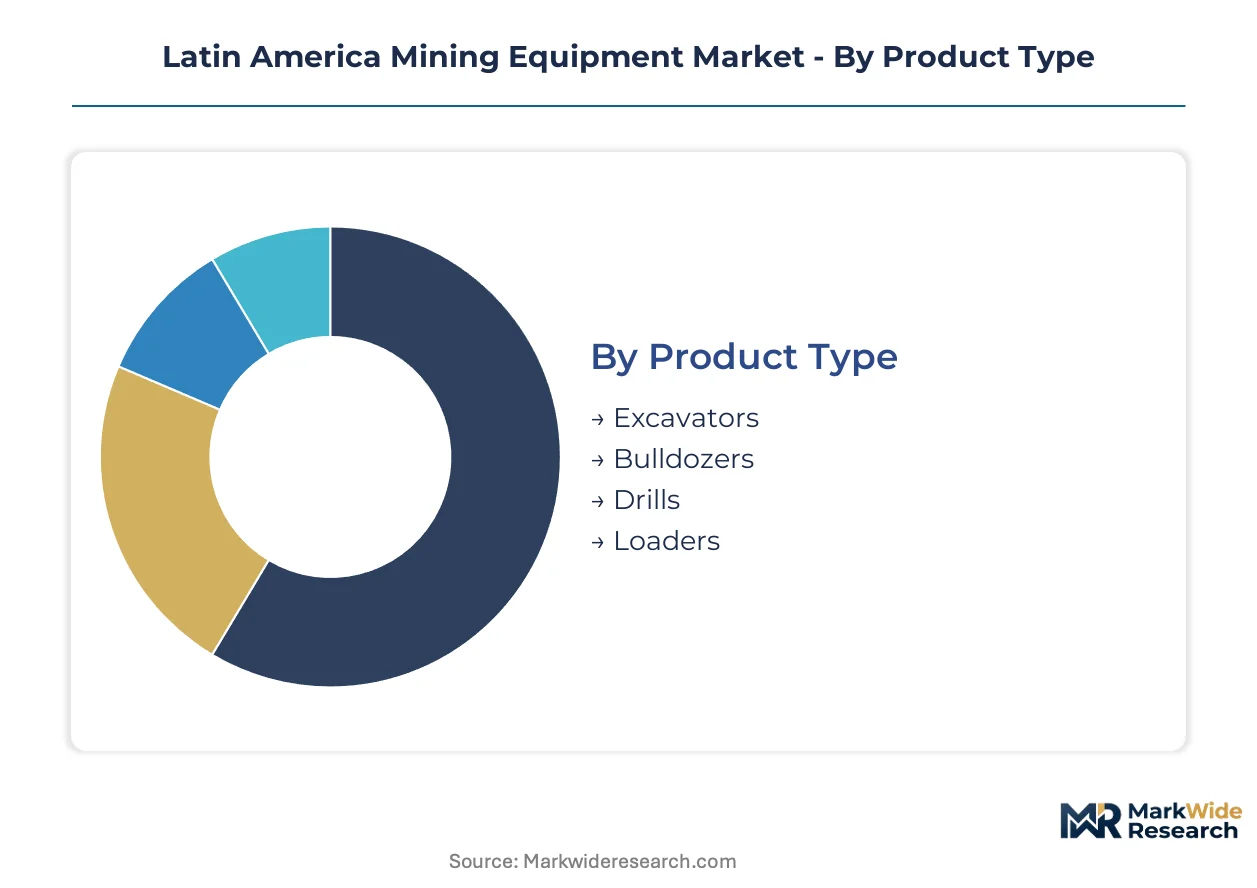
Segmentation in Latin American mining equipment reflects the region's geological diversity and regulatory fragmentation. Equipment specifications must reconcile high-altitude performance requirements in Chile's Atacama with humidity tolerance in Brazil's Carajás basin. Technology choices increasingly hinge on emissions compliance timelines rather than pure operational economics.
Product Type:
Equipment specifications diverge sharply between surface bulk mining and narrow-vein underground extraction, with chassis hardening and cab pressurization becoming non-negotiable above 3,000 meters.
- Excavators:Hydraulic mining shovels with hardened steel undercarriages dominate Chilean open-pit copper operations. Codelco's Escondida and Antofagasta's Los Pelambres specify 400-ton-class units for overburden removal at elevations exceeding 4,000 meters where oxygen-starved combustion demands recalibrated engine management systems.
- Loaders:Underground wheel loaders face accelerating electrification mandates in Peru's polymetallic belt. Battery-electric variants from Sandvik and Epiroc are penetrating Cerro de Pasco and Yauli district operations where ventilation cost reduction and diesel particulate exposure limits create dual conversion incentives.
- Bulldozers:Tracked dozers with specialized ripper configurations handle pre-stripping and haul road maintenance across Brazil's Minas Gerais iron ore districts.
- Drills:Rotary and down-the-hole rigs optimized for hard rock penetration serve Chile's Chuquicamata superpit and Peru's Toromocho porphyry deposits.
Excavators lead on scale; electric loaders lead on momentum.
Technology:
Cost tier stratification separates premium autonomous systems from conventional hydraulics, with mid-market hybrid platforms capturing trial budgets in Brazil's regulatory transition window.
- Automation:Driverless haulage systems with LiDAR terrain mapping and centralized fleet command are retrofitting Chile's deepest open-pit copper mines. Komatsu's FrontRunner and Caterpillar's Command for Hauling compress labor requirements at Escondida and Collahuasi while 5G private networks eliminate latency barriers for remote supervision.
- Electric Drives:Battery-electric powertrains and trolley-assist systems are displacing diesel in underground metal mining. Peru's Ministry of Energy and Mines emissions thresholds accelerate adoption where ventilation infrastructure represents 25-40% of mine development capital.
- Remote Monitoring:Telematics-enabled predictive maintenance contracts penetrate Chile's copper belt as operators seek to minimize unplanned downtime at single-access mine sites.
- Hydraulics:Conventional high-pressure hydraulic systems retain installed base dominance in Brazilian iron ore surface operations where electrification infrastructure remains undeveloped.
Hydraulics retains volume leadership; automation commands the steepest expansion trajectory.
End User:
Application intensity varies by mineral economics, with copper's price resilience sustaining equipment refresh cycles that coal and quarrying cannot match.
- Metal Mining:Copper, gold, and polymetallic extraction drives premium equipment specification across Chile's Atacama, Peru's Andean cordillera, and Brazil's Carajás. Chile's national mining service tailings regulations and Peru's emissions mandates compress replacement cycles for compliant fleet modernization.
- Coal Mining:Colombian Cerrejón and Brazilian Santa Catarina operations favor robust haulers and dozers with dust suppression systems, though thermal coal demand erosion constrains capital deployment.
- Quarrying:Aggregate and dimension stone extraction in São Paulo and Minas Gerais states utilizes mid-size excavators and wheel loaders with shorter depreciation horizons.
- Mineral Exploration:Drill rigs and support vehicles for greenfield copper-gold porphyry targets in Argentina's San Juan and Salta provinces operate on project-specific lease arrangements.
Metal mining anchors equipment demand; exploration exhibits the most volatile procurement patterns.
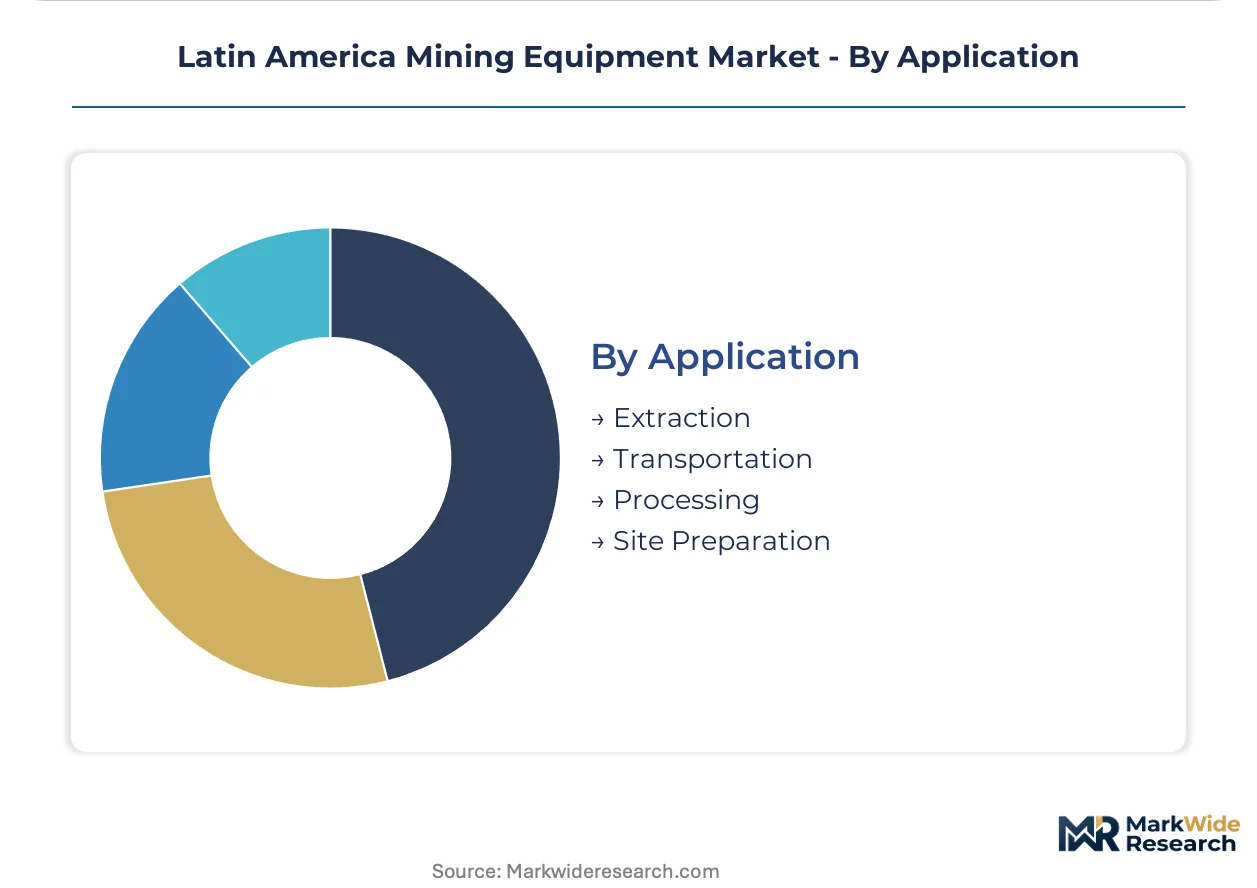
Application:
Volume concentration in extraction and transportation reflects the region's surface mining dominance, while processing equipment ties to concentrator expansion timelines.
- Extraction:Primary rock fracture and ore loading operations specify the largest equipment classes. Chile's open-pit depth extensions at Chuquicamata and Radomiro Tomic require specialized high-altitude excavators and blasthole drills with pressurized cabs.
- Transportation:Autonomous haul truck fleets with 240-400 ton capacity move waste and ore across Chile's superpits. Brazil's ANM closure bond requirements compel longer-life hauler specifications with verified durability metrics.
- Site Preparation:Pre-stripping, haul road construction, and tailings dam earthworks utilize dozers, motor graders, and compactors with integrated monitoring instrumentation under Brazil's dam safety protocols.
- Processing:Crushing, grinding, and materials handling equipment serves concentrator expansions at Cerro Verde, Los Bronces, and Salobo, with procurement tied to brownfield expansion approvals.
Transportation commands capital intensity; extraction maintains the broadest equipment mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean mining engineers and Peruvian equipment technicians anchor Latin America's specialized workforce for high-altitude mineral extraction. Brazilian maintenance specialists support the continent's largest surface iron ore operations. Argentine lithium technicians are emerging around Salta-Jujuy brine projects.
Chile
Copper superpit depth extensions at Chuquicamata and Radomiro Tomic drive demand for pressurized-cab excavators. The national mining service enforces tailings storage facility regulations that broaden markets for safer earthmoving systems. Antofagasta Minerals deploys autonomous haulage at Los Pelambres in the Atacama Desert.
Peru
Narrow-vein polymetallic mining in the Andean cordillera accelerates battery-electric loader adoption. The Ministry of Energy and Mines restricts machinery imports failing updated emissions thresholds. Cerro de Pasco and Yauli district operations cut ventilation costs through electrified drilling rigs.
Brazil
Iron ore corridor expansions in Minas Gerais require longer-life haulers with verified durability metrics. The National Mining Agency mandates progressive decommissioning bonds and closure plans. Vale's Carajás basin operations pilot hybrid excavators switching between grid electricity and diesel.
Argentina
Lithium brine extraction in Salta and Jujuy provinces deploys specialized evaporation pond equipment. Provincial environmental impact assessments require selective extraction pump specifications. Cauchari-Olaroz and Sal de Vida projects anchor battery-grade lithium carbonate production clusters.
Mexico
Gold-silver polymetallic mining in Sonora and Zacatecas sustains underground equipment demand. The Secretariat of Environment and Natural Resources enforces mine closure fund requirements. Fresnillo's Ciénega district operations specify narrow-vein optimized drilling rigs.
Latin America Mining Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Latin America's mining equipment sector. Integrated manufacturers with captive foundry and assembly operations dominate premium autonomous haulage segments. Component suppliers and technology licensors occupy mid-market positions through specialized subsystem partnerships. Strategic moves center on aftermarket service network expansion and high-altitude certification capabilities.
Within the integrated equipment tier, Caterpillar Inc., Komatsu Ltd., and Sandvik AB exemplify divergent competitive positions. Caterpillar leverages extensive dealer networks across the Andean ridge. Komatsu anchors regional positioning through autonomous haulage technology deployment. Sandvik occupies narrow-vein specialization territory in Peruvian polymetallic operations.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Atlas Copco |
| Caterpillar Inc. |
| Volvo Construction Equipment |
| Epiroc AB |
| Komatsu Ltd. |
| Liebherr Group |
| Metso Corporation |
| Sandvik AB |
| Others |
Supply & Pricing Matrix
Metallurgical coal price benchmarks and hardened steel indices cascade through Latin American mining equipment supply chains, compressing margins for mid-tier suppliers while concentrating pricing power with integrated foundry operators capable of absorbing input volatility through captive raw material sourcing.
Pricing Analysis
Bundled full-maintenance lease structures are fragmenting into competitively tendered component rebuilds and field labor packages across Andean copper operations. Pricing stratifies across premium autonomous systems with integrated telemetry, standard hydraulic platforms with dealer service contracts, and economy-tier refurbished units for quarrying applications. Cost compression in the standard tier intensifies as Brazilian iron ore miners demand verified durability metrics under ANM closure bond rules. Exploration contractors exhibit the highest price sensitivity due to project-specific lease arrangements, while Chilean copper majors prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Specialized welding and precision machining workforce availability concentrates in São Paulo state manufacturing corridors, Santiago's industrial suburbs, and Monterrey's equipment assembly clusters. Component sourcing draws from Chinese hydraulic system suppliers, German engine management specialists, and domestic Brazilian steel processors. Single-source vulnerability persists for high-pressure pump assemblies and autonomous haulage sensor modules. Distribution runs through Caterpillar and Komatsu captive dealer networks in Santiago and Lima, with independent parts depots penetrating underserved Brazilian iron ore corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American mining equipment functions as a regulatory compounder where Chile's tailings dam safety overhaul and Peru's emissions mandates continuously force fleet refresh cycles regardless of copper price cycles.
For Market Incumbents: Deepen aftermarket service network density in Brazil's Minas Gerais iron ore districts where independent providers are building certified technician pools to capture unbundled maintenance contracts. Anchor captive foundry capacity for hardened undercarriage steel to offset metallurgical commodity input volatility threatening mid-tier competitors. For New Entrants and Emerging Players: Begin with battery-electric underground loaders for Peru's narrow-vein polymetallic belt where ventilation cost reduction creates dual conversion incentives and established OEMs lack localized service infrastructure. Target provincial environmental certification consultancies in Argentina's Salta-Jujuy lithium corridor as channel partners for evaporation pond equipment specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous haulage technology licensors possessing high-altitude certification capabilities and 5G private network integration expertise. Five-to-ten year viability hinges on regulatory timeline crystallization for diesel phase-outs across Andean jurisdictions. Watch for ANM announcements on progressive electrification mandates as the inflection signal for hybrid platform adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Deployment | Komatsu's FrontRunner systems at Escondida compress labor requirements while raising throughput consistency. |
| Battery-Electric Fleet Conversion | Sandvik's underground loaders cut ventilation costs at Cerro de Pasco operations by eliminating diesel particulate exposure. |
| Aftermarket Service Unbundling | Independent providers building regional parts depots capture competitively tendered work packages from Chilean copper majors. |
| High-Altitude Certification Investment | Pressurized cab and engine recalibration capabilities extend equipment approval cycles by 8-14 months for 3,000-plus-meter operation. |
| Hybrid Platform Pilot Programs | Vale's Carajás basin dual-power excavators hedge against ANM diesel phase-out timelines in Brazil's regulatory roadmap. |
Research Methodology
Coverage spans Chile's Atacama copper belt, Peru's Andean cordillera, Brazil's Minas Gerais iron ore districts, and Argentina's Salta-Jujuy lithium provinces, with primary inputs from each. Mine maintenance directors, OEM procurement teams at Codelco and Antofagasta Minerals, aftermarket service heads, and ANM regulatory affairs officers contributed structured interviews. Secondary validation drew from Chile's national mining service filings, Brazil's National Mining Agency closure bond databases, Peruvian Ministry of Energy and Mines emissions registries, and SEC 10-K equipment supplier disclosures. Bottom-up equipment unit economics triangulated against top-down mineral production forecasts.
Granularity-level modeling distinguished surface bulk mining from narrow-vein underground extraction, with technology choices segmented by automation tier, electrification architecture, and remote monitoring integration. Product type, application intensity, and end-user mineral economics were modeled across the projection horizon. CAGRs derived from equipment replacement cycle compression under regulatory mandates and lithium brine extraction capacity expansion timelines. Forecast inputs incorporated copper price resilience assumptions and Brazilian iron ore corridor depreciation schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Chile-Peru mining labor mobility, abrupt ANM regulatory reversals, and autonomous haulage technology interoperability failures at legacy fleet retrofits. Forecasts reflect documented assumptions on emissions compliance timeline adherence and mineral price stability. Material deviation in copper demand trajectories or Andean diesel phase-out acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Africa Mining Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Drill Pipe Market
Mining Equipment
DTH Drill Market
Mining Equipment
Global Underground Mining Loader Market