
 Mining Drilling Services Market | 2026-2036
Mining Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Drilling Services Market Intelligence
Junior miners and private equity-backed exploration firms are reorganizing procurement priorities toward outsourced drilling partnerships rather than captive fleets. Boart Longyear leverages its global equipment manufacturing base to bundle rig supply with long-term service contracts. Perenti Group anchors its revenue through tier-one iron ore and copper alliances across Australia and Africa. Major Drilling differentiates through deep specialization in complex geotechnical and directional programs where technical risk premiums apply.
Mining drilling services encompass the contracted provision of borehole creation, core recovery, and blasthole preparation using mechanized rigs with specified torque ratings, depth capacities, and sample recovery protocols. Rotary and diamond core methods dominate technical discussions, with reverse circulation gaining favor in greenfields exploration for its speed and cost profile. Exploration drilling commands premium day rates where mineral discovery timelines compress, while production drilling scales through fleet utilization metrics tied to mine plan adherence. Underground drilling grows fastest in base metal corridors, though surface applications still occupy the largest share of deployed capital.
Federal mine safety administrations in Australia, Canada, and Chile enforce operator certification and equipment standards that filter contractor eligibility. ISO 14001 environmental management and jurisdictional mine rehabilitation bonds shape total cost of ownership calculations for drilling procurement. Stakeholders must monitor how automation mandates and emissions thresholds redefine the economic boundary between contract drilling and in-house fleet ownership.
Market Dynamics
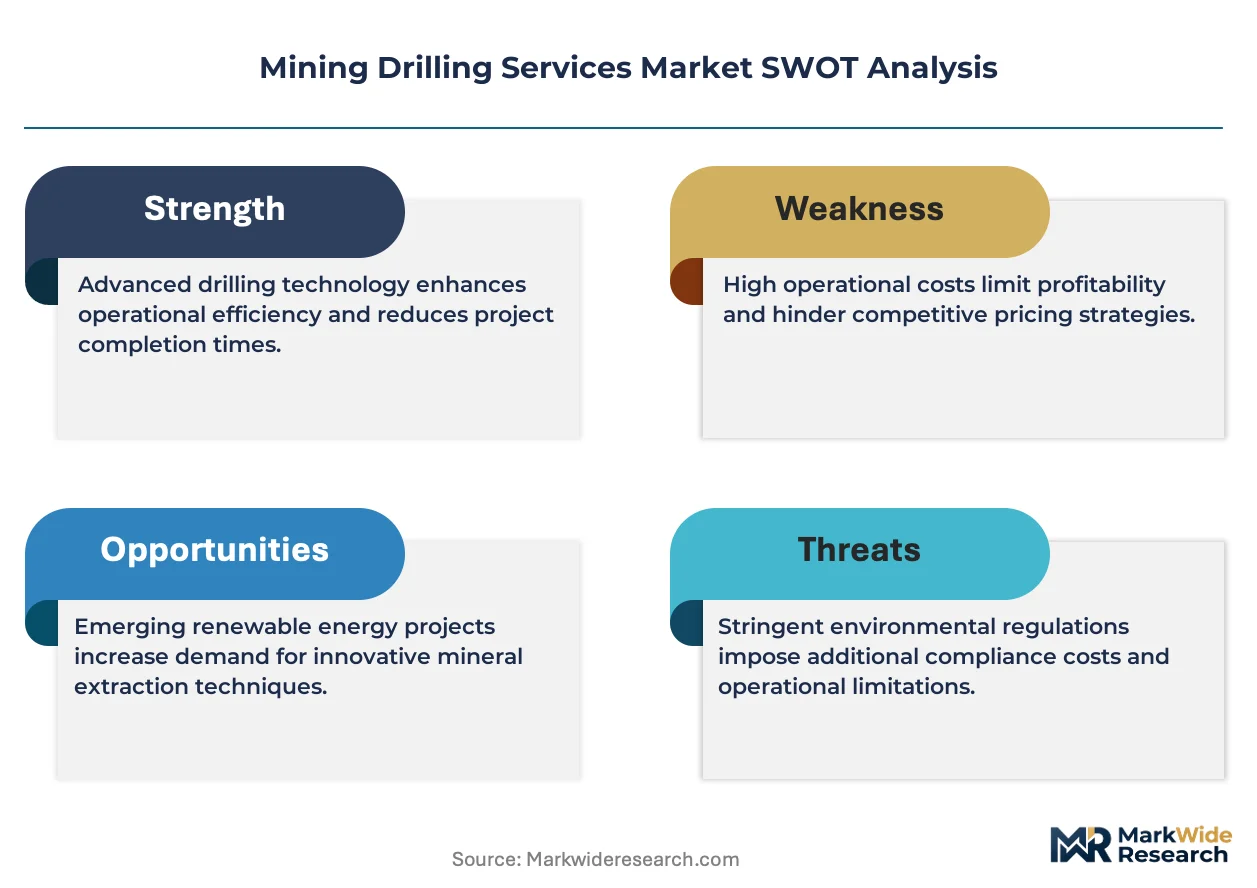
Automation mandates under ISO 18758 and national mining codes are forcing contractors to retrofit legacy fleets with telematics and remote-operated drill rigs, compressing margins while raising technical barriers to contract eligibility.
Growth Catalysts
- Copper-intensive electrification:Grid-scale battery storage and EV manufacturing are accelerating exploration programs in Chilean and Zambian copper belts, where tier-one miners are expanding directional drilling campaigns.
- REACH-aligned environmental protocols:European Union tailings management standards are driving demand for precision blasthole drilling that minimizes overbreak and waste rock generation.
- Reverse circulation speed advantages:Greenfields exploration teams in Australia's Pilbara and Nevada's Great Basin are specifying RC rigs for rapid target delineation where discovery timelines compress.
Market Restraints
- Steel and tungsten carbide input volatility:Drill string and bit manufacturing costs fluctuate with commodity indexes, squeezing day-rate negotiations for fixed-price contracts.
- Specialized rig supply concentration:High-torque underground drill rig production clusters in Sweden and Finland, creating delivery bottlenecks for African and Latin American projects.
- Depth limitation of conventional rotary methods:Ultra-deep targets beyond 2,500 meters require diamond core alternatives that carry higher mobilization costs and slower penetration rates.
Strategic Opportunities
- Underpenetrated lithium triangle expansion:Argentina's Salta and Catamarca provinces are opening to foreign drilling contractors as provincial mining codes liberalize.
- Automation-as-a-service bundling:Contractors can capture recurring revenue by leasing sensor-equipped rigs with predictive maintenance subscriptions rather than pure day-rate models.
- Indonesia's nickel corridor:Laterite nickel projects in Sulawesi and Halmahera are importing Australian directional drilling expertise for resource definition beneath complex cover sequences.
Industry Challenges
- Driller certification bottlenecks:Australia's national mine safety administration and Chile's SERNAGEOMIN impose multi-month qualification timelines that constrain crew scaling during exploration surges.
- Legacy fleet telematics retrofit costs:Mechanical rigs require substantial capital for ISO-compliant automation upgrades, straining balance sheets for mid-tier contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Drilling Services Market |
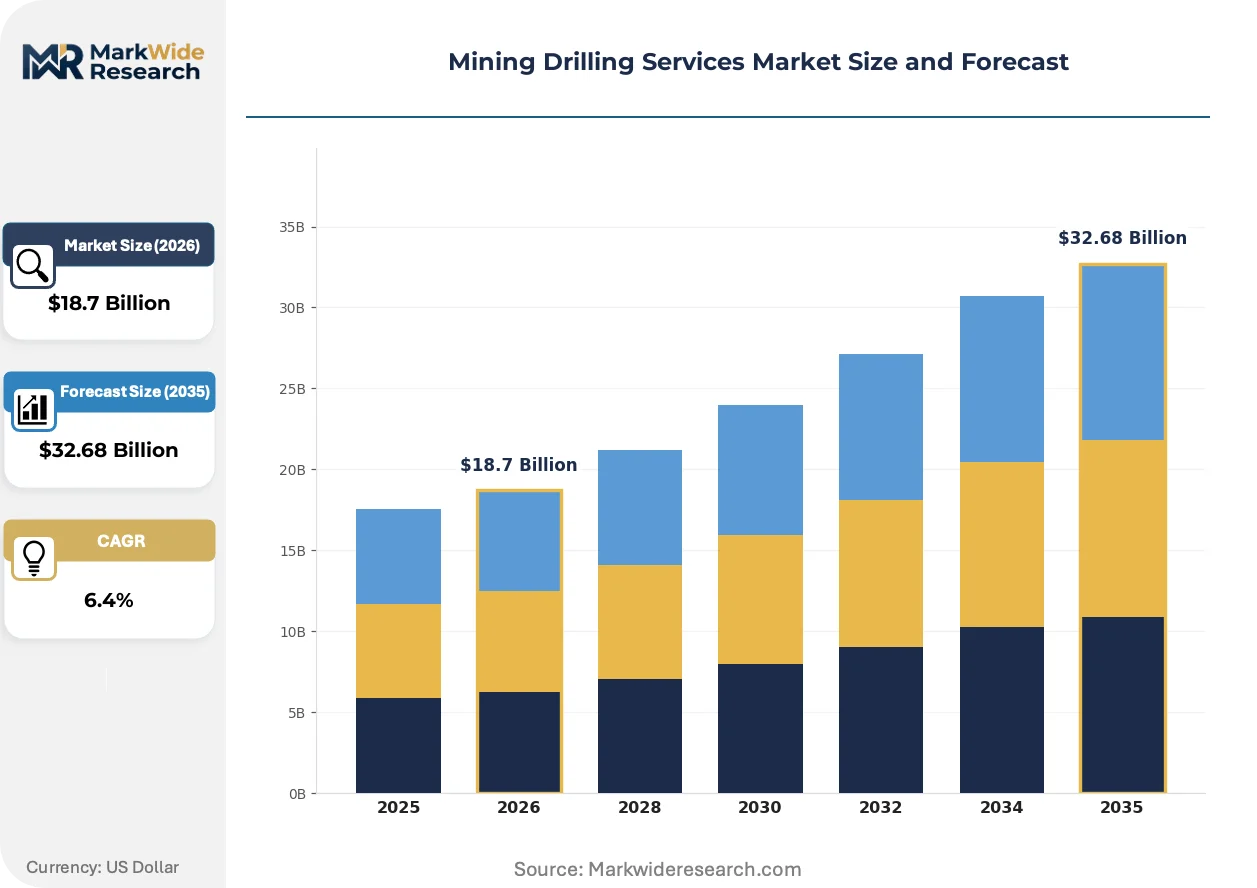
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration Drilling, Production Drilling, Underground Drilling, Directional Drilling Technology: Rotary Drilling, Diamond Core Drilling, Reverse Circulation, Auger Drilling End User: Metal Mining, Coal Mining, Mineral Exploration, Oil Sands Application: Surface Drilling, Underground Mining, Environmental Studies, Geotechnical Investigations |
| Companies Covered | Boart Longyear, Major Drilling, Byrnecut Group, Perenti Group, Capital Drilling, Ausdrill, Action Drill & Blast, Foraco, PT United Tractors Tbk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Drilling Services Market Strategic Shifts & Innovations
Drilling contractors are racing to integrate automation, alternative sample recovery methods, and outcome-based commercial structures that align payment with geological results rather than time on site.
Autonomous rod handling and AI-assisted drill parameter optimization are fragmenting the traditional operator-skill premium that once justified high labor costs. Tier-one iron ore producers in Western Australia's Pilbara are deploying fully remote-operated underground rigs with minimal on-site personnel. This capability compression is enabling contractors to bid lower day rates while maintaining technical performance, squeezing competitors dependent on experienced drill crews.
Canada's provincial mining regulators are harmonizing tailings storage facility design standards with Global Industry Standard on Tailings Management (GISTM) protocols, mandating geotechnical drilling density increases for dam foundation characterization. Copper-gold developers in British Columbia's Golden Triangle are expanding directional drilling programs to satisfy these requirements ahead of permitting timelines. The regulatory drag is lengthening project schedules but expanding addressable drilling meters per development.
Junior miners are unbundling long-term drilling relationships in favor of spot-market contracting through digital procurement platforms that aggregate rig availability across multiple contractors. Western Australian gold explorers are sourcing capacity through these channels during seasonal drilling windows rather than maintaining captive fleets or exclusive partnerships. This transactional pivot is compressing contractor visibility into forward workload and intensifying price competition for visible tenders.
Mining Drilling Services Market Segmentation
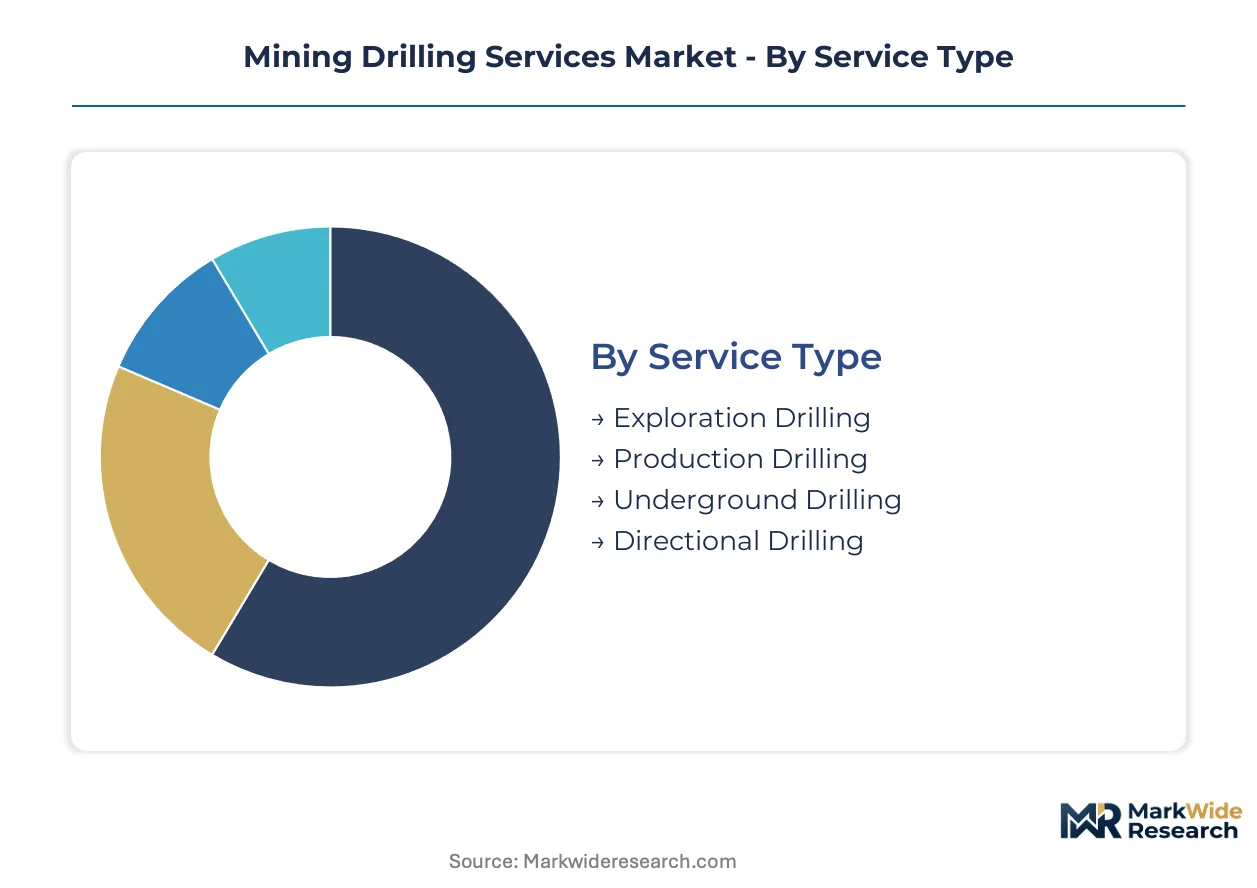
Contractor profitability in mining drilling services hinges on matching technical capabilities to specific geological and operational contexts. Segmentation reveals where specialized equipment investments yield premium day rates versus commoditized volume plays.
Service Type:
Margin pools concentrate where technical complexity creates barriers to entry and justifies risk-adjusted pricing.
- Exploration Drilling:Core recovery and borehole creation for resource definition, utilizing diamond core and reverse circulation methods. Premium day rates apply in Chilean copper belts and Australian lithium provinces where discovery timelines compress and mineral tenure deadlines loom.
- Production Drilling:Blasthole preparation aligned with mine plans and ore control requirements. Iron ore majors in Western Australia's Pilbara drive volume demand through fleet utilization contracts tied to stripping ratios and ore grade targets.
- Underground Drilling:Mechanized borehole execution in confined stoping environments. Base metal corridors in Zambia and Canada are expanding specialized contractor fleets for narrow-vein extraction.
- Directional Drilling:Deviated and horizontal borehole trajectories for complex geometry targets. Geotechnical dam characterization for tailings storage facilities in British Columbia and Chile is expanding addressable meters under GISTM-aligned regulations.
The dominant share belongs to Production Drilling, while Directional Drilling is expanding most quickly as regulatory density increases.
Technology:
Equipment selection determines penetration rates, sample quality, and total program cost structure across varying overburden and rock competence conditions.
- Rotary Drilling:Conventional tricone and PDC bit methods for blasthole and shallow exploration applications. Surface iron ore and coal operations in Australia and Indonesia specify rotary rigs for cost-efficient bulk meterage where sample recovery precision is secondary.
- Diamond Core Drilling:Wireline retrieval systems using impregnated bits for intact core recovery. Ultra-deep targets beyond 2,500 meters in Canadian gold camps and African copper belts require diamond core for geological confidence.
- Reverse Circulation:Dual-wall drill string with pneumatic sample return for rapid target delineation. Nevada's Great Basin gold explorers and Western Australian greenfields teams specify RC for speed advantages in early-stage resource definition.
- Auger Drilling:Continuous flight or hollow-stem methods for unconsolidated overburden and regolith. Laterite nickel projects in Indonesia's Sulawesi employ auger rigs for shallow resource definition beneath complex cover sequences.
Rotary Drilling maintains volume leadership, though Reverse Circulation is gaining share fastest in greenfields exploration procurement.
End User:
Customer type dictates contract duration, technical specification intensity, and counterparty risk profiles.
- Metal Mining:Copper, gold, nickel, and lithium developers with multi-year mine life requirements. Tier-one majors in Chile and Australia anchor contractor revenue through tiered alliance structures with volume commitments.
- Coal Mining:Thermal and metallurgical coal producers with cyclical capital deployment. Indonesian and Australian coal basins drive seasonal demand spikes tied to export price cycles and domestic power procurement.
- Mineral Exploration:Junior miners and private equity-backed ventures with finite funding horizons. Spot-market contracting through digital procurement platforms is compressing contractor visibility in this segment.
- Oil Sands:Bitumen extraction operators in Alberta requiring specialized large-diameter drilling. Steam-assisted gravity drainage projects demand precision wellbore placement for thermal efficiency optimization.
Metal Mining commands the largest contractor wallet share, with Mineral Exploration showing the steepest expansion trajectory as lithium and copper discovery programs accelerate.
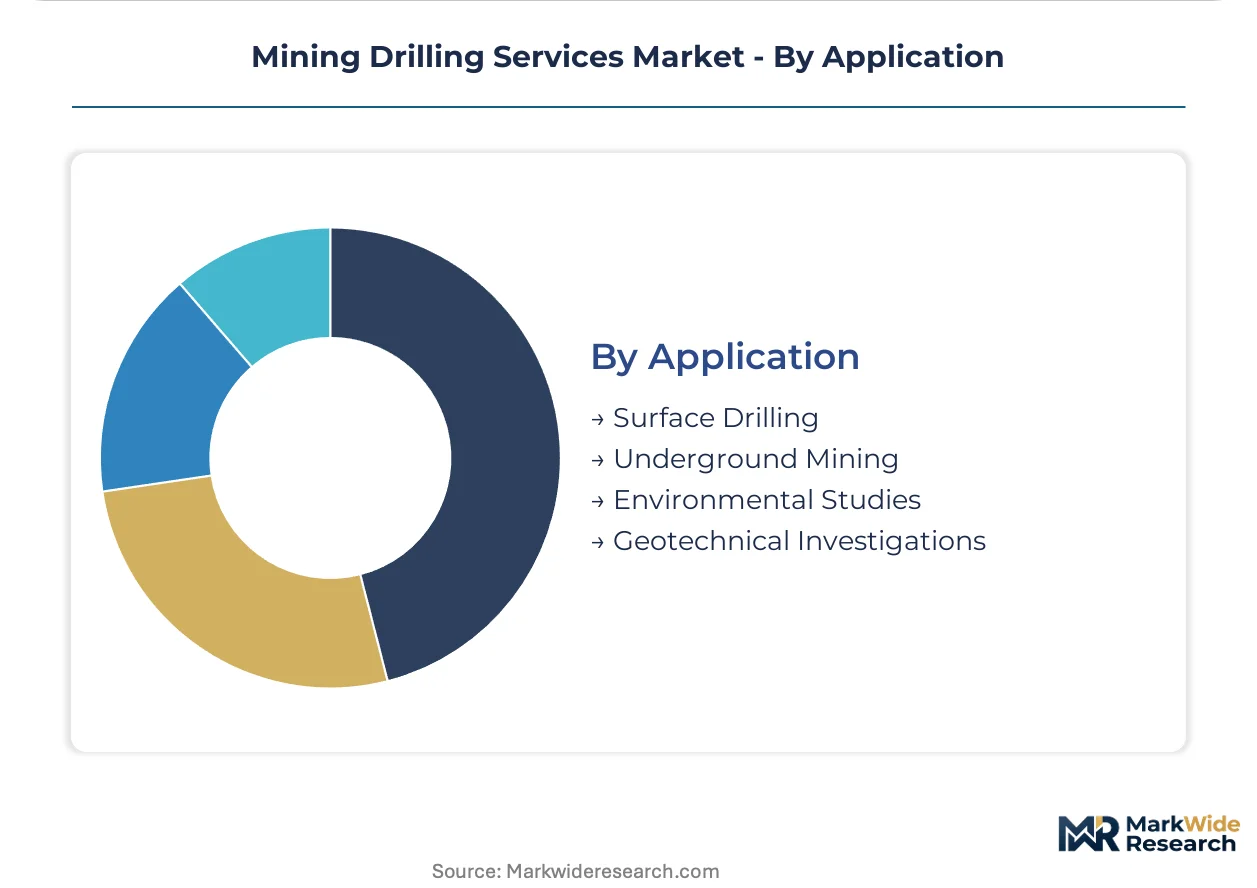
Application:
Operating environment determines rig mobility requirements, safety protocols, and automation integration priorities.
- Surface Drilling:Open-pit and plains-based operations with established access infrastructure. Pilbara iron ore and Chilean copper porphyry deposits deploy the largest surface rig fleets with telematics-enabled remote operation.
- Underground Mining:Confined-space borehole execution with ventilation and ground support constraints. Canadian base metal mines and Australian gold operations are retrofitting fleets for ISO-compliant automation.
- Environmental Studies:Contamination assessment and closure planning boreholes. Alberta's oil sands reclamation and Australian mine rehabilitation bonds are expanding meterage for baseline and post-closure monitoring.
- Geotechnical Investigations:Foundation characterization for tailings dams, waste dumps, and infrastructure. GISTM-aligned dam safety standards in Canada and Chile are mandating increased drilling density for slope stability assessment.
Surface Drilling retains the dominant equipment deployment base, while Geotechnical Investigations is climbing the fastest as tailings regulation tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-torque drill rig manufacturing clusters in Sweden and Finland create supply-side chokepoints for contractors serving African and Latin American projects. Australia's Pilbara and Chile's Atacama concentrate the bulk of active fleet deployment for copper and iron ore expansion programs.
Australia
Western Australia's Pilbara iron ore majors are expanding autonomous blasthole drilling fleets under ISO 18758 automation mandates. The country's national mine safety administration enforces driller certification timelines that constrain crew scaling during exploration surges. Perth-based contractors anchor revenue through tiered alliance structures with volume commitments to BHP and Rio Tinto.
Chile
Copper porphyry developers in the Atacama are accelerating directional drilling campaigns to meet electrification-driven demand timelines. SERNAGEOMIN imposes multi-month qualification protocols that filter contractor eligibility for underground programs. Antofagasta and Calama host the densest concentration of active rigs serving Codelco and private copper developers.
Canada
British Columbia's Golden Triangle copper-gold developers are expanding geotechnical drilling density to satisfy GISTM-aligned tailings dam standards ahead of permitting. Provincial mining regulators harmonize tailings storage facility design with Global Industry Standard protocols. Vancouver anchors contractor headquarters for programs spanning the Yukon and Northwest Territories.
Indonesia
Laterite nickel projects in Sulawesi and Halmahera are importing Australian directional drilling expertise for resource definition beneath complex cover sequences. The country's mining ministry is liberalizing foreign contractor access for critical mineral corridor development. Morowali Industrial Park concentrates processing infrastructure that drives upstream exploration drilling demand.
Zambia
Copper belt expansion programs are drawing specialized underground drilling contractors for narrow-vein extraction in the Copperbelt Province. The national mining code is tightening environmental bond requirements for exploration tenure retention. Kitwe and Ndola serve as logistics hubs for cross-border equipment mobilization serving DRC extensions.
Mining Drilling Services Market Key Industry Players
Concentration sits with integrated rig manufacturers and specialized underground contractors rather than pure-play service providers. Tier-one iron ore and copper alliances in Australia and Africa anchor revenue for scale-driven operators, while mid-tier players compete on spot-market pricing through digital procurement platforms. Two strategic archetypes dominate: vertically integrated manufacturers bundling equipment supply with long-term service contracts, and technical specialists commanding risk-adjusted premiums for complex geotechnical and directional programs. Competitive moves center on automation retrofit partnerships and outcome-based commercial structures that align payment with geological results.
Among Australia-based contractors, Perenti Group and Ausdrill exemplify the scale-driven archetype through fleet utilization contracts tied to major iron ore and copper producers. Boart Longyear represents the integrated manufacturing-service model, leveraging global equipment production to bundle rig supply with multi-year drilling agreements. Major Drilling occupies a position within the technical specialization tier, differentiating through deep expertise in complex directional and geotechnical programs where discovery timelines and regulatory compliance create pricing premiums.
| Leading Market Players |
|---|
| Boart Longyear |
| Major Drilling |
| Byrnecut Group |
| Perenti Group |
| Capital Drilling |
| Ausdrill |
| Action Drill & Blast |
| Foraco |
| PT United Tractors Tbk |
| Others |
Cost & Logistics Intelligence
ISO 18758 automation mandates gate both contractor eligibility and day-rate premiums simultaneously, compressing margins for non-compliant fleets while rewarding telematics-equipped operators with risk-adjusted pricing in Australian and Chilean procurement frameworks.
Pricing Analysis
ISO 18758 dictates the pricing tier structure across the mining drilling services landscape. Three-tier pricing structure across premium, standard, and economy levels separates automation-compliant contractors from legacy fleet operators and spot-market entrants. Price differentiation hinges on certification grade and volume scale, with tier-one iron ore alliances commanding committed utilization rates. Cost compression in the economy tier is intensifying because junior miners are unbundling long-term relationships for digital platform procurement. Mineral exploration firms exhibit the highest price sensitivity, while copper majors in Chile demonstrate the least.
Supply Chain Analysis
Inventory lead times for high-torque underground drill rigs now stretch twelve to eighteen months from Swedish and Finnish manufacturing clusters. Geographic supply concentration centers on Sweden, Finland, and Australia for specialized rig production. Raw material dependencies draw from tungsten carbide bit manufacturing, steel drill string supply, and hydraulic component fabrication. Single-source vulnerability sits with the Nordic rig production base serving African and Latin American projects. Distribution runs through Perth, Santiago, and Vancouver as contractor logistics hubs anchoring regional fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining drilling services market sits in early-cycle expansion as copper-intensive electrification and lithium discovery programs accelerate contract awards across underpenetrated jurisdictions.
For Market Incumbents: Fortify automation compliance ahead of ISO 18758 enforcement timelines to defend contract eligibility against emerging technology specialists. Deepen backward integration into rig manufacturing through partnerships with Swedish equipment producers. Prioritize crew certification pipelines to overcome Australian and Chilean qualification bottlenecks during exploration surges.
For New Entrants and Emerging Players: Differentiate on automation-as-a-service bundling rather than pure day-rate competition to capture recurring revenue streams. Target Argentina's Salta and Catamarca provinces as the most penetrable geography following provincial mining code liberalization. Pursue spot-market digital platform integration as the primary go-to-market angle for junior miner procurement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automation retrofit requirements and telematics fleet upgrades. Long-term viability favors contractors with committed tier-one alliances and technical specialization moats in directional drilling. Monitor crew certification backlog durations as the critical inflection signal for supply-demand imbalance.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Fleet Retrofit | ISO 18758 compliance secures contract eligibility with Chilean copper majors and Australian iron ore producers. |
| Backward Integration Partnership | Equipment manufacturing alliances with Nordic producers reduce lead time exposure for African project mobilization. |
| Automation-as-a-Service Launch | Predictive maintenance subscriptions transform day-rate models into recurring revenue anchored to sensor-equipped rigs. |
| Geographic Expansion | Argentine lithium province entry captures liberalized foreign contractor access ahead of competitor positioning. |
| Technical Specialization Acquisition | Directional drilling expertise commands risk-adjusted premiums in GISTM-aligned geotechnical dam characterization programs. |
Research Approach
Initial hypotheses were tested against primary input from drilling contractors, mine planning engineers, procurement managers at tier-one miners, and fleet operations directors, then refined through secondary validation. Primary fieldwork drew from rig operators in Western Australia's Pilbara, Chile's Atacama, and British Columbia's Golden Triangle. Secondary sources encompassed SERNAGEOMIN regulatory filings, Australian national mine safety administration standards, Global Industry Standard on Tailings Management protocols, and equipment manufacturer production disclosures. Bottom-up rig deployment tallies were triangulated against top-down contract value estimates.
Variance decomposition across service type, technology, end user, and application segments shaped the analytical framework over the projection horizon. Modeled dimensions spanned exploration versus production drilling, rotary versus diamond core versus reverse circulation methods, and surface versus underground operating environments. CAGRs were derived from fleet utilization trajectories tied to mine plan adherence and discovery timeline compression. Industry-specific inputs included copper price sensitivity for Chilean contract awards and lithium tenure deadline pressure for Argentine exploration pacing.
Decision-makers should treat outputs as directional under sustained copper electrification demand and stable automation regulatory trajectories; material deviation in commodity cycles or certification timeline shifts would warrant model refresh. Specific risks include steel and tungsten carbide input volatility, Nordic rig supply bottlenecks, and drainer certification backlog extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Smart Mining Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Africa Mining Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Asia Pacific Mining Equipment Market