
 Asia Pacific Mining Equipment Market | 2026-2036
Asia Pacific Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Mining Equipment Market Outlook
Tier-4 equivalent engine specifications is reorganizing procurement priorities across the Asia Pacific mining equipment sector. Komatsu Ltd. leverages its integrated powertrain manufacturing to dominate Japanese and Australian markets with low-emission excavator lines. SANY Heavy Industry Co Ltd anchors its position through cost-engineered automation packages tailored for Chinese surface coal sites. Caterpillar Inc. competes via aftermarket parts density and dealer coverage across Indonesian nickel and Mongolian copper belts.
Asia Pacific mining equipment encompasses heavy machinery engineered for mineral extraction, earthmoving, and material handling, typically operating at engine outputs exceeding 250 kW and designed for continuous-duty cycles in abrasive environments. The primary industrial purpose centers on enabling efficient, safe, and scalable removal of overburden and ore across surface and subsurface operations. Excavators and loaders command the largest installed base due to their versatility across coal and metal mining applications, while automation technology represents the fastest-expanding margin pool as operators pursue remote-operation capabilities for hazardous underground environments. Drilling machines retain stable replacement demand in resource exploration, though hybrid systems are displacing conventional diesel units in regulatory-sensitive jurisdictions.
China's MIIT enforces GB standards on non-road mobile machinery emissions, compelling domestic and imported equipment to adopt electric-hybrid powertrains or face market exclusion. Australia's state-level mining safety regulators, alongside Japan's METI energy-efficiency frameworks, shape product certification requirements that differentiate export-ready manufacturers from regional assemblers. India's BIS and CEA are developing alignment protocols for mining electrification that will condition import access. Stakeholders must weigh the capital cost of automation and hybrid technology against the regulatory compliance timeline and residual value risk in secondhand equipment markets.
Market Dynamics
China's MIIT emissions enforcement is decomposing diesel-heavy procurement patterns across the Asia Pacific mining equipment sector, forcing fleet operators toward electric-hybrid architectures and compressing residual values for conventional powertrains.
Growth Catalysts
- GB standards compliance:China's MIIT mandates on non-road mobile machinery emissions compel domestic and imported equipment to adopt electric-hybrid powertrains, creating forced replacement cycles across surface and underground coal operations.
- Nickel extraction concentration:Indonesia's nickel processing sector concentrates orders for large-scale excavators and integrated haul systems as downstream battery material demand pulls upstream mining investment.
- Automation technology:Remote-operation capabilities for hazardous underground environments represent the fastest-expanding margin pool as Australian safety regulators mandate reduced human exposure in coal and metal mines.
Market Restraints
- Powertrain cost volatility:Battery cell and rare earth magnet input costs fluctuate with Chinese domestic pricing policies, compressing margins for electric-hybrid equipment manufacturers serving price-sensitive Indonesian and Mongolian operators.
- Dealer network concentration:Aftermarket parts density clusters in Australian and Japanese metropolitan hubs, leaving remote Indonesian nickel sites and Mongolian copper belts exposed to extended downtime risk from sparse service coverage.
- Residual value uncertainty:Tier-4 equivalent engine specifications create stranded asset risk for secondhand diesel equipment, deterring capital deployment from fleet operators with 7-10 year replacement horizons.
Strategic Opportunities
- Indian electrification alignment:India's BIS and CEA are developing mining electrification protocols that will condition import access, creating first-mover advantage for manufacturers pre-certified to emerging standards.
- Autonomous haulage convergence:Integration of LiDAR perception systems with 5G pit-to-port connectivity enables fully autonomous truck fleets in Australian iron ore operations, opening recurring software revenue streams.
- Remanufacturing channel innovation:Component remanufacturing networks in Thailand and Malaysia offer lower-carbon fleet refresh options for Indonesian and Vietnamese contractors facing capital constraints.
Industry Challenges
- Automation skill scarcity:Remote-operation centers require technicians proficient in both mining engineering and network systems administration, a hybrid competency scarce across Australian, Indonesian, and Mongolian labor markets.
- Legacy fleet integration:Retrofitting autonomous haulage compatibility into existing truck fleets demands proprietary interface protocols that fragment interoperability between Komatsu, Caterpillar, and SANY equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Mining Equipment Market |
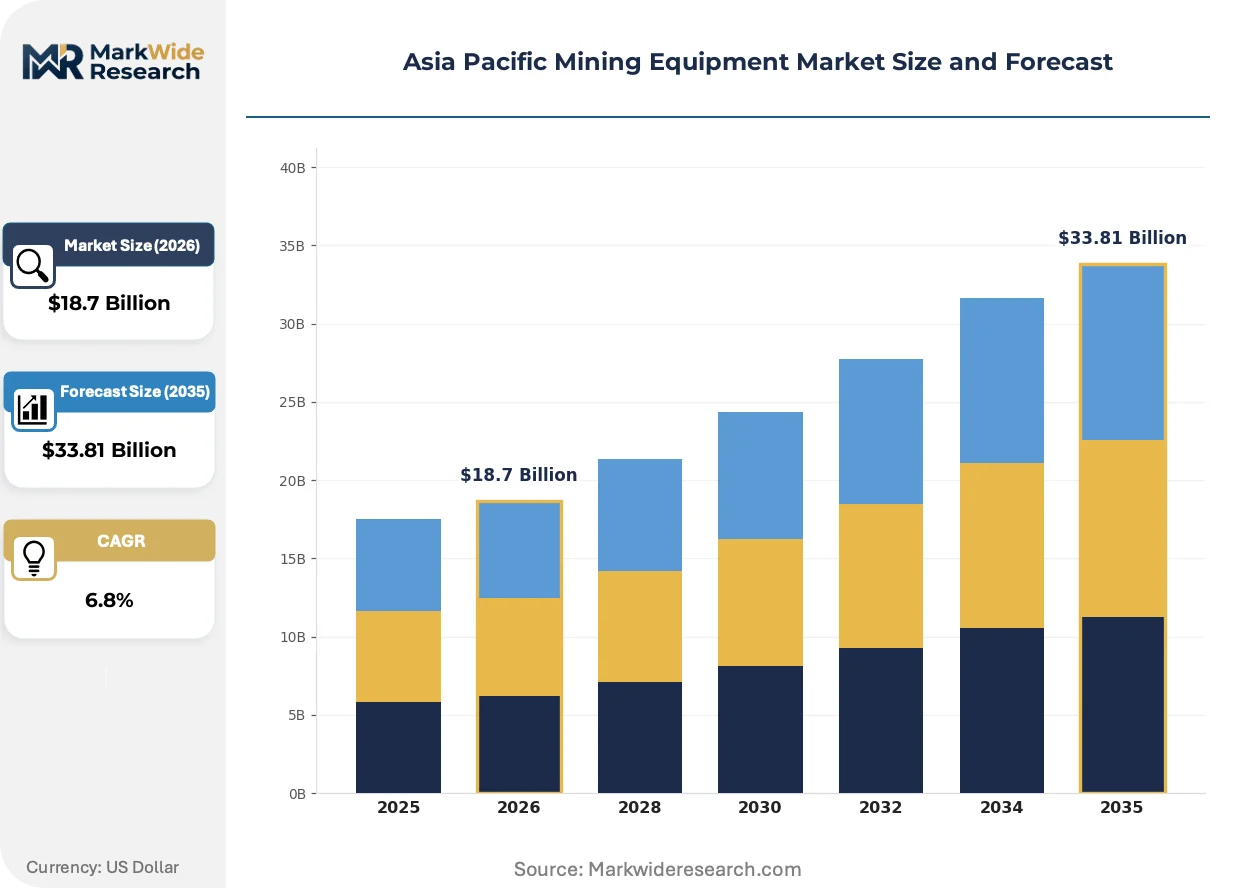
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Drilling Machines, Loaders, Crushers Technology: Automation, Remote Monitoring, Hybrid Systems, Wearable Tech End User: Coal Mining, Metal Mining, Mineral Extraction, Quarrying Application: Surface Mining, Underground Mining, Resource Exploration, Reclamation |
| Companies Covered | Volvo Construction Equipment, SANY Heavy Industry Co Ltd, Caterpillar Inc., Liebherr Group, XCMG Group, Komatsu Ltd., Doosan Infracore, Sandvik AB, Hitachi Construction Machinery Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Mining Equipment Market Strategic Shifts
Electrification architecture is actively decomposing established powertrain supply relationships across the Asia Pacific mining equipment sector, while regulatory enforcement compresses technology adoption timelines and procurement patterns fragment across national compliance regimes.
Electric-hybrid loader technology is decomposing conventional diesel engine demand in Chinese surface coal operations. State-owned mining conglomerates are adopting 250 kW+ electric-hybrid excavators at replacement cycle acceleration. The technology is decomposing Komatsu's historical powertrain integration advantage by forcing open battery and motor supplier relationships.
Japan's METI energy-efficiency frameworks now mandate incremental fuel consumption reductions for imported mining equipment, reshaping product certification requirements that differentiate export-ready manufacturers from regional assemblers. Australian state-level mining safety regulators parallel this with autonomous operation mandates for underground coal. Underground loader segments in both jurisdictions face compressed certification timelines for remote-capable equipment.
After-sales service unbundling is disrupting traditional dealer-dependent maintenance relationships in Indonesian nickel and Mongolian copper operations. Fleet operators are purchasing components directly from manufacturer digital platforms, bypassing distributor markup. This pattern is most visible in Australian iron ore sites where autonomous haulage uptime requirements exceed dealer response capacity.
Asia Pacific Mining Equipment Market Segmentation
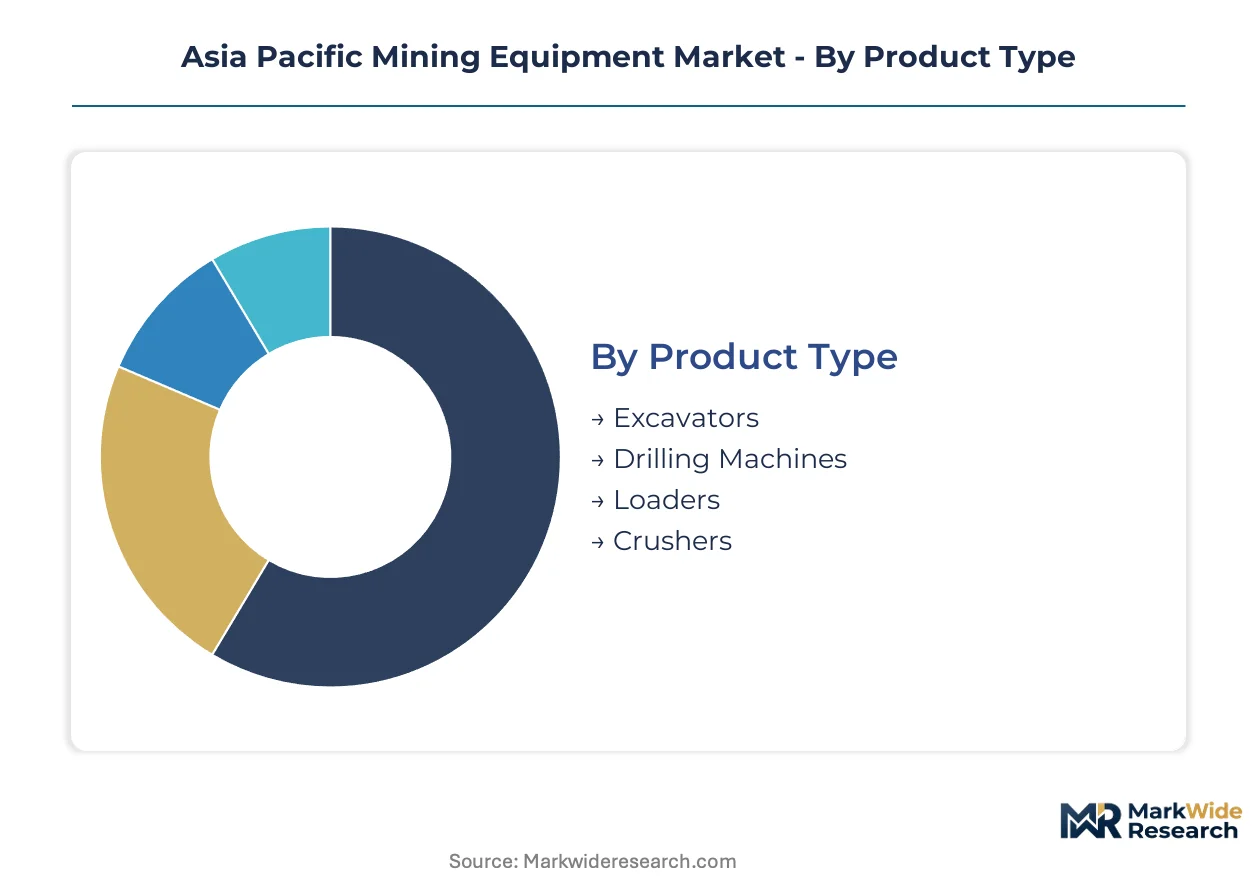
Segmentation reveals how procurement channels fragment across powertrain technologies and regulatory jurisdictions in the Asia Pacific mining equipment sector. Equipment flows through distinct distribution pathways based on automation integration levels and compliance certification tiers.
Product Type:
Channel mix varies sharply by equipment scale, with integrated haul systems moving through manufacturer-direct relationships while standard excavators and loaders flow through regional dealer networks.
- Excavators:Hydraulic systems exceeding 250 kW dominate fleet renewal cycles in Australian underground coal and Indonesian nickel surface operations. Komatsu and SANY compete through differentiated powertrain architectures as China's MIIT emissions enforcement accelerates electric-hybrid model procurement across Chinese state-owned mining conglomerates.
- Loaders:Underground variants face compressed certification timelines from Australian state safety regulators mandating remote-operation capabilities. Electric-hybrid loader technology is displacing conventional diesel demand in Chinese surface coal sites as GB standards compliance becomes a procurement gate.
- Drilling Machines:Exploration rigs retain stable replacement demand through manufacturer service contracts in Australian and Mongolian copper belts.
- Crushers:Mobile crushing units concentrate orders through Indonesian contractor fleets serving downstream nickel processing investments.
Excavators dominate installed base. Loaders are where expansion concentrates.
Technology:
Cost tier stratification separates premium automation packages from standard remote-monitoring configurations, with hybrid powertrains occupying a mid-tier pricing band shaped by battery input volatility.
- Automation:LiDAR perception systems integrated with 5G pit-to-port connectivity enable fully autonomous haulage in Australian iron ore operations. This segment commands the steepest expansion trajectory as safety regulators mandate reduced human exposure in hazardous underground environments across Australian and Chinese jurisdictions.
- Hybrid Systems:Electric-hybrid architectures combine battery-electric powertrains with range-extending diesel generators, addressing range constraints in remote Indonesian nickel sites. Battery cell and rare earth magnet costs fluctuate with Chinese domestic pricing policies, compressing margins for manufacturers serving price-sensitive operators.
- Remote Monitoring:Telematics platforms enable predictive maintenance across dispersed Mongolian copper fleets where dealer service density remains sparse.
- Wearable Tech:Personal safety devices integrate with mine-wide communication networks in Japanese underground limestone operations.
Automation commands premium pricing tiers. Hybrid systems are gaining share fastest.
End User:
Application intensity varies by mineral type, with coal operations driving fleet standardization while metal mining demands customized automation integration.
- Coal Mining:Surface and underground coal operations in China and Australia generate the largest equipment procurement volumes. China's MIIT emissions mandates are forcing replacement cycles toward electric-hybrid excavators and remote-capable loaders.
- Metal Mining:Indonesian nickel extraction concentrates orders for large-scale excavators and integrated haul systems as battery material demand pulls upstream investment. Australian iron ore sites pioneer autonomous haulage deployment.
- Mineral Extraction:Mongolian copper belts rely on durable diesel-heavy fleets where electrification infrastructure remains underdeveloped.
- Quarrying:Vietnamese limestone and aggregate operations source cost-optimized equipment through Thai and Malaysian remanufacturing channels.
Coal mining anchors procurement volume. Metal mining is where technology premium concentrates.
Application:
Geographic concentration shapes equipment specification, with Australian underground coal driving safety-automation integration and Indonesian surface nickel demanding high-availability haul systems.
- Surface Mining:Large-scale excavators and autonomous haul trucks operate in Australian iron ore and Indonesian nickel sites. After-sales service unbundling is disrupting traditional dealer relationships as fleet operators purchase components directly from manufacturer digital platforms.
- Underground Mining:Confined-space operations in Australian coal and Chinese metal mines mandate remote-operation capabilities. Safety regulators compress certification timelines for autonomous loader deployment.
- Resource Exploration:Drilling machine demand clusters in Mongolian copper greenfield developments and Australian mineral prospecting.
- Reclamation:Rehabilitation equipment procurement follows mine closure schedules across Indonesian nickel and Vietnamese coal sites.
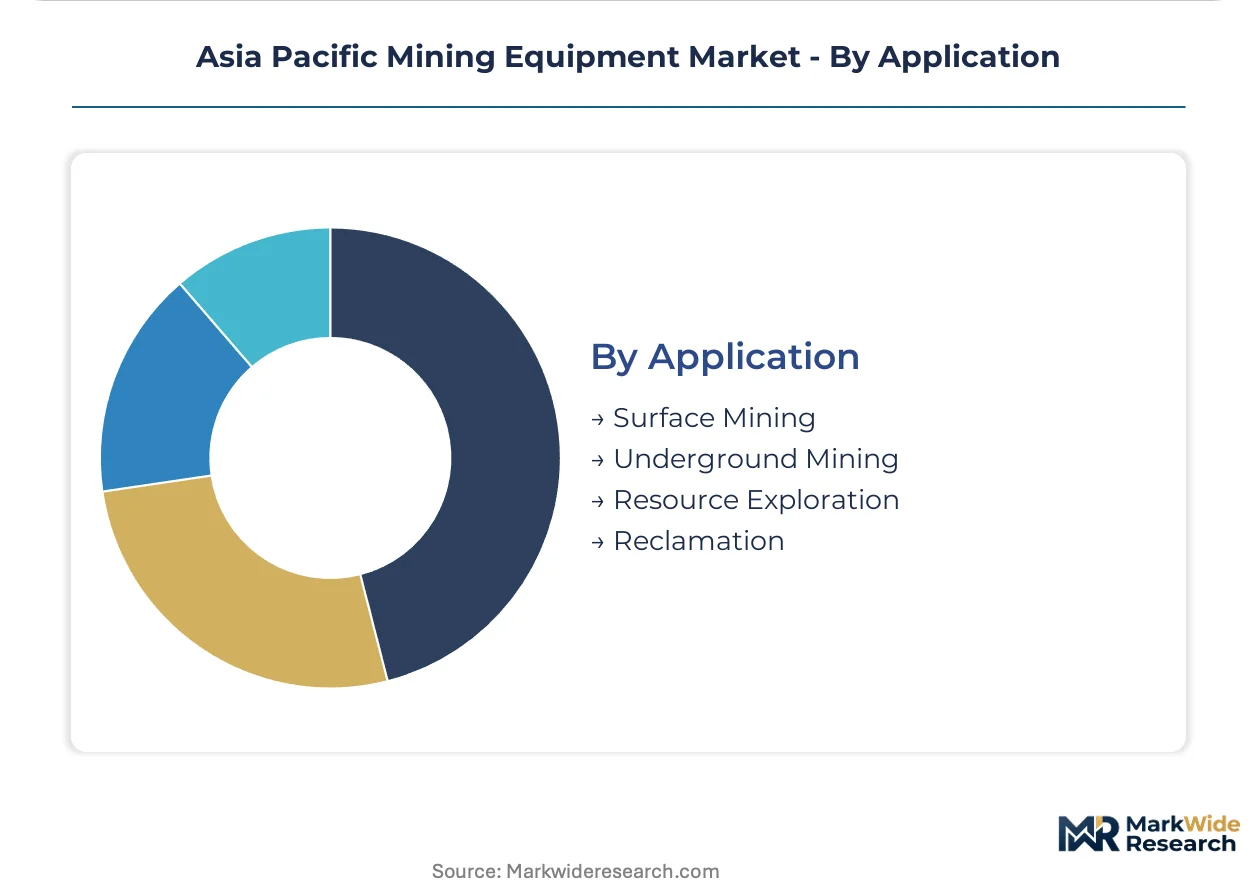
Surface mining dominates capital deployment. Underground mining is where regulatory compliance costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing capacity clusters in Japan and China, with Australian demand pulling premium automation systems and Indonesian nickel expansion driving heavy excavator procurement. National emissions frameworks fragment procurement patterns across the region.
China
State-owned mining conglomerates accelerate replacement cycles for 250 kW+ electric-hybrid excavators as MIIT enforces GB standards on non-road mobile machinery emissions. Domestic manufacturers capture surface coal procurement through cost-engineered automation packages. Shandong and Jiangsu provinces concentrate heavy machinery production clusters serving both domestic and export markets.
Australia
Underground coal operations in Queensland and New South Wales drive fleet renewal demand for remote-capable loaders as state safety regulators mandate reduced human exposure. Western Australian iron ore sites pioneer autonomous haulage deployment with LiDAR-integrated truck fleets. Perth anchors aftermarket service density for dispersed Pilbara operations.
Indonesia
Downstream battery material investment pulls upstream nickel mining expansion, concentrating orders for large-scale excavators and integrated haul systems in Sulawesi and Halmahera operations. Sparse dealer coverage across remote island sites exposes operators to extended downtime risk. Jakarta-based contractors increasingly source components directly from manufacturer digital platforms.
Japan
METI energy-efficiency frameworks mandate incremental fuel consumption reductions for mining equipment certification, differentiating export-ready manufacturers from regional assemblers. Domestic manufacturers leverage integrated powertrain manufacturing for low-emission excavator lines serving Australian and Southeast Asian markets. Nagoya and Osaka metropolitan areas concentrate precision component suppliers.
India
BIS and CEA are developing mining electrification alignment protocols that will condition import access for foreign equipment manufacturers. Surface coal operations in Jharkhand and Odisha generate procurement volume for standard excavators and loaders. First-mover advantage accrues to manufacturers pre-certified to emerging standards.
Asia Pacific Mining Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific mining equipment sector. Japanese and European manufacturers anchor premium automation and electrification tiers, while Chinese and South Korean fabricators dominate mid-market volume through scale economies. The competitive structure separates integrated powertrain specialists from component-assembly operations. Dominant competitive moves include backward integration into battery and motor supply chains and strategic partnerships for autonomous haulage software licensing.
Among Japanese manufacturers, Komatsu Ltd. and Hitachi Construction Machinery Co Ltd exemplify the integrated powertrain archetype with captive manufacturing of engines and hydraulic systems. SANY Heavy Industry Co Ltd represents the cost-engineered automation tier, anchoring Chinese state-owned mining procurement through domestically produced electric-hybrid platforms. These three companies illustrate how geographic origin and manufacturing structure map to distinct competitive positioning across emissions-compliant and price-sensitive market segments.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| SANY Heavy Industry Co Ltd |
| Caterpillar Inc. |
| Liebherr Group |
| XCMG Group |
| Komatsu Ltd. |
| Doosan Infracore |
| Sandvik AB |
| Hitachi Construction Machinery Co Ltd |
| Others |
Value Chain & Pricing Dynamics
China's MIIT GB standards for non-road mobile machinery emissions gate both supplier qualification and price differentiation simultaneously, compelling equipment manufacturers to absorb hybrid powertrain premiums or surrender market access.
Pricing Analysis
GB standards compliance dictates the pricing tier structure across the Asia Pacific mining equipment sector. Three-tier pricing structure across premium automation, certified hybrid, and conventional diesel levels separates Komatsu's integrated powertrain offerings from SANY's cost-engineered automation packages and unbranded regional assemblers. Price differentiation rests on certification grade and after-sales service density. Cost compression in the conventional diesel tier is intensifying because stranded asset risk deters fleet operators with extended replacement horizons. Indonesian nickel contractors exhibit highest price sensitivity due to capital constraints, while Australian iron ore operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
China and Japan anchor heavy machinery manufacturing clusters serving Asia Pacific mining demand. Battery cell production draws from Chinese domestic suppliers, while precision hydraulic components feed from Nagoya and Osaka metropolitan areas. Rare earth magnet sourcing hinges on Chinese domestic pricing policies. Single-source vulnerability concentrates in battery cell supply for electric-hybrid architectures. Distribution runs through manufacturer-direct relationships for integrated haul systems and regional dealer networks for standard excavators and loaders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific mining equipment market represents an early-cycle electrification expansion story, with GB standards enforcement accelerating replacement cycles beyond historical baselines.
For Market Incumbents: Fortify backward integration into battery and motor supply chains to offset input cost volatility from Chinese domestic pricing policies. Deepen captive production of range-extending generator sets for hybrid architectures serving remote Indonesian nickel sites. Lock in long-term service contracts with Australian state-owned mining operators before autonomous haulage software licensing fragments dealer relationships. For New Entrants and Emerging Players: India's BIS and CEA certification fast-track offers first-mover positioning ahead of formal electrification protocol implementation. Target Mongolian copper belt contractors with durable diesel-heavy fleets where electrification infrastructure remains underdeveloped. Pursue component remanufacturing partnerships with Thai and Malaysian facilities to serve capital-constrained Vietnamese limestone operators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric-hybrid equipment manufacturing due to battery cell and rare earth magnet input exposure. Long-term viability favors manufacturers with captive powertrain integration or locked-in raw material offtake agreements. Acquisition target archetype: mid-tier automation specialists with pre-certified remote-operation platforms for Australian underground coal. Signal to watch: Australian state safety regulator mandates for autonomous loader deployment accelerating beyond current certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive cell production insulates margin compression from Chinese domestic pricing volatility. |
| Autonomous Haulage Software Licensing | Recurring revenue streams attach to LiDAR-integrated truck fleets in Australian iron ore. |
| Remanufacturing Network Partnerships | Thai and Malaysian facilities offer lower-carbon refresh options for Indonesian contractors. |
| Indian Electrification Pre-Certification | BIS and CEA alignment protocols condition import access for early-compliant manufacturers. |
| Direct-to-Operator Digital Platforms | Component sales bypass dealer markup in Australian iron ore uptime-critical environments. |
Study Parameters
Initial hypotheses were tested against primary input from mining fleet operations managers, OEM procurement directors, aftermarket service heads, and state mining safety regulators and refined through secondary validation. Mining fleet operations managers provided replacement cycle and technology adoption timelines. OEM procurement directors detailed powertrain sourcing strategies and supplier qualification criteria. Aftermarket service heads illuminated dealer network density gaps across remote Indonesian and Mongolian sites. State mining safety regulators clarified certification timeline compression for autonomous equipment. Secondary sources included customs and trade data on heavy machinery imports, SEC 10-K filings from listed manufacturers, and mining industry association production statistics. Bottom-up equipment unit economics and top-down regional market sizing were triangulated.
Variance decomposition across product type, powertrain technology, automation integration level, end-use mineral category, and national regulatory jurisdiction shaped the analytical framework. CAGRs were derived from replacement cycle modeling, emissions compliance deadline impacts, and downstream battery material demand pull-through. Mine-level capital expenditure plans and fleet operator survey data on technology readiness informed trajectory assumptions.
Underlying assumptions cover GB standards enforcement timelines, battery cell cost curves, and autonomous haulage adoption rates across Australian iron ore, with deviation risk concentrated in Chinese domestic pricing policy shifts and Indonesian nickel investment cycles. Recalibration cycles align with material shifts in national emissions enforcement and safety regulator mandate announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mining Drill Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Hydraulic Drilling Rig Market