
 Aftercoolers Market | 2026-2036
Aftercoolers Market Size, Share, and Industry Trends Forecast 2026-2036
Aftercoolers Market Analysis
Asset-light compressor leasing and pay-per-use service contracts is rewriting competitive entry barriers for aftercooler suppliers. Atlas Copco AB leverages its captive rental fleet to bundle cooling hardware with compressed air service agreements. Kaeser Kompressoren SE anchors its position through direct channel control and regional service density. Parker-Hannifin Corporation competes via aftermarket parts dominance and distribution breadth across industrial clusters.
An aftercooler is a heat exchanger that removes moisture and reduces discharge temperature from compressed air systems, typically operating between 80°F and 120°F outlet conditions to protect downstream pneumatic equipment. The device prevents condensation damage in manufacturing lines, instrumentation, and process control loops. Air-cooled configurations lead volume in remote or water-scarce installations where infrastructure simplicity outweighs thermal efficiency tradeoffs. Water-cooled variants capture margin pools in continuous-process industries such as power generation and petrochemicals where waste heat recovery economics improve total cost of ownership. Shell-and-tube technology dominates heavy-duty mining and automotive stamping applications requiring pressure ratings above 250 psig.
The EPA enforces discharge temperature limits under Clean Air Act stationary source provisions, compelling facility operators to retrofit legacy compressor stations with compliant cooling stages. OSHA's compressed air safety standards for worker exposure and equipment guarding shape product design specifications and installation protocols. ISO 8573 air quality classes for moisture content drive specification behavior across European and North American procurement departments. Stakeholders must monitor how carbon border adjustment mechanisms and industrial emissions tracking requirements alter total cost calculations for cooling system investments.
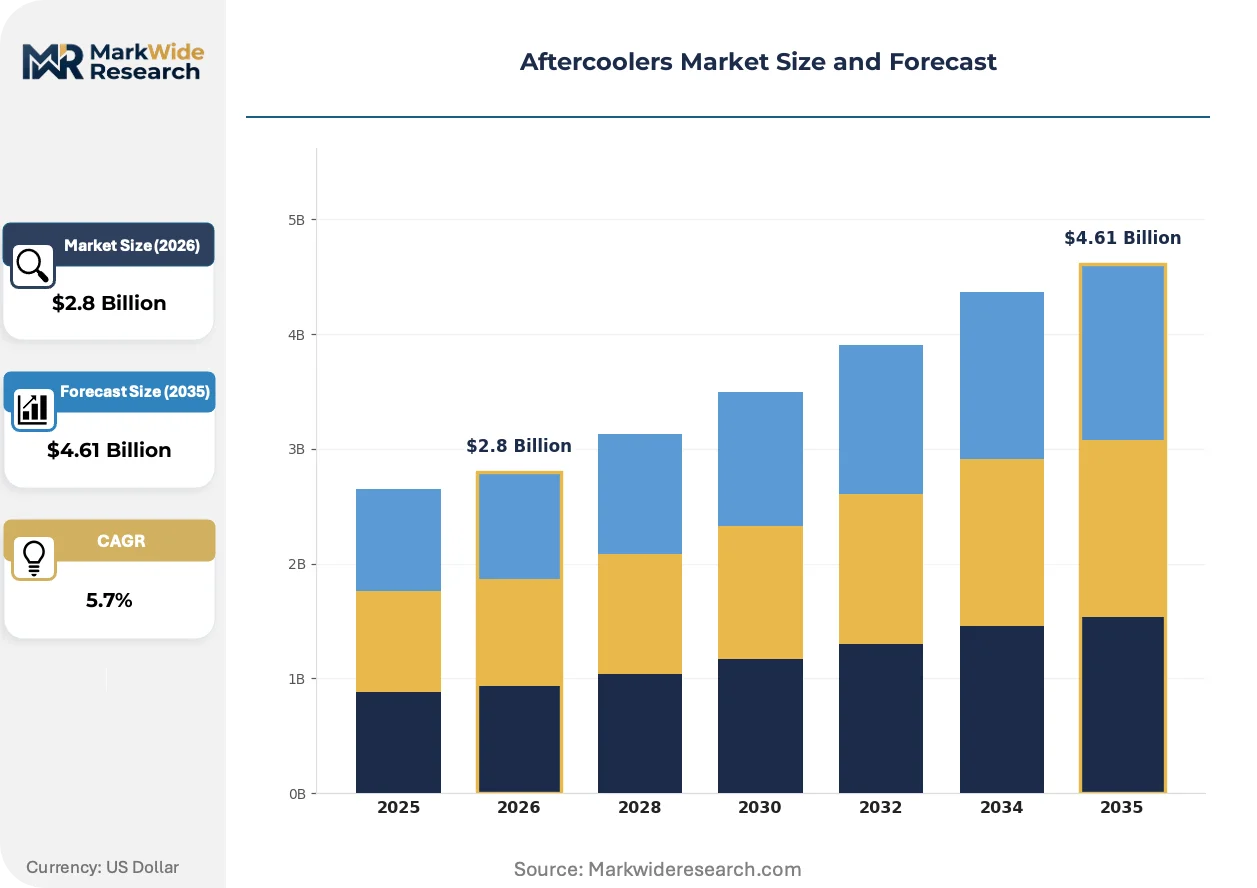
Market Dynamics
Compressed air system operators face mounting pressure from EPA Clean Air Act enforcement to retrofit legacy cooling stages with higher-efficiency aftercooler technology, reshaping capital allocation across manufacturing infrastructure.
Growth Catalysts
- EPA Clean Air Act stationary source provisions:Discharge temperature limits compel facility operators to upgrade compressor stations with compliant cooling equipment, creating replacement demand across industrial clusters.
- Automotive stamping and heavy mining:Shell-and-tube aftercooler configurations capture specification wins where pressure ratings exceed 250 psig and thermal loads are continuous.
- China's industrial infrastructure renewal:State-directed manufacturing modernization accelerates adoption of water-cooled variants in continuous-process industries seeking waste heat recovery economics.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger fabrication depends on non-ferrous metals whose commodity swings compress margin visibility for OEMs and fabricators.
- Water-scarce region limitations:Air-cooled configurations dominate remote installations where thermal efficiency tradeoffs are unavoidable, capping addressable market for higher-margin water-cooled systems.
- ISO 8573 certification timelines:Air quality class compliance for moisture content extends procurement cycles and delays revenue recognition for suppliers targeting European and North American specification departments.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU emissions tracking requirements alter total cost calculations for cooling system investments, favoring suppliers with verified lifecycle data.
- Pay-per-use service contracts:Asset-light compressor leasing models create bundled hardware opportunities for aftercooler suppliers aligned with rental fleet operators.
- Power generation waste heat recovery:Petrochemical and utility sectors seek integrated cooling solutions that improve total cost of ownership through energy capture.
Industry Challenges
- Field service technician scarcity:Installation and maintenance of shell-and-tube systems in high-pressure environments requires specialized pressure vessel certification that outpaces training pipeline output.
- Legacy pneumatic equipment integration:Downstream instrumentation and process control loops in brownfield manufacturing lines demand custom outlet conditioning that extends engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aftercoolers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Oil-Cooled, Heat Exchanger Technology: Plate, Shell-and-Tube, Spiral, Fin Tube End User: Manufacturing, Power Generation, Mining, Automotive Application: Compressed Air Systems, Refrigeration, HVAC, Industrial Processes |
| Companies Covered | Atlas Copco AB, Ingersoll Rand Inc., Parker-Hannifin Corporation, Kaeser Kompressoren SE, Sullair LLC, Hitachi Industrial Equipment Systems Co., Ltd., FS-Elliott Co., LLC, Gardner Denver, Caterpillar, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aftercoolers Market Emerging Trajectories
Sensor integration and predictive maintenance architectures are rewriting how aftercooler performance is monitored and monetized across industrial compressed air networks.
Smart heat exchanger systems with embedded IoT temperature and pressure sensors are digitizing condition monitoring for moisture removal efficiency. Food and beverage processors with stringent air quality requirements are piloting these configurations to preempt condensation damage. The technology is digitizing service revenue models by enabling remote diagnostics that reduce unplanned downtime penalties in continuous manufacturing.
OSHA compressed air safety standards for worker exposure and equipment guarding are tightening installation protocol requirements across US manufacturing facilities. Facility safety officers now specify guarded fan assemblies and accessible drain points as standard procurement criteria. Metal fabrication and automotive assembly plants are responding by consolidating supplier lists to vendors with certified installation training programs.
Compressed air service unbundling is fragmenting traditional hardware-procurement relationships in European industrial clusters. End-users are separating cooling equipment purchase from compressor maintenance contracts, forcing aftercooler suppliers to establish direct specification influence with energy managers. This pattern is most visible in German automotive supply chains where total cost of ownership modeling has displaced single-source bundling.
Aftercoolers Market Segmentation
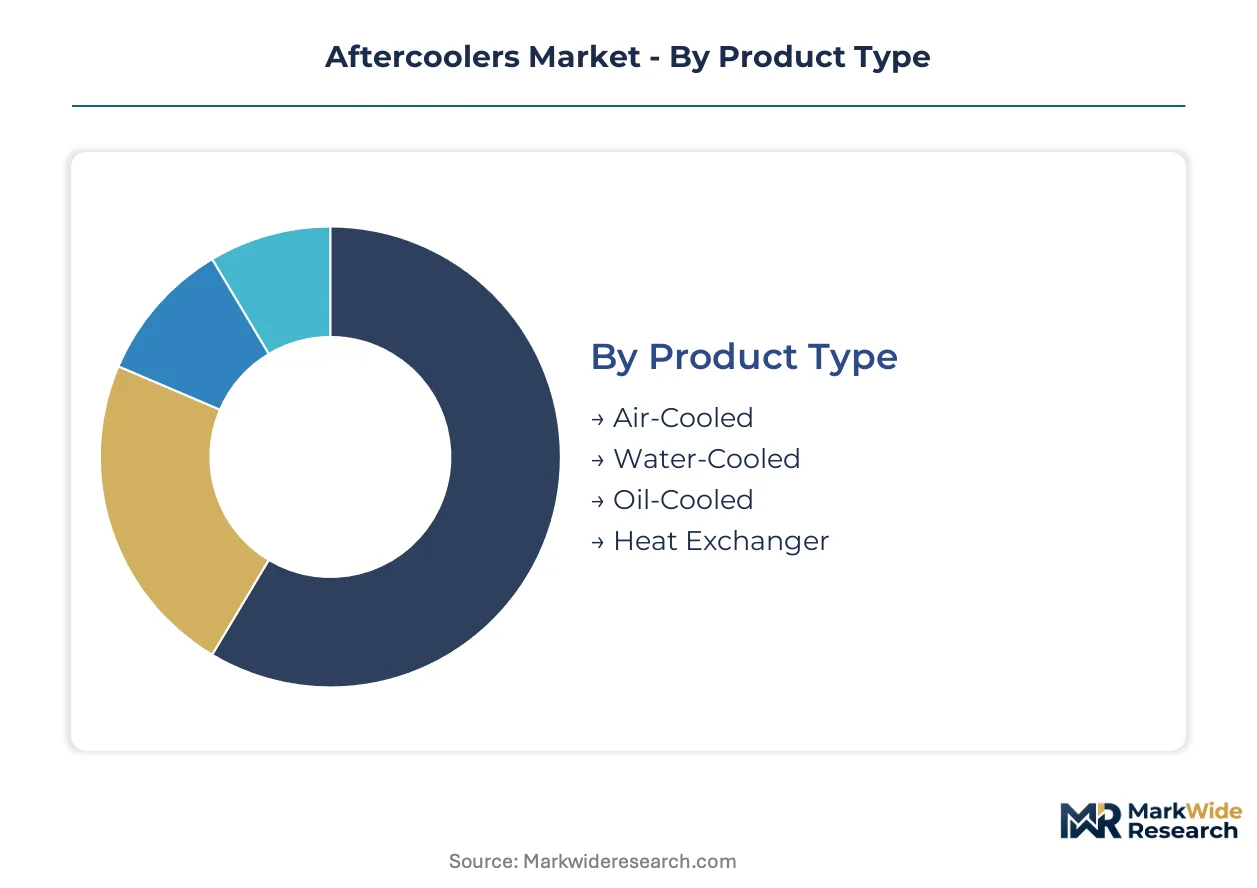
Aftercooler procurement patterns diverge sharply across cooling media, heat exchanger architecture, and end-use intensity. Each segment carries distinct service contract attach rates and lifecycle revenue profiles that reshape supplier economics.
Product Type:
Service intensity climbs with thermal load duty cycles and infrastructure complexity, creating aftermarket revenue ladders that vary by cooling medium.
- Air-Cooled:Aluminum-finned tube bundles with forced convection deliver 80°F to 120°F outlet temperatures without water infrastructure. Demand concentrates in Arizona, Nevada, and Saudi Arabia mining corridors where water scarcity eliminates liquid-cooled alternatives. Copper price volatility compresses fabrication margins for OEMs serving these remote installations.
- Water-Cooled:Shell-and-tube or plate configurations achieve superior thermal efficiency through cooling tower integration. Chinese petrochemical clusters and German automotive stamping plants specify these variants where waste heat recovery improves total cost of ownership calculations. Higher capital outlay is offset by energy capture economics in continuous-process environments.
- Oil-Cooled:Closed-loop lubrication systems serve high-pressure hydraulic circuits in heavy mining equipment. Australian iron ore operations and Canadian oil sands projects drive specification.
- Heat Exchanger:Modular plate-and-frame designs enable capacity scaling in food and beverage processing. ISO 8573 air quality compliance extends procurement cycles for European dairy and brewing facilities.
By volume, Air-Cooled leads. By growth pace, Water-Cooled is expanding most quickly.
Technology:
Heat transfer coefficient and pressure rating requirements fragment specification behavior across industrial clusters with divergent operating envelopes.
- Plate:Corrugated stainless steel plates deliver turbulent flow and compact footprint for HVAC and refrigeration applications. German commercial building retrofits and Japanese precision manufacturing facilities favor these configurations where space constraints dominate.
- Shell-and-Tube:Robust cylindrical pressure vessels withstand ratings above 250 psig in automotive stamping and heavy mining. US OSHA pressure vessel certification requirements extend installation timelines but lock in long-term service relationships for qualified technicians.
- Spiral:Self-cleaning flow paths handle fouling-prone cooling media in wastewater treatment and pulp processing. Nordic district heating networks pilot these for geothermal brine applications.
- Fin Tube:Extended surface area maximizes air-side heat transfer in remote compressor stations. Texas Permian Basin oilfield operations and Kazakhstan pipeline infrastructure specify these for maintenance accessibility.
Shell-and-Tube commands the premium tier. Plate technology is gaining share fastest in building services.
End User:
Capital expenditure cycles and regulatory exposure create distinct purchasing rhythms across industrial verticals.
- Manufacturing:Compressed air quality requirements under EPA Clean Air Act enforcement drive retrofit demand across US Midwest metal fabrication and assembly plants. Brownfield instrumentation integration extends engineering cycles for custom outlet conditioning.
- Power Generation:Combined-cycle gas turbine plants and waste-to-energy facilities seek integrated cooling with heat recovery. Chinese state-directed infrastructure renewal accelerates water-cooled adoption in utility-scale installations.
- Mining:24/7 operating intensity and remote location logistics favor air-cooled durability. Chilean copper belt and South African platinum operations specify shell-and-tube configurations for pressure resilience.
- Automotive:Stamping press pneumatic systems require moisture protection for precision tooling. German supply chain unbundling separates cooling hardware procurement from compressor service contracts.
Manufacturing generates the largest installed base. Power Generation shows the steepest expansion trajectory.
Application:
Moisture removal efficiency standards and operating temperature bands segment specification behavior across process-critical systems.
- Compressed Air Systems:Primary aftercooler function protecting downstream pneumatic equipment from condensation damage. EPA discharge temperature limits compel US facility upgrades.
- Refrigeration:Interstage cooling in industrial refrigeration cycles. Cold storage logistics expansion in India and Southeast Asia drives specification.
- HVAC:Building climate control with air quality compliance. EU Energy Performance of Buildings Directive shapes European procurement criteria.
- Industrial Processes:Custom thermal management in chemical and pharmaceutical production. FDA process validation requirements extend qualification timelines for US drug manufacturing.
Compressed Air Systems anchors volume. Industrial Processes delivers the highest margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented compressor manufacturers in Germany and China supply aftercooler hardware to water-scarce mining corridors in Chile and Australia, while US facilities import European-engineered shell-and-tube systems for automotive stamping retrofits.
United States
EPA Clean Air Act stationary source enforcement compels Midwest metal fabrication plants to upgrade compressor cooling stages. OSHA pressure vessel certification requirements extend installation timelines but lock in long-term service relationships. Texas Permian Basin oilfield operations specify fin-tube configurations for maintenance accessibility in remote compressor stations.
Germany
Automotive supply chain unbundling separates cooling hardware procurement from compressor service contracts in Baden-Württemberg stamping plants. EU Energy Performance of Buildings Directive shapes procurement criteria for commercial building retrofits. Bavarian precision manufacturing facilities favor compact plate configurations where space constraints dominate specification behavior.
China
State-directed manufacturing modernization accelerates water-cooled adoption in Yangtze River Delta petrochemical clusters seeking waste heat recovery economics. MIIT industrial efficiency mandates drive replacement cycles in legacy compressor stations. Shandong Peninsula heavy industry corridors specify shell-and-tube systems for continuous-process thermal loads.
Australia
Water scarcity across Western Australian iron ore operations eliminates liquid-cooled alternatives, concentrating demand on air-cooled durability. Queensland mining logistics favor aluminum-finned tube bundles with forced convection for 80°F to 120°F outlet conditioning. Pilbara Basin remote infrastructure constraints prioritize maintenance accessibility over thermal efficiency tradeoffs.
Chile
Copper belt mining operations in Antofagasta Region specify shell-and-tube configurations for pressure resilience above 250 psig. National mining regulator enforcement of discharge temperature limits accelerates cooling stage retrofits. Atacama Desert water scarcity cements air-cooled dominance despite thermal efficiency penalties in 24/7 operating environments.
Aftercoolers Market Vendor Landscape
On the supply side, the industry is consolidating around captive rental fleet operators and aftermarket parts specialists, with three strategic archetypes emerging: integrated compressor OEMs bundling cooling hardware with service agreements, standalone heat exchanger fabricators serving specification-driven process industries, and regional service networks capturing installation and maintenance revenue. Dominant competitive moves include backward integration into heat exchanger fabrication and geographic expansion through distributor acquisition in industrial clusters.
Among integrated compressor OEMs, Atlas Copco AB and Kaeser Kompressoren SE exemplify the bundled-service archetype, leveraging captive rental fleets to anchor cooling hardware within compressed air service contracts. Parker-Hannifin Corporation occupies a position in the aftermarket-dominated tier, with distribution breadth across industrial clusters supporting specification influence with procurement departments.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| Parker-Hannifin Corporation |
| Kaeser Kompressoren SE |
| Sullair LLC |
| Hitachi Industrial Equipment Systems Co., Ltd. |
| FS-Elliott Co., LLC |
| Gardner Denver |
| Caterpillar, Inc. |
| Others |
Supply Flow & Price Mechanics
Copper and aluminum concentration in Chilean mining corridors and Chinese smelting complexes directly determines margin capture downstream, with heat exchanger fabricators in Germany and the United States absorbing commodity volatility through long-term offtake contracts or captive recycling streams.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 8573 certification grade and volume scale, with certified suppliers commanding 15-20% premiums over uncertified competitors. Cost compression in economy-tier air-cooled configurations is intensifying because Chinese fabricators are scaling plate-and-frame production. Procurement departments at automotive stamping plants show least price sensitivity due to unplanned downtime penalties, while remote mining operators in water-scarce regions prioritize durability over upfront cost.
Supply Chain Analysis
Copper cathode and aluminum coil feedstock dependence draws from Chile, Peru, and Australian concentrate streams before Chinese and German rolling mill processing. Shell-and-tube pressure vessel fabrication relies on seamless steel tubing from Japanese and South Korean mills. Single-source vulnerability concentrates in high-grade copper cathode supply, where Chilean state miner output disruptions ripple through heat exchanger lead times. Distribution runs through captive OEM service networks for bundled compressor contracts, with independent aftermarket channels serving brownfield retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance subscriptions and remote monitoring contracts are expanding faster than hardware replacement cycles, rewarding suppliers who digitize condition monitoring before competitors consolidate platform control.
For Market Incumbents: Pre-empt emerging IoT-native entrants by embedding sensor architectures into shell-and-tube systems before ISO 8573 compliance mandates digitized moisture tracking. Backward integration into copper-aluminum recycling secures margin visibility against Chilean concentrate volatility. Channel control through certified technician networks locks out unqualified installers as OSHA pressure vessel requirements tighten.
For New Entrants and Emerging Players: Establish a beachhead in predictive maintenance software for legacy air-cooled installations, where incumbent OEMs lack retrofit digitization capabilities. Australian and Chilean mining corridors offer the most penetrable geography due to water-scarcity-driven air-cooled dominance and limited local fabrication capacity. A pay-per-uptime revenue model bypasses capital expenditure friction with procurement departments.
For Investors and Strategic Acquirers: Capital is best deployed toward aftermarket-dominated fabricators with established ISO 8573 certification and regional service density in German automotive supply chains. Long-term viability hinges on recurring revenue attach rates exceeding 40% of hardware value. Monitor carbon border adjustment mechanism implementation timelines as the inflection signal for lifecycle-data-ready suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Embedded IoT temperature monitoring enables predictive maintenance contracts with food and beverage processors. |
| Backward Integration into Metal Recycling | Captive copper-aluminum recovery hedges Chilean concentrate price volatility for German fabricators. |
| Certified Technician Network Expansion | OSHA pressure vessel compliance requirements lock out unqualified competitors in US Midwest markets. |
| Waste Heat Recovery System Bundling | Integrated cooling solutions improve total cost of ownership calculations in Chinese petrochemical clusters. |
| Regional Distributor Acquisition | Direct channel control captures installation revenue in Australian Pilbara Basin remote infrastructure. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews across compressed air system operators in US Midwest manufacturing, German automotive stamping, and Chinese petrochemical clusters combined with secondary validation from EPA enforcement records, MIIT industrial efficiency mandates, SEC 10-K filings of listed compressor OEMs, and customs trade data for copper-aluminum heat exchanger imports. Bottom-up unit economics triangulated against top-down industrial capital expenditure tracking.
Scenario-bracketing around EPA enforcement intensity, copper price volatility bands, and Chinese infrastructure renewal pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include cooling media type, heat exchanger architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates, replacement cycle compression under enforcement pressure, and service contract attach rate trajectories. Forecast inputs incorporated brownfield instrumentation integration timelines and field service technician certification pipeline constraints.
Stress conditions across copper-aluminum price spreads, EPA inspection frequency escalation, and Chinese state-directed capital allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and commodity supply chain stability. Cross-checking against industrial compressed air equipment capex surveys and GPO procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Thawing System Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Solar Fan Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market