
 Phenylalanine Market | 2026-2036
Phenylalanine Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylalanine Market Outlook
The EU Green Deal is recalibrating fermentation-based amino acid production standards across European manufacturing. Evonik Industries AG leverages its biotechnology platform to sustain pharmaceutical-grade output from German facilities. CJ CheilJedang Corporation anchors its position through integrated fermentation capacity in South Korea. Ajinomoto Co Inc dominates L-Phenylalanine supply for aspartame precursors with proprietary strain technology.
Phenylalanine is an essential amino acid with the molecular formula C9H11NO2, produced industrially via microbial fermentation of glucose using Corynebacterium glutamicum or Escherichia coli strains engineered for high tyrosine auxotrophy. L-Phenylalanine commands the largest volume share as the sole bioactive isomer for protein synthesis and aspartame manufacture, while DL-Phenylalanine occupies a narrower niche in specialized dietary supplements where racemic mixtures are tolerated. Pharmaceutical applications represent the fastest-expanding margin pool, driven by precision fermentation advances that reduce impurity profiles below pharmacopeial thresholds.
The FDA enforces identity and purity standards for phenylalanine used in food additives under 21 CFR, while the EMA oversees pharmaceutical-grade amino acid monographs through the European Pharmacopoeia. China's NMPA and SAMR jointly regulate fermentation-derived amino acids for domestic drug and food additive use, tightening contaminant limits that reshape export compliance burdens. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as diverging purity specifications will determine which production sites retain multi-regional supply eligibility.
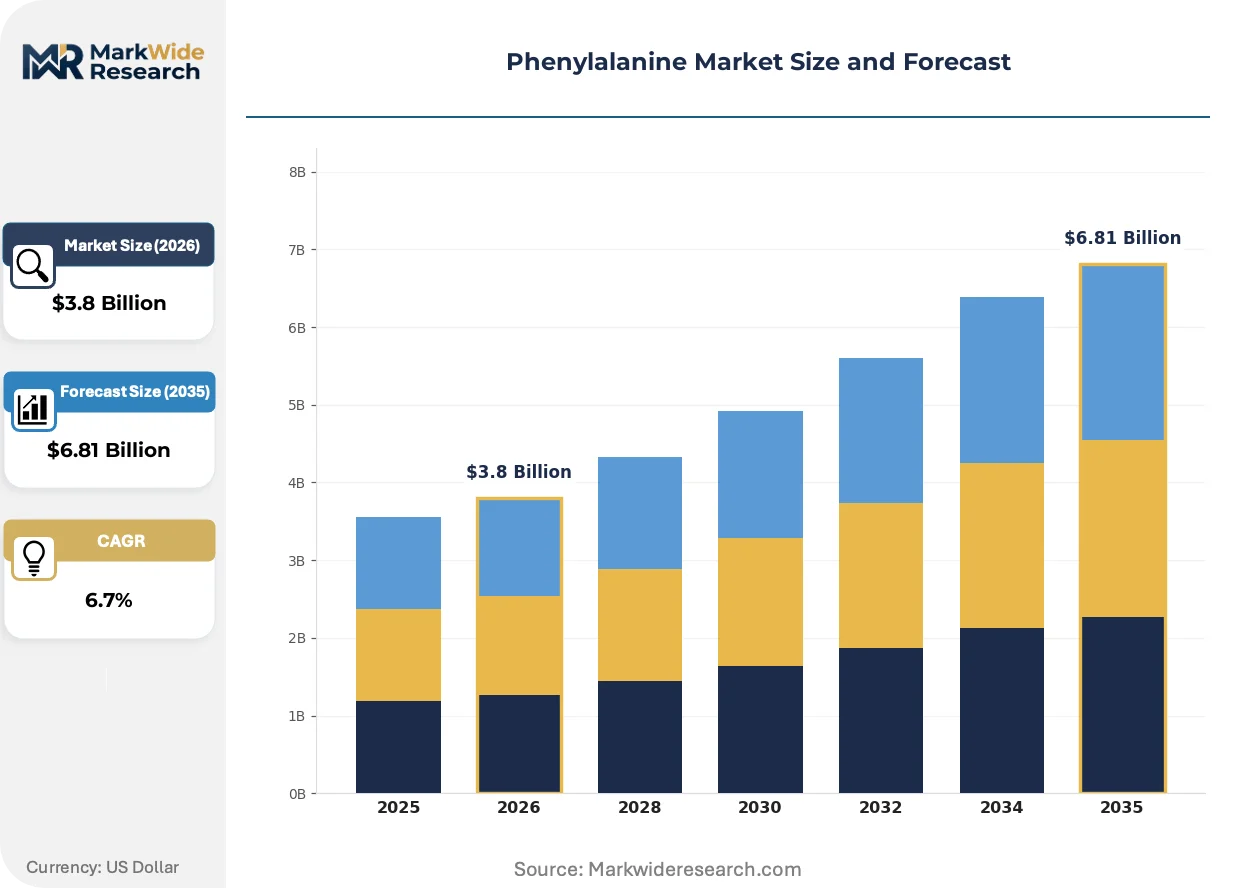
Market Dynamics
Fermentation strain engineering is compressing production economics for pharmaceutical-grade phenylalanine, forcing incumbent manufacturers to retool legacy Corynebacterium platforms or cede high-margin contract positions to biotechnology specialists.
Growth Catalysts
- EU Green Deal:The EU Green Deal is tightening fermentation emissions standards, accelerating capital deployment into closed-loop bioreactor systems across European production facilities.
- Cognitive health formulations:Nutraceutical manufacturers are expanding L-Phenylalanine offtake for nootropic supplement stacks targeting stress-response and focus applications.
- China's pharmaceutical-grade capacity expansion:Domestic amino acid producers in Shandong and Jiangsu provinces are commissioning cGMP-compliant fermentation lines to serve export markets.
Market Restraints
- Glucose feedstock volatility:Corn and wheat-derived glucose prices fluctuate with agricultural commodity cycles, compressing margin predictability for fermentation-based producers.
- Strain IP concentration:Proprietary high-yield phenylalanine strains remain concentrated among a limited set of biotechnology licensors, creating bottlenecks for new market entrants.
- Aspartame demand plateau:Sugar substitute formulation shifts in beverage and food applications are moderating volume growth for L-Phenylalanine's largest industrial outlet.
Strategic Opportunities
- Precision fermentation for pharmaceutical APIs:Contract manufacturers can capture value from small-molecule drug producers seeking USP-grade amino acid inputs with sub-ppm impurity profiles.
- India's specialty chemical corridor:The country's PLI scheme for active pharmaceutical ingredients is creating pull for fermentation-derived amino acid intermediates in Hyderabad and Ahmedabad clusters.
- Enzymatic racemate resolution:Convergence of biocatalysis and continuous processing is opening technical pathways to cost-competitive D-phenylalanine for niche therapeutic applications.
Industry Challenges
- Pharmacopeial harmonization complexity:Diverging purity specifications between USP, EP, and ChP monographs force manufacturers to maintain separate process trains or risk multi-regional disqualification.
- Bioreactor scale-up talent scarcity:Fermentation process engineers with experience in industrial amino acid production remain concentrated in legacy manufacturing regions, constraining greenfield project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylalanine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DL-Phenylalanine, L-Phenylalanine, D-Phenylalanine, Granular, Powder Application: Dietary Supplements, Food & Beverage, Pharmaceuticals, Animal Feed, Cosmetics End User: Manufacturers, Nutraceutical Companies, Pharma Firms, Food Processors, Cosmetic Brands Packaging Type: Bulk Bags, Drums, Plastic Bottles, Pouches, Glass Containers |
| Companies Covered | Ajinomoto Co Inc, Evonik Industries AG, CJ CheilJedang Corporation, Daesang Corporation, Kyowa Hakko Bio Co Ltd, BASF SE, Fufeng Group, Archer Daniels Midland Company, Amino GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylalanine Market Strategic Shifts
Continuous processing architectures and synthetic biology toolkits are restructuring how phenylalanine is manufactured, tested, and qualified for regulated end-uses. Three developments are compressing legacy batch paradigms.
Single-use bioreactor assemblies are modularizing fermentation infrastructure for mid-scale pharmaceutical-grade output. Contract manufacturers serving orphan drug and clinical trial material producers are adopting disposable vessel formats to reduce cross-contamination validation burdens. This hardware shift is modularizing capacity deployment decisions, allowing producers to match bioreactor scale to offtake commitments without multi-year stainless-steel fabrication cycles.
EMA's tightening of elemental impurity limits under ICH Q3D guidelines is forcing fermentation sites to revalidate downstream purification trains. European facilities must demonstrate sub-ppm control of catalyst residues and process metals across extended production campaigns. Pharmaceutical-grade phenylalanine destined for parenteral nutrition applications faces the steepest compliance gradient, with manufacturers in Germany and Switzerland accelerating investment in chelation and crystallization upgrades.
Direct procurement relationships between amino acid consumers and fermentation specialists are displacing traditional distributor intermediaries in high-volume applications. Large nutraceutical compounders and aspartame manufacturers are establishing annual volume contracts with named production sites, extracting traceability guarantees and audit rights that commodity traders cannot match. This channel compression is most advanced in North America, where FDA registration requirements for dietary supplement ingredient suppliers have strengthened buyer leverage in supplier qualification processes.
Phenylalanine Market Segmentation
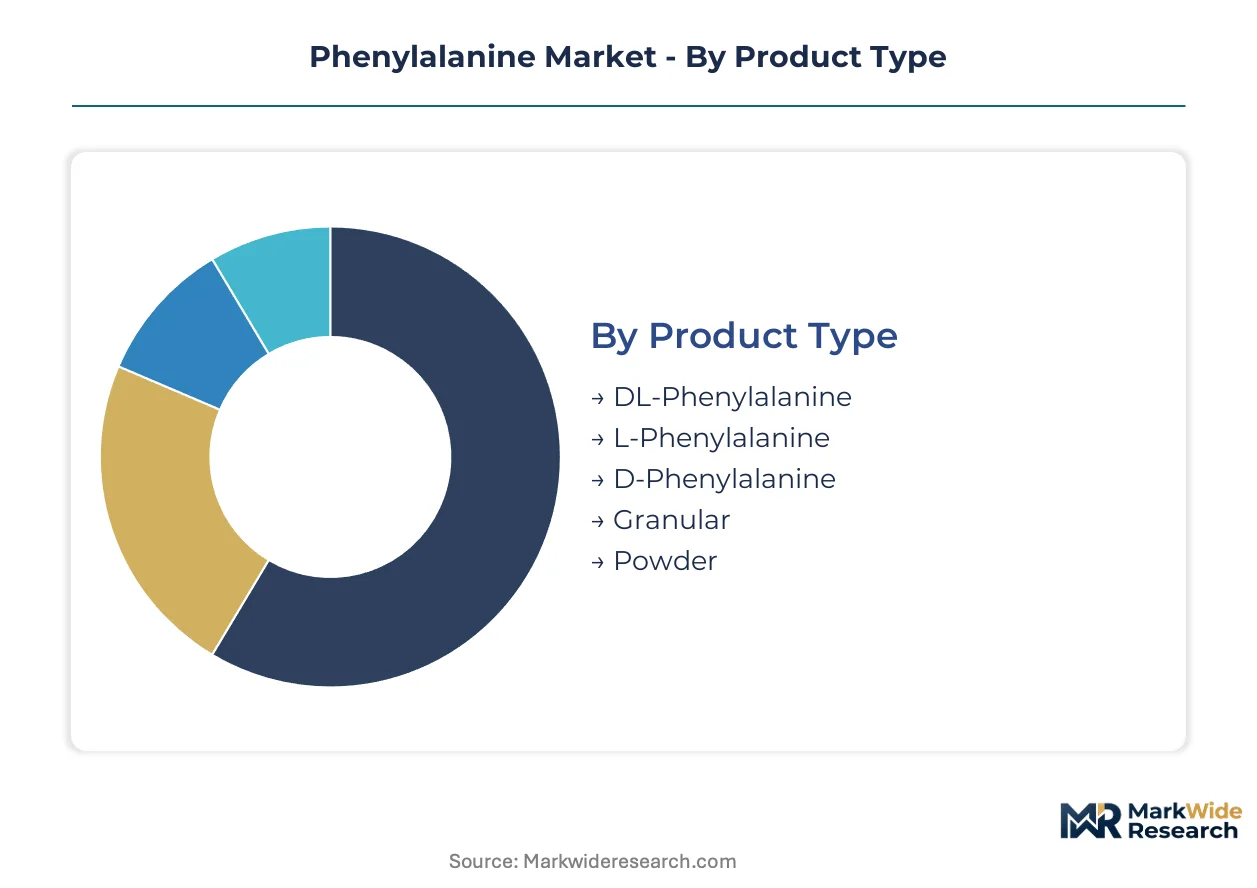
Phenylalanine segmentation reveals divergent value capture across molecular configurations and purity grades. Manufacturers optimize fermentation trains differently for aspartame precursors versus pharmaceutical APIs, creating distinct margin architectures within each product tier.
Product Type:
Volume concentration favors the bioactive L-isomer, while premium pricing accrues to specialized racemic and D-forms serving niche therapeutic applications.
- L-Phenylalanine:The sole biologically active stereoisomer for protein synthesis and aspartame manufacture commands dominant fermentation capacity. Pharmaceutical-grade output from German and Swiss facilities supplies parenteral nutrition formulators facing EMA's tightened elemental impurity limits under ICH Q3D.
- DL-Phenylalanine:Racemic mixtures blend equal D- and L-enantiomers for dietary supplement applications where bioactivity tolerance permits cost-optimized sourcing. Nutraceutical compounders in North America extract traceability guarantees through direct procurement contracts with named fermentation sites.
- D-Phenylalanine:The non-proteinogenic enantiomer serves specialized analgesic and antidepressant research programs requiring stereospecific synthesis pathways.
- Granular:Free-flowing crystalline format reduces dust exposure during high-volume aspartame precursor handling.
- Powder:Micronized particle distribution accelerates dissolution kinetics for instant beverage and clinical nutrition applications.
Today's leader: L-Phenylalanine. Tomorrow's challenger: D-Phenylalanine.
Application:
End-use economics split between commodity-scale food additive volumes and precision-tolerance pharmaceutical margins.
- Pharmaceuticals:USP-grade amino acid for parenteral nutrition and active pharmaceutical ingredient synthesis demands sub-ppm impurity profiles. Precision fermentation advances are compressing production economics for small-molecule drug producers seeking multi-regional pharmacopeial compliance.
- Food & Beverage:Aspartame precursor consumption dominates industrial offtake, though sugar substitute formulation shifts in beverage applications are moderating volume growth trajectories for this outlet.
- Dietary Supplements:Nootropic formulations targeting stress-response and cognitive focus applications are expanding L-phenylalanine offtake among nutraceutical manufacturers.
- Animal Feed:Essential amino acid fortification for monogastric livestock nutrition operates on specification-tolerant procurement terms.
- Cosmetics:Melanin synthesis precursor applications in topical formulations occupy a narrow specialty niche.
Pharmaceuticals capture premium margins; dietary supplements are climbing fastest.
End User:
Procurement sophistication varies from commodity traders serving feed compounders to qualified supplier audits mandated for drug master file holders.
- Pharma Firms:Multi-regional drug manufacturers enforce separate process trains to satisfy diverging USP, EP, and ChP monograph specifications, extracting site-specific audit rights and traceability guarantees.
- Nutraceutical Companies:Cognitive health formulators are scaling purchases for nootropic supplement stacks, establishing annual volume contracts that displace traditional distributor intermediaries.
- Manufacturers:Industrial amino acid consumers across intermediate chemical synthesis operate on spot-market flexibility with lower qualification burdens.
- Food Processors:Aspartame and high-intensity sweetener producers anchor demand concentration with fermentation specialists through direct procurement relationships.
- Cosmetic Brands:Specialty chemical formulators source melanin precursors on specification-matched batch terms.
Pharma Firms dictate quality standards; Nutraceutical Companies are expanding offtake most aggressively.
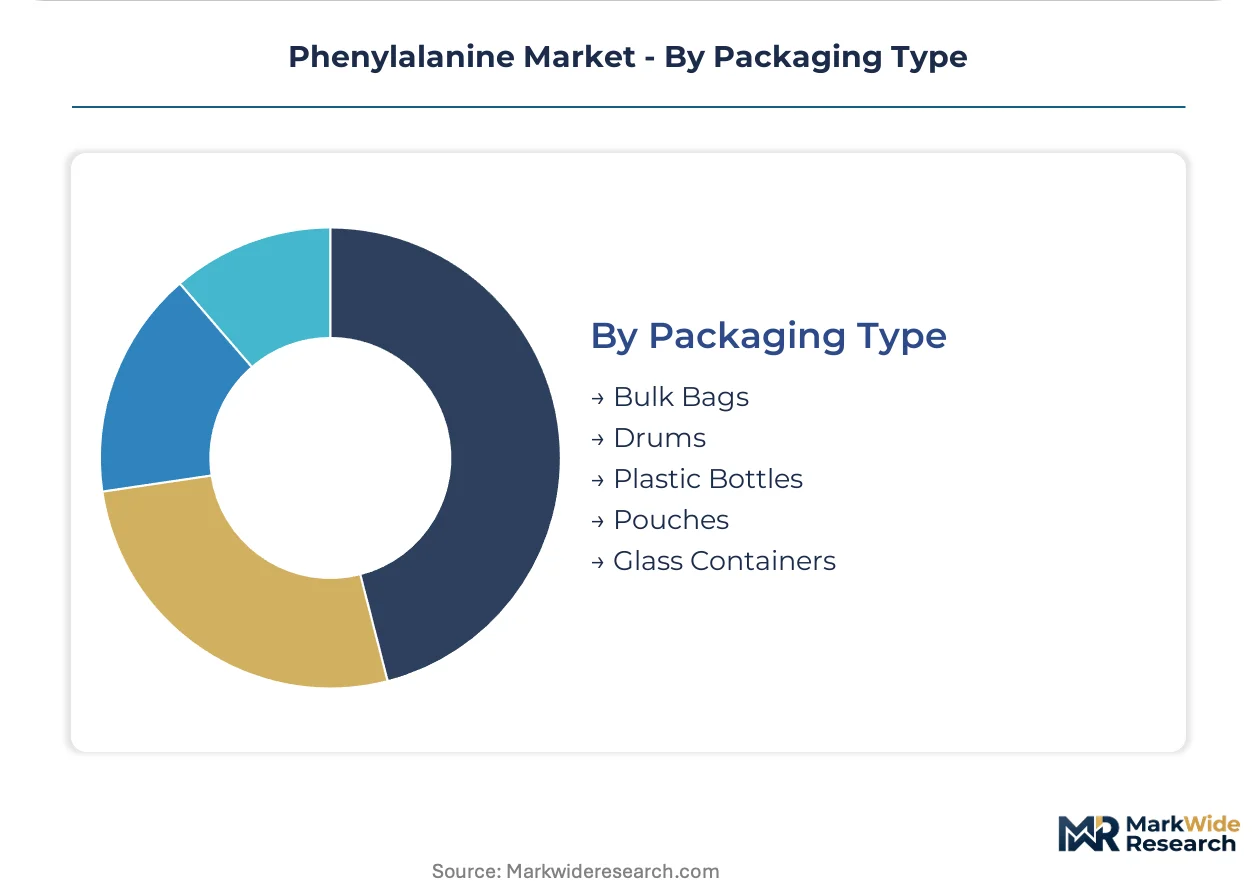
Packaging Type:
Format selection tracks handling automation, contamination control, and downstream processing integration requirements.
- Bulk Bags:Flexible intermediate bulk containers serve high-volume aspartame manufacturers with pneumatic conveying systems and automated dissolution equipment.
- Drums:Steel and fiberboard drums provide pharmaceutical-grade containment with tamper-evident sealing for API and clinical trial material shipments.
- Plastic Bottles:HDPE and PET containers address dietary supplement repackaging workflows with desiccant integration for humidity-sensitive amino acid stability.
- Pouches:Multi-layer laminate sachets support single-serve nutraceutical and cosmetic sample distribution formats.
- Glass Containers:Borosilicate and amber glass vials satisfy parenteral nutrition and reference standard applications requiring inert headspace environments.
Bulk Bags dominate tonnage; Drums command value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The phenylalanine industry traces its industrial-scale fermentation origins to post-war Japan, where amino acid biotechnology first achieved commercial viability before diffusing to German chemical clusters and Chinese coastal manufacturing zones.
China
Shandong and Jiangsu provinces dominate pharmaceutical-grade capacity expansion, with domestic manufacturers commissioning cGMP-compliant fermentation lines for export markets. The NMPA and SAMR have tightened contaminant limits on fermentation-derived amino acids, reshaping compliance burdens for drug and food additive applications. Qingdao and Nanjing anchor the largest concentration of amino acid fermentation infrastructure outside Japan.
Germany
Evonik Industries AG sustains pharmaceutical-grade output from German facilities leveraging biotechnology platforms, supplying parenteral nutrition formulators facing EMA's tightened elemental impurity standards under ICH Q3D. The EU Green Deal is recalibrating fermentation emissions standards across European production sites. The Rhine-Ruhr and Rhine-Main corridors concentrate precision fermentation expertise for USP-grade amino acid manufacture.
Japan
Ajinomoto Co Inc dominates L-phenylalanine supply for aspartame precursors through proprietary strain technology developed from historical fermentation leadership. The PMDA oversees pharmaceutical-grade amino acid monographs with standards that influence pharmacopeial harmonization globally. The Kanto region around Tokyo maintains the deepest concentration of amino acid biotechnology research and production heritage.
South Korea
CJ CheilJedang Corporation anchors its market position through integrated fermentation capacity serving regional nutraceutical and food additive demand. The MFDS regulates pharmaceutical-grade amino acids for domestic use while monitoring export compliance to USP and EP standards. The Busan-Ulsan industrial corridor hosts specialized fermentation infrastructure for high-purity amino acid output.
United States
FDA registration requirements for dietary supplement ingredient suppliers have strengthened buyer leverage in supplier qualification processes, accelerating direct procurement relationships. The agency enforces identity and purity standards under 21 CFR for phenylalanine used in food additives. New Jersey and North Carolina clusters concentrate pharmaceutical-grade amino acid distribution and formulation activities for parenteral nutrition applications.
Phenylalanine Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity-grade stratification, with pharmaceutical-grade specialists capturing value from sub-ppm impurity specifications while feed-grade producers compete on fermentation yield economics. The vendor base compresses around three strategic archetypes: integrated fermentation conglomerates with proprietary strain libraries, contract manufacturers serving orphan drug and clinical trial material producers, and regional glucose-feedstock processors optimizing agricultural commodity cycles. Dominant competitive moves include backward integration into captive glucose supply and technology licensing arrangements for high-yield phenylalanine strains.
Within the integrated fermentation tier, Ajinomoto Co Inc and Evonik Industries AG represent archetypes of proprietary biotechnology platforms sustaining multi-regional pharmacopeial compliance. CJ CheilJedang Corporation occupies a position exemplifying Asian conglomerate leverage across food, feed, and pharmaceutical amino acid segments. These three entities anchor the competitive structure through differentiated strain ownership, geographic production placement, and end-market qualification depth rather than scale alone.
| Leading Market Players |
|---|
| Ajinomoto Co Inc |
| Evonik Industries AG |
| CJ CheilJedang Corporation |
| Daesang Corporation |
| Kyowa Hakko Bio Co Ltd |
| BASF SE |
| Fufeng Group |
| Archer Daniels Midland Company |
| Amino GmbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned glucose processors in Shandong and Jiangsu provinces anchor upstream feedstock supply, creating pricing discipline through captive agricultural sourcing while forcing merchant buyers to absorb corn and wheat commodity volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates USP-certified output from aspartame precursors and specification-tolerant animal nutrition applications. Price differentiation hinges on impurity profiles and pharmacopeial certification, with EMA's ICH Q3D elemental limits commanding premiums. Cost compression in food-grade tiers is intensifying because Chinese cGMP expansions are adding fermenter capacity. Feed compounders exhibit highest price sensitivity; parenteral nutrition formulators show least.
Supply Chain Analysis
Glucose feedstock supply rests on corn processors in China, wheat refiners in Germany, and tapioca converters in Thailand. Corynebacterium strain libraries and chelating resin systems constitute critical component dependencies. Single-source vulnerability concentrates in proprietary high-yield phenylalanine strains held by Japanese and German biotechnology licensors. Distribution runs through direct procurement contracts between fermentation specialists and aspartame manufacturers, displacing commodity traders in high-volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phenylalanine market compounds steadily as precision fermentation advances compress production economics for pharmaceutical-grade output across multiple therapeutic applications.
For Market Incumbents: Hedge against aspartame demand plateau by diversifying into parenteral nutrition and small-molecule API synthesis. Secure backward integration into captive glucose supply to buffer agricultural commodity cycles. Invest in chelation and crystallization upgrades to meet EMA's tightened ICH Q3D elemental impurity standards for European pharmaceutical access. For New Entrants and Emerging Players: Direct-to-pharma digital procurement platforms offer entry routes around entrenched distributor relationships. Target India's specialty chemical corridor under the PLI scheme for active pharmaceutical ingredients, where fermentation-derived amino acid intermediates face supply gaps. Lead with USP-grade qualification and site-specific audit rights to differentiate from commodity traders. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with precision fermentation capabilities but incomplete pharmacopeial certification. The five-to-ten year viability window favors acquisition of mid-scale fermentation sites with upgradeable downstream purification trains. Watch enzymatic racemate resolution breakthroughs as the inflection signal for D-phenylalanine therapeutic niche expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Enables sub-ppm impurity profiles for USP-grade parenteral nutrition supply. |
| Backward Integration into Glucose Supply | Captures margin from agricultural commodity cycles in Shandong corn processing. |
| Chelation and Crystallization Upgrade | Satisfies EMA ICH Q3D standards for European pharmaceutical market access. |
| Direct Procurement Contracting | Displaces distributor intermediaries through named-site traceability guarantees. |
| Enzymatic Racemate Resolution Development | Opens cost-competitive pathways to D-phenylalanine for niche therapeutic applications. |
Study Parameters
Coverage spans China, Germany, Japan, South Korea, and the United States, with primary inputs from each market through interviews with fermentation process engineers, pharmaceutical procurement managers, nutraceutical formulators, and amino acid distribution specialists. Secondary validation draws from NMPA filings, EMA pharmacopeial monographs, FDA 21 CFR standards, and customs trade data for glucose feedstock and amino acid flows. Bottom-up capacity assessments and top-down demand modeling were triangulated.
Rate-of-change decomposition separates volume growth from price realization across pharmaceutical-grade, food-grade, and feed-grade tiers, with end-use industry splits for aspartame, parenteral nutrition, nootropic supplements, and animal feed applications. CAGRs were derived from fermentation capacity commissioning schedules, pharmacopeial harmonization trajectories, and glucose feedstock price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for continuous bioprocessing or cell-free enzymatic synthesis would alter the outlook for incumbent fermentation asset valuations. Forecasts reflect assumptions about EMA-FDA-ChP pharmacopeial convergence, strain IP licensing accessibility, and EU Green Deal emissions compliance costs. A small set of named triggers warrants ongoing watch: enzymatic racemate resolution economics, Indian PLI scheme amino acid allocation, and Chinese cGMP export certification velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market