
 Hydrogen Chloride Market | 2026-2036
Hydrogen Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Chloride Market Outlook
Long-term supply contracts for anhydrous hydrogen chloride is hardening into the dominant commercial format across electronics-grade applications. BASF SE leverages its integrated Ludwigshafen complex to sustain captive chlorine-to-HCl conversion economics. Olin Corporation anchors North American merchant supply through its diaphragm-cell and membrane-cell chlorine operations. Covestro AG differentiates via polyurethane precursor integration, consuming internally produced hydrogen chloride for methylene diphenyl diisocyanate chains.
Hydrogen chloride, a colorless corrosive gas with molecular formula HCl and boiling point of -85°C, serves primarily as a chlorination agent, acid catalyst, and pH modifier across heavy industry. Aqueous hydrogen chloride—marketed as muriatic acid or concentrated hydrochloric acid—commands the largest volume share through steel pickling and oil-well acidizing, though anhydrous grades carry superior margins in electronics and pharmaceutical synthesis. The chemical manufacturing end-user segment dominates absolute consumption, while metal processing applications face structural pressure from alternative descaling technologies.
EPA oversight under the Clean Air Act shapes US hydrogen chloride emissions thresholds for chlor-alkali facilities, while REACH registration requirements in Europe govern anhydrous product classification and handling protocols. China's MEE enforces increasingly stringent chloride discharge limits around the Yangtze River Economic Belt, forcing capacity consolidation into designated chemical parks. Stakeholders must monitor regulatory divergence between emissions-intensive legacy production and membrane-cell technology migration when committing capital to new supply positions.
Market Dynamics
Membrane-cell chlor-alkali technology migration is compressing legacy diaphragm-cell capacity while tightening anhydrous hydrogen chloride supply for electronics-grade applications. This structural shift concentrates production in integrated chemical parks where emissions compliance and feedstock integration coexist.
Growth Catalysts
- Semiconductor fabrication expansion:East Asian wafer foundries are scaling 3nm and 2nm process nodes, multiplying etching gas consumption per wafer. Jiangsu Province's chemical industrial parks are capturing this demand concentration.
- REACH anhydrous classification harmonization:ECHA registration requirements are standardizing handling protocols across EU pharmaceutical synthesis clusters, reducing cross-border friction for high-purity product movement.
- Steel pickling intensity:Automotive lightweighting programs are increasing high-strength alloy processing, sustaining muriatic acid volume through metal surface preparation applications.
Market Restraints
- Chlorine feedstock volatility:Electrolytic caustic soda demand fluctuations transmit directly to HCl co-production economics, compressing merchant margins during chlorine oversupply cycles.
- Yangtze River discharge limits:China's MEE chloride concentration caps are forcing capacity retirement outside designated chemical parks, removing swing supply from the spot market.
- Laser descaling substitution:Steel processors in Germany and Japan are piloting dry ablation systems for precision components, threatening acid pickling volume in high-value segments.
Strategic Opportunities
- India pharmaceutical API synthesis:CDSCO bulk drug park incentives are attracting hydrogen chloride consumers for acetylation and chlorination steps in generic active ingredient production.
- Carbon capture solvent chemistry:Amine-based post-combustion capture systems require HCl for regeneration catalyst preparation, opening industrial emissions abatement as a demand vertical.
- Direct-to-fab gas distribution:Bulk anhydrous delivery via pipeline to semiconductor clusters bypasses cylinder logistics, capturing margin from packaging-intensive merchant supply.
Industry Challenges
- Corrosion engineering expertise scarcity:Hastelloy and tantalum equipment specification for high-purity production requires specialized metallurgical knowledge concentrated in aging workforce cohorts.
- EPA Title V permitting timelines:New source review for chlor-alkali expansions stretches 18-24 months, delaying capacity response to electronics-grade demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Chloride Market |
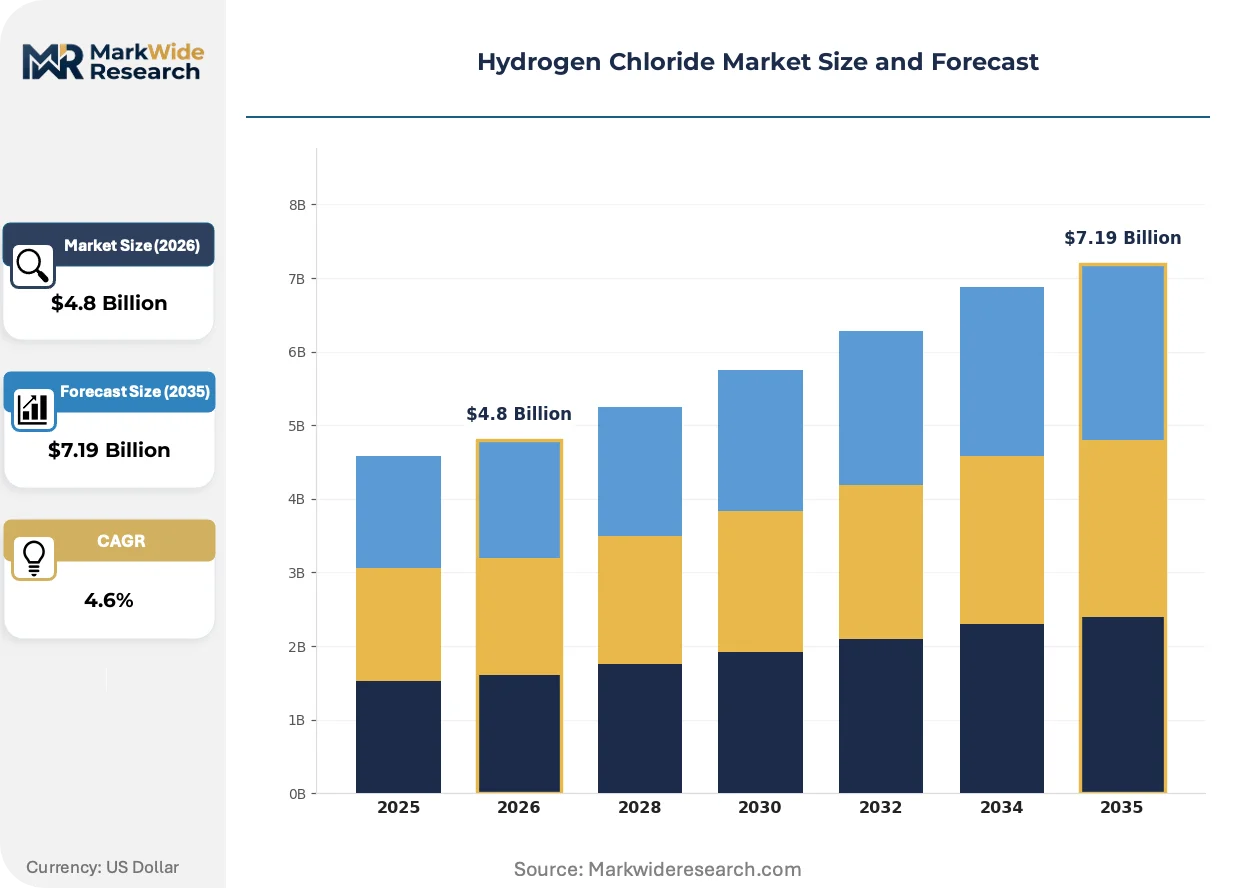
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Aqueous, Gas, Liquid End User: Chemical Manufacturing, Metal Processing, Pharmaceuticals, Agriculture Application: Neutralization, pH Control, Production of Chlorides, Synthesis of Organic Compounds Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | BASF SE, Olin Corporation, Occidental Petroleum Corporation, Westlake Chemical Corporation, Covestro AG, Air Liquide, Linde plc, AGC Chemicals, ERCO Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Chloride Market Strategic Shifts
Production technology differentiation and supply chain reconfiguration are fragmenting merchant market structures while creating captive integration premiums for quality-assured product streams.
Membrane-cell electrolysis is expanding into anhydrous hydrogen chloride production for electronics applications. Semiconductor fabricators in Taiwan and South Korea are specifying membrane-origin material for 5nm etching processes due to trace metal consistency. This technology is compressing spot market availability as integrated producers prioritize captive and contract volumes over merchant sales.
China's MEE is enforcing GB 31571-2015 emission standard revisions that tighten hydrogen chloride stack concentration limits to 30 mg per cubic meter. Chlor-alkali operators in Shandong and Jiangsu are consolidating into state-designated chemical industrial parks where centralized wastewater treatment enables compliance. High-purity anhydrous producers with membrane-cell assets are capturing displaced legacy capacity market share.
Long-term offtake contracting is displacing spot procurement for electronics-grade material. Korean memory chip manufacturers are locking five-year supply agreements with fixed volume floors and quality audit rights. This pattern concentrates procurement leverage with integrated chemical park operators in China and captive chlorine-to-HCl converters in Germany.
Hydrogen Chloride Market Segmentation
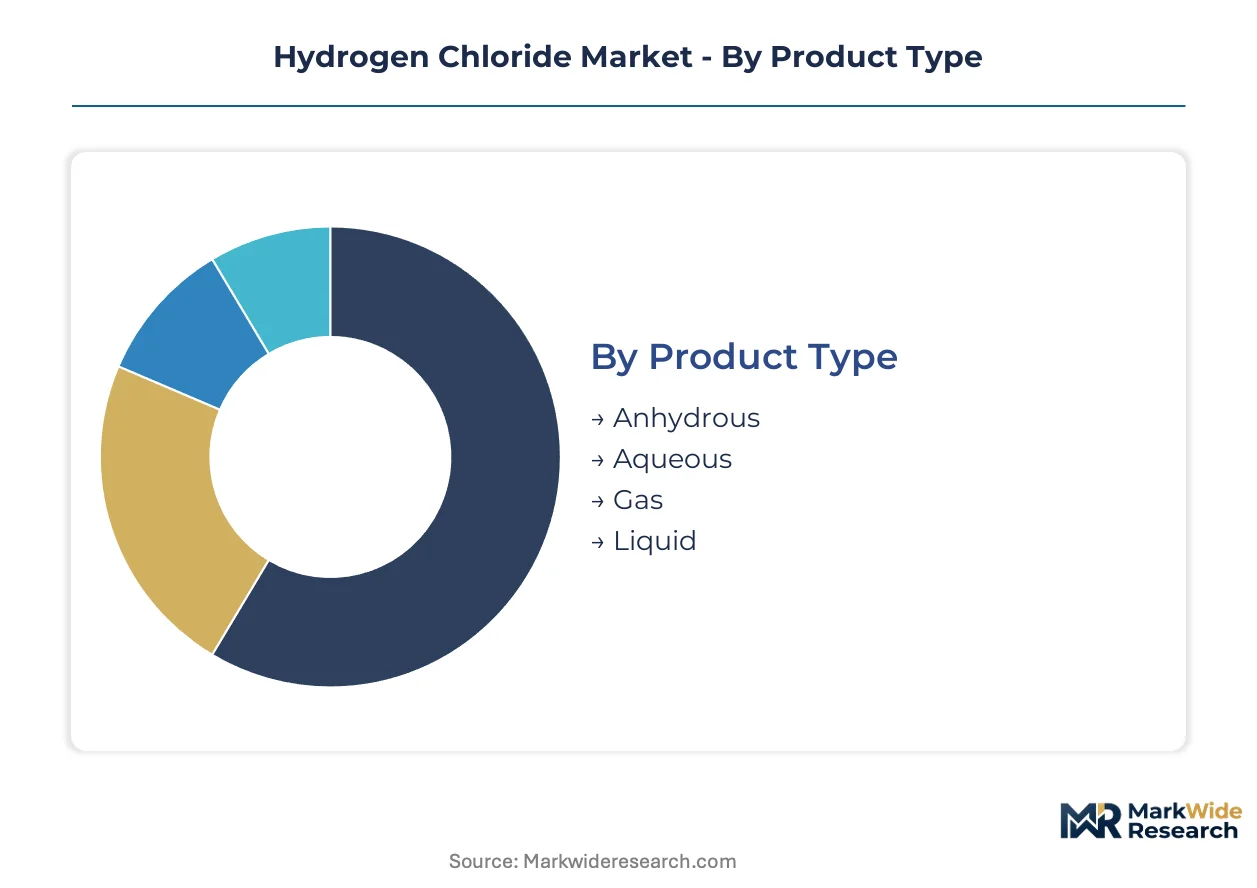
Hydrogen chloride segmentation separates commodity volume plays from precision-margin opportunities. Product form and end-use specifications create distinct competitive arenas with divergent capital intensity and regulatory exposure.
Product Type:
Anhydrous grades command premium positioning against aqueous bulk volumes, with gas and liquid forms occupying intermediate tiers.
- Anhydrous:High-purity material with moisture content below 0.5 ppm serves semiconductor etching and pharmaceutical synthesis. Taiwanese wafer foundries specify membrane-cell origin for 3nm process nodes, locking five-year offtake contracts with fixed quality audit rights.
- Aqueous:Concentrated hydrochloric acid (37% HCl by weight) dominates steel pickling and oil-well acidizing. Jiangsu Province chemical parks supply automotive lightweighting programs processing high-strength alloys.
- Gas:Pipeline-delivered bulk anhydrous bypasses cylinder logistics for chlor-alkali integrated sites.
- Liquid:Pressurized tank car shipments serve regional merchant markets with moderate purity requirements.
Today's leader: Aqueous. Tomorrow's challenger: Anhydrous.
End User:
Customer concentration spans process industries with varying tolerance for supply interruption and specification variance.
- Chemical Manufacturing:Chlorination agents and acid catalysts for acetylation reactions. CDSCO bulk drug park incentives in India attract hydrogen chloride consumers for generic API synthesis, expanding fastest among emerging demand centers.
- Metal Processing:Muriatic acid for steel surface preparation faces structural pressure from laser descaling pilots in Germany and Japan.
- Pharmaceuticals:REACH-registered anhydrous material for peptide synthesis and salt formation.
- Agriculture:pH modification for fertilizer production and soil treatment applications.
Chemical manufacturing absorbs the greatest absolute volume. Pharmaceutical specifications capture the steepest margin expansion.
Application:
Functional use cases separate commodity replacement demand from process-embedded consumption with switching costs.
- Neutralization:Wastewater treatment and effluent pH balancing in chemical park centralized facilities.
- pH Control:Food processing and water treatment with food-grade certification requirements.
- Production of Chlorides:Ferric chloride and aluminum chloride precursor chemistry for water treatment coagulants.
- Synthesis of Organic Compounds:Chlorination and acetylation steps in agrochemical and pharmaceutical intermediates.
Chloride production runs the highest volume throughput. Organic synthesis commands specification premiums with captive supply preference.
Distribution Channel:
Channel selection reflects customer scale, urgency tolerance, and technical service requirements.
- Direct Sales:Long-term contracts with semiconductor fabricators and integrated chemical producers.
- Distributors:Regional inventory positioning for metal processors and small-batch pharmaceutical users.
- Wholesale:Bulk tank car and pipeline deliveries to chlor-alkali adjacent consumers.
- Online Retail:Laboratory-grade packaging for research institutions and analytical applications.
Direct sales lock the most valuable demand. Distributor networks defend share in fragmented downstream segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's membrane-cell conversion pace outstrips Germany's REACH compliance timeline, while South Korea locks long-term supply contracts faster than US permitting allows. Regulatory divergence is fragmenting regional supply architectures.
China
Jiangsu Province's chemical industrial parks absorb semiconductor etching demand from Taiwan and South Korea. MEE enforces GB 31571-2015 revisions capping stack emissions at 30 mg per cubic meter. Shandong operators consolidate into state-designated parks where centralized wastewater treatment enables compliance.
Germany
BASF SE's Ludwigshafen complex sustains captive chlorine-to-HCl conversion for polyurethane precursor chains. ECHA REACH registration governs anhydrous handling protocols across pharmaceutical synthesis clusters. Covestro AG consumes internally produced hydrogen chloride for methylene diphenyl diisocyanate production.
United States
Olin Corporation anchors North American merchant supply through diaphragm-cell and membrane-cell chlorine operations. EPA Title V permitting stretches 18-24 months for chlor-alkali expansions under Clean Air Act oversight. Gulf Coast petrochemical corridors face emissions threshold pressure from legacy production.
South Korea
Memory chip manufacturers specify membrane-origin material for 5nm etching processes. Korean fabricators lock five-year supply agreements with fixed volume floors and quality audit rights. Seoul Capital Area semiconductor clusters drive direct-to-fab pipeline distribution economics.
India
CDSCO bulk drug park incentives attract hydrogen chloride consumers for acetylation and chlorination in generic API synthesis. Maharashtra and Gujarat chemical corridors expand chlor-alkali capacity for pharmaceutical intermediate production. BIS standards govern industrial-grade specifications for metal processing applications.
Hydrogen Chloride Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical park operators capturing premium electronics-grade volumes while merchant suppliers defend aqueous acid markets. The vendor base concentrates around chlor-alkali originators with captive chlorine feedstock positions. Three archetypes dominate: membrane-cell technology adopters, polyurethane-integrated chemical conglomerates, and industrial gas distributors with packaged gas capabilities. Capacity consolidation and long-term offtake contracting represent the dominant competitive moves.
Among German-integrated chemical conglomerates, BASF SE and Covestro AG exemplify backward integration strategies, while Olin Corporation represents North American merchant supply anchoring. These three occupy positions spanning captive production, downstream chemical integration, and regional merchant distribution respectively.
| Leading Market Players |
|---|
| BASF SE |
| Olin Corporation |
| Occidental Petroleum Corporation |
| Westlake Chemical Corporation |
| Covestro AG |
| Air Liquide |
| Linde plc |
| AGC Chemicals |
| ERCO Worldwide |
| Others |
Value Chain & Pricing Dynamics
Chlor-alkali feedstock indices cascade through membrane-cell and diaphragm-cell production tiers, compressing merchant margins when chlorine oversupply cycles collide with electronics-grade purity premiums. Contract structures now separate Jiangsu Province chemical park operators from spot-dependent aqueous acid suppliers.
Pricing Analysis
Capacity additions in China's designated chemical industrial parks are reshaping price floors for anhydrous grades while legacy diaphragm-cell retirements tighten spot availability. Three-tier pricing structure across electronics-grade, industrial-grade, and aqueous bulk levels reflects membrane-cell origin certification and REACH registration status. Cost compression in steel pickling tiers is intensifying because laser descaling pilots in Germany and Japan threaten volume. Metal processors show highest price sensitivity; semiconductor fabricators lock long-term offtake with quality audit rights.
Supply Chain Analysis
Direct-to-fab pipeline channels handle Korean memory chip manufacturer demand, bypassing cylinder logistics for membrane-origin material. Supply concentrates in China, Germany, and South Korea, with Jiangsu Province chemical parks and BASF's Ludwigshafen complex anchoring regional hubs. Raw material dependencies center on electrolytic chlorine, caustic soda co-production economics, and tantalum equipment for high-purity handling. Single-source vulnerability runs through corrosion engineering expertise scarcity for Hastelloy specification. Distribution runs through integrated chemical park operators, regional tank car networks, and packaged gas distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where semiconductor etching specifications toward 3nm and 2nm nodes reward membrane-cell origin certification with contract premiums.
For Market Incumbents: Lock in long-term offtake agreements with Korean and Taiwanese fabricators before EPA Title V permitting timelines allow North American capacity response. Prioritize captive chlorine-to-HCl conversion economics at integrated sites to defend margin position against merchant spot volatility. Invest in corrosion engineering workforce development to address Hastelloy specification scarcity threatening high-purity expansion timelines. For New Entrants and Emerging Players: Enter via CDSCO bulk drug park incentives in Maharashtra and Gujarat, where pharmaceutical API synthesis demand for acetylation chemistry outstrips regional chlor-alkali capacity. Carbon capture solvent chemistry represents adjacent white-space, with amine-based post-combustion systems requiring HCl for regeneration catalyst preparation. Position around direct-to-fab gas distribution partnerships rather than packaged merchant supply. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane-cell technology migration eliminates legacy diaphragm-cell economics, stranding non-integrated aqueous acid producers. Target chemical park operators with captive feedstock integration and existing MEE emissions compliance infrastructure. Watch Korean memory chip manufacturer contract renewal cycles as inflection indicator for electronics-grade demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Technology Migration | MEE GB 31571-2015 compliance in Jiangsu Province chemical parks displaces legacy diaphragm-cell capacity. |
| Long-Term Supply Agreement | Korean fabricators lock five-year contracts with fixed volume floors, concentrating procurement leverage. |
| Backward Integration | BASF's Ludwigshafen complex sustains captive chlorine-to-HCl conversion for polyurethane precursor chains. |
| Direct-to-Fab Distribution | Pipeline delivery to Seoul Capital Area semiconductor clusters bypasses packaging-intensive merchant economics. |
| Workforce Capability Investment | Hastelloy and tantalum equipment specification training addresses aging metallurgical knowledge scarcity. |
Study Parameters
Coverage spans China, Germany, South Korea, the United States, and India, with primary inputs from each regional chlor-alkali production cluster. The approach combines primary interviews with plant managers, procurement leads at downstream chemical manufacturers, distribution channel partners, and technical R&D directors with secondary validation from customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE emissions disclosure databases. Bottom-up capacity modeling and top-down demand triangulation anchor volume and value estimates.
Granularity-level modeling extends to grade tier (anhydrous, aqueous, gas, liquid), end-use industry (chemical manufacturing, metal processing, pharmaceuticals, agriculture), packaging format (pipeline, tank car, cylinder, laboratory-grade), and regional production hub. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers across the analysis window. Forecast inputs incorporate semiconductor fabrication node migration timelines, MEE chemical park consolidation schedules, and REACH registration compliance trajectories.
Inputs from plant-level production disclosures and regulatory filing databases were available through the study window; gaps in real-time spot pricing transparency introduce uncertainty bands around merchant margin estimates. Forecasts reflect assumptions around membrane-cell technology adoption pace, emissions standard enforcement intensity, and etching gas intensity per wafer. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzalkonium Bromide Market
Chemicals
Potassium Iodide Market
Chemicals
Electroplating Chemicals Market
Chemicals
Calcium Borate Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Cupric Chloride Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Amine Oxide Market
Chemicals
Lime Sulfur Market
Chemicals
Hydrophobing Agents Market
Chemicals
Flooring Chemicals Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Bronopol Market
Chemicals
P-Ethylphenol Market
Chemicals
Calcium Carbide Market
Chemicals
Egypt Construction Chemicals Market