
 Dimethyl Terephthalate (DMT) Market | 2026-2036
Dimethyl Terephthalate (DMT) Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Terephthalate (DMT) Market Analysis
Asset-light leasing arrangements for PET polymerization units is rewriting competitive entry dynamics in the DMT value chain. Eastman Chemical Company leverages its backward integration into paraxylene feedstocks to sustain margin stability across volatile raw-material cycles. SK Chemicals Co., Ltd. anchors its position through specialized optical-grade polyester output for electronics substrates. OAO Mogilevkhimvolokno competes on geographic proximity to European textile converters, reducing inland logistics exposure.
Dimethyl terephthalate is a dimethyl ester of terephthalic acid with the formula C10H10O4, produced via esterification of purified terephthalic acid or oxidation of p-xylene followed by methylation, serving primarily as a monomer for polyethylene terephthalate (PET) resin synthesis. Polyester applications dominate volume offtake, though film production for flexible electronics substrates represents the fastest-expanding margin pool as display manufacturers demand ultra-high-purity grades. Plasticizers for automotive interior compounds face structural pressure from bio-based alternatives, while resins for packaging applications retain steady demand through lightweighting mandates across beverage and food-contact segments.
The EPA regulates air emissions from DMT production facilities under Clean Air Act standards, while REACH restricts residual heavy-metal content in PET destined for EU consumer goods, effectively filtering non-compliant Asian exporters from premium supply tiers. China's MEE enforces wastewater discharge limits around p-xylene oxidation corridors, raising capital requirements for new DMT capacity additions. Stakeholders must monitor regulatory divergence between California's SB 54 packaging recycling rules and EU CSRD supply-chain disclosure requirements, as compliance fragmentation will determine which production configurations retain access to high-margin brand-contract volumes.
Market Dynamics
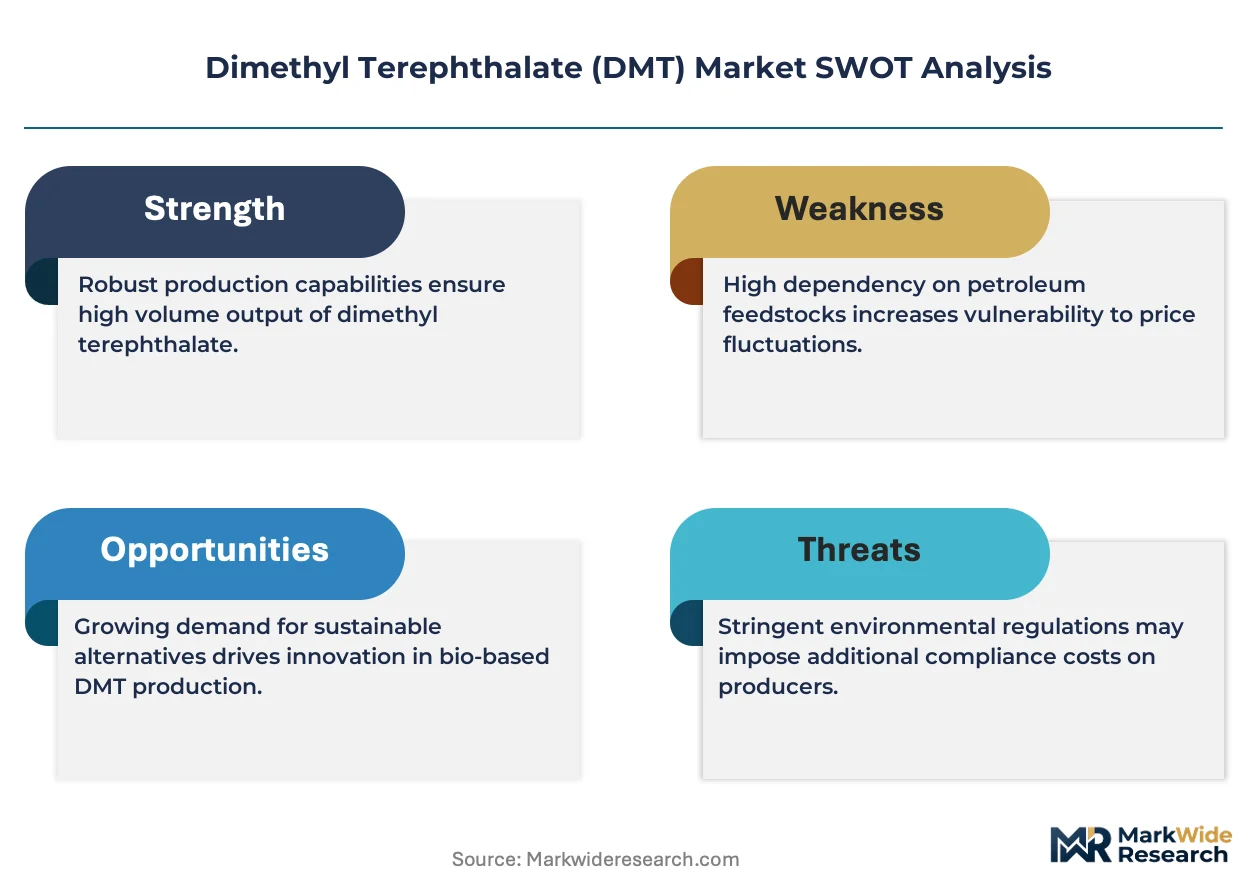
Recycled-content mandates from apparel brands are compressing virgin polyester margins and forcing DMT producers to certify mass-balance chain of custody or lose contract eligibility.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recycled content thresholds for PET beverage bottles create certified demand pull for DMT-derived resins with verified recycled feedstock integration.
- Optical-grade polyester for electronics:Display manufacturers in South Korea and Taiwan specify ultra-high-purity DMT for flexible substrate films, expanding addressable margin pools beyond commodity textile grades.
- China's integrated PTA-DMT-PET corridors:Concentrated capacity along the Yangtze River Delta reduces inter-plant logistics costs and accelerates inventory turns for export-oriented polyester fiber producers.
Market Restraints
- Paraxylene feedstock volatility:Crude-linked aromatics pricing transmits directly to DMT cost structures, compressing producer margins during naphtha price spikes without corresponding polyester price recovery.
- Single-country supply concentration:Overreliance on Chinese merchant DMT output exposes converters to freight cost surges and customs processing delays during port congestion events.
- Purified Terephthalic Acid substitution:Direct PTA-to-PET polymerization routes bypass DMT entirely in bottle-grade applications, structurally capping DMT volume growth in the highest-margin packaging segment.
Strategic Opportunities
- India's polyester capacity buildout:Reliance Industries and Indorama Ventures are expanding PET resin plants in Gujarat, creating demand for imported DMT where domestic oxidation capacity remains underdeveloped.
- Bio-based p-xylene pathways:Fermentation-derived aromatics from Anellotech and Neste partnerships offer mass-balance certification routes for brand-compliant circular polyester without fossil attribution.
- Digital product passports:EU CSRD supply-chain disclosure requirements reward early adopters of blockchain-tracked DMT batches with preferential sourcing contracts from compliance-forward apparel brands.
Industry Challenges
- Specialized catalyst procurement:Esterification catalysts with heavy-metal content below REACH thresholds require qualified supplier relationships that smaller DMT producers struggle to secure at scale.
- Legacy oxidation asset retrofit costs:Converting older p-xylene plants to meet China's MEE wastewater discharge standards demands capital commitments that strain balance sheets already pressured by feedstock volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Terephthalate (DMT) Market |
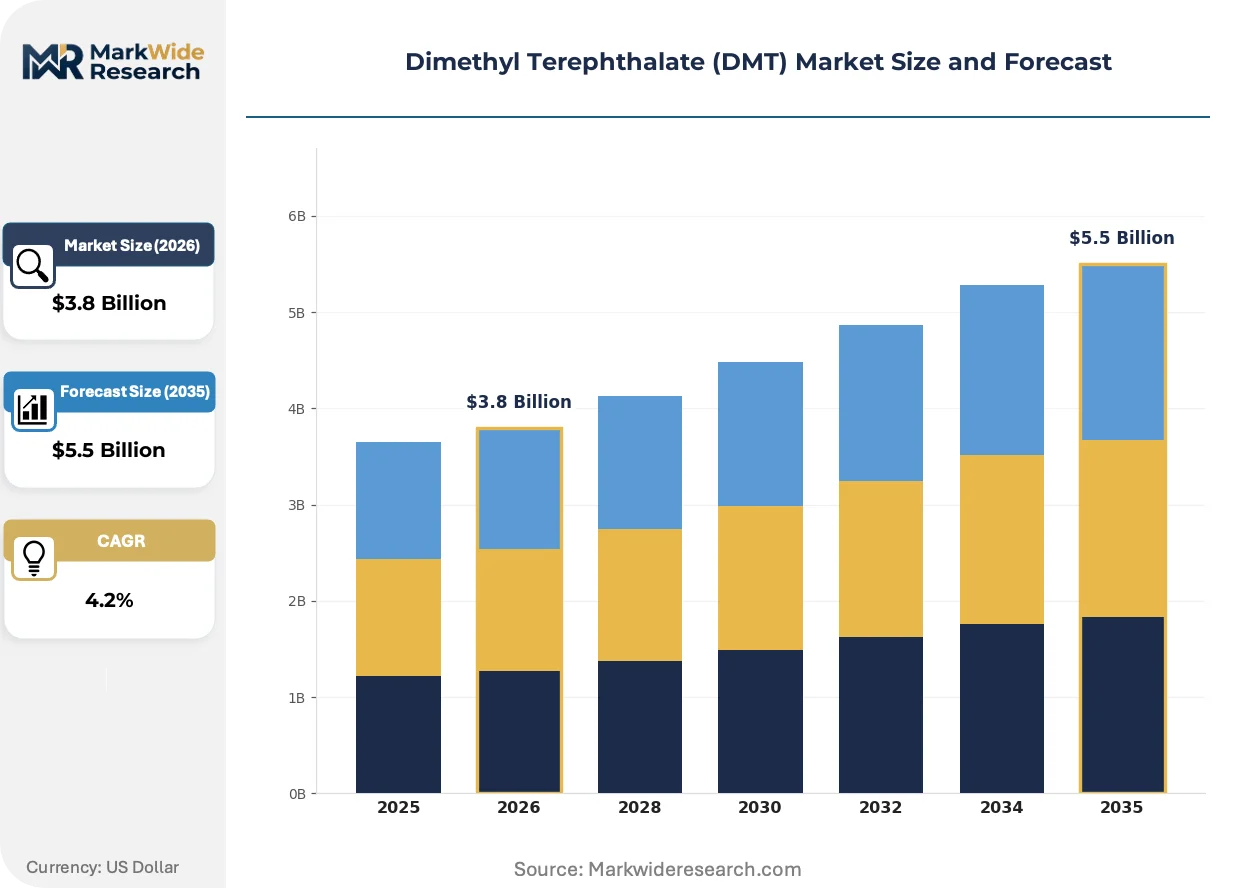
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Plasticizers, Resins, Fibers End Use Industry: Textiles, Packaging, Automotive, Electronics Application: Film Production, Coatings, Adhesives, 3D Printing Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | OXXYNOVA GmbH, Nan Ya Plastics Corporation, Eastman Chemical Company, Zhejiang Juhua Co., Ltd., Asahi Kasei Corporation, SK Chemicals Co., Ltd., OAO Mogilevkhimvolokno, Connect Chemicals, SASA Polyester Sanayi A.Ş., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Terephthalate (DMT) Market Emerging Trajectories
Process intensification and molecular traceability are converging to redefine competitive advantage in DMT production, separating certified-sustainable supply chains from commodity bulk supply.
Membrane-based methanol recovery systems are rendering obsolete conventional distillation trains in DMT purification stages. European specialty chemical producers have piloted these units at 40% energy reduction versus thermal separation. The technology is compressing operating cost structures for producers serving carbon-accounted brand supply chains.
REACH Annex XVII restrictions on heavy-metal catalyst residues are tightening purity specifications for DMT destined for EU food-contact applications. Residual cobalt and manganese limits now filter non-compliant Asian merchant supply from premium packaging-grade contracts. German converters have shifted procurement toward ECHA-registered producers with documented catalyst substitution protocols.
Mass-balance certification is displacing conventional spot-market purchasing for polyester fiber offtake. Brand sustainability teams now require ISCC PLUS or equivalent chain-of-custody documentation before contract award, compressing the merchant spot market to distressed-volume clearing. This shift concentrates demand among DMT producers with integrated chemical recycling partnerships in the Netherlands and Belgium.
Dimethyl Terephthalate (DMT) Market Segmentation
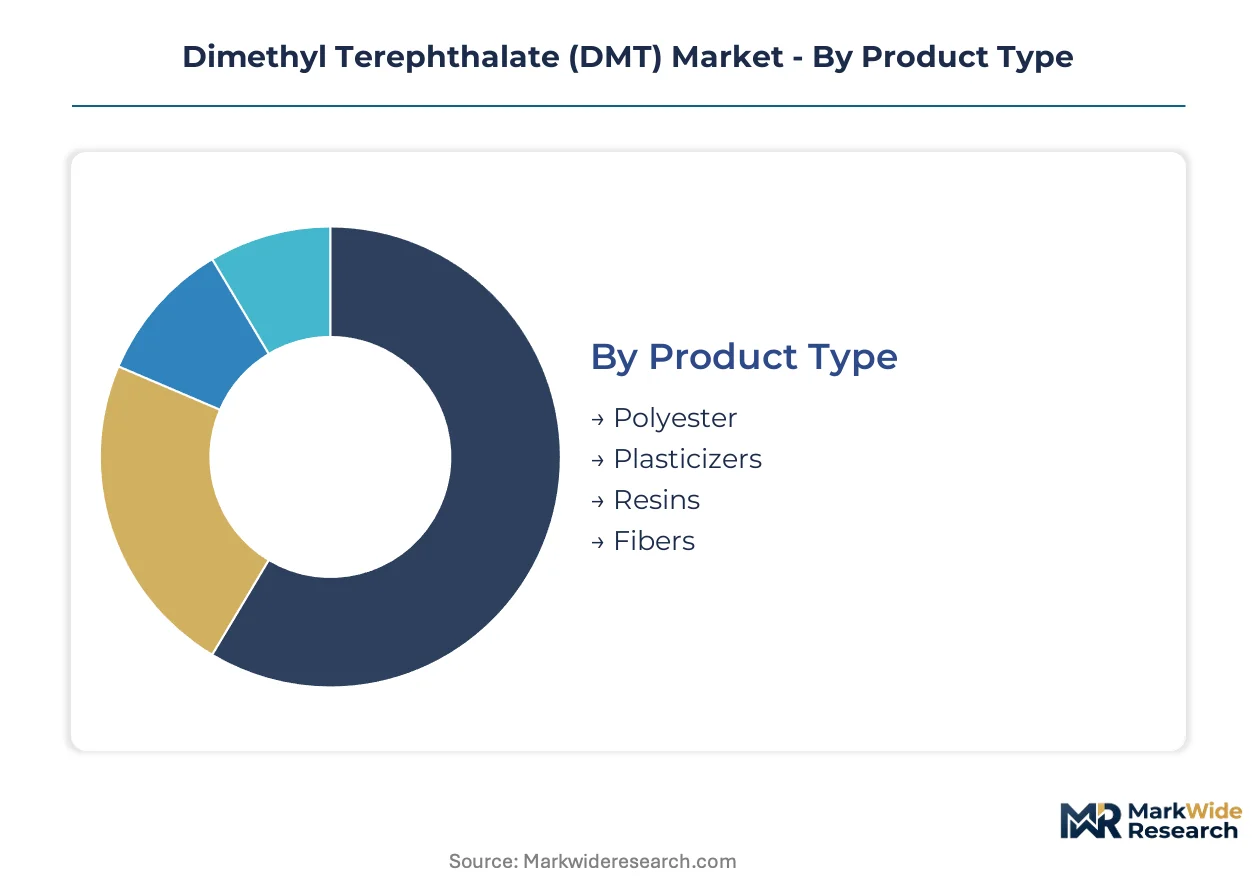
DMT demand fragments sharply across conversion technologies and end-use specifications, with polymerization routes and purity grades determining contract eligibility and margin capture. Producers must align product configurations with the diverging certification requirements of textile brands, electronics manufacturers, and food-contact packaging converters.
Product Type:
Polyester applications span commodity fiber to optical-grade film substrates, creating distinct margin tiers based on purity certification and chain-of-custody documentation.
- Polyester:Dominant volume application serving PET resin synthesis for bottle-grade and fiber-grade outputs. Textile brands in Bangladesh and Vietnam now mandate mass-balance certification for virgin polyester feedstock, filtering uncertified DMT from contract supply pools.
- Plasticizers:Automotive interior compounds rely on DMT-derived plasticizers for dashboard and trim flexibility. Bio-based alternatives from succinic acid fermentation are displacing fossil-derived options in European OEM specifications, compressing addressable volume.
- Resins:Packaging-grade PET resins require heavy-metal catalyst residues below REACH Annex XVII thresholds. German and Dutch converters have shifted procurement toward ECHA-registered producers with documented substitution protocols.
- Fibers:Industrial filament and staple fiber production concentrates in China's Yangtze River Delta integrated corridors. Direct PTA polymerization routes are eroding DMT's share in commodity textile applications.
Established volume favors Polyester; emerging adoption favors Resins as packaging circularity mandates tighten.
End Use Industry:
Customer procurement patterns diverge between spot-market textile converters and long-contract electronics substrate manufacturers.
- Textiles:Apparel brands including H&M and Inditex enforce recycled-content minimums that compress virgin polyester margins. Mass-balance certification now gates contract eligibility for DMT suppliers to South and Southeast Asian fiber producers.
- Packaging:EU Green Deal mandates for recycled PET content in beverage bottles create certified demand pull. Producers with chemical recycling partnerships in the Netherlands and Belgium capture premium contract tiers.
- Automotive:Interior trim and under-hood applications specify heat-resistant polyester compounds. Lightweighting mandates sustain steady resin demand despite plasticizer substitution pressure.
- Electronics:Display manufacturers in South Korea and Taiwan specify ultra-high-purity DMT for flexible substrate films. Optical-grade specifications expand addressable margin pools beyond commodity textile grades.
Electronics commands the steepest expansion trajectory; textiles retains the deepest volume base.
Application:
Functional performance requirements separate commodity film from precision coating and additive manufacturing specifications.
- Film Production:Biaxially oriented PET film for flexible electronics and food packaging demands residual metal content below 5 ppm. Membrane-based methanol recovery systems enable European producers to meet these thresholds at reduced energy intensity.
- Coatings:Powder and liquid coating formulations utilize DMT-derived polyester resins for automotive and industrial metal protection. REACH compliance on volatile organic compound emissions shapes formulation chemistry.
- Adhesives:Hot-melt and reactive adhesive systems incorporate DMT-based polyesters for bond strength and thermal stability. Packaging assembly lines in Poland and the Czech Republic drive regional demand concentration.
- 3D Printing:Fused filament fabrication uses PETG and copolyester materials derived from high-purity DMT. Prototyping and small-batch production in German engineering clusters sustain niche volume.
Film production captures the fastest margin expansion; coatings maintains the broadest geographic footprint.
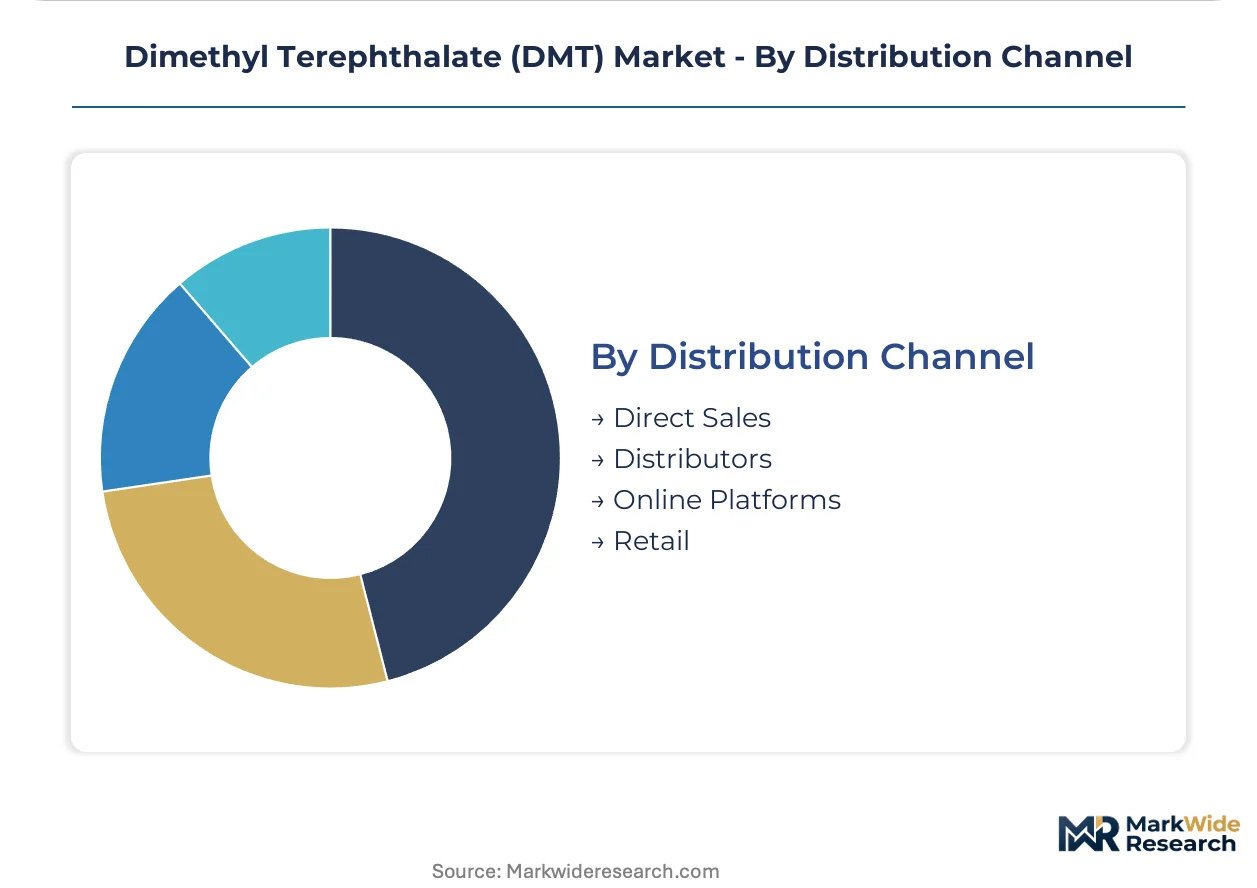
Distribution Channel:
Supply chain configuration determines access to certified-sustainable contract tiers versus commodity spot markets.
- Direct Sales:Integrated PTA-DMT-PET producers in China and contract manufacturers in India transact directly with resin converters. Long-term offtake agreements predominate for volume fiber and packaging applications.
- Distributors:Regional chemical distributors serve mid-scale European textile converters with smaller batch requirements. Inventory pooling reduces working capital burdens for buyers lacking direct producer relationships.
- Online Platforms:Specialty chemical marketplaces facilitate spot purchases for laboratory and pilot-scale quantities. Limited penetration in bulk industrial segments due to certification documentation requirements.
- Retail:Consumer-facing channels for DMT-based products remain negligible; retail exposure is indirect through finished goods only.
Direct sales commands the dominant share; distributor networks gain traction among compliance-constrained mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping regional DMT trade flows as integrated polyester corridors in Asia absorb domestic output while European converters seek certified-sustainable imports to meet circularity mandates.
China
Yangtze River Delta integrated PTA-DMT-PET complexes anchor regional supply chains for textile fiber exports. The MEE enforces wastewater discharge limits around p-xylene oxidation corridors, raising capital requirements for new capacity additions. Zhejiang and Jiangsu provinces concentrate merchant DMT output serving Southeast Asian converters.
Germany
Packaging-grade resin converters in North Rhine-Westphalia demand REACH Annex XVII-compliant DMT with documented catalyst substitution protocols. The EU Green Deal mandates recycled PET content thresholds for beverage bottles, creating certified demand pull. Chemical recycling partnerships in the Netherlands and Belgium enable German processors to access mass-balance certified feedstock.
United States
EPA Clean Air Act standards regulate emissions from DMT production facilities serving specialty resin applications. California's SB 54 packaging recycling rules diverge from EU disclosure requirements, creating compliance fragmentation for multinational brand supply chains. Gulf Coast petrochemical corridors maintain paraxylene feedstock integration for domestic polymerization.
India
Reliance Industries and Indorama Ventures are expanding PET resin plants in Gujarat, creating demand for imported DMT where domestic oxidation capacity remains underdeveloped. The BIS maintains quality standards for packaging-grade resins used in food-contact applications. Maharashtra textile clusters increasingly specify mass-balance certification for virgin polyester feedstock.
South Korea
Display manufacturers in Gyeonggi Province specify ultra-high-purity DMT for flexible substrate films, expanding addressable margin pools beyond commodity textile grades. The MFDS regulates food-contact material purity standards for packaging applications. Busan-Ulsan chemical complexes maintain optical-grade polyester output for electronics substrate supply to Taiwan and Japan.
Dimethyl Terephthalate (DMT) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The DMT market structures around three tiers: integrated petrochemical majors with captive paraxylene supply, merchant DMT producers serving regional converter demand, and specialty chemical firms targeting optical-grade specifications. Competitive moves center on backward integration into feedstocks and mass-balance certification partnerships with chemical recyclers.
Among German specialty chemical producers, OXXYNOVA GmbH represents the precision-manufacturing archetype with ECHA-registered production protocols. Eastman Chemical Company exemplifies integrated petrochemical positioning with upstream control over aromatics supply chains. SK Chemicals Co., Ltd. occupies a position within the optical-grade specialization tier serving electronics substrate manufacturers in South Korea and Taiwan.
| Leading Market Players |
|---|
| OXXYNOVA GmbH |
| Nan Ya Plastics Corporation |
| Eastman Chemical Company |
| Zhejiang Juhua Co., Ltd. |
| Asahi Kasei Corporation |
| SK Chemicals Co., Ltd. |
| OAO Mogilevkhimvolokno |
| Connect Chemicals |
| SASA Polyester Sanayi A.Ş. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta container freight corridors transmit volatile bunker fuel costs directly to DMT landed pricing in European and Indian markets, amplifying margin compression for merchant producers lacking integrated feedstock positions while rewarding backward-integrated majors with cost-passing leverage against textile converters.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium optical-grade, standard packaging-grade, and economy textile-grade tiers. Price differentiation rests on REACH Annex XVII certification status and mass-balance chain-of-custody documentation, with German electronics manufacturers least sensitive and Bangladeshi fiber converters most price-responsive. Cost compression in commodity textile grades is intensifying because direct PTA polymerization routes bypass DMT entirely in bottle-grade applications.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for European distributors serving mid-scale textile converters, straining working capital for merchant producers without supply-chain finance facilities. Geographic concentration centers on China, South Korea, and Germany, with feedstock dependencies on paraxylene from Gulf Coast aromatics corridors and methanol from Middle Eastern gas derivatives. Single-country supply concentration exposes converters to freight cost surges and customs processing delays during port congestion events. Distribution runs through direct sales for integrated PTA-DMT-PET producers and regional chemical distributors for smaller batch requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DMT market functions as a regulatory entrenchment story where REACH Annex XVII compliance and mass-balance certification create switching costs that lock brand-contract volumes behind qualified supplier relationships.
For Market Incumbents: Entrench position through captive paraxylene integration and ECHA-registered catalyst substitution protocols that filter non-compliant Asian merchant supply from premium packaging-grade contracts. Accelerate chemical recycling partnerships in the Netherlands and Belgium to secure ISCC PLUS certification ahead of EU Green Deal recycled-content mandates. PTA substitution in bottle-grade applications represents the primary volume threat requiring optical-grade diversification into South Korean display substrate supply chains.
For New Entrants and Emerging Players: India's underdeveloped domestic oxidation capacity creates import-dependent demand from Reliance Industries and Indorama Ventures expansion in Gujarat, where mass-balance certification gaps among existing suppliers open contract eligibility. Target optical-grade specifications for flexible electronics substrates in Taiwan and South Korea, where ultra-high-purity requirements command margin premiums beyond commodity textile grades. Pursue asset-light leasing arrangements for PET polymerization units to minimize capital intensity while building backward integration into bio-based p-xylene pathways through Anellotech or Neste partnerships.
For Investors and Strategic Acquirers: Specialized optical-grade producers with ECHA-registered protocols and existing electronics substrate relationships represent the most defensible acquisition archetype, given REACH entrenchment and display manufacturer switching costs. Long-term viability hinges on circular polyester certification adoption rates across apparel brand supply chains. Monitor EU CSRD supply-chain disclosure implementation timelines as the inflection indicator for mass-balance contract concentration versus spot-market commoditization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paraxylene Feedstocks | Eastman Chemical's captive aromatics supply insulates margin stability against naphtha price volatility cycles. |
| Mass-Balance Certification Investment | ISCC PLUS documentation gates contract eligibility with H&M and Inditex recycled-content mandates. |
| Optical-Grade Capacity Expansion | SK Chemicals' ultra-high-purity output captures premium pricing from Samsung Display substrate specifications. |
| Chemical Recycling Partnership | Netherlands-Belgium circular feedstock integration enables German converters to meet EU Green Deal thresholds. |
| Membrane-Based Methanol Recovery | OXXYNOVA's piloted systems reduce energy intensity 40% for carbon-accounted brand supply chains. |
Methodological Framework
Operator-level perspectives from polyester plant managers, downstream OEM procurement leads at beverage packaging converters, ECHA regulatory affairs specialists, and Yangtze River Delta logistics coordinators anchored the qualitative base. Secondary validation drew from REACH Annex XVII compliance databases, EU customs trade flows for DMT and PTA, SEC 10-K disclosures from integrated petrochemical majors, and MEE wastewater discharge enforcement records. Bottom-up capacity modeling across China's Zhejiang and Jiangsu provinces triangulated against top-down polyester fiber demand forecasts from Bangladesh and Vietnam textile clusters.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning purity grade tier, end-use industry, polymerization route, and regional production hub. CAGRs were derived from regression analysis of historical polyester fiber output against apparel brand recycled-content mandate adoption curves. Industry-specific forecast inputs included paraxylene-naphtha spread volatility patterns and EU CSRD disclosure timeline acceleration scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by merchant DMT specialists or accelerated bio-based p-xylene commercialization would shift outcomes. Macroeconomic crude price shocks, REACH catalyst residue threshold tightening, or breakthrough direct PET polymerization technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
PAG Base Stock Market