
 Ammonium Sulfate Market | 2026-2036
Ammonium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Sulfate Market Intelligence
A skilled agronomist workforce shortage across the North American fertilizer sector is unwinding traditional distribution models and pushing producers toward precision agriculture partnerships. BASF leverages its integrated crop nutrition platform to bundle ammonium sulfate with digital soil analytics. AdvanSix anchors its position through captive caprolactam byproduct streams that feed low-cost sulfate production. Sumitomo Chemical competes via deep roots in Asian specialty fertilizer channels.
Ammonium sulfate is an inorganic salt with the formula (NH₄)₂SO₄, containing 21% nitrogen and 24% sulfur by weight, produced primarily through the direct reaction of ammonia with sulfuric acid or as a byproduct of caprolactam manufacturing; its primary purpose is to correct sulfur deficiencies in alkaline soils while supplying readily available nitrogen for crop uptake. Granular grades dominate volume due to superior handling and blending compatibility with bulk fertilizer systems, while slow-release formulations command premium positioning in high-value horticultural and turf management segments. Powder variants sustain steady demand in water treatment and industrial feed supplement applications where rapid dissolution is essential.
EPA nutrient management standards under the Clean Water Act and REACH registration requirements in Europe constrain product formulations and mandate emission controls during manufacturing. Fertilizer quality certifications from ISO and national agricultural departments shape import eligibility and farmer procurement decisions. Stakeholders must monitor evolving sulfur recovery regulations and carbon border adjustments that could restructure feedstock sourcing economics.
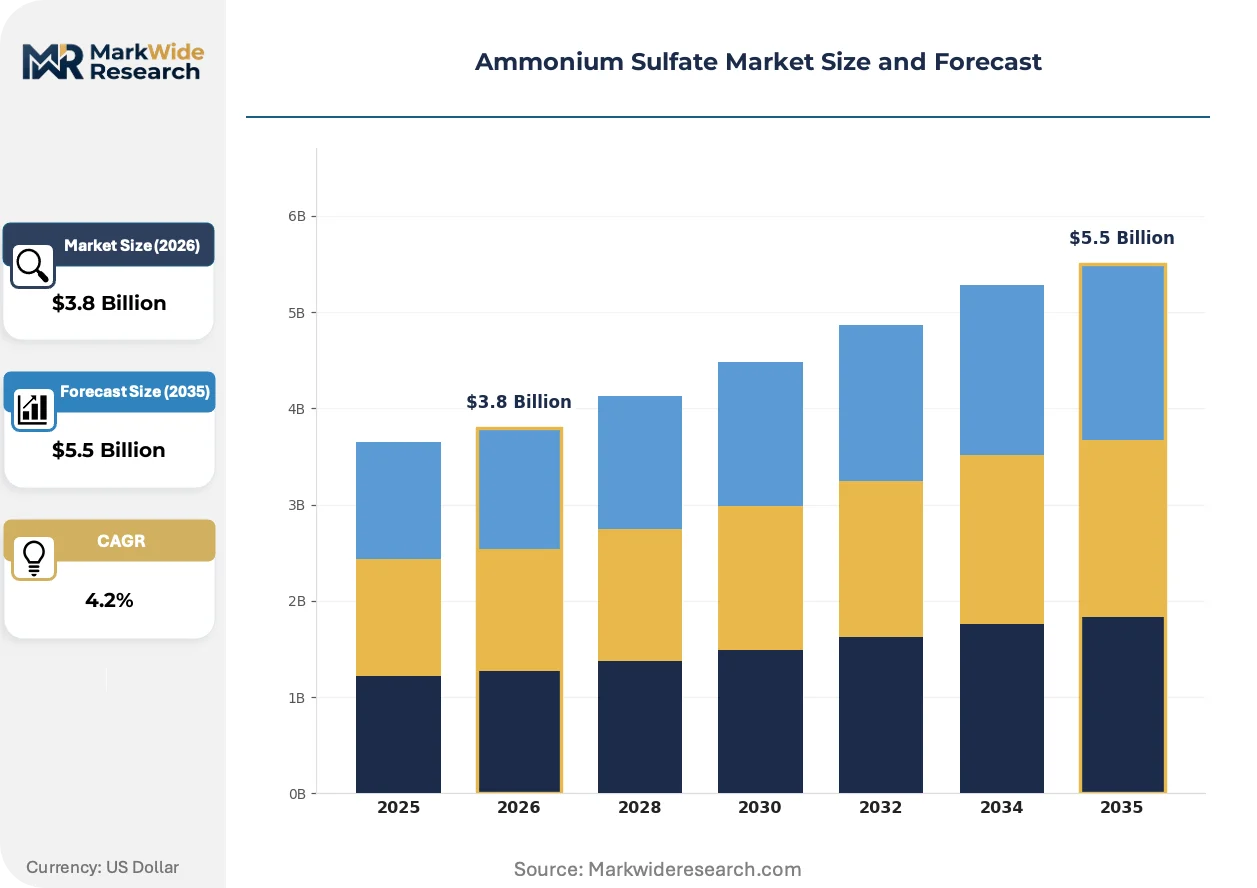
Market Dynamics
Sulfur-deficiency correction in precision agriculture is pulling ammonium sulfate into bundled crop nutrition platforms, while EPA nutrient management rules and REACH compliance reshape formulation standards and manufacturing emissions controls across major production centers.
Growth Catalysts
- Specialty fertilizer channels:Precision agriculture adoption in the United States Corn Belt drives consistent offtake as growers seek targeted sulfur supplementation for depleted soils.
- REACH compliance thresholds:European product quality mandates are accelerating premium-grade ammonium sulfate demand among quality-certified importers and blenders.
- Caprolactam byproduct streams:Captive sulfate production from synthetic fiber manufacturing creates low-cost supply anchors that sustain price-competitive positioning in bulk fertilizer markets.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress manufacturing margins for acid-route production facilities concentrated in energy-import-dependent regions.
- Single-source supply risk:Caprolactam-derived sulfate output ties fertilizer volumes to synthetic fiber demand cycles, creating volume inflexibility during textile sector downturns.
- UREA substitution pressure:Nitrogen-only fertilizers command farmer preference in sulfur-adequate soils, limiting ammonium sulfate penetration in balanced-nutrition markets.
Strategic Opportunities
- Slow-release formulation expansion:Premium horticultural and turf management segments reward sulfur-coated variants with sustained nutrient release profiles.
- Water treatment applications:Powder-grade rapid-dissolution specifications are capturing industrial feed supplement demand from municipal treatment facilities.
- Carbon border adjustment positioning:EU Green Deal implementation creates first-mover advantages for producers with verified low-emission manufacturing footprints.
Industry Challenges
- Agronomist workforce scarcity:North American fertilizer distribution networks face technical advisory gaps that complicate precision agriculture partnership execution.
- ISO certification timelines:Multi-stage fertilizer quality audits delay import eligibility for new market entrants seeking national agricultural department approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Sulfate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Slow-Release End Use Industry: Agriculture, Horticulture, Fertilizers, Food Processing Application: Soil Amendment, Fertilization, Feed Supplements, Water Treatment Packaging Type: Bags, Bulk, Drums, Totes |
| Companies Covered | BASF, Evonik Industries, LANXESS, Sumitomo Chemical, Domo Chemicals, AdvanSix, Arkema, Novus International, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Sulfate Market Strategic Shifts & Innovations
Digital soil analytics integration is restructuring how sulfur-deficiency correction gets prescribed and procured, compressing traditional dealer networks while elevating platform-based bundled offerings.
Controlled-release coating technology is displacing conventional granular applications in high-value crop segments. Specialty vegetable producers in California's Central Valley and Florida's citrus belt are adopting polymer-sulfur matrix formulations at accelerating rates. This displacement is compressing commodity-grade pricing power while opening margin pools in certified-sustainable supply chains.
EPA Clean Water Act nutrient management standards are tightening discharge permits for nitrogen runoff from agricultural watersheds. Manufacturing facilities face upgraded scrubber and wastewater treatment capex to maintain operating licenses. Corn Belt fertilizer blenders are responding by shifting toward enhanced-efficiency formulations that reduce field-application frequency.
Farmer buying committees are consolidating procurement through cooperative purchasing platforms that bypass traditional dealer markups. Large-scale operations in Illinois and Iowa are aggregating seasonal volume commitments through digital marketplaces. This disintermediation is most visible among operations exceeding 5,000 managed acres where logistics coordination justifies direct manufacturer relationships.
Ammonium Sulfate Market Segmentation
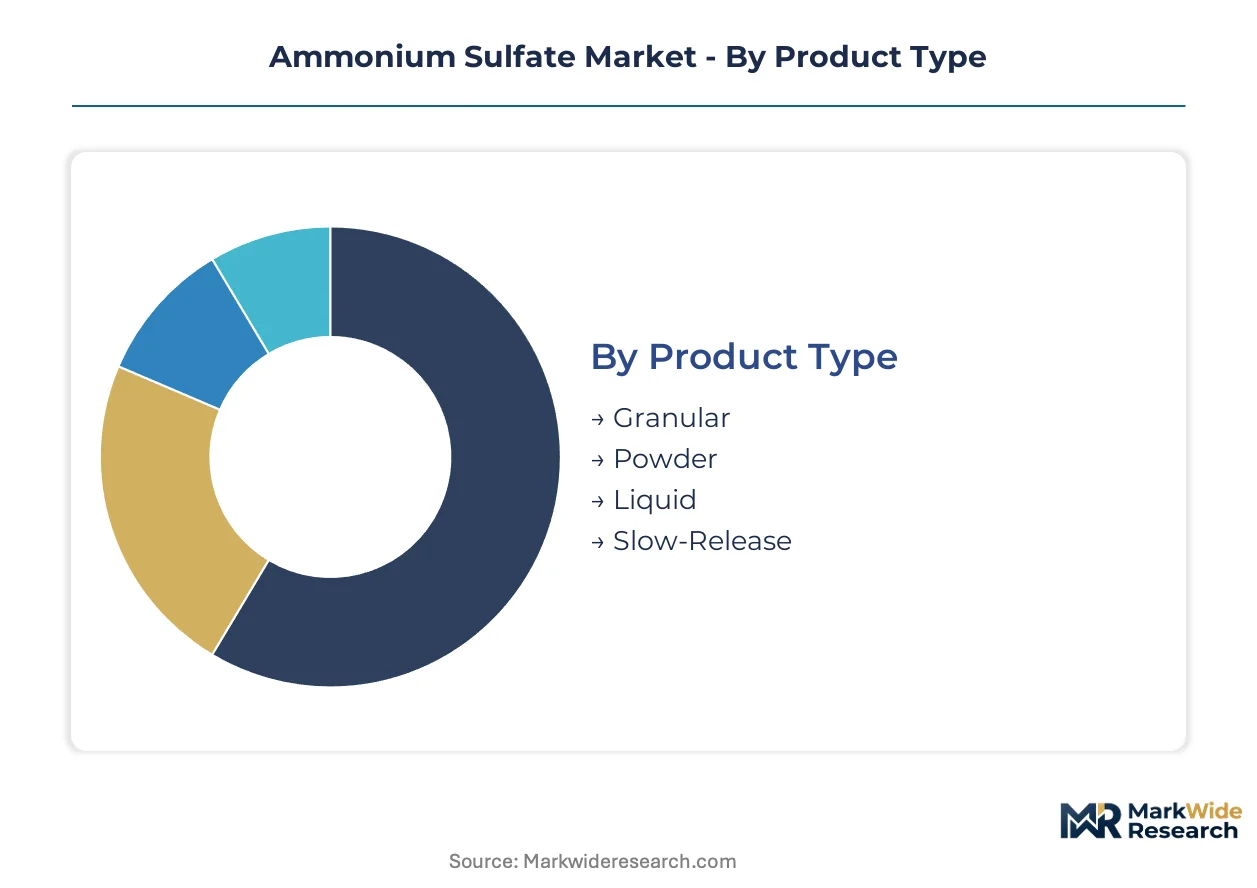
Margin capture in ammonium sulfate varies sharply by physical form and application specificity. Producers with coating capabilities and certified agricultural channels command sustained premiums over commodity acid-route manufacturers.
Product Type:
Granular and slow-release formulations concentrate margin pools through handling efficiency and premium horticultural positioning, while powder and liquid grades compete on volume throughput in industrial channels.
- Granular:Standard spherical particles sized 2-4mm enable mechanical spreading and bulk blending with NPK fertilizers. United States Corn Belt operations favor this grade for sulfur-deficiency correction in continuous corn-soybean rotations, with demand anchored by precision agriculture platform bundling.
- Slow-Release:Sulfur-polymer or resin-coated granules meter nutrient release over 6-12 weeks. California Central Valley vegetable producers and Florida citrus operations absorb premium pricing for reduced application frequency and runoff compliance under EPA Clean Water Act watershed permits.
- Powder:Rapid-dissolution specifications serve water treatment facilities and industrial feed supplement formulators where immediate ionic availability is essential.
- Liquid:Pre-dissolved solutions integrate with fertigation systems and aerial application services in high-value crop districts.
Granular holds installed capacity. Slow-release is rotating up the share rankings.
End Use Industry:
Volume concentration tracks sulfur-depleted soil geographies, with agricultural procurement dwarfing specialty channels despite lower per-ton margins.
- Agriculture:Row-crop operations across Illinois, Iowa, and Indiana drive baseline consumption for sulfur-deficiency correction in high-yield corn systems. Cooperative purchasing platforms are consolidating procurement among operations exceeding 5,000 managed acres.
- Horticulture:Greenhouse and nursery operators in the Netherlands and Belgium adopt precision sulfate dosing for substrate-grown vegetables and ornamental propagation, with quality certifications from national agricultural departments shaping supplier eligibility.
- Fertilizers:Bulk blenders and compound fertilizer manufacturers incorporate ammonium sulfate as a sulfur source in NPK formulations for distribution through agricultural retail networks.
- Food Processing:Food-grade specifications serve yeast fermentation and dough conditioning applications under FDA and EFSA purity standards.
Agriculture absorbs volume concentration. Horticulture is climbing the fastest on margin contribution.
Application:
Soil amendment and fertilization applications dominate tonnage, while feed supplements and water treatment sustain steady demand through specification-driven procurement.
- Soil Amendment:Alkaline soil pH correction in arid and semi-arid growing regions drives consistent offtake, with application rates calibrated through digital soil analytics platforms that integrate with variable-rate equipment.
- Fertilization:Direct crop nutrition supplies nitrogen and sulfur in plant-available forms, with EPA nutrient management standards under the Clean Water Act tightening runoff controls and pushing adoption of enhanced-efficiency formulations.
- Feed Supplements:Ruminal protein sources for dairy and beef cattle operations meet amino acid requirements in sulfur-deficient forage systems.
- Water Treatment:Municipal and industrial facilities employ rapid-dissolution powder grades for pH adjustment and flocculation processes.
Fertilization commands volume leadership. Water treatment is expanding most quickly in specification-grade niches.
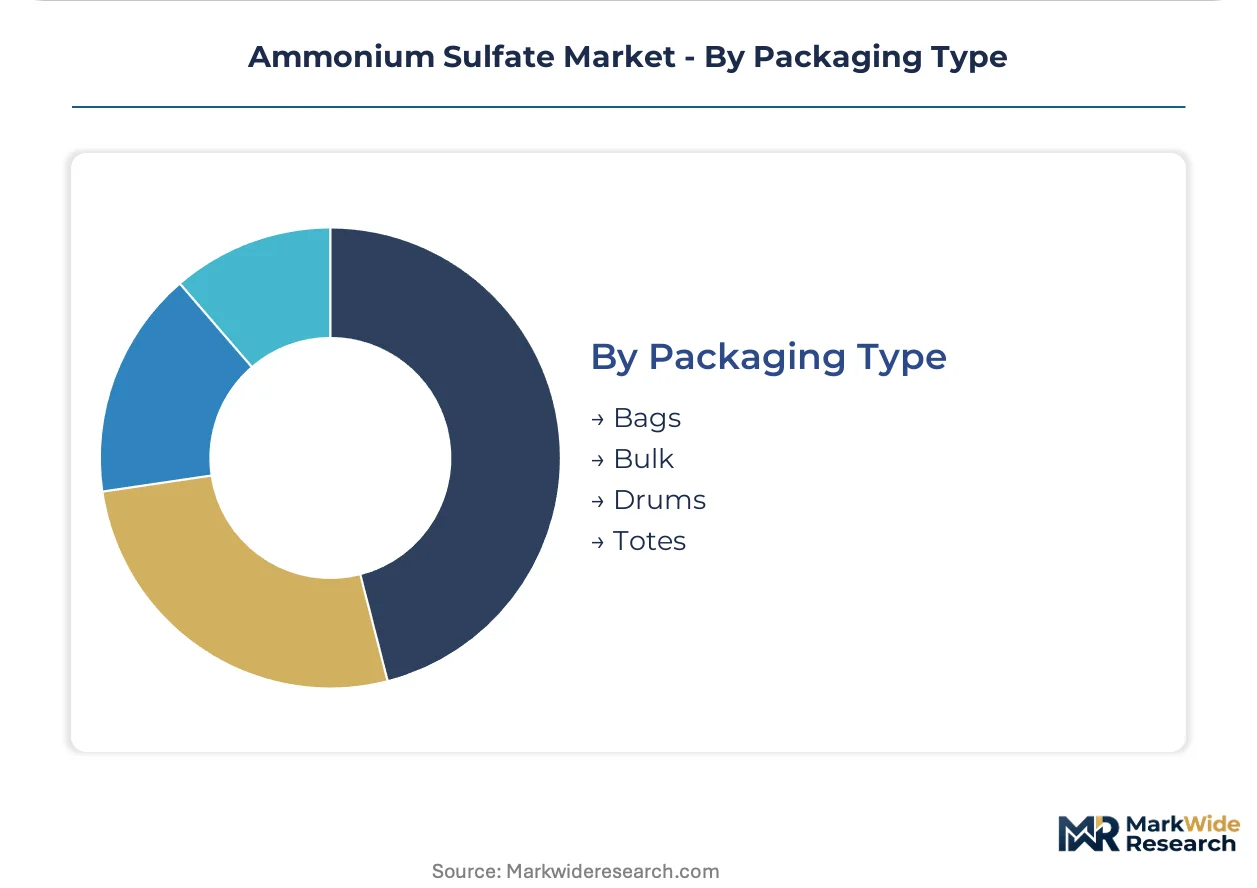
Packaging Type:
Cost tier stratification separates bulk commodity movements from certified small-package channels serving specialty applicators.
- Bulk:Railcar and pneumatic truck deliveries serve Corn Belt fertilizer blenders and compound manufacturers with minimum order thresholds that exclude smaller operations.
- Bags:25-50kg woven polypropylene units enable retail distribution through agricultural supply cooperatives and independent dealers.
- Drums:Steel and fiber containers protect hygroscopic powder grades during storage and transport for industrial chemical applications.
- Totes:Intermediate bulk containers consolidate liquid and semi-bulk powder shipments for mid-scale horticultural and water treatment facilities.
Bulk retains infrastructure dominance. Totes are gaining share fastest among mid-tier operations seeking flexible procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography, with the United States Corn Belt favoring bulk granular grades for sulfur-deficiency correction while European horticulture clusters absorb premium slow-release formulations under REACH-mandated quality thresholds.
United States
Illinois and Iowa row-crop operations drive granular sulfate demand through cooperative purchasing platforms that aggregate volumes above 5,000 managed acres. EPA Clean Water Act nutrient management standards tighten discharge permits for nitrogen runoff, pushing Corn Belt blenders toward enhanced-efficiency formulations. Precision agriculture partnerships in Indiana integrate digital soil analytics with variable-rate application equipment.
Germany
Rhineland-Palatinate and Lower Saxony chemical manufacturing clusters supply both acid-route and caprolactam-derived sulfate grades to domestic and export markets. REACH registration requirements constrain product formulations and mandate emission controls during production. BASF's Ludwigshafen complex anchors integrated crop nutrition platforms that bundle sulfate with digital advisory services.
China
Shandong and Jiangsu provinces concentrate caprolactam byproduct sulfate output tied to synthetic fiber manufacturing cycles. The country's national environmental regulator enforces sulfur recovery standards that reshape feedstock sourcing economics. Yangtze River Delta fertilizer blenders serve high-value horticultural districts with specification-grade material.
Brazil
São Paulo and Paraná soybean-corn rotations generate consistent sulfur supplementation demand as double-cropping intensifies soil nutrient depletion. The national agricultural regulator certifies import eligibility for quality-compliant sulfate sources. Mato Grosso bulk terminals handle rising granular volumes for distribution through agricultural retail networks.
Netherlands
North Brabant greenhouse operators adopt precision sulfate dosing for substrate-grown vegetables under EU Green Deal sustainability protocols. ECHA enforcement of REACH thresholds accelerates premium-grade demand among certified importers. Rotterdam port infrastructure enables efficient re-export distribution to Belgian and German horticulture clusters.
Ammonium Sulfate Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting dual feedstock routes—direct acid reaction and caprolactam byproduct recovery—that create divergent cost positions. Three archetypes dominate: diversified chemical conglomerates with captive ammonia supply, synthetic fiber manufacturers monetizing sulfate byproduct streams, and regional blenders sourcing merchant material for formulation. Capacity expansion and strategic partnerships represent the prevailing competitive moves, as players seek to secure agronomist advisory capabilities and lock in Corn Belt distribution relationships.
Within the integrated chemical tier, BASF and Evonik Industries exemplify archetypes combining upstream ammonia access with downstream crop nutrition platforms. AdvanSix occupies a position representing caprolactam-derived sulfate specialists that leverage synthetic fiber manufacturing integration for cost-competitive bulk positioning. Sumitomo Chemical anchors the Asia-Pacific regional vector through established specialty fertilizer channel relationships.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| LANXESS |
| Sumitomo Chemical |
| Domo Chemicals |
| AdvanSix |
| Arkema |
| Novus International |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
REACH registration requirements in Europe and EPA nutrient management standards in the United States simultaneously gate supply qualification and stratify price differentiation, with certified low-emission manufacturing footprints commanding premium positioning against commodity acid-route volumes.
Pricing Analysis
Long-term offtake contracts dominate Corn Belt procurement through cooperative purchasing platforms, while spot transactions sustain powder-grade industrial channels. Price differentiation rests on sulfur recovery certification tiers and carbon intensity verification under EU Green Deal protocols. Cost compression in standard granular grades is intensifying because caprolactam byproduct streams flood bulk markets during synthetic fiber downturns. Row-crop operations exceeding 5,000 managed acres exhibit highest price sensitivity; premium slow-release horticultural buyers show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Yangtze River container availability constrain European and Asian supply responsiveness respectively. Production gravity centers on Germany, China, and the United States, with feedstock economics drawing from natural gas-priced ammonia routes and captive caprolactam byproduct recovery. Single-source vulnerability runs through synthetic fiber demand cycles that throttle caprolactam-derived sulfate volumes. Distribution runs through railcar bulk terminals serving Corn Belt blenders and pneumatic truck networks for water treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ammonium sulfate market rewards producers with integrated agronomist advisory capabilities, yet technical workforce gaps across North American distribution networks constrain partnership execution for platform-based bundled offerings.
For Market Incumbents: Compound platform integration advantages by embedding digital soil analytics with variable-rate application equipment in Illinois and Iowa cooperative purchasing networks. Deepen backward integration into captive ammonia supply or sulfur recovery infrastructure to offset feedstock volatility from natural gas price swings. Prioritize ISO certification maintenance against tightening EPA Clean Water Act discharge permit thresholds. For New Entrants and Emerging Players: Differentiate on rapid-dissolution powder specifications for municipal water treatment facilities where incumbent agricultural channels hold weaker positions. White-space targets include mid-scale horticultural operations in the Netherlands and Belgium seeking REACH-compliant substrate dosing solutions. Pursue tote-based flexible procurement models that bypass bulk terminal infrastructure requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across slow-release coating capabilities as polymer-sulfur matrix R&D demands specialized equipment investment. Long-term viability favors producers with verified low-emission manufacturing footprints positioned for EU carbon border adjustment implementation. Acquisition target archetype: regional blenders with locked Corn Belt distribution relationships and pending quality certification timelines. Signal to watch: agronomist workforce scarcity indices in North American fertilizer sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive feedstock supply insulates margin compression from natural gas volatility in acid-route production. |
| Slow-Release Coating Capacity Expansion | Polymer-sulfur matrix capabilities capture premium positioning in California Central Valley vegetable districts. |
| Precision Agriculture Partnership | Digital soil analytics bundling locks in Corn Belt cooperative purchasing platform volumes above 5,000 acres. |
| REACH Certification Investment | European quality thresholds gate import eligibility for Rotterdam re-export distribution to horticulture clusters. |
| Water Treatment Specification Development | Rapid-dissolution powder grades serve municipal pH adjustment demand outside agricultural seasonality cycles. |
Research Approach
Operator-level perspectives from fertilizer plant managers, Corn Belt procurement leads at agricultural cooperatives, distribution channel partners, and technical R&D directors anchored the qualitative base. Secondary validation drew from EPA discharge permit filings, ECHA REACH registration databases, USDA agricultural census data, and customs trade records. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness across ammonia feedstock price scenarios and synthetic fiber demand cycle variations. Segmentation dimensions modeled included physical form tier, end-use industry concentration, application specificity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year consumption estimates, with fertilizer quality certification timelines and carbon border adjustment implementation schedules serving as key inflection inputs.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued Corn Belt sulfur-depletion correction demand; material deviation would warrant model refresh. Forecasts incorporate EPA nutrient management standard evolution and EU Green Deal carbon intensity verification protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Tertiary Butylhydroquinone Market