
 Asia-Pacific Solid Sulfur Market | 2026-2036
Asia-Pacific Solid Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solid Sulfur Market Insights
Middle Eastern sour crude processing is shifting additional sulfur volumes toward Asian offtake markets. Sinopec leverages integrated refinery-fertilizer complexes along China's eastern coast to capture value from recovered sulfur. CNPC anchors northwest Asian supply through pipeline-connected processing hubs in Xinjiang and Gansu. IOCL competes on logistics scale, operating dedicated sulfur handling infrastructure at multiple coastal refineries.
Asia-Pacific solid sulfur refers to elemental sulfur in stable crystalline or formed states, typically exceeding 99.5% purity, produced through Claus process recovery from hydrogen sulfide-bearing gas streams or mined from volcanic and sedimentary deposits; it functions primarily as a feedstock for sulfuric acid manufacturing and direct soil amendment in agriculture. Granular product dominates procurement volumes among fertilizer companies due to superior flowability and reduced dust generation during bulk handling. Powdered sulfur leads chemical manufacturing applications where rapid dissolution kinetics offset higher handling costs. Direct sales channels control the largest value pool, reflecting long-term offtake contracts between refineries and industrial consumers that bypass intermediary markups.
China's MEE enforces sulfur recovery mandates at refineries and petrochemical complexes, tightening specifications for solid sulfur purity and packaging. India's CEA coordinates with fertilizer ministry directives to prioritize domestic sulfur allocation for urea and DAP production. BIS quality certifications shape import acceptance criteria at Indian ports, filtering non-compliant Middle Eastern shipments. Stakeholders must monitor regulatory divergence between Chinese emissions enforcement and Indian fertilizer subsidy mechanics to anticipate supply allocation shifts.
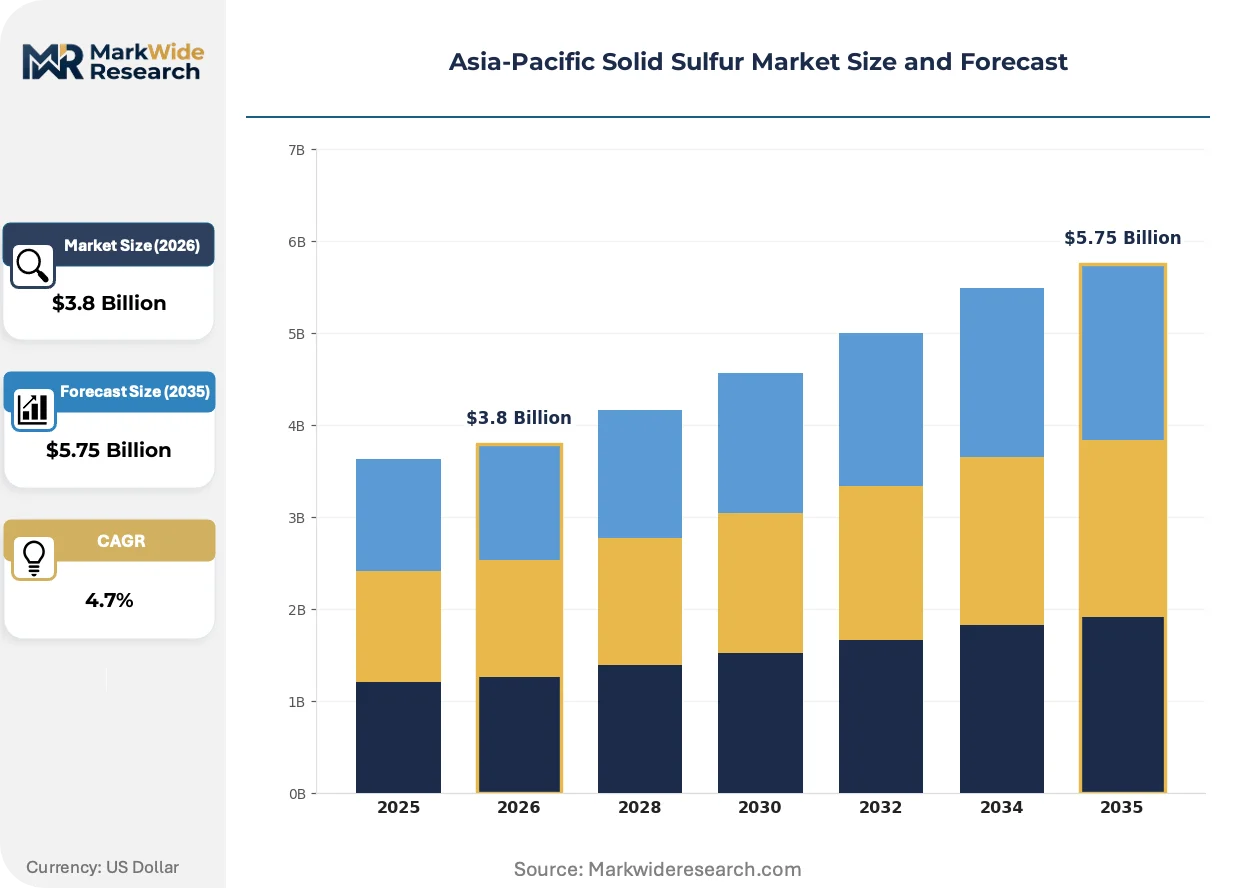
Market Dynamics
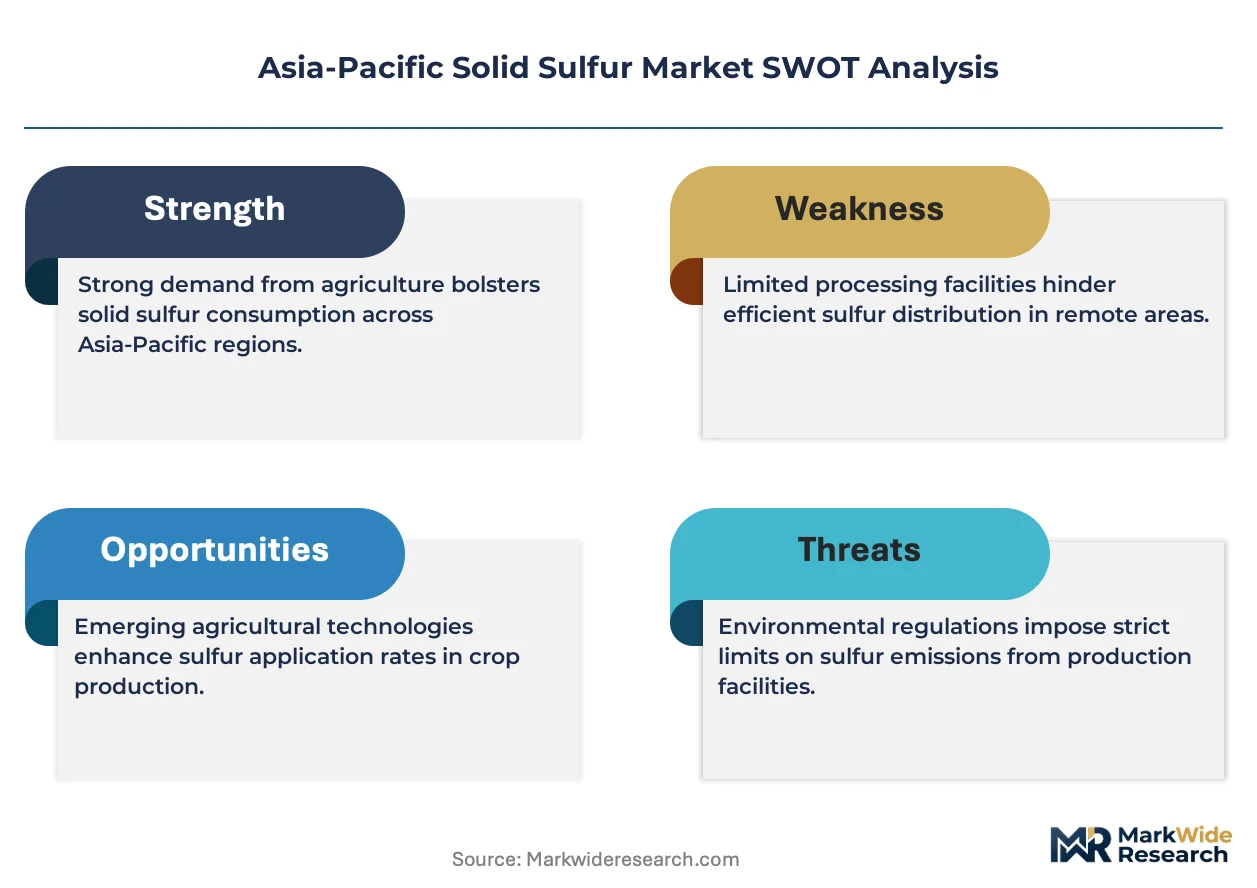
Refinery sulfur recovery mandates across Asia-Pacific are redirecting supply streams toward higher-purity solid outputs, compressing legacy processing margins while elevating quality premiums for compliant producers.
Growth Catalysts
- India's fertilizer subsidy mechanics:Priority domestic sulfur allocation for urea and DAP production is securing dedicated offtake volumes from coastal handling terminals.
- Claus process efficiency gains:Advanced tail gas treatment technologies are pushing recovery rates above 99.5% purity thresholds demanded by chemical manufacturers.
- China's dual carbon framework:MEE emissions standards are forcing refinery upgrades that yield premium-grade solid sulfur as a byproduct rather than waste.
Market Restraints
- Middle Eastern supply concentration:Sour crude processing hubs in the Gulf states control marginal export volumes, exposing Asian buyers to shipping cost volatility and geopolitical transit risks.
- Natural gas input cost sensitivity:Claus process hydrogen production depends on natural gas feedstock pricing, which fluctuates with regional LNG spot markets.
- Phosphate fertilizer substitution pressure:Compound fertilizers with reduced sulfur content are gaining traction in precision agriculture segments, threatening direct soil amendment demand.
Strategic Opportunities
- Vietnam's underdeveloped sulfuric acid sector:Fertilizer cooperatives in the Mekong Delta lack integrated acid plants, creating openings for packaged sulfur distributors.
- Indonesia's nickel processing expansion:Battery-grade nickel refineries require sulfuric acid leaching, pulling solid sulfur into new metallurgical applications outside agriculture.
- Pipeline-connected inland hubs:Xinjiang and Gansu processing complexes offer captive supply chains that bypass congested coastal port infrastructure.
Industry Challenges
- BIS certification timelines:Indian port authorities reject non-compliant Middle Eastern shipments, creating inventory stranded at sea and working capital compression for traders.
- Legacy handling infrastructure:Bulk terminals at Paradip and Visakhapatnam require dust suppression retrofits to meet granular sulfur specifications, demanding capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solid Sulfur Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Flake, Liquid Application: Agriculture, Chemical Manufacturing, Rubber Production, Pharmaceuticals End User: Fertilizer Companies, Industrial Manufacturers, Construction Firms, Oil Refineries Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Saudi Aramco, Abu Dhabi National Oil Company (ADNOC), China National Petroleum Corporation (CNPC), China Petroleum & Chemical Corporation (Sinopec), Shell plc, Gazprom, Indian Oil Corporation Limited (IOCL), Suncor Energy Inc., Koch Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solid Sulfur Market Trends and Innovations
Processing technologies and procurement architectures are converging to reshape how elemental sulfur moves from refinery stack to end-use conversion, with purity grades and logistics configurations becoming primary competitive differentiators.
Molten sulfur forming and prilling technologies are electrifying traditional flaking operations. Fertilizer cooperatives in India and Indonesia are adopting these systems to reduce dust generation during bulk handling. The shift is compressing margins for legacy cast sulfur producers while enabling premium pricing for flowable granular product.
China's MEE is tightening sulfur recovery mandates at refineries and petrochemical complexes, with new specifications for solid sulfur purity and packaging. Industrial clusters along the eastern coast are retrofitting Claus units to meet these thresholds. Chemical manufacturers sourcing feedstock are now filtering suppliers through compliance certification gates.
Long-term offtake contracting is displacing spot market trading among integrated refinery-fertilizer complexes. Direct sales channels between producers and industrial consumers are consolidating volume commitments that bypass intermediary traders. This pattern is most visible in China and India, where state-linked energy companies are internalizing sulfur supply chains.
Asia-Pacific Solid Sulfur Market Segmentation
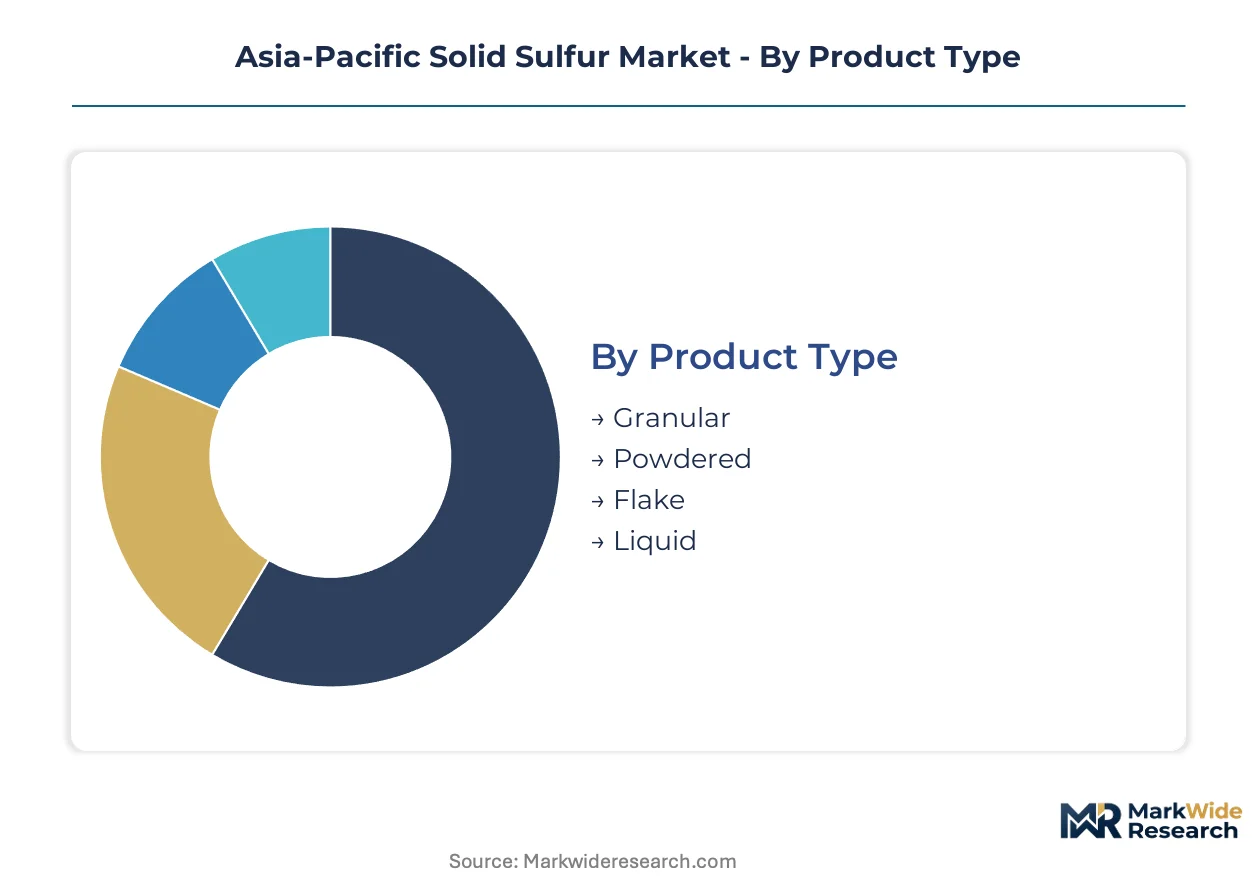
Segmentation in the Asia-Pacific solid sulfur market reveals how purity grades, handling properties, and procurement channels command distinct pricing premiums. Refinery output specifications and fertilizer cooperative requirements are splitting procurement patterns across technical and commercial dimensions.
Product Type:
Buyers differentiate primarily by flowability needs and dust generation tolerance during bulk handling operations.
- Granular:Formed sulfur with spherical particle geometry between 2-4mm diameter, produced through molten sulfur prilling or wet granulation. Fertilizer cooperatives in India's Paradip and Visakhapatnam terminals specify granular for automated bulk handling systems. MEE emissions standards in China are pushing refineries toward granular output to minimize particulate release during storage.
- Powdered:Micronized sulfur with particle sizes below 100 mesh, offering rapid dissolution kinetics for chemical synthesis. Chemical manufacturers in China's eastern coastal clusters source powdered grades for sulfuric acid catalysis where reaction speed offsets handling complexity.
- Flake:Cast sulfur formed through rapid cooling of molten streams on water-cooled drums. Legacy production persists at smaller refineries in Indonesia and Vietnam lacking prilling infrastructure.
- Liquid:Molten sulfur maintained at 115-140°C for pipeline transport and direct industrial consumption. IOCL's dedicated handling terminals use heated storage for liquid transfer to adjacent fertilizer complexes.
Granular leads volumes today; powdered is gaining share fastest.
Application:
End-use chemistry determines sulfur purity thresholds and packaging specifications across procurement contracts.
- Agriculture:Direct soil amendment and phosphate fertilizer feedstock consuming the largest volume share. India's urea and DAP production under CEA-coordinated subsidy programs anchors regional demand.
- Chemical Manufacturing:Sulfuric acid production for industrial feedstocks and battery materials. Indonesia's nickel processing expansion is pulling solid sulfur into hydrometallurgical leaching circuits.
- Rubber Production:Vulcanization accelerator applications requiring high-purity grades with controlled ash content. Southeast Asian tire manufacturing clusters source specified sulfur for cross-linking chemistry.
- Pharmaceuticals:Ultra-pure grades for active pharmaceutical ingredient synthesis. Stringent BIS certification requirements filter import shipments at Indian ports.
Agriculture dominates contract volumes; chemical manufacturing shows the steepest expansion trajectory.
End User:
Scale of operations and integration depth separate procurement behaviors across buyer categories.
- Fertilizer Companies:Integrated phosphate producers and urea manufacturers with dedicated sulfur handling infrastructure. Sinopec's refinery-fertilizer complexes capture captive supply from Claus process recovery.
- Industrial Manufacturers:Chemical processors, pigment producers, and specialty material makers purchasing on specification rather than volume. BIS quality certifications shape supplier qualification at Indian ports.
- Construction Firms:Asphalt modification and concrete additive applications consuming lower-purity grades. Vietnam's infrastructure build-out is generating spot demand for construction-grade sulfur.
- Oil Refineries:Internal sulfur recovery operations supplying affiliated chemical complexes. CNPC's Xinjiang and Gansu hubs pipeline solid sulfur to inland processing facilities.
Fertilizer companies anchor procurement volumes; industrial manufacturers are diversifying supplier bases most aggressively.
Distribution Channel:
Contract duration and price discovery mechanisms vary sharply across channel structures.
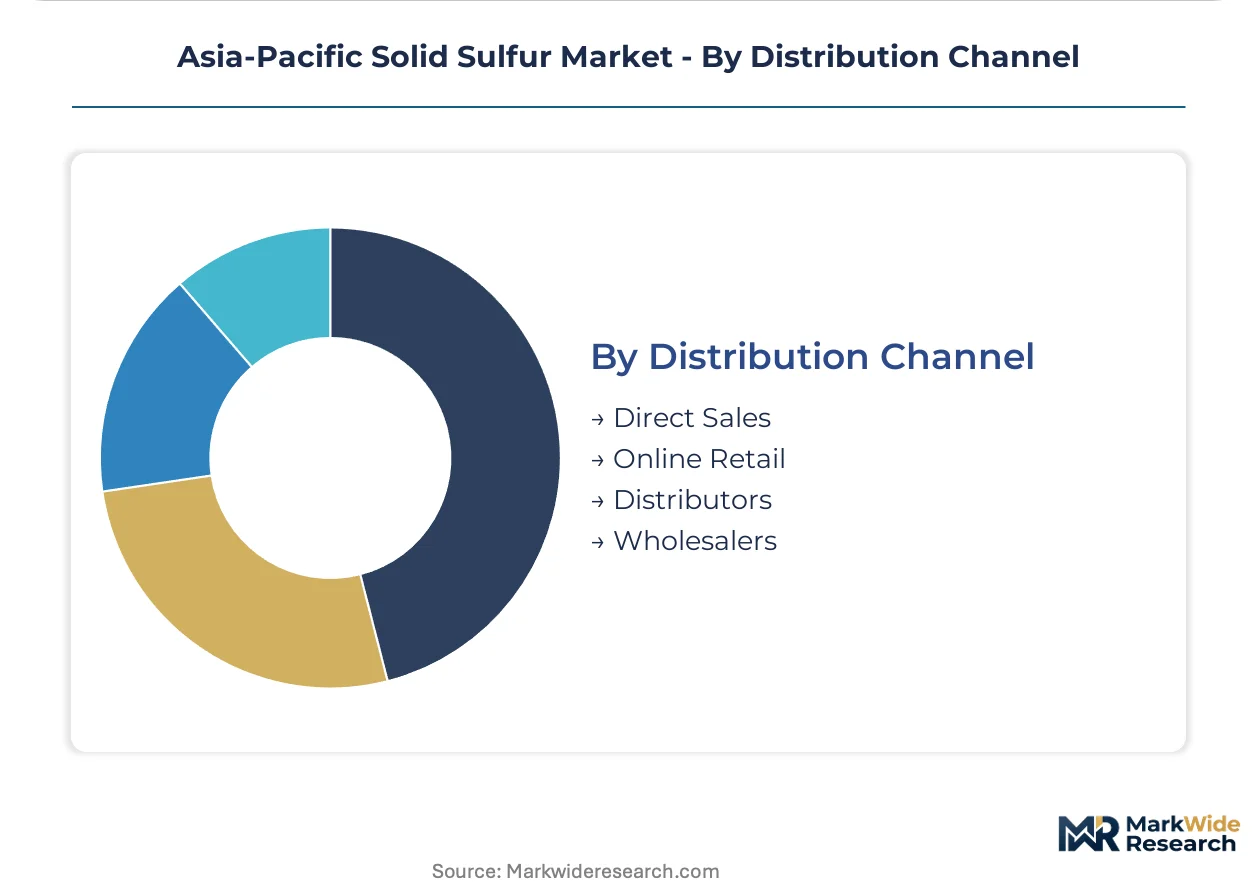
- Direct Sales:Long-term offtake agreements between refineries and industrial consumers bypassing intermediary markups. State-linked energy companies in China and India are internalizing sulfur supply chains through direct contracting.
- Distributors:Regional stockists providing packaged sulfur and technical support to mid-scale chemical processors. Mekong Delta fertilizer cooperatives rely on distributors where integrated acid plants are absent.
- Wholesalers:Bulk volume aggregators serving construction and smaller agricultural buyers. Spot market exposure concentrates in this channel.
- Online Retail:Digital platforms for packaged sulfur and specialty grades, currently marginal in regional trade.
Direct sales control the largest value pool; distributor networks are expanding fastest in Southeast Asian markets lacking refinery integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between emissions enforcement intensity and fertilizer subsidy mechanics is redirecting solid sulfur procurement flows across the Asia-Pacific. Producers in jurisdictions with stricter MEE mandates capture quality premiums, while Indian coastal terminals absorb volume diverted from Middle Eastern sour crude processing.
China
Claus process upgrades at eastern coastal refineries are yielding sulfur exceeding 99.5% purity thresholds. MEE emissions standards force stack gas recovery investments that upgrade byproduct quality. Sinopec's integrated refinery-fertilizer complexes in Shandong and Jiangsu pipeline molten sulfur directly to adjacent acid plants.
India
CEA-coordinated subsidy programs prioritize domestic sulfur allocation for urea and DAP production at Paradip and Visakhapatnam. BIS certification requirements filter import shipments, stranding non-compliant Middle Eastern cargoes. IOCL operates dedicated handling terminals at multiple coastal refineries to secure captive supply.
Japan
METI industrial efficiency directives drive sulfur recovery optimization at residual fuel oil processors. JIS quality standards shape import acceptance criteria for chemical manufacturing feedstock. Chubu region refineries supply specialty-grade sulfur to tire manufacturing clusters in Aichi and Osaka prefectures.
Indonesia
Nickel processing expansion in Sulawesi and Halmahera pulls solid sulfur into hydrometallurgical leaching circuits for battery-grade production. Fertilizer cooperatives in the Java corridor rely on distributor networks where integrated acid plants remain absent. State-owned energy holding Pertamina evaluates Claus unit retrofits at Cilacap and Balikpapan refineries.
Vietnam
Mekong Delta fertilizer cooperatives lack integrated sulfuric acid capacity, creating openings for packaged sulfur distributors. Construction-grade demand from infrastructure build-out in Ho Chi Minh City corridor absorbs lower-purity spot volumes. Dung Quat refinery evaluates molten sulfur forming investments to supply regional chemical processors.
Asia-Pacific Solid Sulfur Market Competitive Landscape
Middle Eastern producers anchor the export supply tier; Chinese and Indian state-linked energy groups hold integrated domestic positions. Market structure splits between refinery-captive output and merchant trading volumes. Three archetypes dominate: sour crude processors with stack gas recovery, state-linked energy conglomerates with fertilizer integration, and regional distributors serving fragmented agricultural offtake. Competitive moves concentrate on Claus unit efficiency upgrades and long-term offtake contracting that displaces spot market exposure.
Within the state-linked integrated tier, China National Petroleum Corporation and Sinopec exemplify refinery-fertilizer complex models that internalize sulfur supply chains. Indian Oil Corporation Limited occupies a position bridging captive production and coastal terminal logistics scale. Among Middle Eastern exporters, Saudi Aramco and Abu Dhabi National Oil Company represent sour crude processing hubs that control marginal export volumes directed toward Asian offtake markets.
| Leading Market Players |
|---|
| Saudi Aramco |
| Abu Dhabi National Oil Company (ADNOC) |
| China National Petroleum Corporation (CNPC) |
| China Petroleum & Chemical Corporation (Sinopec) |
| Shell plc |
| Gazprom |
| Indian Oil Corporation Limited (IOCL) |
| Suncor Energy Inc. |
| Koch Industries |
| Others |
Pricing and Supply Chain Analysis
China's MEE emissions standards gate qualified supply and premium-tier pricing access by forcing refinery upgrades that yield higher-purity solid sulfur outputs. Compliance certification separates premium granular product from legacy flake grades, compressing margins for non-compliant producers while elevating quality premiums for MEE-certified suppliers serving chemical manufacturers and fertilizer cooperatives.
Pricing Analysis
Distributor margins compress pricing power for packaged sulfur distributors serving Mekong Delta fertilizer cooperatives where integrated acid plants remain absent. The dominant pricing structure runs through long-term offtake contracts between refineries and industrial consumers, with price differentiation anchored in BIS certification tiers and volume scale commitments. Pricing pressure stems from Middle Eastern sour crude supply concentration exposing Asian buyers to shipping cost volatility. Fertilizer companies demonstrate highest price sensitivity due to CEA-coordinated subsidy mechanics, while pharmaceutical-grade buyers show lowest sensitivity given stringent purity requirements.
Supply Chain Analysis
Returns and remanufacturing flows are minimal given sulfur's consumable nature, though molten sulfur reheating at IOCL's Paradip and Visakhapatnam terminals creates circular thermal energy recovery. Geographic supply concentrates in China, Saudi Arabia, and the United Arab Emirates, with raw material dependencies on sour crude processing, natural gas feedstock for Claus hydrogen production, and sulfuric acid catalyst materials. Single-source vulnerability from Middle Eastern export hub concentration threatens supply continuity. Distribution runs through direct sales channels controlling the largest value pool, with distributor networks expanding fastest in Southeast Asian markets lacking refinery integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through Claus process efficiency gains that reduce natural gas input costs while pushing recovery rates above premium-grade purity thresholds. Premium-tier shifts toward granular product specifications enable pricing power capture from fertilizer cooperatives upgrading bulk handling infrastructure.
For Market Incumbents: Acquire dedicated sulfur handling terminals at strategic coastal locations to secure captive supply positions against Middle Eastern export volatility. Sinopec's integrated refinery-fertilizer complex model demonstrates how backward integration into Claus process recovery insulates against spot market exposure. Incumbents should prioritize BIS certification investments to filter non-compliant import competition at Indian ports. For New Entrants and Emerging Players: Vietnam's Mekong Delta fertilizer cooperatives present an underserved buyer archetype lacking integrated sulfuric acid capacity and dependent on packaged sulfur distributors. New entrants should target Indonesia's nickel processing expansion in Sulawesi and Halmahera, where battery-grade refineries require sulfuric acid leaching feedstock outside traditional agricultural demand. A technical service-led go-to-market angle differentiates against commodity traders. For Investors and Strategic Acquirers: Roll-up economics work for regional packaged sulfur distributors because geographic fragmentation across Southeast Asian markets prevents scale concentration by global traders. The five-to-ten-year viability window favors acquisition of distributor networks with established BIS certification pathways and coastal terminal access. Monitor CEA subsidy program adjustments and MEE enforcement intensity as inflection indicators for supply allocation shifts between Chinese and Indian demand centers.| Strategic Initiative | Industry Significance |
|---|---|
| Claus Unit Efficiency Upgrade | Advanced tail gas treatment at Sinopec complexes pushes recovery rates above premium-grade thresholds demanded by chemical manufacturers. |
| Backward Integration into Terminal Infrastructure | IOCL's dedicated handling terminals at Paradip and Visakhapatnam bypass congested port infrastructure and secure captive supply. |
| BIS Certification Investment | Quality certification gates filter non-compliant Middle Eastern shipments and create competitive moats at Indian ports. |
| Long-term Offtake Contracting | Direct sales channels between CNPC's Xinjiang hubs and inland processing facilities displace spot market exposure. |
| Molten Sulfur Forming Technology | Prilling investments at Dung Quat refinery enable granular output specifications preferred by automated bulk handling systems. |
Research Methodology
Bottom-up fertilizer and chemical manufacturing modeling reconciled against top-down refinery sulfur recovery tracking forms the analytical core of this study. Primary interviews with Claus process engineers, procurement leads at phosphate fertilizer cooperatives, BIS certification auditors, and Middle Eastern export traders combined with secondary validation from customs trade data, MEE emissions disclosure filings, CEA subsidy program directives, and SEC filings from integrated energy conglomerates. Triangulation across supply-side capacity assessments and demand-side consumption modeling ensures dimensional consistency.
Historical trendline analysis of refinery output volumes and fertilizer consumption patterns anchored projection frameworks across the analysis window. Segmentation dimensions modeled include product type granularity, application chemistry requirements, end-user integration depth, and distribution channel structure. CAGRs derived from slope analysis of fitted trendlines adjusted for regulatory enforcement intensity and subsidy program mechanics. Industry-specific forecast inputs incorporate Claus process efficiency curves and phosphate fertilizer substitution elasticity parameters.
Underlying measurement precision varies by segment; direct sales channels with disclosed contract volumes carry tighter precision than distributor network estimates. Forecasts reflect assumptions regarding MEE enforcement continuity and CEA subsidy program stability. Practitioners should monitor regulatory divergence between Chinese emissions mandates and Indian fertilizer mechanics, alongside Middle Eastern sour crude processing volumes, for early signals of supply allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
Calcium Nitrate Market