
 US Industrial Fasteners Market | 2026-2036
US Industrial Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Fasteners Market Insights
Carbon fiber-reinforced polymers is recalibrating product economics across aerospace and automotive fastening applications, displacing traditional steel in weight-critical joints. Illinois Tool Works Inc. leverages its captive polymer compounding capacity to control raw material costs. Stanley Black and Decker, Inc. anchors its position through dense distribution networks spanning industrial supply houses and direct contractor channels. Fastenal Company dominates the vending-machine replenishment model, embedding inventory directly at customer plants.
US industrial fasteners are threaded or non-threaded mechanical devices, typically manufactured from alloy steel with Rockwell hardness ratings between C25 and C39, designed to create clamp loads that secure structural assemblies against shear and tensile forces. Steel material grades still generate the bulk of revenue, though stainless steel commands premium positioning in coastal and chemical-processing environments where ASTM A193 and A194 specifications govern selection. Aerospace end users represent the fastest-growing demand pool, driven by Boeing and Lockheed Martin production ramps that require NAS and MS-specified fasteners with full material traceability. Mechanical fastening technology retains volume leadership, while hybrid systems combining adhesive bonding with threaded elements are capturing margin-rich positions in wind turbine and EV battery tray applications.
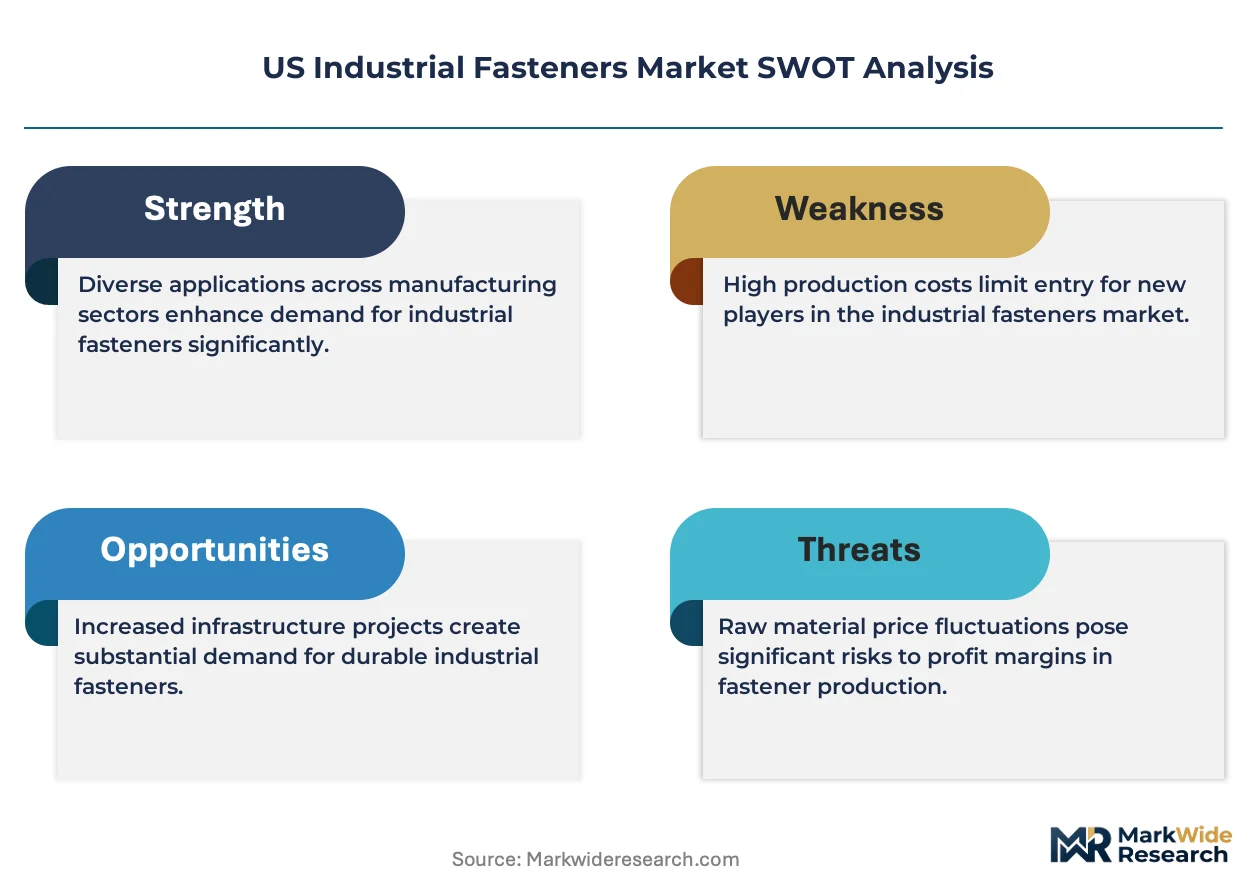
NHTSA crashworthiness protocols and FAA airworthiness directives jointly shape fastener certification requirements, forcing suppliers to maintain dual quality systems for automotive and aerospace compliance. OSHA fall-protection standards in construction drive demand for tamper-resistant structural connections in elevated work platforms. ASTM International and SAE International publish the dimensional and performance benchmarks that govern market access. Stakeholders must monitor how Buy American provisions in federal infrastructure spending redirect sourcing decisions toward domestic melt-and-manufacture supply chains.
Market Dynamics
The US Industrial Fasteners Market pivots on NHTSA crashworthiness mandates that force material upgrades across automotive supply chains, compressing procurement timelines while elevating certification burdens for domestic manufacturers serving Michigan and Ohio assembly corridors.
Growth Catalysts
- EV Platform Buildouts:Electric vehicle battery tray architectures require corrosion-resistant fastening systems with higher clamp-load tolerances, pulling demand through Gulf Coast petrochemical infrastructure expansions.
- FAA Airworthiness Directives:Aerospace fastener specifications with full material traceability are accelerating production ramps at Boeing and Lockheed Martin facilities.
- Buy American Provisions:Federal infrastructure spending redirects sourcing toward domestic melt-and-manufacture supply chains, privileging US-based threading and heat-treatment operations.
Market Restraints
- Alloy Steel Price Volatility:Raw material input costs for Rockwell C25-C39 grade stock fluctuate with scrap metal and energy pricing, compressing margin stability for mid-volume producers.
- Dual Quality System Burden:Suppliers maintaining parallel NHTSA automotive and FAA aerospace compliance face duplicated audit and documentation costs without volume offset.
- Carbon Fiber Substitution:Reinforced polymer joints in weight-critical aerospace applications displace traditional steel fasteners in specified load-bearing connections.
Strategic Opportunities
- Wind Turbine Hybrid Systems:Adhesive-bonded threaded fastening combinations capture margin-rich positions in blade-to-hub connections requiring vibration damping.
- OSHA Fall-Protection Mandates:Construction elevated work platforms drive specification of tamper-resistant structural connections with documented torque verification.
- Vending-Machine Embedded Inventory:Direct plant-floor replenishment models reduce customer working capital requirements while locking out distributor competition.
Industry Challenges
- Metallurgical Talent Scarcity:Heat-treatment and thread-rolling specialization gaps constrain throughput expansion at domestic forges.
- ASTM/SAE Certification Timelines:Dimensional and performance benchmark testing cycles extend new product qualification windows beyond customer procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Fasteners Market |
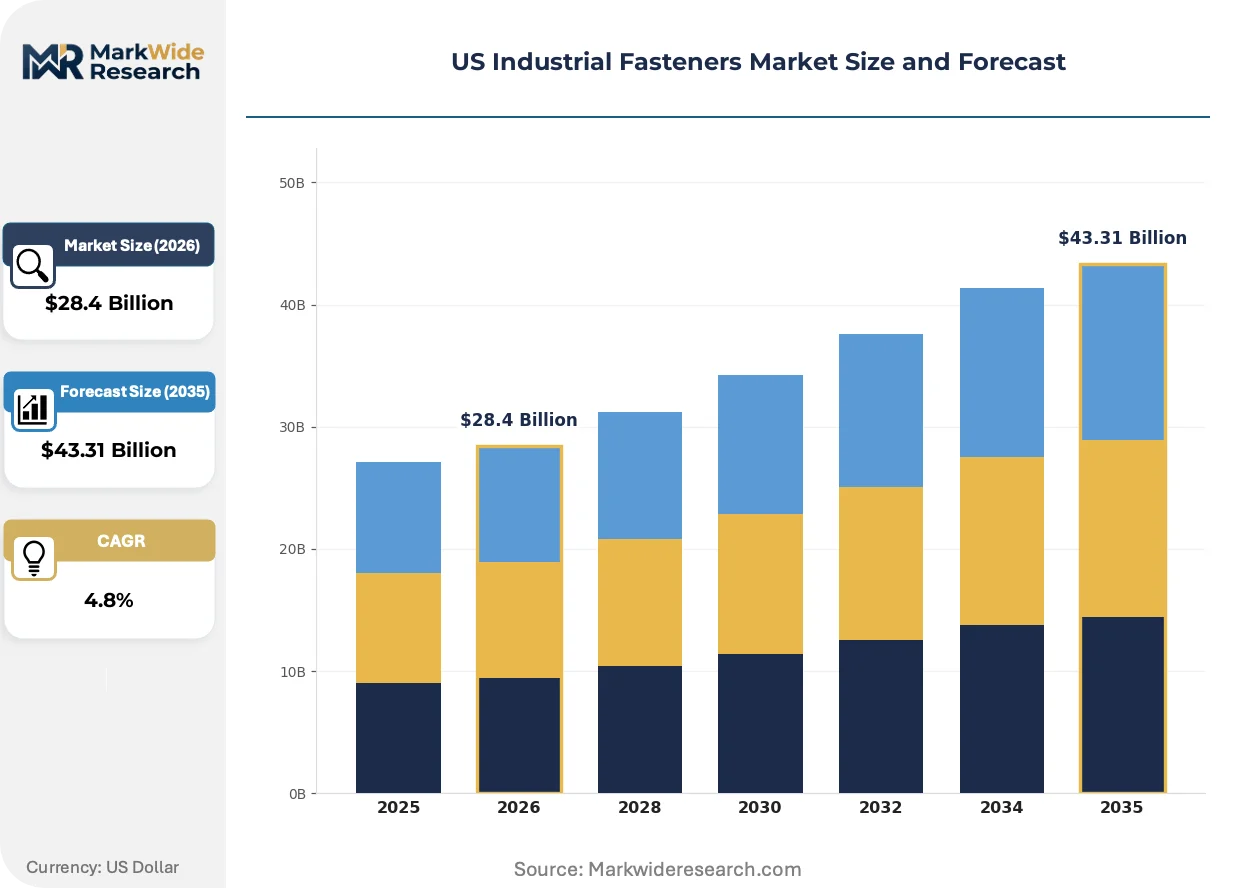
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Screws Material: Steel, Stainless Steel, Aluminum, Plastic End User: Aerospace, Automotive, Construction, Electronics Fastening Technology: Mechanical, Chemical, Magnetic, Hybrid |
| Companies Covered | Illinois Tool Works Inc., Stanley Black and Decker, Inc., Arconic Fastening Systems and Rings, Hilti Corporation, Acument Global Technologies, Inc., MW Industries, Inc., Fastenal Company, ATF, Inc., Birmingham Fastener and Supply, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Fasteners Market Trends and Innovations
Fastener engineering across US manufacturing is fragmenting into application-specific architectures that privilege weight reduction, regulatory traceability, and embedded supply chain proximity over commodity interchangeability.
Additive-manufactured titanium alloy fasteners are modularizing production economics for low-volume aerospace brackets and satellite structural nodes. Boeing's defense division adopts these geometries for non-critical joints where traditional forging die costs prove prohibitive. This technology is modularizing supplier entry barriers, enabling tier-two machine shops to bypass capital-intensive cold-heading equipment.
NHTSA updated crashworthiness standards are forcing alloy grade escalations in automotive chassis and battery enclosure assemblies. Suppliers must now certify batch-level tensile and shear performance under accelerated corrosion cycling. The Detroit Three OEMs are consolidating approved vendor lists to suppliers with captive metallurgical laboratories and in-house salt-spray testing capacity.
Contractor purchasing departments are consolidating supplier relationships around integrated inventory management platforms that synchronize consumption data with automatic replenishment triggers. Industrial supply houses lose share to direct manufacturer programs that embed technical service engineers at customer plants. This concentration is most visible across Texas and Louisiana refinery construction sites where ASTM A193 specification fasteners move through vendor-managed stock programs rather than traditional distribution.
US Industrial Fasteners Market Segmentation
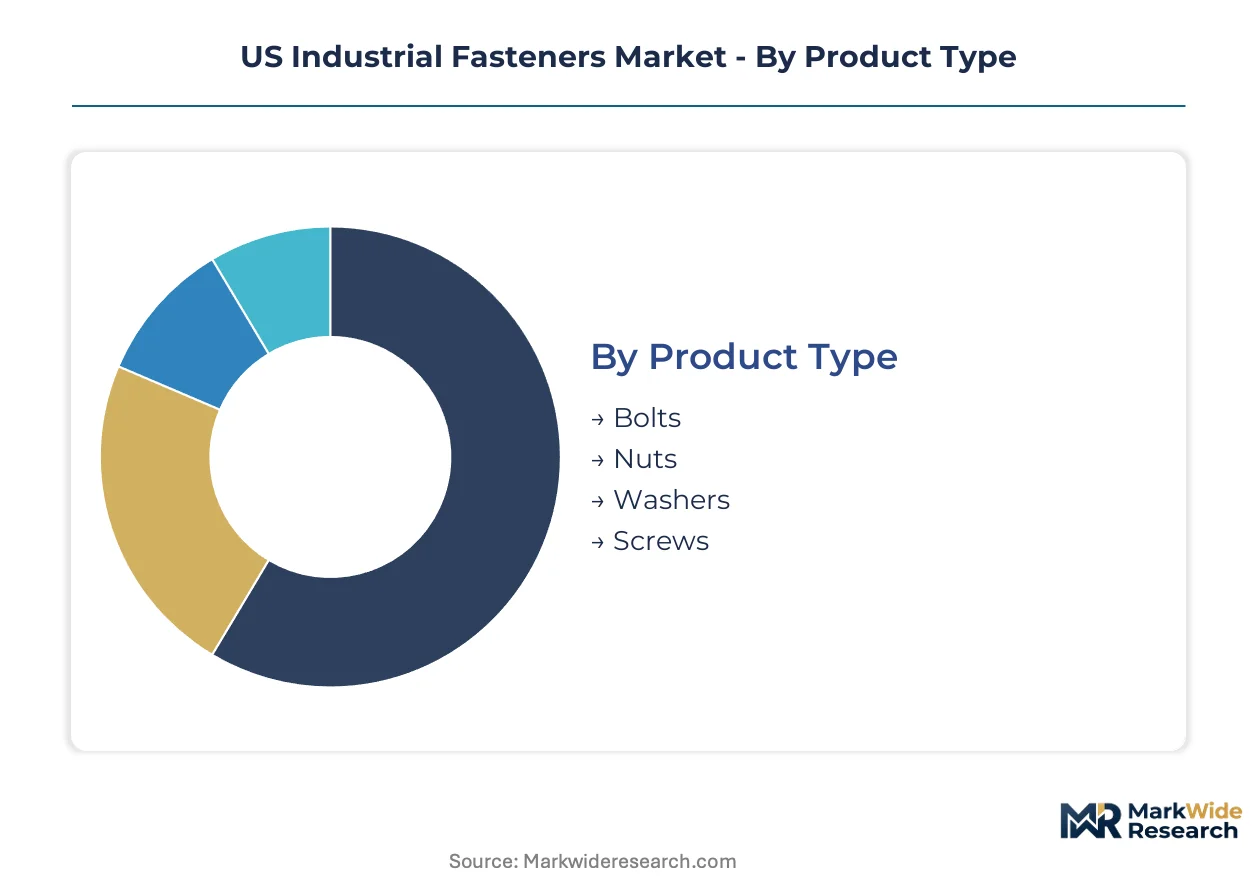
Fastener segmentation in the US market reveals how specification requirements fragment procurement patterns across industries. Material grade and fastening technology choices determine supplier qualification pathways and margin structures.
Product Type:
Volume leadership sits with threaded fasteners for mass-market applications, while premium positioning concentrates in specialized geometries for regulated end-uses.
- Bolts:Hex-head and socket-head configurations dominate structural assemblies with ASTM A193 and A194 specifications governing petrochemical and infrastructure applications. Gulf Coast refinery buildouts pull demand for B7 and B8 grade alloy bolts with full material certification.
- Screws:Self-tapping and thread-forming variants capture high-volume automotive and electronics assembly where installation speed outweighs removability. Michigan and Ohio EV battery tray architectures specify corrosion-resistant drives with documented torque-tension curves.
- Nuts:Hex and heavy-hex patterns pair with matching bolt grades across construction and industrial machinery.
- Washers:Hardened and beveled varieties distribute clamp loads in structural steel connections.
Today's leader: Bolts. Tomorrow's challenger: Screws.
Material:
Cost tier separation runs widest here, with commodity steel at volume base and specialty alloys commanding multiples at the top.
- Steel:Alloy grades with Rockwell C25-C39 hardness ratings generate the bulk of tonnage through cold-heading and hot-forging operations. Scrap metal price volatility compresses margin stability for mid-volume producers serving construction and general industrial channels.
- Stainless Steel:300-series and 400-series grades command premium positioning in coastal environments and chemical-processing facilities where ASTM A193/A194 specifications govern selection. Full traceability requirements from Boeing and Lockheed Martin production ramps accelerate demand for aerospace-grade material lots.
- Aluminum:Lightweight alloys address weight-critical joints in aerospace brackets and satellite structural nodes.
- Plastic:Nylon and composite variants serve electrical insulation and corrosion-immune applications.
Steel maintains volume dominance. Stainless steel gains share fastest in regulated end-uses.
End User:
Application-driven specification divergence creates distinct supplier ecosystems with incompatible certification requirements.
- Automotive:NHTSA crashworthiness mandates force alloy grade escalations in chassis and battery enclosure assemblies. The Detroit Three OEMs consolidate approved vendor lists to suppliers with captive metallurgical laboratories and in-house salt-spray testing capacity.
- Aerospace:NAS and MS-specified fasteners with full material traceability requirements accelerate production ramps at Boeing and Lockheed Martin facilities. FAA airworthiness directives shape quality system investments that tier-two suppliers struggle to replicate.
- Construction:OSHA fall-protection standards drive tamper-resistant structural connections in elevated work platforms with documented torque verification.
- Electronics:Miniaturized precision fasteners serve PCB mounting and enclosure assembly where space constraints dominate design.
Automotive anchors current volume. Aerospace climbs the fastest on specification intensity.
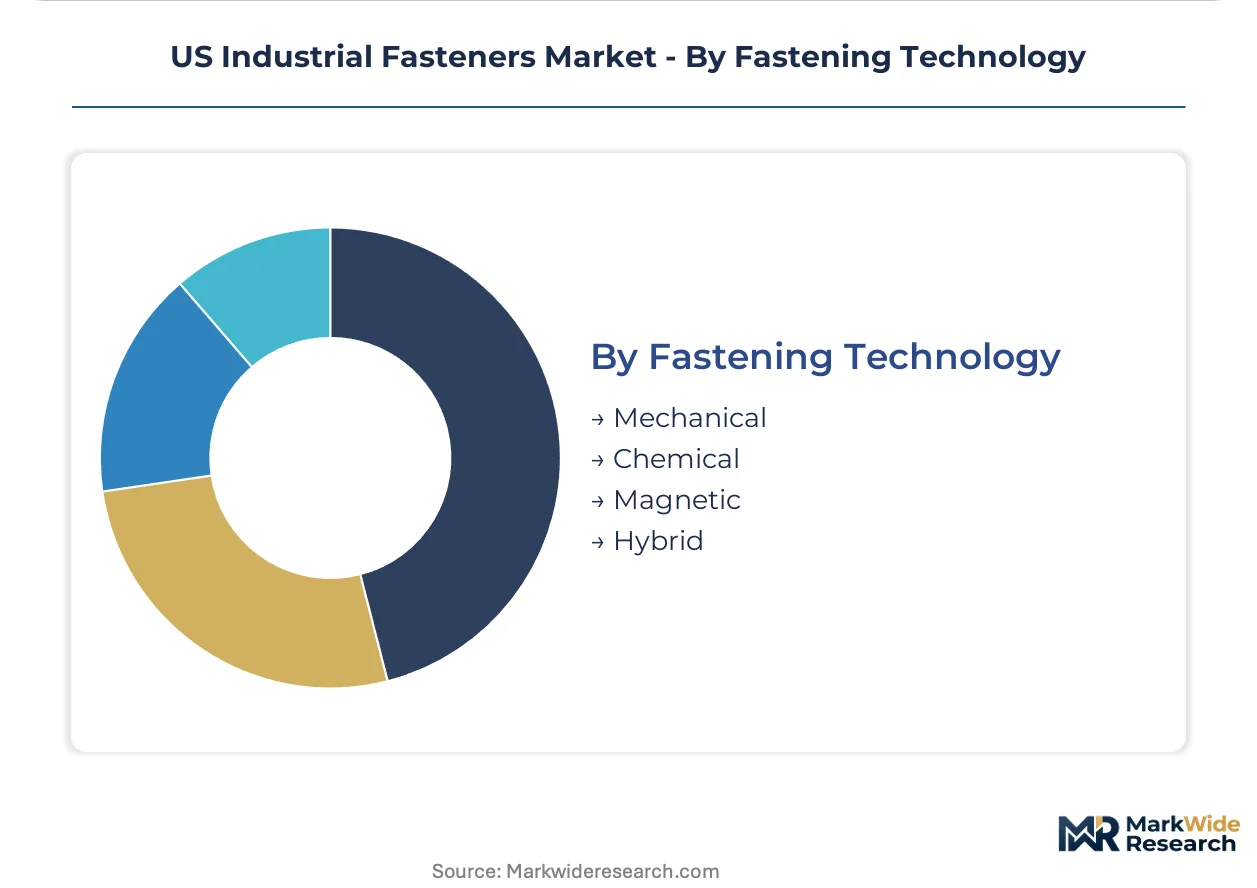
Fastening Technology:
Maturity gradients separate established mechanical methods from emerging hybrid architectures capturing margin-rich positions.
- Mechanical:Threaded and non-threaded devices retain volume leadership across automotive, construction, and general industrial applications. Heat-treatment and thread-rolling specialization gaps at domestic forges constrain throughput expansion for high-strength grades.
- Hybrid:Adhesive-bonded threaded combinations capture margin-rich positions in wind turbine blade-to-hub connections requiring vibration damping and in EV battery trays needing load distribution plus sealing.
- Chemical:Adhesive and epoxy systems serve permanent joints where removability is not required.
- Magnetic:Rare-earth fastening enables rapid attachment in fixture and tooling applications.
Mechanical holds installed base. Hybrid systems show steepest expansion trajectory in renewable energy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes automotive corridor anchors US industrial fastener demand through Michigan and Ohio assembly plant expansions. NHTSA crashworthiness mandates concentrate procurement around suppliers with captive metallurgical testing capacity. Regional output splits between high-volume automotive supply and specialized aerospace fabrication serving Boeing and Lockheed Martin production ramps.
Michigan
Detroit Three OEM battery tray architectures specify corrosion-resistant drives with documented torque-tension curves. NHTSA updated standards force alloy grade escalations in chassis assemblies. Grand Rapids and Lansing forges consolidate approved vendor lists to suppliers with in-house salt-spray testing laboratories.
Ohio
EV platform buildouts pull demand for higher clamp-load tolerance fastening systems across Columbus and Toledo manufacturing zones. Buy American provisions in federal infrastructure spending redirect sourcing toward domestic melt-and-manufacture operations. Cleveland-area heat-treatment specialists face throughput constraints from metallurgical talent scarcity.
Texas
Gulf Coast petrochemical corridor refinery expansions require ASTM A193 specification fasteners with full material certification. OSHA fall-protection standards drive tamper-resistant structural connections in elevated Houston and Beaumont construction platforms. Vendor-managed stock programs displace traditional distribution through direct manufacturer embedded inventory models.
California
Aerospace fastener specifications with NAS and MS traceability requirements accelerate production at Southern California satellite structural node suppliers. FAA airworthiness directives shape quality system investments that tier-two fabricators struggle to replicate. Los Angeles and San Diego precision machining clusters adopt additive-manufactured titanium alloy geometries for low-volume brackets.
Illinois
Chicago-area polymer compounding operations control raw material costs for carbon fiber-reinforced fastener alternatives displacing steel in weight-critical joints. Captive upstream capacity insulates margin stability against alloy steel price volatility. Rockford and Peoria distribution networks span industrial supply houses and direct contractor channels.
US Industrial Fasteners Market Competitive Landscape
Global majors compete with regional champions across distribution density and captive metallurgical capacity. The vendor base separates into integrated manufacturers with in-house heat-treatment, specialized aerospace certification holders, and high-velocity distribution platforms. Three archetypes dominate: vertically integrated alloy processors, NAS-specification aerospace specialists, and vending-machine embedded inventory operators. Consolidation pressures favor M&A among mid-volume forges and strategic partnerships between distributors and plant-floor technical service providers.
Within the integrated manufacturing tier, Illinois Tool Works Inc. and Stanley Black and Decker, Inc. exemplify scale-driven positions through captive polymer compounding and dense distribution networks. Fastenal Company anchors the vending-machine replenishment model, embedding inventory directly at customer plants to reduce working capital requirements. These three represent distinct competitive vectors: backward integration into raw materials, upstream control over distribution channels, and proximity-based inventory lock-in.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Stanley Black and Decker, Inc. |
| Arconic Fastening Systems and Rings |
| Hilti Corporation |
| Acument Global Technologies, Inc. |
| MW Industries, Inc. |
| Fastenal Company |
| ATF, Inc. |
| Birmingham Fastener and Supply, Inc. |
| Others |
Pricing and Supply Chain Analysis
NHTSA crashworthiness mandates gate qualified supply and premium-tier pricing access by forcing alloy grade escalations that only captive metallurgical laboratories can certify. Suppliers without in-house salt-spray testing capacity face exclusion from Detroit Three OEM approved vendor lists, compressing margin recovery for mid-volume forges while rewarding integrated manufacturers with pricing power over certified batches.
Pricing Analysis
Alloy steel scrap and energy input costs pass through to finished fastener pricing on contract reset cycles, with three-tier pricing structure across premium, standard, and economy levels separating aerospace NAS-specification lots from construction-grade commodity tonnage. Price differentiation hinges on certification grade and volume scale, with full material traceability commanding substantial premiums. Pricing pressure stems from carbon fiber-reinforced polymer substitution in weight-critical joints. Construction procurement teams show highest price sensitivity; aerospace buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Michigan and Ohio EV assembly corridors, while industrial supply houses cede share to embedded inventory models. Raw material sourcing draws from domestic scrap recyclers, specialty alloy producers, and captive polymer compounding operations. Heat-treatment and thread-rolling specialization gaps at domestic forges constrain throughput expansion. Tariff exposure on specialty alloy imports threatens margin stability for non-integrated suppliers. Distribution runs through vendor-managed stock programs at Gulf Coast refinery sites and vending-machine replenishment at automotive plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through captive metallurgical capacity that locks in premium-tier pricing and excludes commodity competitors. The shift toward hybrid fastening systems in wind and EV applications creates additional value-capture opportunities for specification holders.
For Market Incumbents: To counter carbon fiber-reinforced polymer displacement in aerospace brackets, deepen backward integration into specialty alloy melt operations and expand captive heat-treatment capacity in Ohio and Michigan. Certification investment in dual NHTSA-FAA quality systems maintains approved vendor status as Detroit Three OEMs consolidate supplier lists.
For New Entrants and Emerging Players: Additive-manufactured titanium alloy geometries for low-volume satellite structural nodes offer technology-first wedge positioning without capital-intensive cold-heading equipment. Target Southern California precision machining clusters with direct technical service embedding at Boeing and Lockheed Martin tier-two suppliers. Go-to-market through hybrid system partnerships with wind turbine blade manufacturers captures margin-rich vibration-damping applications.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap forges with captive metallurgical laboratories because NHTSA and FAA certification timelines create insurmountable barriers for greenfield entrants. Platform consolidation across Great Lakes automotive corridor suppliers captures OEM consolidation tailwinds. Watch for inflection when Buy American infrastructure spending redirects federal project sourcing toward domestic melt-and-manufacture operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Production | Captive melt capacity insulates margin stability against scrap metal price volatility at Rockwell C25-C39 grade suppliers. |
| Dual Certification Investment | Parallel NHTSA automotive and FAA aerospace quality systems maintain approved vendor access across Detroit Three and Boeing supply chains. |
| Hybrid Fastening System Development | Adhesive-bonded threaded combinations capture premium positioning in wind turbine blade-to-hub connections requiring vibration damping. |
| Embedded Inventory Expansion | Vending-machine replenishment models at Michigan and Ohio automotive plants reduce customer working capital while locking out distributor competition. |
| Metallurgical Talent Acquisition | Heat-treatment and thread-rolling specialization recruitment alleviates throughput constraints at domestic forges serving Gulf Coast petrochemical buildouts. |
Research Methodology
Direct dialogue with fastener procurement managers at Detroit Three OEMs, Tier 1 supplier quality engineers, Gulf Coast refinery maintenance directors, aerospace fabrication program managers, and industrial distribution channel heads grounded qualitative assessment. Secondary validation drew from NHTSA crashworthiness protocol filings, FAA airworthiness directive databases, ASTM International specification releases, SEC 10-K disclosures from listed manufacturers, and customs trade data on alloy steel imports. Bottom-up and top-down triangulation cross-checked segment-level demand against macro industrial production indices.
Bottom-up modeling anchored volume projections in platform-specific fastener counts per EV battery tray, wind turbine blade assembly, and aerospace bracket configuration. Segmentation dimensions included material grade tier, fastening technology type, end-use industry, and regional production cluster. CAGRs derived from regression analysis against industrial production indices and OEM build-rate forecasts. Industry-specific inputs incorporated Boeing and Lockheed Martin production ramp schedules, NHTSA rulemaking timelines, and Buy American provision implementation across federal infrastructure awards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to alloy steel price volatility, carbon fiber substitution rates, and metallurgical talent availability. Forecasts reflect documented assumptions regarding OEM vendor consolidation pace and infrastructure spending authorization levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Steel Cord Market
Industrial Materials
Fly Ash Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Cork Material Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Self Locking Nuts Market