
 Mineral Processing Equipment Market | 2026-2036
Mineral Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Processing Equipment Market Outlook
ISO 14001 environmental management certification is reorganizing supplier qualification protocols for major mining procurement departments. Metso Outotec leverages its integrated technology portfolio to dominate large-scale grinding mill installations across Nordic and South American markets. Sandvik competes through advanced automation in its crushing systems, while Multotec anchors its position in dense medium separation and spiral concentrator supply across African platinum and chrome operations.
Mineral processing equipment encompasses the mechanical and electromechanical systems used to reduce ore particle size, liberate valuable minerals from gangue material, and separate concentrates through physical or chemical methods, with typical throughput capacities ranging from 50 to over 10,000 tonnes per day depending on commodity and circuit design. Crushers and milling machines constitute the largest installed base by capital value, though flotation cells command premium pricing due to complex aeration and reagent control requirements that determine recovery rates. Gravity separation technology maintains strong adoption in gold and tin applications where energy costs favor dense medium and jigging circuits over intensive comminution.
Australia's Department of Industry, Science and Resources enforces mine safety and environmental compliance that shapes equipment specification for tailings and water recovery systems, while the EU's REACH regulation and F-Gas Directive constrain reagent chemistry and refrigerant choices in European-sourced processing circuits. The US EPA and Mine Safety and Health Administration impose discharge and dust control standards that filter into equipment design for domestic copper and molybdenum operations. Stakeholders must monitor how carbon border adjustment mechanisms and Scope 3 emissions accounting reshape capital allocation toward electrified and water-efficient processing trains.
Market Dynamics
Automated comminution circuits are compressing operator headcounts while stricter tailings dam safety standards in Chile, Canada, and Australia are forcing wholesale equipment replacements ahead of depreciation schedules.
Growth Catalysts
- Copper electrification demand:Grid infrastructure expansion and EV manufacturing are pulling concentrate throughput requirements upward, particularly in Chilean porphyry operations.
- Lithium extraction scaling:Hard-rock spodumene processing in Western Australia and Quebec is driving capital allocation toward dense medium separation and thermal treatment circuits.
- REACH chemical compliance:The EU's restriction on hazardous reagents is accelerating equipment upgrades to closed-loop flotation systems with automated reagent dosing.
Market Restraints
- Steel input volatility:Grinding mill liner and crusher wear part costs fluctuate with alloy steel pricing, compressing OEM margin buffers on fixed-price contracts.
- Specialized foundry concentration:High-chrome white iron casting capacity clusters in South Africa and India, creating single-source vulnerability for critical wear components.
- Water scarcity physics:Arid-region projects face hard limits on concentrate thickener efficiency, capping recoverable ore grades regardless of capital deployment.
Strategic Opportunities
- Indonesian nickel laterite processing:HPAL circuit demand is outpacing local fabrication capacity, opening slots for modular equipment suppliers with fast-track delivery models.
- EU Green Deal carbon border adjustments:Scope 3 emissions accounting favors electrified crushing and grinding trains over diesel-powered mobile fleets in European-bound concentrate supply chains.
- Sensor-based ore sorting convergence:XRT and EM sensor integration with AI classification is opening upstream pre-concentration applications previously uneconomic for sub-dollar-per-pound commodities.
Industry Challenges
- Automation systems integration:Legacy DCS architectures in brownfield plants resist seamless integration with modern model-predictive control platforms, extending commissioning timelines.
- Metallurgical testwork bottlenecks:Qualified mineralogy laboratories in Saskatchewan and Nevada face 16-week backlogs, delaying feasibility study equipment specifications.
- Competency gaps in comminution modeling:Shortage of engineers trained in JKSimMet and similar simulation tools is stretching OEM application support teams across multiple concurrent projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Processing Equipment Market |
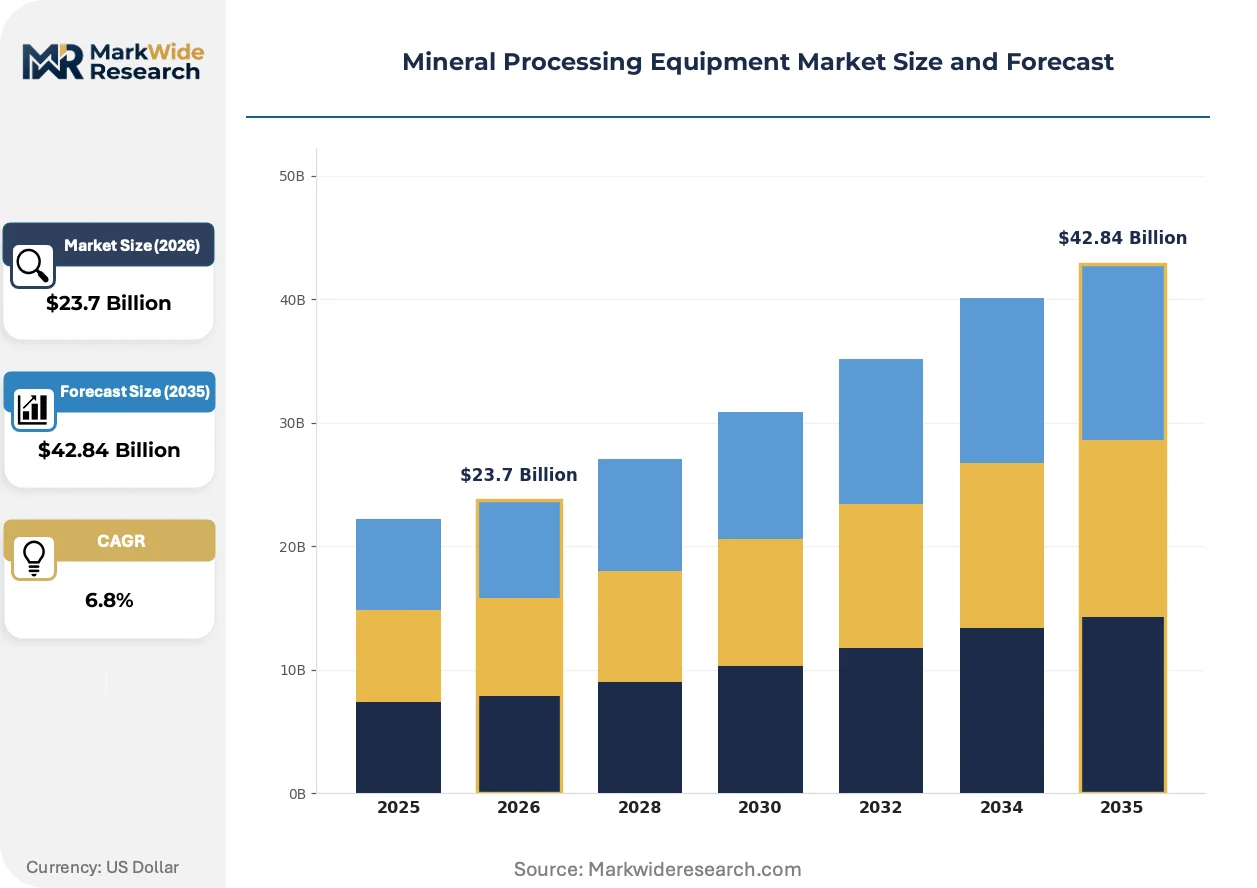
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushers, Milling Machines, Separators, Flotation Cells Technology: Gravity Separation, Magnetic Separation, Hydrocyclones, Agitation Flotation End User: Mining, Construction, Recycling, Environmental Solution: On-premise, Cloud-based, Custom Solutions, Consulting Services |
| Companies Covered | Sandvik, Terex, Metso Outotec, Eriez Manufacturing, Multotec, FLSmidth, Thyssenkrupp, Tenova, Weir Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Processing Equipment Market Strategic Shifts
Digital twin deployment and water-energy nexus optimization are compressing design-to-commission cycles while reconfiguring supplier-customer relationships around performance guarantees rather than equipment delivery.
High-pressure grinding rolls (HPGR) are displacing traditional SAG mills in competent ore applications by reducing energy intensity and steel media consumption. Copper-gold operators in British Columbia and Kazakhstan are retrofitting HPGRs into existing pebble crushing circuits. The technology is displacing incumbent suppliers locked into ball mill maintenance revenue models.
Chile's updated Dam Safety Law and Canada's MAC Tailings Guidelines are mandating independent third-party review of tailings storage facility designs. Equipment vendors must now certify thickeners and filtration systems to explicit seismic and geotechnical performance standards. Australian procurement departments are inserting these certification requirements into tender documents for African and South American projects.
Performance-based service contracts are replacing traditional spare parts agreements, with operators paying per tonne of concentrate produced rather than per component replaced. This compresses supplier margins on low-efficiency equipment while rewarding predictive maintenance algorithms. The shift is most visible in Pilbara iron ore operations where Rio Tinto and BHP have unbundled maintenance from capital procurement.
Mineral Processing Equipment Market Segmentation
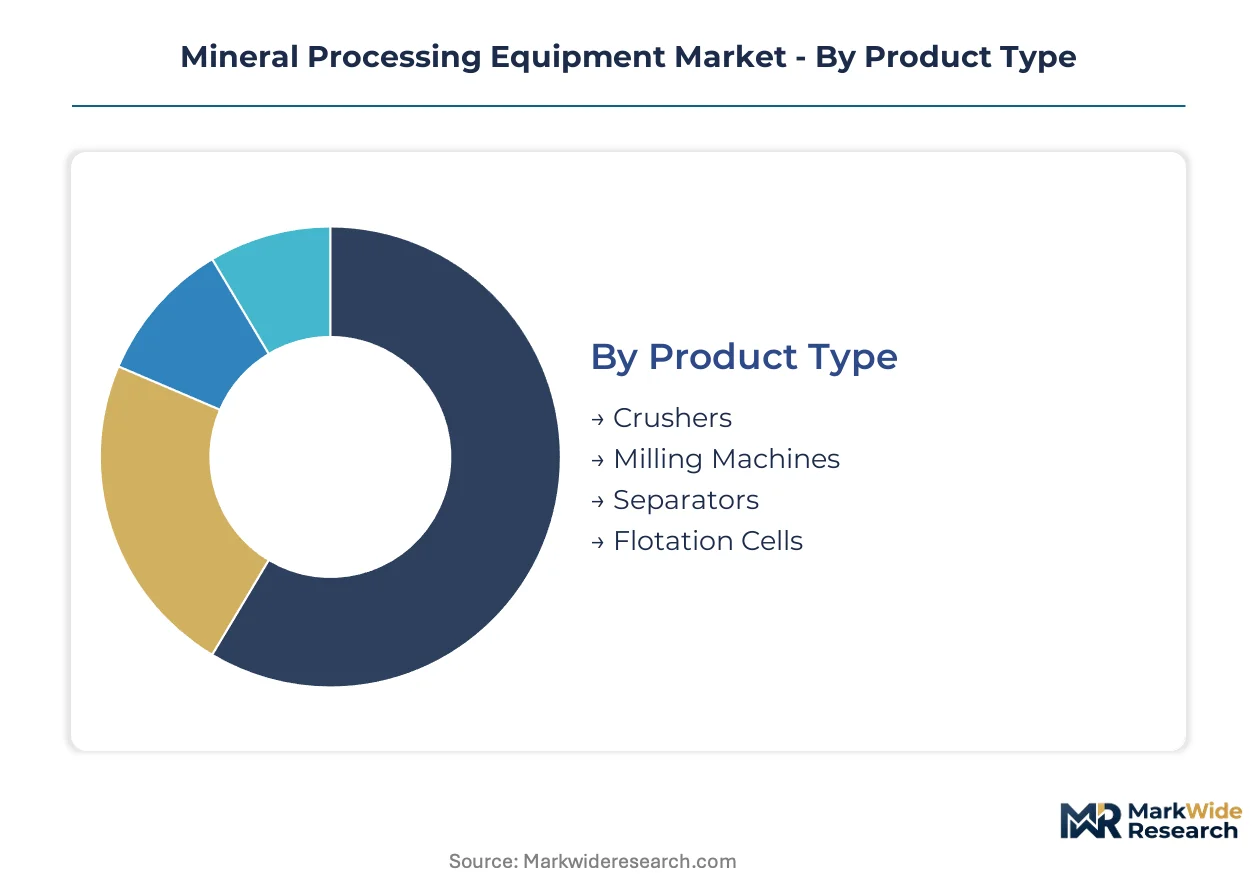
Equipment segmentation in mineral processing reflects divergent capital intensity and regulatory exposure across ore types. Procurement departments weight technology choices against tailings compliance costs and energy efficiency mandates.
Product Type:
EU REACH chemical restrictions and Chile's Dam Safety Law drive differentiation in equipment specification, with filtration and closed-loop systems commanding premium qualification protocols.
- Crushers:Jaw, cone, and gyratory configurations reduce run-of-mine ore to manageable feed sizes for downstream circuits. Australian iron ore operators in the Pilbara are retrofitting automated control systems to meet dust emission limits under the Department of Industry, Science and Resources protocols.
- Milling Machines:SAG mills, ball mills, and stirred media mills liberate valuable minerals through abrasive comminution. High-pressure grinding rolls are displacing traditional SAG configurations in competent ore bodies across British Columbia and Kazakhstan, driven by energy intensity reduction targets.
- Separators:Dense medium, spiral, and jigging systems exploit density differentials for pre-concentration.
- Flotation Cells:Aerated tanks with automated reagent dosing recover fine disseminated sulfides and oxides.
Established volume favors crushers; emerging adoption favors flotation cells with closed-loop reagent recovery.
Technology:
Capital deployment patterns split between energy-intensive comminution and selective pre-concentration methods that reduce downstream load.
- Gravity Separation:Dense medium baths, spirals, and shaking tables exploit specific gravity differentials without chemical reagents. Gold and tin operations in arid regions favor gravity circuits over flotation to minimize water consumption and tailings treatment costs.
- Magnetic Separation:Low-intensity and high-intensity magnetic separators recover ferromagnetic and paramagnetic minerals. Iron ore concentrators in Western Australia and the Mesabi Range deploy wet drum separators at scales exceeding 10,000 tonnes per day.
- Hydrocyclones:Centrifugal classification devices separate particles by size in closed grinding circuits.
- Agitation Flotation:Mechanically agitated cells with forced air injection treat fine-grained sulfide ores.
Gravity separation holds margin stability; agitation flotation gains share fastest in copper-lithium circuits.
End User:
Customer concentration varies by commodity cycle, with mining capital budgets dominating equipment procurement while environmental compliance opens secondary demand channels.
- Mining:Copper, gold, iron ore, and lithium producers commission integrated processing trains from crushing through concentrate dewatering. Chilean porphyry copper operators and Western Australian spodumene miners are expanding comminution capacity to meet battery supply chain offtake agreements.
- Construction:Aggregate producers deploy portable crushing and screening plants for road base and concrete feedstock.
- Recycling:Scrap metal and construction waste processors deploy magnetic and eddy-current separation for material recovery.
- Environmental:Soil remediation and water treatment contractors specify mobile processing units for contaminated site cleanup.
Mining absorbs the dominant equipment volume; environmental applications show steepest expansion trajectory as remediation liabilities mount.
Solution:
Service model differentiation tracks digital maturity and in-house engineering capability across operator tiers.
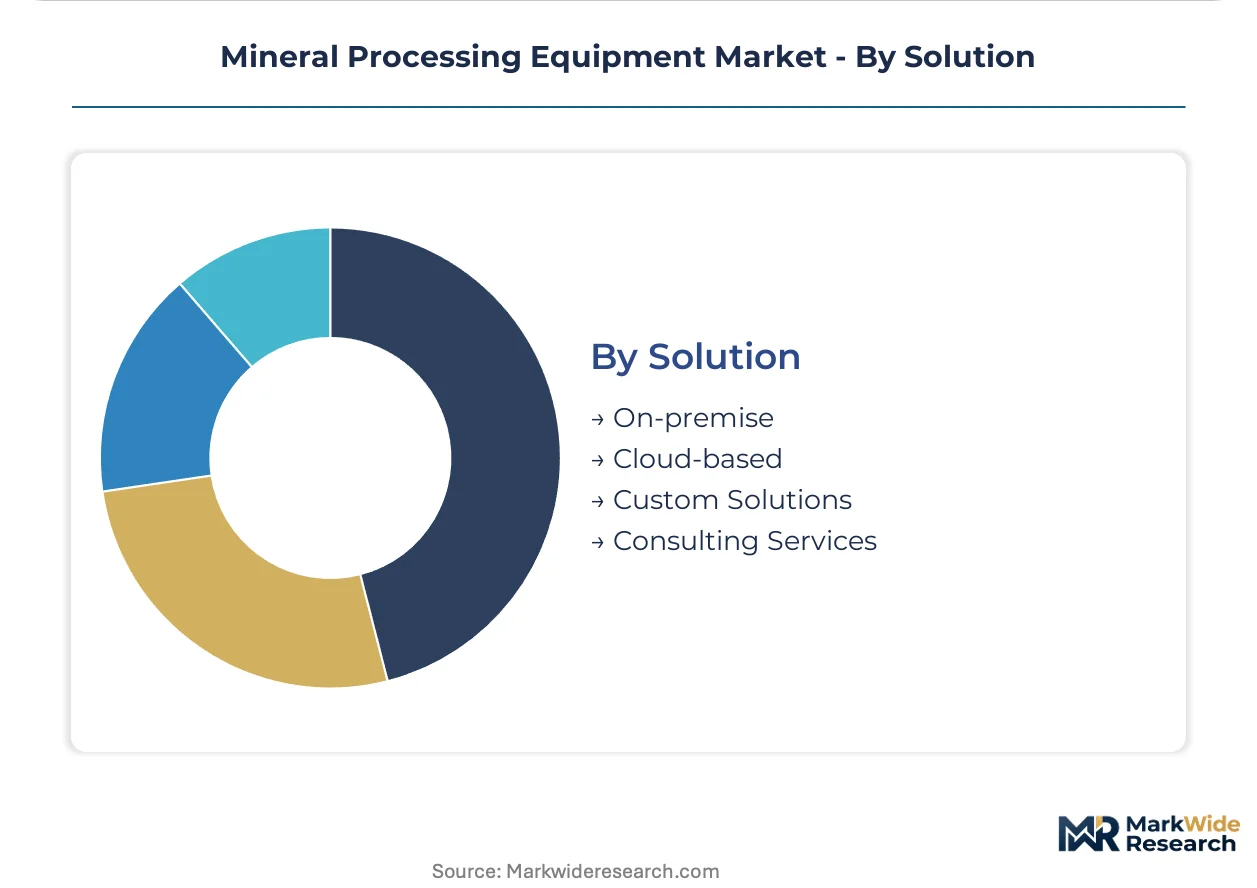
- On-premise:Installed hardware with local control systems dominates brownfield expansions where legacy DCS architectures resist cloud migration. Rio Tinto and BHP in the Pilbara maintain on-premise crushing automation to ensure sub-50ms control loop response.
- Cloud-based:Remote monitoring and model-predictive control platforms aggregate fleet data across multiple sites.
- Custom Solutions:Engineered-to-order equipment trains address ore-specific metallurgical challenges.
- Consulting Services:Process optimization and commissioning support contracts supplement hardware procurement.
On-premise retains share in latency-sensitive comminution; cloud-based solutions climb fastest in filtration and thickening remote monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper electrification and lithium extraction are concentrating capital deployment among mining operators in Australia, Chile, and Canada. Procurement departments in these markets enforce tailings compliance and automation specifications that filter into equipment qualification protocols elsewhere.
Australia
Western Australian spodumene miners and Pilbara iron ore operators are expanding comminution capacity under battery supply chain offtake agreements. The Department of Industry, Science and Resources enforces dust emission limits that shape automated crushing control specifications. Perth-based engineering clusters dominate feasibility study and commissioning support for African and South American projects.
Chile
Porphyry copper operations are retrofitting HPGR circuits to meet concentrate throughput requirements from grid infrastructure and EV manufacturing demand. The updated Dam Safety Law mandates independent third-party review of tailings storage facility designs, forcing thickener and filtration system upgrades. Antofagasta and Santiago procurement offices are inserting seismic certification requirements into tender documents for cross-border projects.
Canada
British Columbia copper-gold operators and Quebec hard-rock lithium projects are driving capital allocation toward dense medium separation and thermal treatment circuits. The MAC Tailings Guidelines require equipment vendors to certify performance to explicit geotechnical standards. Vancouver and Montreal engineering hubs anchor North American metallurgical testwork and simulation modeling capacity.
China
Domestic copper concentrate demand and Indonesian nickel laterite investment are pulling processing equipment procurement toward HPAL circuit fabrication. MIIT and MEE standards constrain reagent chemistry and water recovery system design for both domestic and overseas projects. Zhengzhou and Shenyang manufacturing clusters supply grinding mill liners and crusher wear components across Central Asian and African operations.
South Africa
Platinum and chrome operations in the Bushveld Complex anchor dense medium separation and spiral concentrator demand. The concentration of high-chrome white iron foundry capacity creates single-source vulnerability for critical wear components exported globally. Johannesburg procurement departments coordinate equipment supply across sub-Saharan greenfield and brownfield expansions.
Mineral Processing Equipment Market Competitive Environment
Player mix skews toward integrated technology providers with full comminution-to-concentrate portfolios alongside specialized component fabricators serving regional aftermarket demand. Market structure shows moderate consolidation at the top tier, with a long tail of regional foundries and automation integrators competing on delivery speed and customization. Two strategic archetypes dominate: full-line OEMs bundling grinding mills, crushers, and flotation trains; and niche specialists anchoring specific separation technologies or wear-resistant components. Competitive moves center on performance-based service contracts replacing spare parts agreements, and modular fast-track delivery models for HPAL and remote-site projects.
Among Nordic and South American integrated technology providers, Metso Outotec and Sandvik occupy positions exemplifying the full-line archetype, while Multotec represents the specialized component and separation technology tier. These companies anchor distinct competitive vectors—integrated portfolio breadth versus deep regional aftermarket presence—without overlapping positioning. The distinction between bundled comminution-to-concentrate offerings and focused dense medium or spiral concentrator supply shapes how procurement departments structure tender evaluations across copper, lithium, and iron ore applications.
| Leading Market Players |
|---|
| Sandvik |
| Terex |
| Metso Outotec |
| Eriez Manufacturing |
| Multotec |
| FLSmidth |
| Thyssenkrupp |
| Tenova |
| Weir Group |
| Others |
Value Chain & Pricing Dynamics
Grinding mill foundry capacity utilization above 85% in South Africa and India compresses margin buffers for high-chrome white iron castings, concentrating pricing power among integrated OEMs while forcing smaller fabricators toward alloy steel spot markets. This scale asymmetry elevates cost-plus contract indexation to alloy surcharges as the dominant procurement mechanism across crushing and milling equipment supply.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked alloy steel indexation dominate fixed-price mill and crusher procurement, with premium pricing attaching to ISO 14001-certified suppliers and seismic-performance guarantees under Chile's Dam Safety Law. Price differentiation separates premium-tier integrated comminution trains from standard modular components and economy-grade aftermarket wear parts. Cost compression in standard-tier crushing systems is intensifying because Chinese grinding media exports are undercutting European foundry pricing. Junior miners and African platinum operations exhibit highest price sensitivity; tier-one copper producers in Chile and Australia prioritize performance guarantees over unit cost.
Supply Chain Analysis
Extended lead times for SAG mill girth gears—stretching 26-32 weeks—force operators into speculative inventory positions or premium expedite fees. Supply concentrates in China for grinding mill liners, South Africa for high-chrome white iron castings, and Finland for HPGR roller assemblies. Raw material flows draw from Australian iron ore, Chilean copper concentrate, and Indonesian nickel laterite feedstocks. Single-source vulnerability in South African foundry capacity creates structural risk for critical wear component availability. Distribution runs through OEM direct sales for large integrated trains and regional distributors for aftermarket consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral processing equipment procurement is shifting toward platform-economics logic where interoperability between sensor-based ore sorting, automated comminution, and closed-loop flotation determines supplier stickiness. The convergence of XRT pre-concentration with AI-classified feed control exemplifies this ecosystem inflection.
For Market Incumbents: Secure backward integration into high-chrome white iron foundry capacity to neutralize South African supply concentration risk. Anchor cloud-based predictive maintenance platforms to equipment performance guarantees, displacing pure spare parts revenue models. Defend against modular fast-track entrants by embedding seismic certification and water-recovery compliance into tender specifications that resist disaggregation. For New Entrants and Emerging Players: Differentiate on HPAL circuit modularity for Indonesian nickel laterite projects where local fabrication capacity lags demand. Target environmental remediation contractors with mobile processing units for soil cleanup liabilities. Penetrate through sensor-based ore sorting integration with legacy DCS architectures, offering commissioning support that incumbent OEMs underserve. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized separation technology providers with dense medium and spiral concentrator expertise over full-line grinding mill OEMs locked into maintenance revenue erosion. Long-term viability rests on water-energy nexus optimization capabilities as arid-region project economics tighten. Watch for carbon border adjustment mechanism enforcement in EU concentrate supply chains as the inflection signal for electrified processing train preference.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contract Expansion | Rio Tinto and BHP unbundling maintenance from capital procurement compresses pure equipment margins industry-wide. |
| HPGR Retrofit Acceleration | British Columbia copper-gold operators displace SAG mill incumbents with energy-efficient pebble crushing circuits. |
| Seismic Certification Investment | Chile's Dam Safety Law mandates third-party thickener and filtration review, creating compliance-based differentiation. |
| Sensor-Based Ore Sorting Integration | XRT and EM sensor convergence with AI classification opens upstream pre-concentration for sub-dollar-per-pound commodities. |
| Cloud-Based Remote Monitoring Deployment | Filtration and thickening systems shift toward latency-tolerant cloud architectures, reducing on-premise control costs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers, maintenance directors at Pilbara iron ore and Chilean copper operations, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC filings of listed mining equipment suppliers, Australian Department of Industry compliance disclosures, Chilean Dam Safety Law regulatory texts, and EU REACH restriction annexes. Bottom-up equipment shipment aggregation and top-down mining capital expenditure analysis were triangulated against feasibility study pipeline databases.
Across the analysis window, volume and value projections were developed through segmented modeling by equipment type, technology category, end-use commodity, and solution delivery model. CAGRs were derived from regression against mining capital expenditure cycles, battery supply chain offtake trajectories, and tailings compliance upgrade schedules. Industry-specific forecast inputs incorporated metallurgical testwork backlog durations and qualified simulation engineer availability constraints.
Material uncertainties—steel alloy price volatility, foundry capacity disruptions, and jurisdictional tailings regulation acceleration—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding copper electrification demand persistence and lithium extraction scaling continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Static Mixer Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Injection Molding Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Paint Knife Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Extruders Market
Industrial Materials
Injection Mold Hot Runners Market