
 Gravity Die Casting Market | 2026-2036
Gravity Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Gravity Die Casting Market Foresight
China's foundry belt is reconfiguring gravity die casting supply for electric vehicle platforms. Nemak SAB de CV anchors North American light-metal casting through dedicated automotive powertrain programs. Georg Fischer AG leverages Swiss precision engineering to dominate high-integrity aluminum housing production for European OEMs. Ryobi Limited sustains Japanese competitive position through integrated permanent mold R&D and captive machining capacity.
Gravity die casting employs reusable metal molds into which molten aluminum, magnesium, zinc, or copper alloys pour under gravitational force without external pressure, typically achieving dimensional tolerances of CT6-CT9 and surface finishes suitable for minimal post-processing in structural automotive and aerospace applications. Aluminum alloys occupy the largest product category due to strength-to-weight ratios critical for powertrain and chassis components, while magnesium alloys represent the fastest-growing alloy segment as OEMs pursue mass reduction targets beyond aluminum's capabilities. Automotive parts generate the dominant application volume, though aerospace components command premium pricing through stringent NADCAP and AS9100 certification requirements.
EPA fuel economy standards and EU F-Gas Regulation jointly accelerate ferrous-to-aluminum substitution in powertrain housings, while China's MIIT dual carbon goals enforce foundry energy efficiency benchmarks that favor permanent mold over sand casting processes. ISO 9001 and IATF 16949 quality frameworks govern supplier qualification, effectively filtering market access for uncertified producers. Stakeholders must monitor evolving alloy specifications for solid-state battery thermal management housings and assess captive versus outsourced casting strategies as OEMs reconsider vertical integration boundaries.
Market Dynamics
Automotive OEMs are compressing powertrain weight targets faster than sand casting cycle times permit, forcing permanent mold capacity expansion across supplier tiers. EPA fuel economy mandates and EU CO2 fleet regulations now treat aluminum gravity die castings as compliance infrastructure rather than optional lightweighting.
Growth Catalysts
- EPA Vehicle Efficiency Standards:US automakers must achieve fleet-average targets that aluminum powertrain housings directly enable, pulling demand from ferrous alternatives.
- China MIIT Dual Carbon Goals:Foundry energy efficiency benchmarks favor permanent mold processes over sand casting, concentrating investment in eastern province clusters.
- Solid-state battery thermal management:Next-generation EV platforms require precision-cast aluminum housings with complex internal geometries for liquid cooling circuits.
Market Restraints
- Primary aluminum price volatility:LME aluminum swings compress foundry margins on fixed-price automotive contracts.
- Tooling lead times:Permanent mold fabrication requires 12-16 week cycles, constraining responsiveness to demand spikes.
- High-pressure die casting substitution:Thinner-wall magnesium components from HPDC lines displace gravity die castings in non-structural brackets.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for domestic EV manufacturing create captive casting demand as OEMs establish assembly capacity.
- Aerospace NADCAP certification:AS9100-qualified foundries command premium pricing for structural airframe components with traceability requirements.
- Closed-loop alloy recycling:Integrated remelt facilities reduce primary aluminum dependence and align with EU Green Deal circular economy mandates.
Industry Challenges
- Permanent mold design engineering:Shortage of technicians skilled in gating system optimization for directional solidification limits capacity expansion.
- IATF 16949 audit timelines:New supplier qualification cycles extend 18-24 months, delaying market entry for emerging foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gravity Die Casting Market |
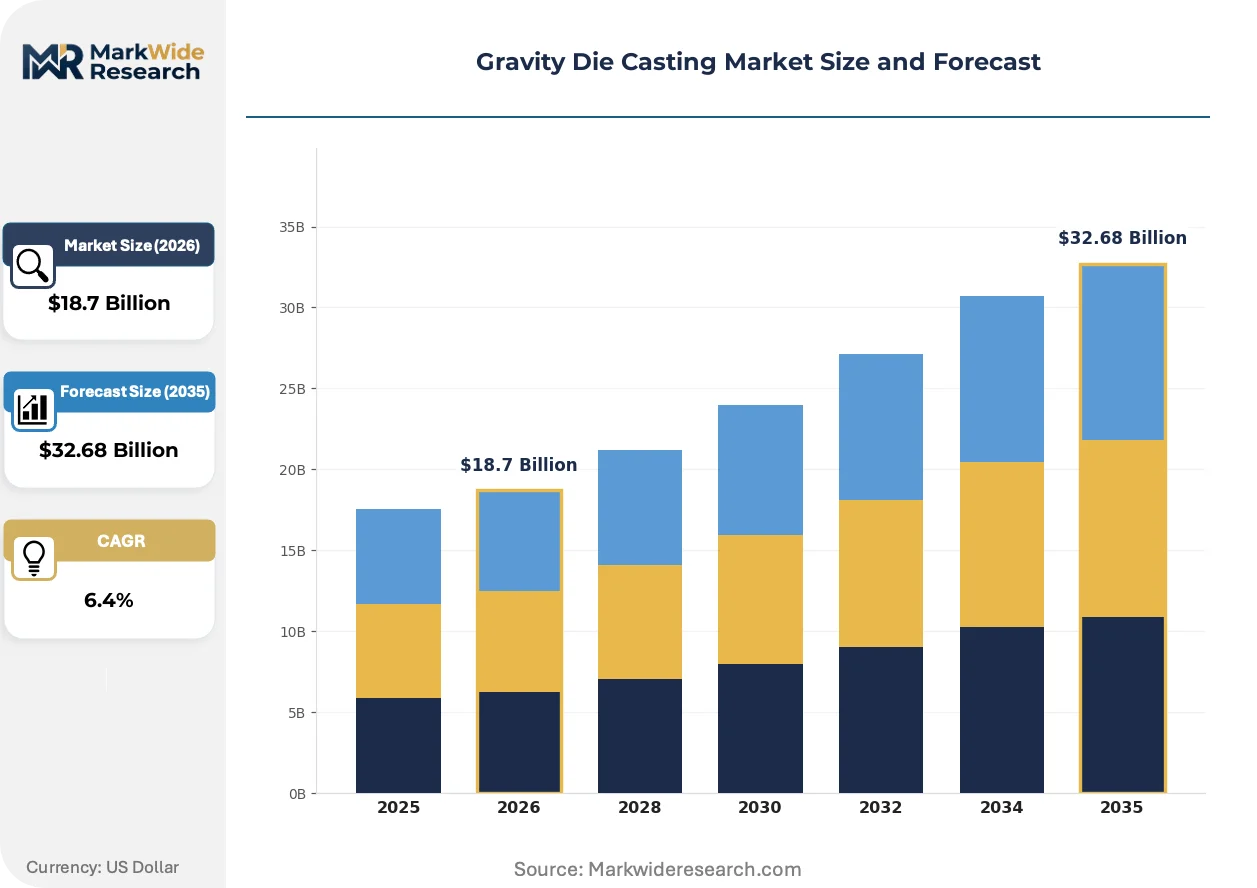
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alloys, Zinc Alloys, Magnesium Alloys, Copper Alloys Application: Aerospace Components, Automotive Parts, Industrial Equipment, Consumer Goods End User: Aerospace Industry, Automotive Manufacturers, Machinery Producers, Electronics Sector Process Type: High Pressure, Low Pressure, Permanent Mold, Sand Casting |
| Companies Covered | Nemak SAB de CV, Georg Fischer AG, Ryobi Limited, Linamar Corporation, Endurance Technologies Ltd, Rockman Industries, Hitachi Metals Ltd, CIE Automotive, Minda Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gravity Die Casting Market Shifts & Advancements
Digital thread integration across casting simulation, mold design, and production monitoring is compressing development cycles. Foundries now embed sensors in permanent molds to capture thermal gradient data for real-time process adjustment.
Simulation software is digitizing gravity die casting development by predicting porosity formation and solidification patterns before mold cutting. Tier-1 automotive suppliers deploy these tools to reduce first-article approval iterations. The technology is digitizing supplier-OEM technical collaboration, compressing program launch timelines.
EU F-Gas Regulation is accelerating ferrous-to-aluminum substitution in powertrain housings by penalizing high-GWP refrigerants and rewarding lightweight thermal management systems. OEMs now specify gravity die castings for battery enclosure bases to offset HVAC system mass. German and French automakers lead this specification shift, integrating casting suppliers earlier into platform architecture decisions.
Buyer consolidation among EV platform specialists is concentrating procurement authority with fewer powertrain engineers managing multi-source casting agreements. Tier-2 foundries face direct technical audits from OEMs rather than Tier-1 intermediaries. This pattern is most pronounced in China's Yangtze River Delta, where NIO, XPeng, and Li Auto maintain resident engineers at key supplier facilities.
Gravity Die Casting Market Segmentation
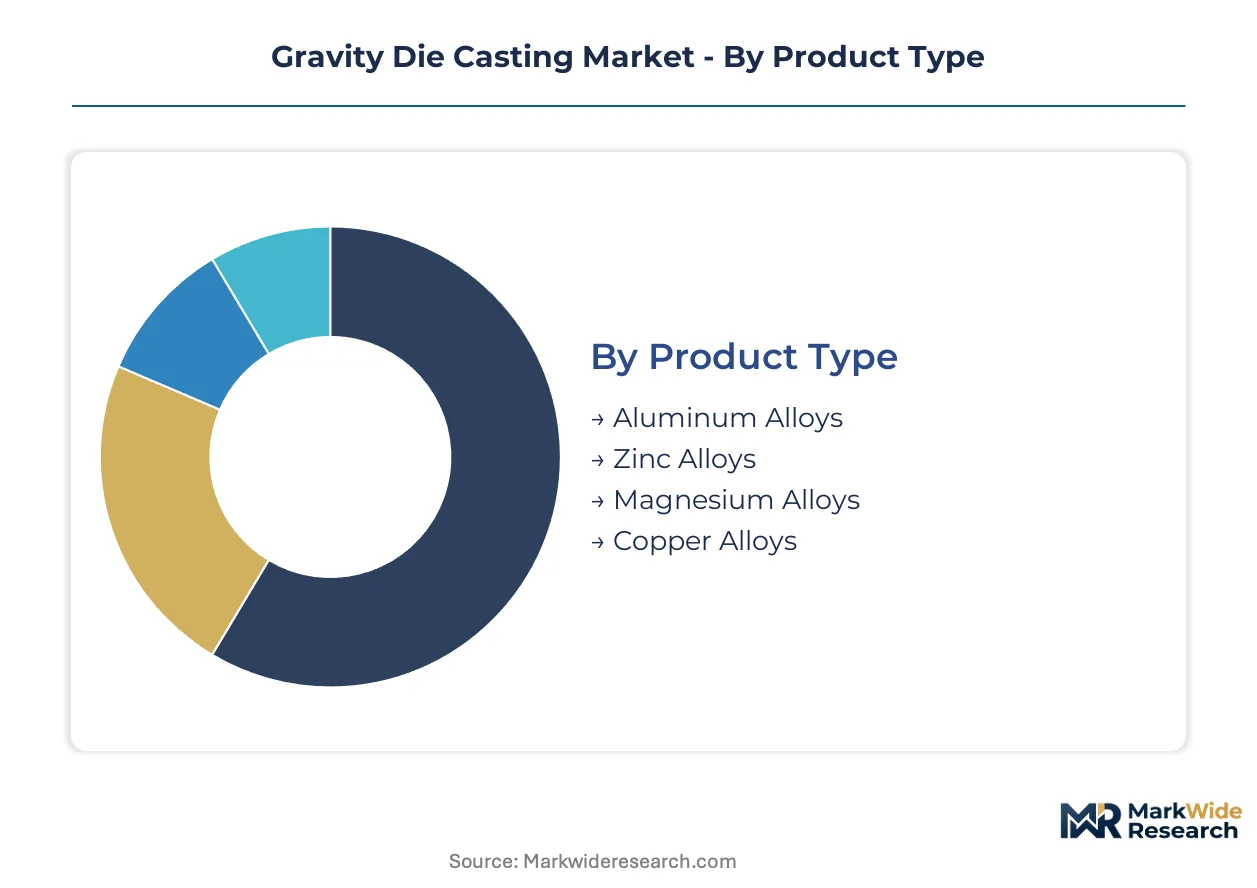
Gravity die casting serves divergent performance requirements across mobility, energy, and industrial sectors. Alloy selection and process configuration determine which end-use specifications suppliers can meet.
Product Type:
Alloy families span density, thermal conductivity, and corrosion resistance requirements from chassis structures to electronic housings.
- Aluminum Alloys:A356 and A380 grades deliver strength-to-weight ratios essential for powertrain housings and suspension knuckles. Demand concentrates in Germany and Japan where automakers specify these alloys for EPA and EU CO2 compliance-driven lightweighting programs.
- Magnesium Alloys:AZ91D and AM60B offer 33% mass reduction versus aluminum for seat frames and steering column brackets. China's eastern province foundries are scaling AZ91D capacity to supply NIO and XPeng EV platforms pursuing maximum range efficiency.
- Zinc Alloys:ZA-8 and ZA-12 provide excellent castability for decorative hardware and small mechanical components.
- Copper Alloys:C83600 and C84400 bronze formulations serve marine fittings and electrical busbar applications requiring conductivity and corrosion resistance.
The dominant share belongs to Aluminum Alloys, while Magnesium Alloys is closing the gap fastest.
Application:
End-use specifications range from aerospace NADCAP traceability to automotive IATF 16949 volume production.
- Automotive Parts:Engine blocks, transmission cases, and battery enclosure bases constitute the highest volume application. German and Japanese OEMs specify these for powertrain weight reduction under tightening EPA and EU fleet efficiency mandates.
- Aerospace Components:Structural brackets and actuator housings require AS9100 certification and full material traceability. Premium pricing reflects NADCAP audit requirements and lot-controlled mechanical testing protocols.
- Industrial Equipment:Pump housings, valve bodies, and compressor components serve fluid handling and pneumatic systems.
- Consumer Goods:Cookware bases, lighting fixtures, and recreational equipment leverage gravity die casting surface finish quality.
Automotive Parts commands the largest volume position, with Aerospace Components generating the highest margin per kilogram cast.
End User:
Customer technical requirements stratify from automotive PPAP submission to aerospace first-article inspection.
- Automotive Manufacturers:Tier-1 suppliers and OEM foundry operations specify permanent mold processes for powertrain structural integrity. China's MIIT dual carbon goals are accelerating foundry consolidation to serve BYD and Gelectric vehicle platforms.
- Aerospace Industry:Boeing, Airbus, and their tiered suppliers demand NADCAP-specialized facilities with thermal processing and non-destructive testing capabilities.
- Machinery Producers:Construction equipment and agricultural machinery OEMs source hydraulic component castings.
- Electronics Sector:Thermal management housings for power electronics and LED modules require precision dimensional control.
Automotive Manufacturers absorb the majority of tonnage, though Electronics Sector procurement is expanding most quickly for EV inverter and charging infrastructure applications.
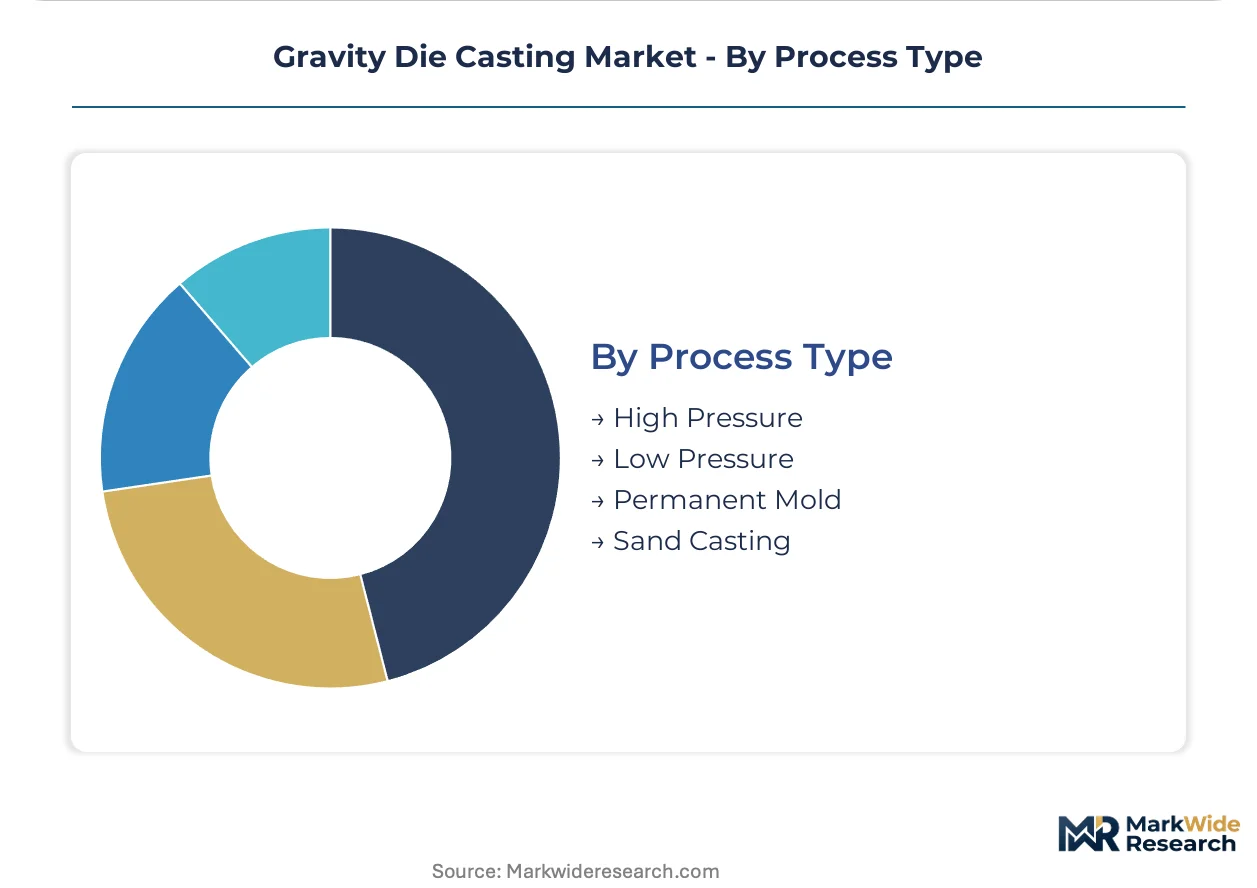
Process Type:
Process selection balances capital intensity, cycle time, and geometric complexity requirements.
- Permanent Mold:Reusable steel or cast iron molds enable medium-to-high volume production with CT6-CT9 dimensional tolerances. China's eastern province clusters favor this process for MIIT energy efficiency compliance versus sand casting alternatives.
- Low Pressure:Controlled metal rise reduces porosity for pressure-tight applications like cylinder heads and wheels. German automakers specify this for high-integrity powertrain components.
- High Pressure:Die casting machines inject molten metal at high velocity for thin-wall magnesium and aluminum components.
- Sand Casting:Expendable pattern processes accommodate prototype quantities and geometrically complex single-piece production.
Permanent Mold holds the installed base advantage, while Low Pressure is gaining specification share for structural EV battery housings requiring leak-tight integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals anchor China's eastern province foundry clusters, where permanent mold capacity expansion outpaces all other geographies. Germany's KBA enforces EU CO2 fleet targets that pull aluminum gravity die casting demand from ferrous alternatives. Japan's METI coordinates automotive lightweighting programs with integrated permanent mold R&D investments.
China
NIO, XPeng, and Li Auto specify precision-cast aluminum housings for solid-state battery thermal management. MIIT energy efficiency benchmarks favor permanent mold processes over sand casting alternatives. Yangtze River Delta foundry clusters in Jiangsu and Zhejiang provinces consolidate capacity to serve domestic EV platform demand.
Germany
BMW, Mercedes-Benz, and Volkswagen compress powertrain weight targets faster than sand casting cycle times permit. EU F-Gas Regulation penalizes high-GWP refrigerants and rewards lightweight thermal management systems. Bavarian and Baden-Württemberg automotive supplier networks expand dedicated permanent mold lines for high-integrity aluminum housing production.
Japan
Toyota and Honda sustain competitive position through integrated permanent mold R&D and captive machining capacity. METI coordinates national lightweighting initiatives with foundry technology roadmaps. Aichi and Shizuoka prefecture manufacturing belts concentrate Ryobi Limited and Hitachi Metals Ltd gravity die casting operations for powertrain structural components.
United States
Ford and General Motors must achieve EPA fleet-average efficiency targets that aluminum powertrain housings directly enable. EPA vehicle efficiency standards treat gravity die castings as compliance infrastructure rather than optional lightweighting. Michigan and Ohio automotive corridors anchor Nemak SAB de CV and Linamar Corporation permanent mold capacity for transmission case production.
India
Maruti Suzuki and Tata Motors localize EV assembly under PLI scheme incentives for domestic manufacturing. BIS quality frameworks govern supplier qualification alongside automotive OEM IATF 16949 requirements. Maharashtra and Gujarat industrial corridors attract Endurance Technologies Ltd and Minda Corporation capacity expansion for two-wheeler and passenger vehicle powertrain castings.
Gravity Die Casting Market Competitive Landscape
Vertically integrated automotive Tier-1s and specialized foundry operators split the market between captive supply security and outsourced flexibility. Consolidation concentrates procurement authority with fewer powertrain engineers managing multi-source agreements. Swiss precision engineering specialists and Japanese integrated RD-manufacturing groups represent distinct strategic archetypes. Capacity expansion and closed-loop alloy recycling constitute the dominant competitive moves across supplier tiers.
Within the integrated automotive Tier-1 tier, Nemak SAB de CV and Georg Fischer AG exemplify geographic anchoring strategies, with the former representing North American light-metal casting concentration and the latter occupying high-integrity European supply positions. Ryobi Limited sits within the Japanese integrated manufacturing archetype. These three entities demonstrate how regional automotive production gravity shapes competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Nemak SAB de CV |
| Georg Fischer AG |
| Ryobi Limited |
| Linamar Corporation |
| Endurance Technologies Ltd |
| Rockman Industries |
| Hitachi Metals Ltd |
| CIE Automotive |
| Minda Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Jiangsu and Zhejiang foundry clusters is compressing spot pricing for A356 aluminum housings while tightening contract margins for Tier-1 suppliers serving German and Japanese OEMs. This utilization gap between eastern province exporters and captive European producers creates divergent pricing power dynamics across supplier tiers.
Pricing Analysis
Contract pricing for automotive aluminum castings spreads 15-25% between Yangtze River Delta export foundries and Bavarian high-integrity specialists serving BMW and Mercedes-Benz. Three-tier pricing structure across NADCAP-certified aerospace, IATF 16949 automotive, and uncertified industrial tiers reflects quality-grade differentiation and audit-burden recovery. Pricing pressure stems from LME aluminum volatility on fixed-price OEM contracts stretching 36-48 months. Chinese EV platform specialists exhibit highest price sensitivity, while aerospace Tier-1s prioritize lot-traceability over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced permanent mold simulation software limit technology transfer to emerging foundries in India and Southeast Asia. Primary aluminum supply concentrates in China, Russia, and the Gulf states, while specialty magnesium feeds from Shanxi and Ningxia provinces. Tooling steel and copper alloy dependencies create single-source vulnerability for precision mold fabrication. Distribution runs through Tier-1 automotive supplier networks with direct OEM technical audits replacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity die casting is shifting toward a service-attach model where mold lifecycle management and real-time process monitoring subscriptions expand faster than per-unit casting revenue. Recurring revenue from embedded thermal sensors and predictive maintenance algorithms is displacing pure tonnage-based pricing.
For Market Incumbents: Insulate margin position through captive recycling facilities that reduce LME aluminum exposure and lock in alloy specifications for solid-state battery thermal management programs. High-pressure die casting substitution for magnesium brackets threatens structural automotive volume; defend through IATF 16949 certification moats and resident engineer placements at NIO and XPeng facilities.
For New Entrants and Emerging Players: Build out aerospace NADCAP-qualified capacity in India and Southeast Asia where AS9100 audit backlogs create supply gaps for Boeing and Airbus tiered suppliers. India's PLI scheme for domestic EV manufacturing offers the most penetrable entry point; pursue direct technical partnerships with Maruti Suzuki and Tata Motors platform engineers rather than Tier-1 intermediaries.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundries with integrated machining and closed-loop remelt operations serving multi-year automotive platform contracts. Long-term viability hinges on exposure to EV thermal management and aerospace structural demand rather than legacy internal combustion powertrain volume. Watch for IATF 16949 certification completion timelines as inflection signals for supplier qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Alloy Recycling | Reduces primary aluminum dependence and aligns with EU Green Deal circular economy mandates. |
| NADCAP Certification Investment | Unlocks premium pricing for Boeing and Airbus structural components with full material traceability. |
| Digital Thread Integration | Compresses first-article approval cycles through real-time thermal gradient monitoring in permanent molds. |
| Resident Engineer Placement | Deepens OEM technical collaboration as NIO and XPeng bypass Tier-1 procurement intermediaries. |
| Low-Pressure Process Expansion | Captures EV battery housing demand requiring leak-tight integrity for liquid cooling circuits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and MIIT energy efficiency disclosures to establish baseline supply and demand parameters. Interviews with foundry operations managers, Tier-1 automotive procurement leads, OEM platform engineers, and aerospace quality auditors supplied forward-looking contract and specification intelligence. Bottom-up capacity tallies across China's eastern province clusters were triangulated against top-down automotive production forecasts.
Forecast inputs span alloy family substitution rates, EPA and EU fleet efficiency mandate trajectories, and EV platform thermal management content per vehicle. Segmentation dimensions include propulsion architecture, certification tier, and regional production cluster. CAGRs were derived from fitted trend analysis across historical foundry output and projected OEM lightweighting targets, with MIIT dual carbon compliance timelines and solid-state battery commercialization curves as key demand shapers.
Stress conditions across LME aluminum price bands, permanent mold tooling lead times, and IATF 16949 audit queue lengths were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EV adoption pacing and aerospace build rates. Material shifts in EPA vehicle efficiency standard stringency or EU F-Gas Regulation enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Tooling Board Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Global Melamine Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Tablet Press Tooling Market