
 Powder Processing Service Market | 2026-2036
Powder Processing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Processing Service Market Insights
A capital-intensity divergence between integrated equipment manufacturers and independent toll processors is bifurcating competitive dynamics across the powder processing service landscape. Hosokawa Micron Corporation leverages its captive milling technology portfolio to anchor premium service tiers in pharmaceutical and fine chemical applications. Charles Ross and Son Company specializes in batch mixing and blending systems, occupying a defensible niche among mid-scale contract manufacturers. Syntegon Technology GmbH extends its packaging and processing integration expertise to control end-to-end powder handling workflows for food and nutraceutical clients.
Powder processing service encompasses mechanical and thermal operations that reduce, blend, classify, or agglomerate particulate solids to specified particle size distributions, typically ranging from nanometers to several millimeters depending on end-use requirements. These services transform raw bulk materials into functional intermediates with controlled flow properties, density, and surface characteristics essential for downstream tableting, sintering, or formulation processes. Milling and granulation services command the largest revenue share due to their ubiquity across pharmaceutical active ingredient preparation and specialty chemical production. Jet milling and cryogenic milling technologies are gaining traction in electronic materials and temperature-sensitive pharmaceutical applications where narrow particle size distributions determine product performance. Mixing and coating services concentrate margin pools in cosmetic and nutraceutical segments where brand owners outsource complex multi-component formulations to avoid capital deployment.
Regulatory frameworks including FDA current good manufacturing practice standards, REACH substance registration requirements, and ISO 13485 quality management systems for medical devices shape operational compliance burdens and customer qualification timelines across the powder processing service sector. EPA air quality standards for particulate emissions further constrain facility siting and equipment selection for dry processing operations in the United States. Stakeholders must monitor evolving pharmacopeial standards for elemental impurities and particle morphology characterization as specification tightening accelerates qualification costs and favors processors with advanced analytical capabilities.
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch cycle times and forcing toll processors to retool legacy equipment toward real-time release testing capabilities.
Growth Catalysts
- API Outsourcing Surge:Pharmaceutical sponsors in Germany and Switzerland are transferring powder processing volumes to contract manufacturers to free capital for biologics R&D.
- REACH Registration Deadlines:ECHA substance evaluation timelines are accelerating demand for certified toll processors with pre-validated documentation packages.
- Jet Milling Adoption:Electronic materials producers in Japan are contracting specialized micronization services for thermal interface materials requiring sub-10-micron particle distributions.
Market Restraints
- Energy Cost Volatility:Natural gas price swings in European Union member states are eroding margins for thermal drying and spray granulation operations.
- Equipment Lead Times:German and Italian precision milling equipment manufacturers face 18-month backlogs, constraining capacity expansion for mid-scale toll processors.
- Substitute Processes:Solution-based manufacturing routes for active pharmaceutical ingredients are displacing solid-state powder processing in certain synthetic pathways.
Strategic Opportunities
- Cell Therapy Excipients:Cryogenic milling capacity for lipid nanoparticle and cell culture media components remains underdeveloped in North American toll processing infrastructure.
- India PLI Scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing are attracting powder processing investment toward Gujarat and Telangana clusters.
- Continuous Direct Compression:Integration of real-time particle size analyzers with roller compaction lines enables pharmaceutical clients to bypass traditional batch granulation steps entirely.
Industry Challenges
- Qualified Personnel Scarcity:Process engineers with combined expertise in PAT tools and powder rheology command premium compensation and extended recruitment cycles.
- Validation Protocol Burden:FDA process validation guidance revisions require three consecutive commercial-scale batches, extending qualification timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Processing Service Market |
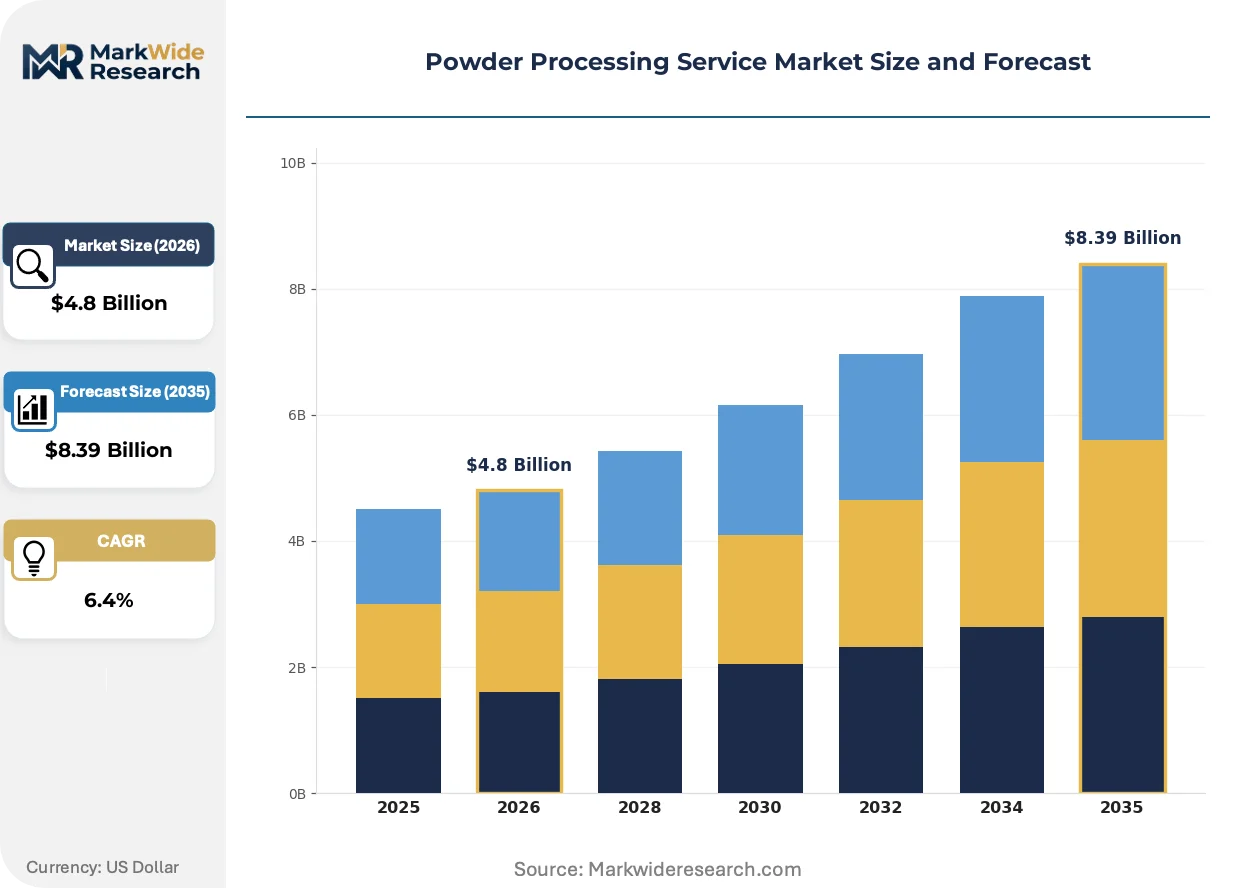
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Granulation, Milling, Mixing, Sieving, Coating, Agglomeration Application: Pharmaceuticals, Food Ingredients, Chemicals, Cosmetics, Ceramics, Additives End User Industry: Contract Manufacturers, Specialty Chemical Producers, Nutraceutical Firms, Personal Care Brands, Electronic Materials Suppliers, Aerospace Fabricators Technology: Dry Powder Processing, Wet Granulation, Fluid Bed, High Shear Mixing, Jet Milling, Cryogenic Milling |
| Companies Covered | Hosokawa Micron Corporation, Charles Ross and Son Company, Syntegon Technology GmbH, Bepex International LLC, Ongsun Powder Processing Equipment Co., Ltd, Hänsel Processing GmbH, Powder Process Solutions, British Rema, Guilin Hongcheng Mining Equipment Manufacture Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Processing Service Market Trends and Innovations
Digital twin implementations and advanced process analytical technology are converging to enable predictive control of particle attributes, reducing offline testing burden.
Continuous fluid bed granulation systems with integrated online moisture and particle size sensing are displacing traditional batch fluid bed operations in oral solid dosage manufacturing. Mid-scale pharmaceutical contract manufacturers in Ireland and Denmark are piloting these lines to support real-time release ambitions. The technology is displacing conventional end-point testing workflows and compressing batch release cycles from weeks to hours.
EMA's revised Annex 1 sterile manufacturing guidelines are extending contamination control requirements into powder handling areas previously exempt from Grade A/B classification. Toll processors serving the European Union market must now install isolator technology or restricted access barrier systems for certain potent compound operations. High-potency active pharmaceutical ingredient manufacturers in the Netherlands and Belgium are prioritizing capital allocation toward containment upgrades ahead of 2025 inspection cycles.
Performance-based service agreements are replacing conventional toll fee structures in pharmaceutical supply relationships. Brand owners now tie processor compensation to achieved particle size distribution targets and batch yield rates rather than input kilograms processed. This model is most visible among mid-sized biotechnology sponsors in Massachusetts and North Carolina seeking to align processor incentives with downstream tableting success rates.
Powder Processing Service Market Segmentation
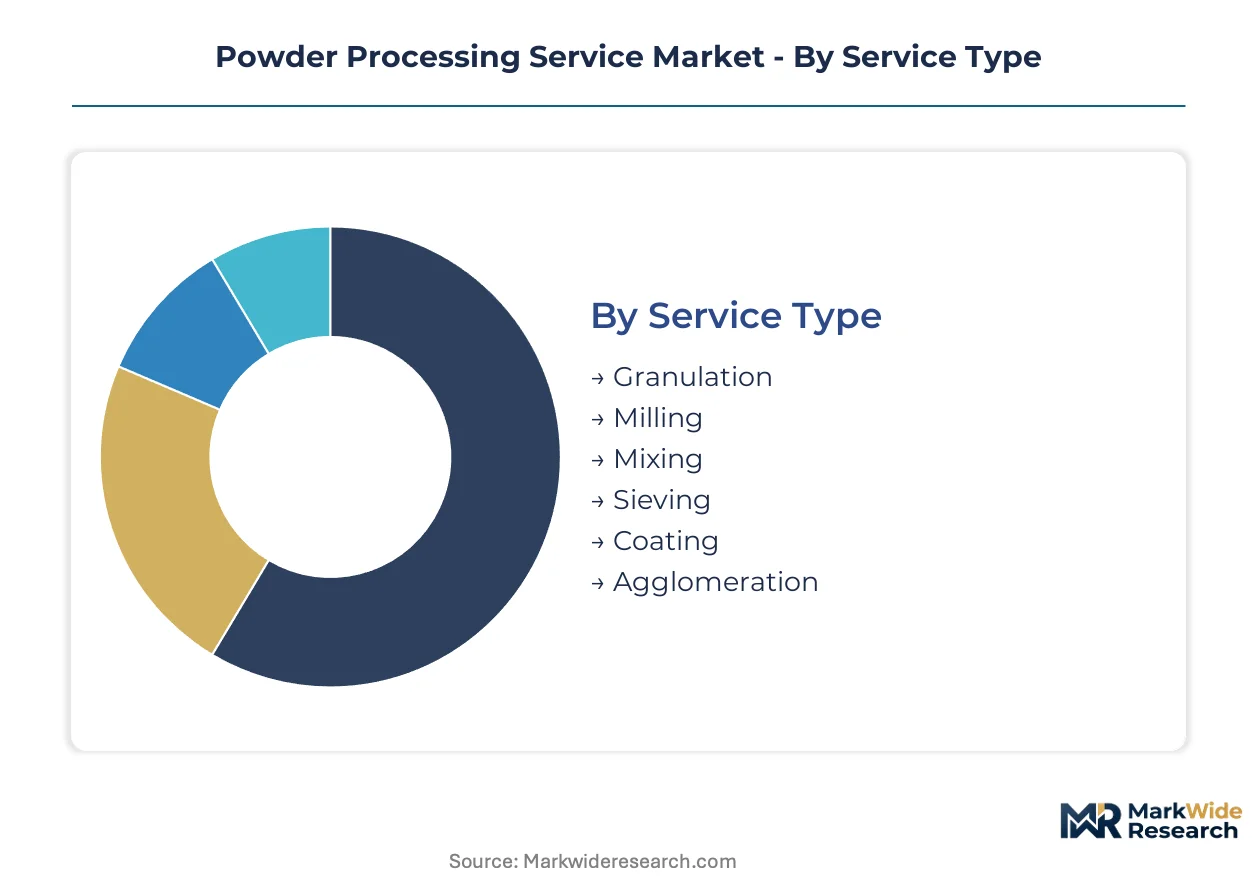
Powder processing service providers differentiate capabilities across equipment modalities, regulatory compliance tiers, and batch-scale thresholds. Segmentation clarity enables pharmaceutical sponsors to match outsourcing decisions with specific particle engineering requirements.
Service Type:
Solution-based API synthesis routes threaten granulation and agglomeration services most directly, while precision milling retains defensive positioning against substitute processes.
- Milling:Mechanical comminution reduces particle size through impact, shear, or attrition mechanisms to achieve specified distributions for downstream tableting or dispersion. Jet milling capacity concentrates in Germany and Switzerland where electronic materials producers contract sub-10-micron thermal interface material processing. REACH documentation packages and FDA process validation requirements extend customer qualification timelines for new milling relationships.
- Granulation:Wet and dry agglomeration transforms fine powders into free-flowing granules with improved compression characteristics. Continuous fluid bed granulation with integrated PAT sensing is displacing batch operations among Irish and Danish contract manufacturers serving oral solid dosage sponsors. EMA Annex 1 sterile manufacturing guidelines now extend containment requirements into previously exempt powder handling areas.
- Mixing:Homogeneous blending of multiple powder components with controlled shear intensity and residence time distribution.
- Sieving:Particle size classification through mechanical screening to remove oversize material or achieve narrow cut points.
- Coating:Functional film application onto particle surfaces for taste masking, moisture protection, or modified release profiles.
- Agglomeration:Size enlargement through compaction, sintering, or binding to improve flow and reduce dusting.
Milling retains volume leadership; continuous granulation holds the steepest expansion curve.
Application:
Margin concentration follows regulatory burden intensity, with pharmaceutical applications commanding premium pricing tiers against commodity chemical processing.
- Pharmaceuticals:Active pharmaceutical ingredient micronization, excipient preparation, and intermediate granulation for oral solid dosage forms. Sponsors in Massachusetts and North Carolina are adopting performance-based service agreements tying processor compensation to achieved particle size targets rather than input kilograms.
- Food Ingredients:Particle engineering for texture modification, solubility enhancement, and controlled release of flavors or nutrients. Nutraceutical brand owners outsource complex multi-component formulations to avoid capital deployment in mixing and coating infrastructure.
- Chemicals:Specialty chemical toll processing for agrochemical intermediates and industrial catalyst precursors.
- Cosmetics:Pigment dispersion and powder foundation milling with tight color consistency specifications.
- Ceramics:Raw material preparation for sintered components with controlled density and surface characteristics.
- Additives:Functional powder processing for lubricants, plastics compounding, and coating formulations.
Pharmaceuticals anchor revenue concentration; food ingredients are climbing the fastest.
End User Industry:
Procurement patterns diverge between capital-constrained biotechnology sponsors seeking flexible capacity and integrated chemical majors optimizing internal asset utilization.
- Contract Manufacturers:Pharmaceutical CDMOs serving sponsor companies with integrated powder-to-tablet capabilities. Mid-scale processors face 18-month equipment backlogs from German and Italian precision milling suppliers, constraining expansion timelines.
- Specialty Chemical Producers:Toll processing relationships for batch-scale agrochemical and fine chemical intermediates. Natural gas price volatility in EU member states erodes margins for thermal drying operations.
- Nutraceutical Firms:Outsourced blending and coating for dietary supplement powders and functional food ingredients.
- Personal Care Brands:Contract micronization and dispersion services for cosmetic powder formulations.
- Electronic Materials Suppliers:Japanese producers contracting jet milling for thermal interface materials requiring narrow sub-10-micron distributions.
- Aerospace Fabricators:Powder metallurgy feedstock preparation for additive manufacturing and hot isostatic pressing applications.
Contract manufacturers retain volume leadership; electronic materials suppliers hold the steepest expansion curve.
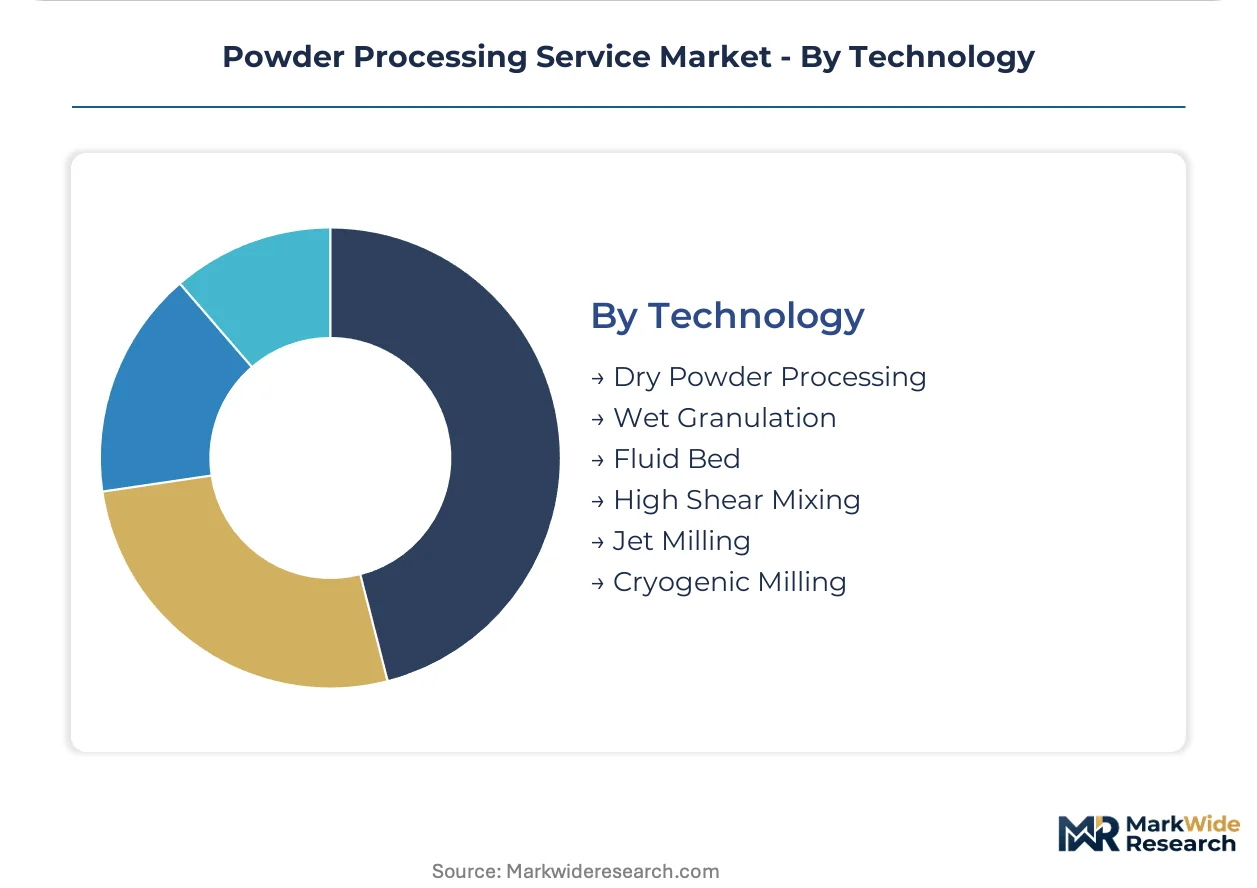
Technology:
Capital intensity stratifies competitive positioning between integrated equipment manufacturers with captive technology portfolios and independent toll processors leasing standardized units.
- Jet Milling:High-velocity particle-on-particle impact achieves sub-10-micron distributions without contamination from grinding media. Electronic materials applications in Japan drive capacity expansion for thermal interface material production.
- Cryogenic Milling:Liquid nitrogen or carbon dioxide cooling enables size reduction of temperature-sensitive or elastic materials. North American infrastructure for lipid nanoparticle and cell culture media excipients remains underdeveloped relative to demand from cell therapy developers.
- Dry Powder Processing:Mechanical size reduction and classification without liquid phase introduction.
- Wet Granulation:Binder addition and liquid-phase agglomeration for improved compressibility.
- Fluid Bed:Air-suspension processing for drying, granulation, and coating with integrated online sensing.
- High Shear Mixing:Intense mechanical energy input for rapid wet massing and granule densification.
Dry powder processing retains volume leadership; cryogenic milling holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss toll processing clusters where REACH documentation and FDA validation capabilities command 30-40% premiums over Southern European competitors. North American processors face compressed margins from energy cost volatility and qualified personnel scarcity.
Germany
Specialized toll processors in the Rhine-Ruhr and Bavarian chemical clusters serve pharmaceutical and fine chemical sponsors with integrated jet milling and containment infrastructure. ECHA substance evaluation timelines accelerate demand for pre-validated documentation packages. Frankfurt and Hamburg harbor zones concentrate import-export logistics for temperature-sensitive API intermediates requiring cryogenic handling.
United States
Massachusetts and North Carolina biotechnology sponsors adopt performance-based service agreements tying processor compensation to particle size targets rather than throughput volumes. FDA process validation guidance revisions extend qualification timelines for three consecutive commercial-scale batches. Greater Boston contract manufacturers pilot continuous fluid bed granulation with integrated PAT sensing for real-time release.
Switzerland
Basel-region pharmaceutical sponsors transfer powder processing volumes to contract manufacturers, freeing capital for biologics R&D pipelines. Swissmedic inspection cycles and pharmacopeial standards for elemental impurities tighten specification requirements. Zurich and Geneva clusters specialize in high-potency API micronization with isolator technology for containment.
Japan
Electronic materials producers in the Kanto and Kansai regions contract jet milling services for thermal interface materials requiring sub-10-micron particle distributions. METI industrial standards and PMDA quality management requirements shape equipment qualification protocols. Nagoya and Osaka manufacturing corridors concentrate precision milling capacity for semiconductor packaging materials.
India
Production-linked incentives for active pharmaceutical ingredient manufacturing attract powder processing investment toward Gujarat and Telangana clusters. CDSCO manufacturing licensing and FSSAI food safety standards govern multi-purpose facility operations. Ahmedabad and Hyderabad industrial zones expand cryogenic milling infrastructure for lipid nanoparticle excipients serving cell therapy developers.
Powder Processing Service Market Competitive Landscape
Concentration sits with integrated equipment manufacturers possessing captive technology portfolios and long-standing pharmaceutical validation relationships. The vendor base stratifies across three tiers: multinational machinery builders with service divisions, independent toll processors leasing standardized units, and regional specialists in niche thermal or containment applications. Dominant competitive moves include backward integration into analytical testing capabilities and strategic partnerships with CDMOs seeking end-to-end powder-to-tablet workflows.
Within the integrated equipment tier, Hosokawa Micron Corporation and Syntegon Technology GmbH exemplify archetypes leveraging proprietary milling and packaging technology to anchor premium service offerings. Charles Ross and Son Company occupies a position among mid-scale batch processing specialists. Independent toll processors including Bepex International LLC and British Rema represent the equipment-leasing model competing on flexibility and geographic proximity rather than captive technology control.
| Leading Market Players |
|---|
| Hosokawa Micron Corporation |
| Charles Ross and Son Company |
| Syntegon Technology GmbH |
| Bepex International LLC |
| Ongsun Powder Processing Equipment Co., Ltd |
| Hänsel Processing GmbH |
| Powder Process Solutions |
| British Rema |
| Guilin Hongcheng Mining Equipment Manufacture Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Equipment utilization rates above 85% at German toll processors create scale economies that compress per-kilogram processing costs while simultaneously elevating price floors for mid-scale competitors lacking comparable throughput. This capacity concentration reinforces a bifurcation where REACH-validated facilities command substantial premiums over Southern European operators, while energy-intensive thermal services face margin compression from natural gas volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order jet milling with isolator containment from standard batch blending services, with price differentiation anchored in FDA validation tiers and REACH documentation completeness. Contract-based long-term offtake agreements dominate pharmaceutical relationships, though performance-based models tying compensation to particle size achievement are displacing throughput-based structures among Massachusetts biotechnology sponsors. Pricing pressure stems from solution-based API synthesis routes displacing solid-state processing in select therapeutic categories. Mid-scale contract manufacturers exhibit highest price sensitivity due to capital constraints, while integrated chemical majors prioritize qualification speed over unit cost.
Supply Chain Analysis
Eighteen-month equipment lead times from German and Italian precision milling manufacturers constrain inventory availability for capacity expansion, forcing toll processors to commit capital years ahead of demand confirmation. Supply concentrates in Germany, Switzerland, and Japan, with specialized containment infrastructure and jet milling capacity drawing from precision engineering ecosystems in Bavaria, Basel, and Nagoya. Raw material dependencies include high-purity grinding media, pharmaceutical-grade excipients, and liquid nitrogen for cryogenic operations. Single-source vulnerability pervades precision milling equipment supply, where three European manufacturers control critical spindle and classifier technology. Distribution runs through pharmaceutical CDMO networks and direct sponsor relationships, with harbor zones in Frankfurt and Hamburg anchoring temperature-sensitive API logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characteristics define this market as continuous manufacturing mandates and cell therapy excipient demand create penetration headroom previously unavailable to toll processors. FDA and EMA regulatory alignment around real-time release testing accelerates adoption curves for integrated PAT-enabled facilities.
For Market Incumbents: Secure backward integration into analytical testing capabilities to capture qualification timeline value currently leaking to third-party laboratories. Anchor capacity expansion in Switzerland and Germany where REACH documentation packages and FDA validation relationships create defendable positioning against emerging Indian competitors. Prioritize containment infrastructure upgrades ahead of EMA Annex 1 enforcement cycles to preserve high-potency API processing premiums.
For New Entrants and Emerging Players: Lead with cryogenic milling capacity for lipid nanoparticle excipients in North American markets where infrastructure lags cell therapy developer demand. Target Gujarat and Telangana clusters under India's PLI scheme for API manufacturing, where production-linked incentives compress effective capital requirements. Position through performance-based service agreements that align compensation with downstream tableting success, mirroring Massachusetts sponsor procurement patterns.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among toll processors with captive equipment technology and long-standing pharmaceutical validation relationships, suggesting durable cash flow quality in integrated machinery-service hybrids. Five-to-ten-year viability favors processors with PAT-enabled continuous processing lines over legacy batch operators facing retooling obsolescence. Acquisition target archetype: mid-scale European toll processors with REACH documentation packages and underutilized containment infrastructure. Monitor FDA process validation guidance revisions as inflection signal—accelerated batch qualification requirements would concentrate demand toward processors with established commercial-scale track records.
| Strategic Initiative | Industry Significance |
|---|---|
| Containment Infrastructure Upgrade | EMA Annex 1 compliance preserves high-potency API processing access in Netherlands and Belgium. |
| Continuous Processing Line Deployment | Integrated PAT sensing enables real-time release for Irish and Danish oral solid dosage manufacturers. |
| Cryogenic Capacity Expansion | Liquid nitrogen milling infrastructure captures lipid nanoparticle excipient demand from cell therapy developers. |
| Backward Integration into Analytics | In-house particle characterization reduces qualification timelines for pharmaceutical sponsor introductions. |
| Geographic Expansion to India | Gujarat and Telangana clusters leverage PLI incentives for API manufacturing toll processing. |
Research Methodology
A standing panel of toll processing operations directors, pharmaceutical sponsor procurement managers, regulatory affairs leads at CDMOs, and precision milling equipment manufacturers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection databases, REACH registration dossiers, and SEC filings from disclosed pharmaceutical services relationships. Bottom-up capacity utilization estimates triangulated against top-down pharmaceutical outsourcing spend allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning service type, application, technology modality, and regional regulatory cluster. CAGRs derived from equipment capacity expansion pipelines, sponsor R&D pipeline disclosures, and regulatory mandate implementation timelines. Forecast inputs incorporated continuous manufacturing adoption curves, cell therapy developer demand projections, and energy cost scenario modeling for thermal processing operations.
Forecasts assume regulatory continuity in FDA cGMP enforcement, REACH substance evaluation timelines, and EMA Annex 1 implementation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Magnet Rings Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Mineral Wool Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Industrial Round Wood Market