
 SQUID Sensor Market | 2026-2036
SQUID Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
SQUID Sensor Market Analytics
German cryogenic engineering firms is pivoting toward modular dilution refrigerator designs that slash SQUID system footprint. Supracon AG leverages its Dresden manufacturing base to dominate European low-temperature SQUID supply. Magnicon GmbH anchors precision electronics for multi-channel SQUID readout, while Quantum Design Inc. competes through integrated magnetometer platforms that bundle sensors with cryostats.
A SQUID sensor exploits superconducting quantum interference to detect magnetic fields below one femtotesla, requiring liquid helium or advanced cryocoolers to maintain niobium or yttrium barium copper oxide junctions below their critical temperature. Low-temperature SQUIDs sustain dominance in medical imaging due to unmatched noise floors, while high-temperature SQUIDs extend into portable geological exploration where liquid nitrogen cooling proves operationally simpler. Scientific research applications concentrate margin pools around custom multi-channel arrays, whereas industrial monitoring segments favor standardized single-sensor deployments.
FDA 510(k) pathways govern clinical magnetoencephalography systems in the United States, while EMA medical device regulations shape European commercialization timelines for brain-mapping equipment. ISO 13485 certification pressures sensor manufacturers to document traceability across superconducting wafer fabrication. Buyers must weigh cryogen-free cooling roadmaps against established liquid helium infrastructure when planning decade-long instrument deployments.
Market Dynamics
The SQUID sensor market pivots on cryogenic cooling economics, where niobium Josephson junction fabrication advances are compressing system footprints while NIH-funded neuroscience consortia in the United States sustain procurement velocity for multi-channel arrays.
Growth Catalysts
- NIH neuroscience funding:Federal research consortia in the United States drive magnetoencephalography installations for pre-surgical brain mapping, sustaining demand for low-temperature SQUID arrays.
- Modular dilution refrigerator designs:German cryogenic engineering firms are shrinking system footprints, expanding clinical deployment feasibility in space-constrained hospital environments.
- High-temperature superconducting materials:Yttrium barium copper oxide junctions enable liquid nitrogen cooling, opening portable geological exploration applications where helium logistics prove prohibitive.
Market Restraints
- Helium supply concentration:Geographic bottlenecks in helium extraction and refining create input cost volatility for liquid helium-dependent low-temperature SQUID systems.
- FDA 510(k) pathway duration:Clinical magnetoencephalography commercialization in the United States faces extended regulatory review timelines, compressing manufacturer cash conversion cycles.
- Cryogen-free cooling performance gaps:Pulse-tube and Gifford-McMahon coolers introduce vibration noise that degrades magnetic field resolution below liquid helium baselines.
Strategic Opportunities
- EMA medical device regulation harmonization:Streamlined European brain-mapping equipment approvals create white space for multi-channel array vendors to scale across Germany, France, and the Netherlands.
- Quantum sensing convergence:Integration of SQUID magnetometers with atomic vapor cell sensors enables hybrid platforms for next-generation neuromorphic computing readout applications.
- Geological exploration in remote terrains:High-temperature SQUID deployments for mineral detection in the Australian Outback and Canadian Shield bypass helium logistics entirely.
Industry Challenges
- ISO 13485 traceability documentation:Superconducting wafer fabrication requires exhaustive batch records, extending quality system implementation timelines for sensor manufacturers entering clinical segments.
- Cryogenic technician scarcity:Specialized skills in dilution refrigerator maintenance and Josephson junction diagnostics concentrate in legacy physics departments, constraining field service expansion.
- Multi-channel array integration complexity:Synchronizing hundreds of SQUID readout channels with precision electronics demands firmware-architecture expertise that vendor engineering teams struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SQUID Sensor Market |
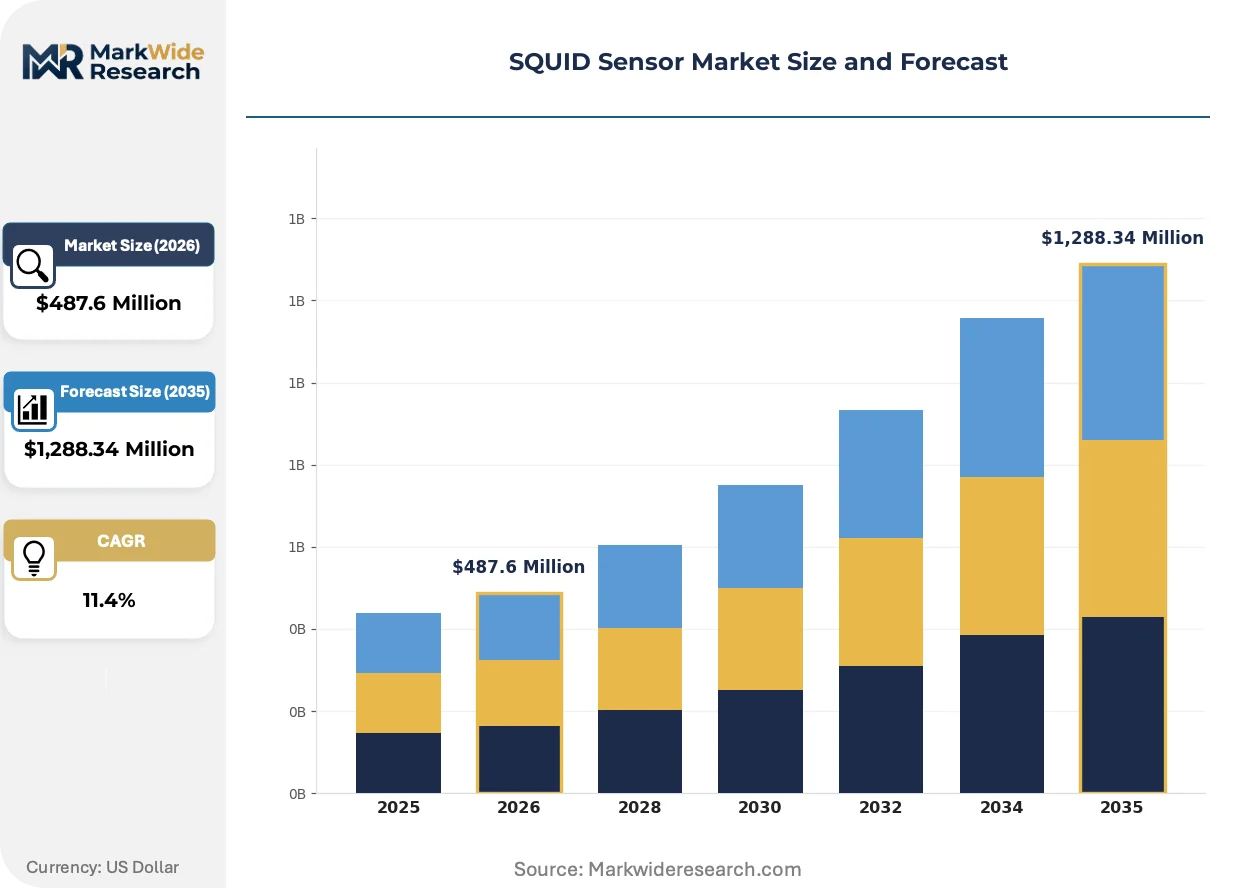
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Temperature SQUIDs, High-Temperature SQUIDs, Flux-Based SQUIDs, RF SQUIDs Application: Scientific Research, Medical Imaging, Geological Exploration, Industrial Monitoring End User: Healthcare, Academia, Oil & Gas, Manufacturing Deployment: On-Premises, Cloud-Based, Portable, Fixed Installation |
| Companies Covered | Supracon AG, Magnicon GmbH, Quantum Design Inc., Asahi Kasei Microdevices, Honeywell International Inc., Cryogenic Ltd, Tristan Technologies Inc., Infineon Technologies AG, STAR Cryoelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SQUID Sensor Market Evolving Landscape
Three vectors reshape competitive positioning: cryogen-free cooling architectures, regulatory harmonization pressures, and procurement model evolution toward instrument-as-a-service structures.
Niobium-based Josephson junction fabrication is absorbing process innovations from semiconductor lithography, enabling sub-micron feature sizes that reduce critical current dispersion. Medical imaging OEMs in Germany and Japan are qualifying these refined junctions for next-generation magnetoencephalography systems. The technology is absorbing quality-control protocols from CMOS foundries, compressing defect rates and extending mean time between cryogenic maintenance cycles.
EU Medical Device Regulation (MDR) implementation is extending conformity assessment timelines for brain-mapping equipment across European member states. Manufacturers must now compile clinical evidence packages that satisfy notified body scrutiny beyond previous Medical Device Directive thresholds. The regulation is compressing commercialization schedules for multi-channel SQUID arrays, favoring incumbents with established quality management systems over new entrants.
Hospital procurement departments are unbundling after-sales service from capital equipment purchases, negotiating separate multi-year maintenance contracts with third-party cryogenic service providers. This disintermediation fragments vendor revenue streams while creating channel conflict between sensor manufacturers and independent service organizations. The pattern is most visible in United States academic medical centers, where NIH-funded consortia prioritize operational expenditure flexibility over upfront capital commitments.
SQUID Sensor Market Segmentation
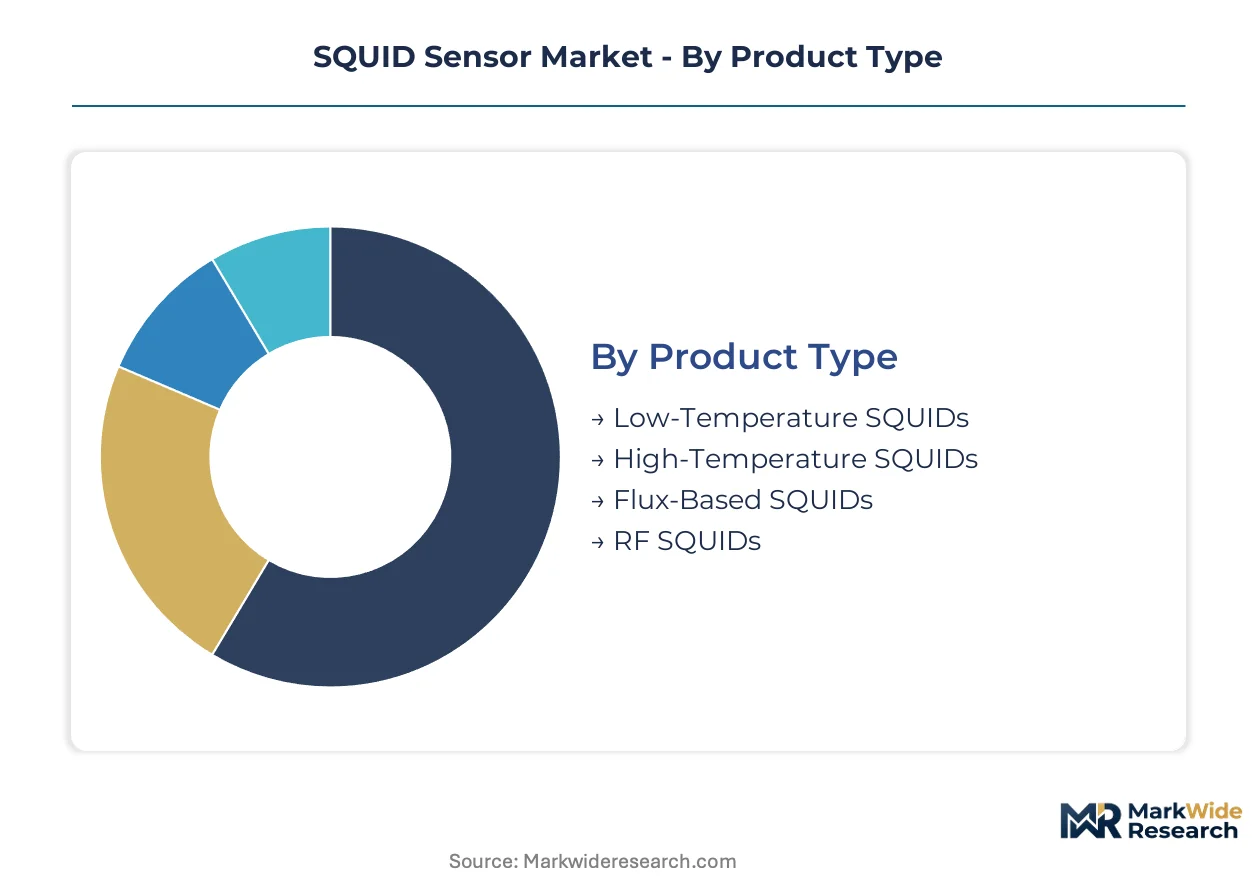
SQUID sensor procurement patterns diverge sharply across cooling architectures and end-use environments, with upgrade cycles spanning 8-12 years for hospital installations versus 3-5 year refresh rates in research laboratories. Understanding these segment boundaries clarifies where cryogenic engineering investments concentrate and which application verticals drive next-generation junction fabrication roadmaps.
Product Type:
Replacement cycles for SQUID sensors hinge on cooling infrastructure amortization, with liquid helium systems requiring synchronized cryostat upgrades that extend deployment timelines.
- Low-Temperature SQUIDs:Niobium Josephson junctions operating below 9.2 Kelvin deliver femtotesla-level noise floors essential for magnetoencephalography. NIH-funded neuroscience consortia in the United States anchor demand, though helium supply bottlenecks constrain expansion in helium-importing nations.
- High-Temperature SQUIDs:Yttrium barium copper oxide junctions function at liquid nitrogen temperatures, eliminating helium logistics for geological fieldwork. Australian mineral exploration operators and Canadian Shield survey teams favor these units for remote terrain deployments where cryogen transport proves prohibitive.
- Flux-Based SQUIDs:Direct-coupled magnetometer designs integrate pickup coils with Josephson junction loops for simplified readout electronics.
- RF SQUIDs:Single-junction configurations serve as sensitive radio-frequency detectors in quantum computing readout applications.
Low-Temperature SQUIDs sit at the top of the volume ranking, with High-Temperature SQUIDs climbing the fastest.
Application:
Application selection correlates with magnetic field resolution requirements and operational mobility constraints, creating distinct margin profiles across stationary versus field-deployed use cases.
- Scientific Research:Multi-channel SQUID arrays for condensed matter physics command premium pricing due to custom firmware requirements. German Max Planck Institutes and Japanese national laboratories sustain procurement through institutional grant funding cycles.
- Medical Imaging:Magnetoencephalography systems for pre-surgical brain mapping require FDA 510(k) clearance in the United States and EMA MDR conformity in Europe, extending commercialization timelines.
- Geological Exploration:Aeromagnetic and ground-based mineral detection favors portable high-temperature configurations.
- Industrial Monitoring:Non-destructive testing and quality control applications utilize standardized single-sensor deployments with shorter procurement cycles.
Scientific Research captures the highest absolute spending per installation, while Medical Imaging demonstrates the steepest expansion trajectory.
End User:
End-user procurement authority shapes vendor engagement models, with healthcare systems negotiating enterprise service contracts distinct from academic grant-funded purchases.
- Healthcare:Hospital radiology departments and specialized neurology centers prioritize FDA-cleared magnetoencephalography platforms with multi-year maintenance agreements.
- Academia:University physics departments and national laboratories favor configurable multi-channel arrays with open firmware architectures for experimental flexibility.
- Oil & Gas:Exploration divisions of integrated energy companies deploy portable SQUID magnetometers for subsurface reservoir characterization.
- Manufacturing:Semiconductor fabrication facilities and aerospace component suppliers integrate SQUID-based non-destructive testing into quality assurance workflows.
Healthcare dominates current installed base value, with Academia generating the most frequent repeat procurement cycles.
Deployment:
Deployment architecture determines cooling system integration complexity and data pipeline requirements, with cloud connectivity emerging as a differentiator for distributed sensor networks.
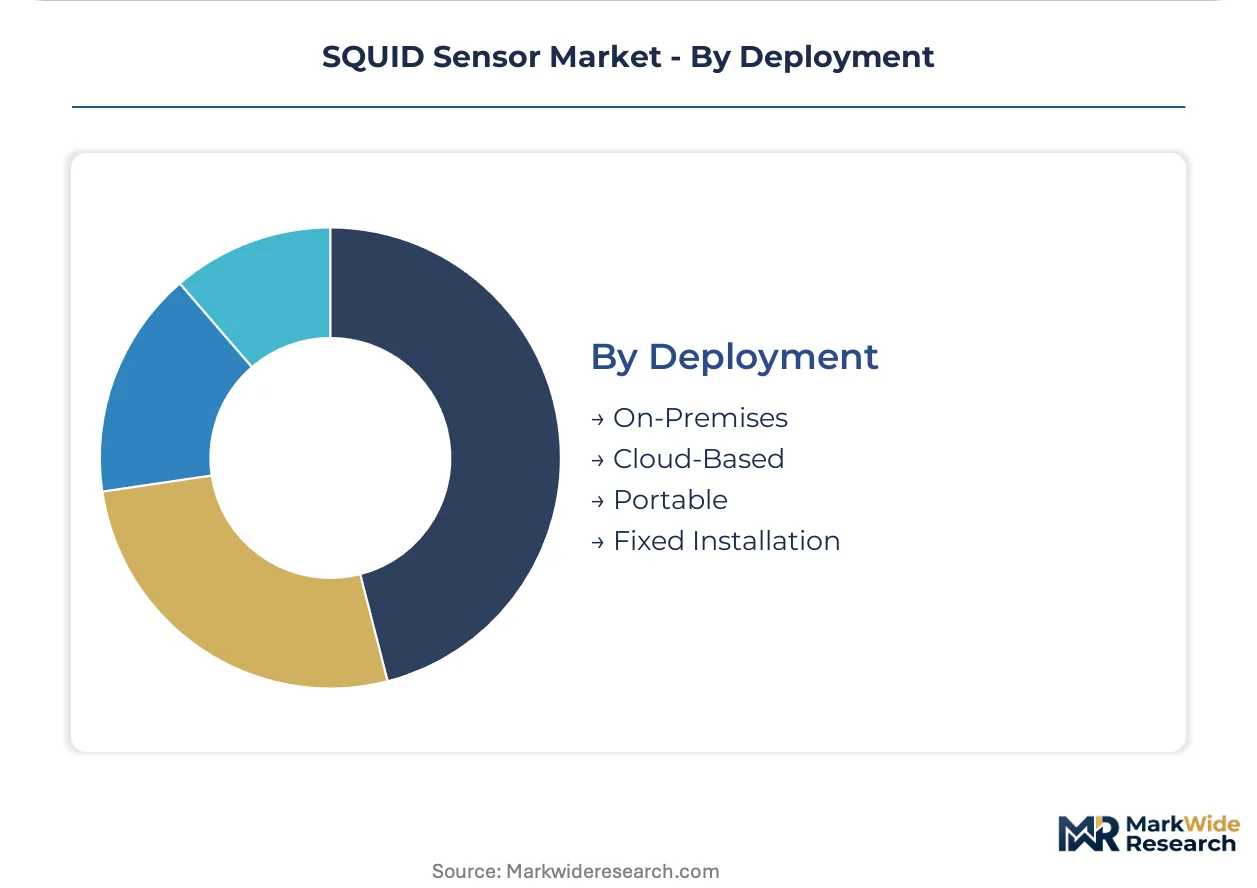
- On-Premises:Hospital-based magnetoencephalography suites and laboratory fixed installations require dedicated cryogenic infrastructure with localized technician support.
- Cloud-Based:Remote monitoring platforms aggregate SQUID array data for centralized analysis, appealing to multi-site research consortia.
- Portable:Backpack-mounted or vehicle-towed high-temperature SQUID systems enable rapid geological survey deployment without fixed infrastructure.
- Fixed Installation:Permanent magnetometer stations for geomagnetic observation and environmental monitoring operate with automated cryogenic maintenance protocols.
Fixed Installation maintains the largest cumulative deployed base, with Portable configurations gaining share fastest in resource exploration verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands European SQUID sensor procurement through its dense cryogenic engineering cluster, while Japan leverages national laboratory networks to sustain magnetoencephalography deployment velocity.
United States
NIH neuroscience consortia drive multi-channel SQUID array procurement for pre-surgical brain mapping at academic medical centers. FDA 510(k) pathways govern clinical magnetoencephalography commercialization, extending manufacturer review timelines. Greater Boston anchors demand concentration, with Massachusetts General Hospital and MIT Lincoln Laboratory sustaining adjacent procurement cycles.
Germany
Max Planck Institutes and university physics departments sustain institutional grant-funded purchases of custom multi-channel arrays. EMA Medical Device Regulation extends conformity assessment timelines for brain-mapping equipment across member states. Dresden concentrates manufacturing competence, with Supracon AG leveraging its fabrication base to dominate European low-temperature SQUID supply.
Japan
National laboratories and specialized neurology centers prioritize magnetoencephalography platforms for epilepsy surgery planning. METI industrial policy supports domestic superconducting electronics manufacturing through targeted R&D subsidies. Tokyo-Osaka corridor hosts the densest installed base of clinical MEG systems in Asia-Pacific.
United Kingdom
Oxford and Cambridge university consortia drive scientific research procurement of configurable SQUID arrays with open firmware architectures. UK Medicines and Healthcare products Regulatory Agency oversees clinical device registration timelines. London-Southeast corridor concentrates hospital radiology department demand for FDA-cleared magnetoencephalography platforms.
Australia
Mineral exploration operators in the Outback deploy portable high-temperature SQUID systems for aeromagnetic surveys where helium logistics prove prohibitive. Therapeutic Goods Administration regulates medical device importation pathways. Western Australia anchors field deployment concentration, with survey contractors bypassing cryogen transport entirely through liquid nitrogen cooling architectures.
SQUID Sensor Market Competitive Landscape
German producers anchor one tier of cryogenic system integration; United States specialists hold another around precision electronics and multi-channel readout architectures. The vendor base stratifies across three tiers: integrated platform providers bundling sensors with cryostats, component specialists supplying Josephson junction fabrication, and regional service organizations maintaining dilution refrigerator infrastructure. Two dominant competitive moves define current positioning: backward integration into superconducting wafer fabrication to secure junction supply, and geographic expansion through third-party cryogenic service partnerships to fragment after-sales revenue streams.
Within the integrated platform tier, Quantum Design Inc. and Tristan Technologies Inc. exemplify vendors bundling magnetometer sensors with cryogenic infrastructure. Among German component specialists, Supracon AG and Magnicon GmbH occupy positions at opposite ends of the value chain—one anchoring superconducting fabrication, the other precision multi-channel electronics. Asahi Kasei Microdevices represents the Asian specialist archetype, sitting within a broader microdevice manufacturing portfolio that diversifies exposure across sensing applications.
| Leading Market Players |
|---|
| Supracon AG |
| Magnicon GmbH |
| Quantum Design Inc. |
| Asahi Kasei Microdevices |
| Honeywell International Inc. |
| Cryogenic Ltd |
| Tristan Technologies Inc. |
| Infineon Technologies AG |
| STAR Cryoelectronics |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-cleared magnetoencephalography platforms and unvalidated research-grade arrays manifests in pricing spreads exceeding threefold, with supply chain configurations clustering around distinct cryogenic infrastructure tiers that lock buyers into decade-long cooling technology commitments.
Pricing Analysis
Distributor margins for SQUID sensor systems compress at 12-18% for multi-channel magnetoencephalography platforms, while direct-to-academic pricing carries steeper discounts reflecting grant-funded procurement constraints. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) certification status and helium versus cryogen-free cooling architectures. Pricing pressure stems from hospital procurement departments unbundling service contracts from capital equipment purchases. Academic laboratories exhibit highest price sensitivity due to fixed institutional grant ceilings, whereas specialized neurology centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Freight costs for liquid helium dewars constrain field deployment economics, with remote geological survey teams absorbing transport premiums that can match sensor hardware values for single deployments. Niobium Josephson junction fabrication concentrates in Germany, Japan, and the United States, while precision multi-channel electronics sourcing draws from German and United States specialist vendors. Raw material dependencies span high-purity niobium, yttrium barium copper oxide substrates, and specialized cryogenic stainless steels. Single-source vulnerability concentrates around dilution refrigerator compressors from a limited supplier base. Distribution runs through integrated platform providers bundling sensors with cryostats, supplemented by component specialists serving custom research array builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in cryogen-free cooling transitions and premium-tier magnetoencephalography platform upgrades, with niobium-based Josephson junction fabrication advances compressing cost structures for next-generation deployments.
For Market Incumbents: Extend backward integration into superconducting wafer fabrication to secure captive Josephson junction supply against emerging thin-film deposition specialists. Deepen geographic footprint through third-party cryogenic service partnerships in Asia-Pacific academic medical centers, defending installed base relationships against modular dilution refrigerator entrants. Prioritize ISO 13485 quality system investments to accelerate EMA MDR conformity timelines for brain-mapping equipment commercialization. For New Entrants and Emerging Players: Launch via portable high-temperature SQUID configurations targeting Australian mineral exploration operators and Canadian Shield survey contractors where helium logistics create incumbent vulnerability. White-space concentration appears in cloud-based remote monitoring platforms aggregating distributed sensor networks for multi-site research consortia. Pursue instrument-as-a-service procurement models that disaggregate capital expenditure into operational budgets, aligning with United States academic medical center purchasing committee preferences. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic technician scarcity constrains field service expansion for independent service organizations lacking dilution refrigerator maintenance capabilities. Five-to-ten year viability favors vendors with integrated platform architectures spanning sensors, cryostats, and precision electronics rather than pure-play component suppliers exposed to OEM backward integration. Signal to monitor: NIH neuroscience funding appropriation trajectories and METI industrial policy shifts affecting Japanese domestic superconducting electronics manufacturing subsidies.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Cooling Platform Development | Pulse-tube and Gifford-McMahon architectures bypass helium logistics for remote geological deployments. |
| Backward Integration into Josephson Junction Fabrication | Captive niobium-based superconducting wafer production secures supply against thin-film deposition bottlenecks. |
| EMA MDR Conformity Investment | Streamlined European brain-mapping equipment approvals create scaling pathways across Germany, France, and Netherlands. |
| Instrument-as-a-Service Procurement Model | Unbundled maintenance contracts align with United States academic medical center operational expenditure priorities. |
| Quantum Sensing Convergence Partnership | Hybrid SQUID-atomic vapor cell platforms target neuromorphic computing readout applications. |
Research Methodology
Coverage spans United States, Germany, Japan, United Kingdom, and Australia, with primary inputs from each market combining structured interviews with cryogenic engineering executives, hospital biomedical engineering directors, academic physics department procurement leads, and mineral exploration survey contractors. Secondary validation draws from FDA 510(k) filings, EMA MDR conformity assessment databases, NIH grant award records, METI industrial policy documentation, and hospital procurement database extracts. Bottom-up and top-down triangulation reconciles sensor unit shipment estimates with aggregate institutional capital expenditure tracking.
Granularity-level modeling extends across cooling architecture tiers, application verticals, and end-user procurement authority segments, with regional regulatory cluster differentiation for FDA, EMA, and TGA jurisdiction-specific commercialization timelines. CAGRs derive from weighted average growth trajectories across scientific research, medical imaging, geological exploration, and industrial monitoring application segments. Industry-specific forecast inputs incorporate helium supply concentration risk premiums and cryogen-free cooling performance gap resolution timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt helium supply disruption scenarios or accelerated FDA 510(k) pathway reforms. Stakeholders should weight assumptions against their own operating context, particularly regarding liquid helium infrastructure amortization schedules and cryogenic technician field service availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Water Quality Sensor Market