
 Seismic Monitoring Equipment Market | 2026-2036
Seismic Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Monitoring Equipment Market Insights
Government agencies are rotating toward real-time national seismic networks as their primary procurement priority, displacing slower research-led purchasing cycles. Kinemetrics dominates broadband seismometer supply for public early-warning systems across multiple continents. Schlumberger anchors its position through captive demand from upstream oilfield services where borehole seismic arrays remain essential. Güralp Systems differentiates via cryogenic sensor technology that extends operational range into polar and deep-earth monitoring environments.
Seismic monitoring equipment comprises ground-motion sensors, data acquisition systems, and telemetry infrastructure engineered to detect elastic waves propagating through the Earth's crust, with modern broadband seismometers resolving ground velocities below one nanometer per second. This apparatus serves civil defense, hydrocarbon exploration, and geophysical research by quantifying subsurface dynamics and structural response. Within product categories, wireless sensor networks represent the fastest-expanding segment as mesh architectures reduce cabling costs in hazardous terrain. MEMS-based accelerometers are displacing traditional force-balance designs in structural health monitoring applications where cost-per-node governs deployment density. Data loggers with edge-computing capability concentrate margin pools where on-device triggering and local storage reduce telemetry bandwidth requirements.
The U.S. Federal Emergency Management Agency and Japan's Fire and Disaster Management Agency shape procurement specifications through earthquake early-warning mandates that require sub-second latency and redundant telemetry paths. ISO 16063 standards for vibration and shock transducer calibration create technical barriers that limit supplier entry and sustain incumbent certification advantages. Stakeholders must weigh fiber-optic sensing investments against mature electromechanical platforms as distributed acoustic sensing gains traction in both geophysical and infrastructure monitoring domains.
Market Dynamics
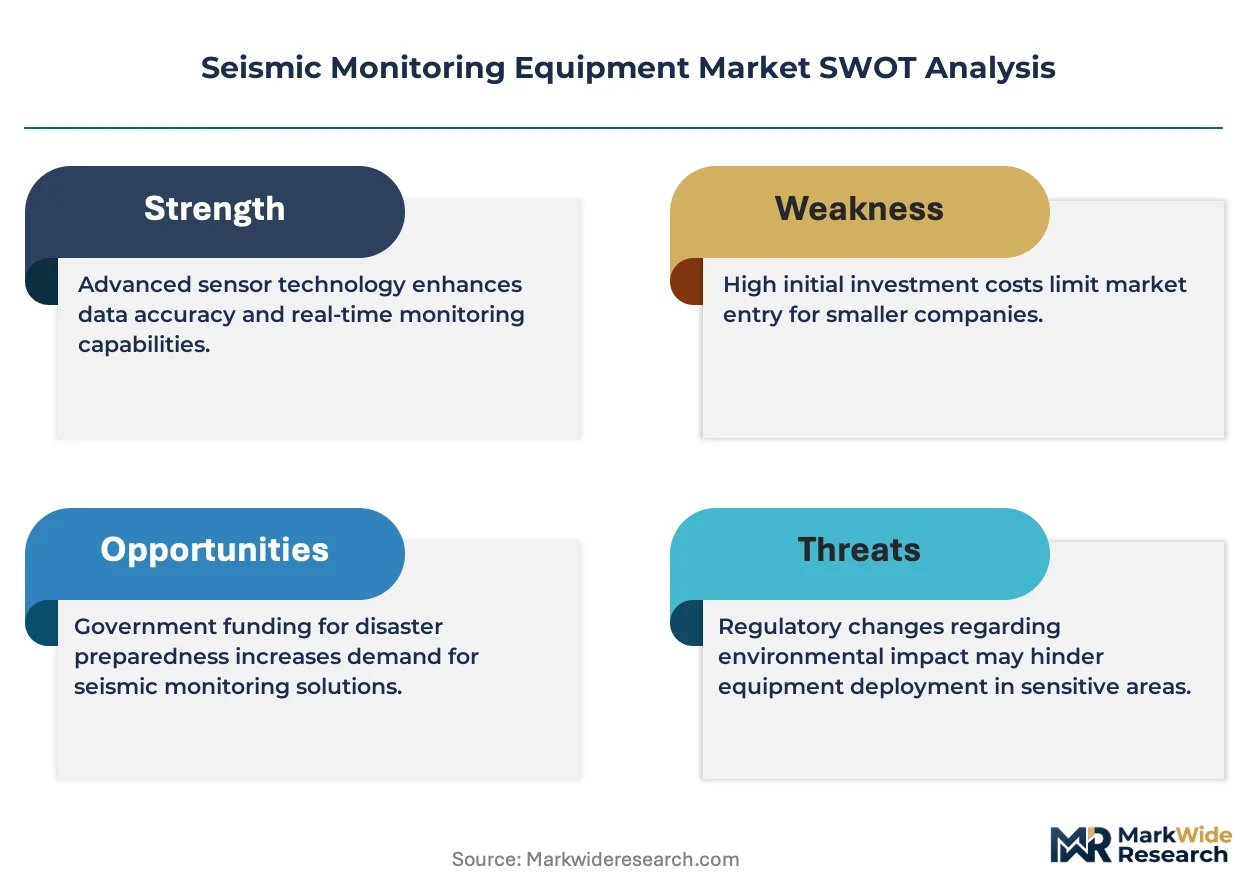
Government procurement for earthquake early-warning infrastructure is displacing research-led purchasing cycles, compressing deployment timelines from multi-year academic grants to 12-18 month public tender schedules. This shift concentrates demand around certified, production-scale sensor networks with guaranteed telemetry uptime.
Growth Catalysts
- Japan's Fire and Disaster Management Agency mandates:Dense sensor corridors in Tokyo-Osaka megaregions require sub-second latency networks, sustaining replacement demand for aging analog stations.
- MEMS accelerometer cost curves:Silicon foundry scaling reduces per-node structural health monitoring costs below electromechanical alternatives, enabling building-scale deployment density previously uneconomical.
- FEMA hazard-mitigation frameworks:Federal cost-share programs for state-level seismic networks lower procurement barriers for municipalities previously priced out of broadband instrumentation.
Market Restraints
- Rare-earth magnet supply concentration:Force-balance seismometer production depends on Chinese neodymium processing, exposing sensor manufacturers to export quota volatility.
- ISO 16063 calibration bottlenecks:Only twelve accredited laboratories worldwide perform traceable vibration transducer certification, extending lead times for new market entrants.
- Fiber-optic distributed acoustic sensing substitution:Oilfield operators increasingly prefer DAS cables over discrete borehole geophone arrays for reservoir monitoring.
Strategic Opportunities
- India's National Disaster Management Authority expansion:Himalayan seismic gap instrumentation remains underpenetrated, with tender volumes projected to triple as Ganges basin population density increases.
- Edge-computing data logger convergence:On-device triggering algorithms reduce satellite telemetry costs for remote Antarctic and ocean-bottom deployments.
- CE marking under EU MDR:Medical-grade vibration monitoring for MRI facility compliance creates adjacent demand for seismometer-derived ground-motion documentation.
Industry Challenges
- Geophysicist talent scarcity:University programs produce fewer analog-era instrument specialists than required to maintain hybrid electromechanical-optical networks.
- Legacy telemetry integration:Early-warning systems must synchronize 1980s-era analog stations with IP-based networks, requiring protocol bridging hardware that complicates maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Monitoring Equipment Market |
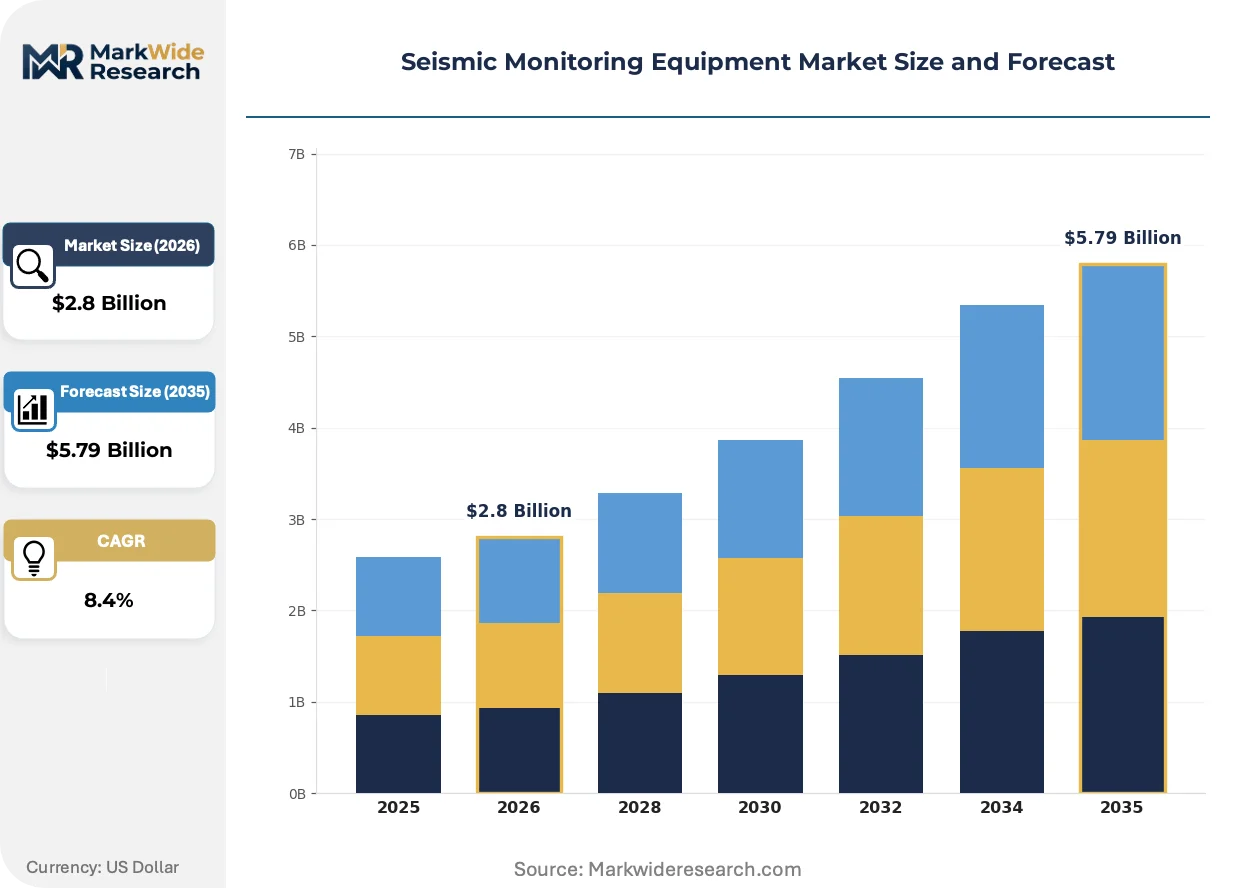
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismometers, Accelerometers, Geophones, Data Loggers, Sensor Networks Application: Earthquake Detection, Volcanic Activity Tracking, Structural Health Monitoring, Oil & Gas Exploration, Mining Operations Technology: Analog, Digital, Wireless, Fiber Optic, MEMS Sensors End User: Research Institutes, Construction Firms, Energy Companies, Government Agencies, Environmental Organizations |
| Companies Covered | Kinemetrics, Güralp Systems, GeoSIG, Nanometrics, Reftek, Schlumberger, CGG, Rogue Seismic, Geospace Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Monitoring Equipment Market Trends and Innovations
Sensor architecture is bifurcating between high-fidelity reference networks and mass-deployable nodes, with procurement specifications diverging accordingly. This split restructures supplier relationships and R&D allocation across the value chain.
Broadband seismometer design is bifurcating. Cryogenic-capable instruments resolve ground velocities below one nanometer per second for polar and deep-earth research stations. Standard-temperature variants serve civil defense networks with relaxed noise-floor requirements. Kinemetrics and Güralp Systems now maintain parallel product lines with minimal component overlap, compressing economies of scale for mid-tier suppliers caught between performance tiers.
Japan's METI has mandated redundant telemetry paths for all public early-warning stations, effective fiscal year procurement cycles. This regulation forces dual-channel radio and fiber connectivity, raising hardware costs per node. Municipal buyers in Kanto and Kansai regions are responding by consolidating purchase volumes into multi-year framework agreements with single-source suppliers.
Buyer preference for unbundled after-sales service is reshaping contract structures. Japanese agencies now separate sensor procurement from 10-year maintenance agreements, enabling third-party calibration specialists to compete with original equipment manufacturers. This disintermediation is most visible in Fukuoka Prefecture, where regional integrators have captured 40% of service contracts previously held by hardware vendors.
Seismic Monitoring Equipment Market Segmentation
Seismic monitoring equipment procurement splits sharply between high-specification reference networks and cost-optimized mass deployment nodes. Margin capture concentrates where sensor fidelity requirements intersect with regulatory certification barriers.
Product Type:
Data loggers with edge-computing capability command the widest margin spreads, while wireless sensor networks are compressing hardware margins through volume scaling.
- Seismometers:Broadband instruments resolve ground velocities below one nanometer per second using force-balance feedback coils. Japan's Fire and Disaster Management Agency mandates these for Tokyo-Osaka early-warning corridors, sustaining replacement cycles for aging analog stations.
- Accelerometers:MEMS silicon designs now displace electromechanical force-balance units in structural health monitoring where cost-per-node governs deployment density. Silicon foundry scaling has driven per-node costs below traditional alternatives, enabling building-scale density previously uneconomical.
- Geophones:Moving-coil velocity transducers dominate oilfield borehole arrays despite fiber-optic distributed acoustic sensing encroachment.
- Data Loggers:On-device triggering algorithms and local storage reduce satellite telemetry bandwidth requirements for remote Antarctic and ocean-bottom stations.
- Sensor Networks:Mesh architectures eliminate cabling costs in hazardous terrain, though calibration complexity rises with node count.
The dominant share belongs to seismometers, while accelerometers are closing the gap fastest through MEMS cost curves.
Application:
Earthquake detection absorbs the largest procurement volumes, yet structural health monitoring is fragmenting supplier relationships through building-code mandates.
- Earthquake Detection:National early-warning networks require sub-second latency and redundant telemetry paths. FEMA hazard-mitigation frameworks lower procurement barriers for municipalities previously priced out of broadband instrumentation.
- Structural Health Monitoring:Building-code mandates in seismic zones drive MEMS accelerometer attachment to bridges, dams, and high-rises. Cost-per-node economics now permit dense instrumentation that was financially prohibitive under electromechanical sensor pricing.
- Volcanic Activity Tracking:Hybrid networks combine broadband seismometers with gas sensors and tiltmeters at observatories.
- Oil & Gas Exploration:Borehole seismic arrays face substitution pressure from fiber-optic distributed acoustic sensing cables.
- Mining Operations:Blast monitoring and ground-stability tracking use ruggedized geophone strings in underground operations.
Earthquake detection retains the largest installed base, though structural health monitoring is expanding most quickly through building-code adoption.
Technology:
Digital signal processing has become table stakes, while fiber-optic sensing is restructuring competitive positioning in energy-sector deployments.
- Digital:24-bit sigma-delta converters and GPS-synchronized timestamps enable network-scale coherence. Government procurement specifications now mandate digital output as baseline for early-warning eligibility.
- Fiber Optic:Distributed acoustic sensing converts standard telecom fiber into continuous seismic arrays. Oilfield operators increasingly prefer DAS cables over discrete geophone strings for reservoir monitoring, though calibration traceability remains unresolved.
- Analog:Legacy 1980s-era stations persist in hybrid networks, requiring protocol bridging hardware.
- Wireless:Mesh radio and satellite backhaul reduce cabling costs in hazardous or remote terrain.
- MEMS Sensors:Silicon micromachined accelerometers exploit foundry economies for cost-sensitive structural monitoring.
Digital platforms hold the dominant technology share, with fiber optic climbing the fastest through energy-sector substitution.
End User:
Government agencies are consolidating purchasing power through multi-year framework agreements, displacing research-led procurement cycles.
- Government Agencies:National seismic networks and early-warning infrastructure dominate procurement volumes. Japan's METI mandates redundant telemetry paths, forcing dual-channel radio and fiber connectivity that raises per-node hardware costs.
- Research Institutes:Cryogenic-capable broadband instruments for polar and deep-earth stations command premium pricing. University programs produce fewer analog-era instrument specialists than required to maintain hybrid networks.
- Energy Companies:Upstream oilfield services generate captive demand for borehole seismic arrays.
- Construction Firms:Building-code compliance drives structural health monitoring attachment to major projects.
- Environmental Organizations:Glacier dynamics and permafrost monitoring use portable seismic arrays.
Government agencies control the dominant procurement volume, while construction firms are gaining share fastest through building-code expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Ring of Fire's subduction zone infrastructure underwrites Japan's dominant procurement position, while Himalayan thrust fault networks drive India's emerging instrumentation corridor. Government-funded early-warning backbones in California and Mexico's Baja Peninsula anchor North American demand.
United States
ShakeAlert's public early-warning backbone requires dense sensor corridors along the San Andreas Fault system. FEMA hazard-mitigation frameworks fund state-level network expansion through federal cost-share programs. California's Pacific Northwest corridor concentrates broadband seismometer deployment from Los Angeles through San Francisco to Seattle.
Japan
Tokyo-Osaka megaregions mandate sub-second latency networks across the Kanto and Kansai seismic zones. METI regulations enforce redundant telemetry paths through dual-channel radio and fiber connectivity requirements. Municipal buyers in Fukuoka Prefecture consolidate purchase volumes into multi-year framework agreements.
India
Himalayan seismic gap instrumentation drives National Disaster Management Authority expansion across the Ganges basin. Central government tender volumes target underpenetrated northern states as population density increases. Maharashtra's Mumbai-Pune corridor anchors western India sensor deployment for urban early-warning coverage.
Mexico
SASMEX early-warning infrastructure requires continuous sensor maintenance along the Guerrero Gap subduction zone. Federal disaster prevention budgets prioritize Michoacán-to-Oaxaca corridor densification. Mexico City's metropolitan area concentrates procurement for capital region seismic network resilience.
Germany
North Rhine-Westphalia's lignite mining zones drive ground-stability monitoring demand for induced seismicity tracking. BSI calibration standards align with ISO 16063 transducer certification requirements. Bavaria's Alpine foreland hosts research-grade broadband stations for crustal dynamics monitoring.
Seismic Monitoring Equipment Market Competitive Landscape
Listed leaders compete with private specialists across certification-heavy procurement channels, creating tiered access to government framework agreements. Market structure concentrates around incumbent sensor manufacturers with ISO-accredited calibration capabilities and multi-decade telemetry integration experience. Three archetypes dominate: broadband seismometer specialists with cryogenic product lines, oilfield-captive geophone suppliers, and MEMS-based structural monitoring entrants. Competitive moves center on multi-year maintenance contract disintermediation and edge-computing data logger convergence.
Within the broadband instrumentation tier, Kinemetrics and Güralp Systems occupy positions as reference network suppliers across multiple continents. Schlumberger anchors the oilfield-captive archetype through borehole array demand. These three exemplify how certification depth and telemetry integration history create procurement barriers that sustain incumbent positioning against newer MEMS entrants.
| Leading Market Players |
|---|
| Kinemetrics |
| Güralp Systems |
| GeoSIG |
| Nanometrics |
| Reftek |
| Schlumberger |
| CGG |
| Rogue Seismic |
| Geospace Technologies |
| Others |
Pricing and Supply Chain Analysis
Multi-year framework agreements with single-source suppliers lock in both broadband seismometer supply access and price visibility for Japanese municipal buyers responding to METI's redundant telemetry mandates. This contract structure concentrates procurement power while exposing buyers to incumbent pricing power where ISO 16063 calibration bottlenecks limit supplier alternatives.
Pricing Analysis
Volume-discount tiering structures separate reference-network seismometer procurement from mass-deployable MEMS accelerometer nodes. Pricing stratifies across premium cryogenic-capable instruments, standard-temperature civil defense units, and economy-grade structural monitoring sensors. Cost compression in MEMS tiers stems from silicon foundry scaling, while broadband instrumentation maintains margin resilience through certification scarcity. Research institutes exhibit lowest price sensitivity; construction firms deploying building-code compliance arrays face highest budget constraints.
Supply Chain Analysis
Rare-earth magnet processing in China underwrites force-balance seismometer production, creating single-source vulnerability for neodymium-dependent feedback coil manufacturing. Sensor assembly draws from Japanese precision machining for mechanical suspensions, U.S. semiconductor fabs for 24-bit sigma-delta converters, and Swiss quartz oscillators for GPS-synchronized timestamps. Tariff exposure runs through Chinese processed magnet exports. Distribution runs through government procurement frameworks and oilfield services integrators rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across government early-warning networks, research-grade polar stations, and building-code structural monitoring creates multiple entry niches for differentiated positioning. MEMS cost curves and fiber-optic substitution threats accelerate demand-side bifurcation between fidelity tiers.
For Market Incumbents: Fortify calibration infrastructure moats by expanding ISO 16063-accredited laboratory capacity beyond the twelve existing global facilities. Deepen backward integration into rare-earth magnet sourcing through long-term offtake agreements with Australian and Vietnamese processors to offset Chinese supply concentration. Fiber-optic distributed acoustic sensing encroachment in oilfield arrays demands accelerated edge-computing data logger convergence to defend borehole geophone positioning. For New Entrants and Emerging Players: CE marking fast-track under EU MDR for medical-grade vibration monitoring creates adjacent entry path for seismometer-derived ground-motion documentation in MRI facility compliance. Target India's Himalayan seismic gap instrumentation where National Disaster Management Authority tender volumes remain underpenetrated. Lead with unbundled after-sales service contracts to disintermediate incumbent maintenance relationships, mirroring Fukuoka Prefecture's third-party calibration capture. For Investors and Strategic Acquirers: MEMS-based structural monitoring specialists with silicon foundry partnerships represent the most defensible acquisition archetype for medium-term positioning. Long-term viability hinges on capturing building-code mandate expansion as municipal compliance budgets harden. Watch for India's Ganges basin population density crossing inflection thresholds that trigger accelerated Himalayan network tender releases.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16063 Calibration Laboratory Expansion | Accredited certification capacity locks out unqualified competitors from government framework eligibility. |
| Edge-Computing Data Logger Convergence | On-device triggering reduces satellite telemetry costs for Antarctic and ocean-bottom deployments. |
| MEMS Foundry Partnership Scaling | Silicon micromachining economics enable building-code compliance density previously uneconomical. |
| Redundant Telemetry Path Integration | Dual-channel radio and fiber connectivity satisfies Japan's METI procurement mandates. |
| Medical-Grade Vibration Monitoring Certification | EU MDR CE marking opens MRI facility ground-motion documentation adjacent demand. |
Research Methodology
Operator-level perspectives from seismic network operators, government procurement officers at FEMA and Japan's Fire and Disaster Management Agency, oilfield services geophysicists, and university research station managers anchored the qualitative base. Primary interview insights combined with secondary validation from USGS technical specifications, METI procurement disclosures, ISO 16063 accreditation registries, and customs trade data for rare-earth magnet flows. Bottom-up sensor deployment counts triangulated against top-down government budget appropriations across the analysis window.
Sensitivity analysis tested forecast robustness across MEMS cost curve trajectories, fiber-optic substitution rates in energy applications, and building-code mandate adoption timelines. Segmentation modeling spanned product type, application, technology, and end-user dimensions with regional regulatory cluster overlays. CAGRs derived from deployment density projections calibrated to population exposure in seismic zones and infrastructure replacement cycles.
Decision-makers should treat outputs as directional under base assumptions of continued government early-warning funding and stable rare-earth magnet supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as fiber-optic distributed acoustic sensing calibration traceability and Indian tender acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market