
 Sensor Bearing Market | 2026-2036
Sensor Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Bearing Market Intelligence
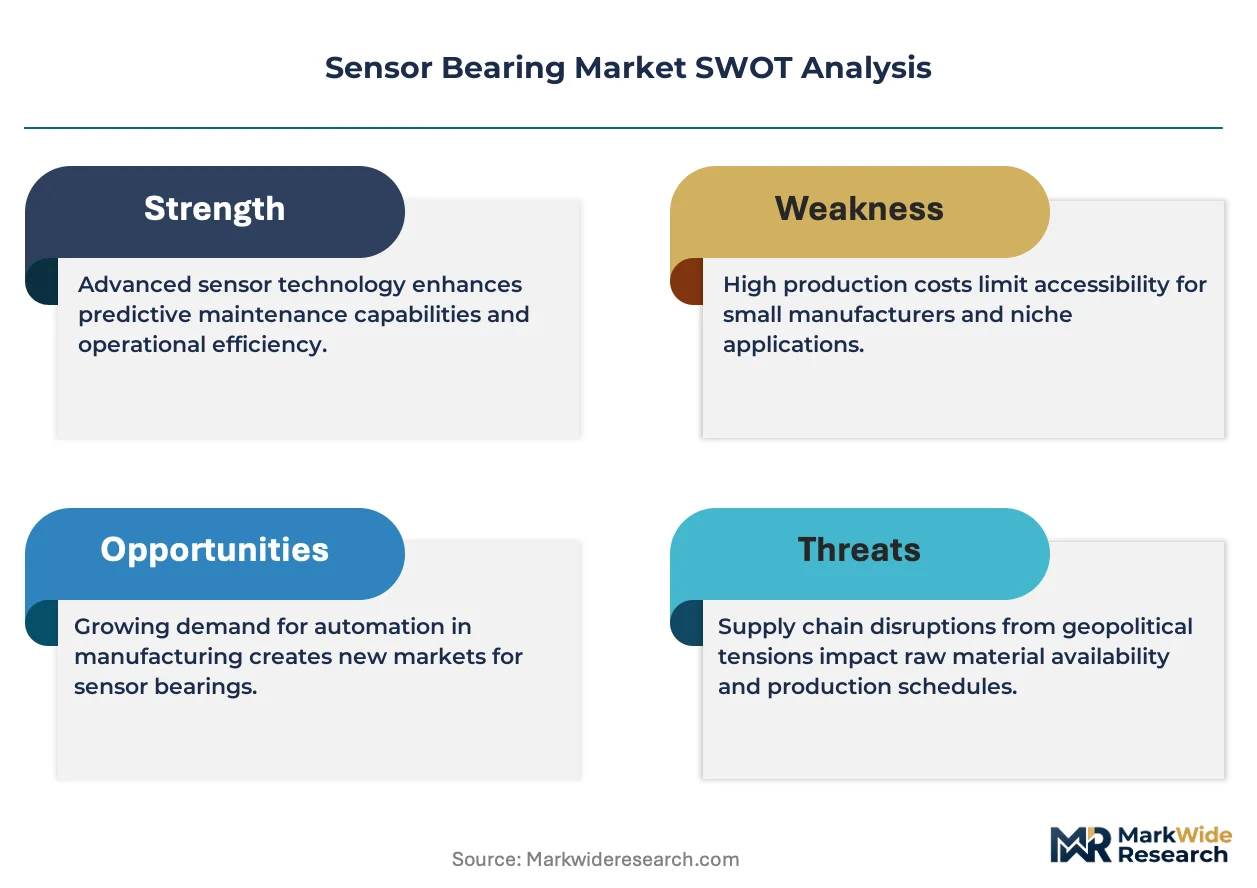
A procurement shift toward single-source partnerships for fully integrated sensor units is hardening supply chain relationships. This move away from multi-sourcing discrete components benefits established, full-system providers. SKF leverages its global manufacturing footprint to serve multinational OEMs with consistent product quality. Schaeffler Technologies AG & Co. KG specializes in customized solutions for demanding applications in aerospace and industrial automation. NTN Corporation competes on the basis of advanced material science and bearing longevity in high-speed environments.
A sensor bearing integrates measurement components directly into a standard bearing assembly to monitor operational parameters. These units typically incorporate an inductive sensor ring with a specific magnetic pole count to detect rotational speed, direction, and angular position. The primary purpose is to provide real-time data for condition monitoring, enabling predictive maintenance and enhancing control in automated systems. While inductive technology remains the standard for industrial machinery, optical sensors are finding new applications in high-precision robotics. Ball bearings represent the largest product segment by volume.
Regulatory frameworks directly influence design and adoption, mandating higher levels of operational safety and data logging. The EU Machinery Directive, enforced via CE marking, sets performance and reliability standards for components used in industrial equipment across Europe. In the United States, the FAA imposes stringent requirements for sensor components used in aerospace equipment. Stakeholders must decide whether to invest in higher-cost, certified bearings that provide compliance and data assurance or opt for lower-cost alternatives with greater performance risk.
Market Dynamics
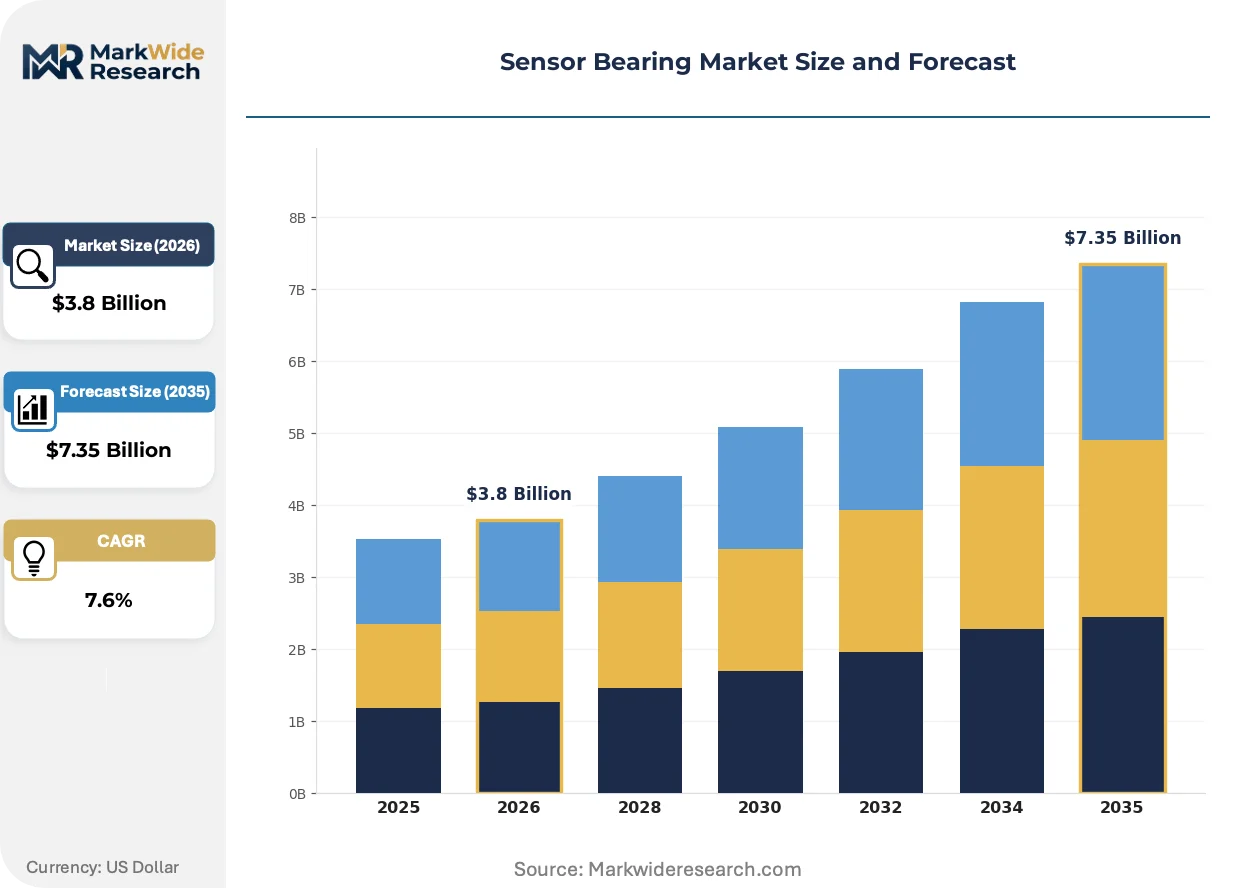
The convergence of industrial automation with stringent regulatory pressures for equipment efficiency and data logging is the central force shaping the sensor bearing market. Mandates like the EU's CSRD are compelling operators to adopt predictive maintenance, transforming bearings from simple mechanical parts into critical data nodes.
Growth Catalysts
- Predictive Maintenance Adoption:The expansion of Industry 4.0 initiatives in manufacturing, particularly within China's industrial clusters, drives demand for sensor bearings to enable real-time condition monitoring and prevent unplanned downtime in automated machinery.
- Renewable Energy Expansion:Growth in wind and solar energy systems requires advanced components for monitoring drivetrain health in wind turbines and position accuracy in solar trackers, creating a dedicated demand stream for robust sensor units.
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) pressures companies to document and improve equipment efficiency and reliability, directly boosting the business case for investing in sensor technologies that provide verifiable performance data.
Market Restraints
- Higher Unit Cost:The initial procurement cost for an integrated sensor bearing is significantly higher than for a standard mechanical bearing, creating a barrier for cost-sensitive applications or retrofits on older equipment.
- Technical Vulnerabilities:Inductive and optical sensors integrated within bearings can be susceptible to electromagnetic interference, extreme temperatures, and high-vibration environments, limiting their application in certain harsh industrial settings without additional shielding.
- Substitution from External Sensors:In some scenarios, non-contact external sensors that monitor vibration or temperature can provide sufficient data for condition monitoring without requiring the replacement of the entire bearing assembly, posing a viable alternative.
Strategic Opportunities
- High-Precision Robotics:The growing use of automated guided vehicles (AGVs) and collaborative robots in logistics and manufacturing creates new demand for compact sensor bearings that provide precise angular position and speed data for motion control.
- Wireless Integration:Developing sensor bearings with embedded wireless communication capabilities, such as Bluetooth Low Energy or LoRaWAN, offers an opportunity to simplify installation and data collection, especially in difficult-to-access or mobile equipment.
- Aerospace and Defense Certification:Gaining certifications for sensor bearing components under stringent aerospace frameworks, such as those from the FAA, opens a high-margin market for applications requiring verified reliability and performance data.
Industry Challenges
- Legacy System Integration:Operators face significant hurdles in integrating the data streams from modern sensor bearings into older, legacy manufacturing execution systems (MES) and SCADA platforms that lack compatible communication protocols.
- Data Protocol Standardization:A lack of universal standards for data output formats and communication protocols among different sensor bearing manufacturers complicates interoperability and forces end-users into single-vendor ecosystems.
- Technician Skill Gaps:The market faces a shortage of maintenance technicians who possess both the mechanical expertise to install bearings and the electronics and software skills required to configure sensors and interpret their data output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Bearing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Magnetic Bearings, Fluid Bearings, Jewel Bearings Technology: Capacitive, Piezoelectric, Inductive, Optical, Ultrasonic Application: Aerospace Equipment, Manufacturing Machinery, Renewable Energy Systems, Robotics, Marine Vessels End User: OEMs, Machine Shops, Automation Providers, Research Labs, Aftermarket Service Providers |
| Companies Covered | SKF, Schaeffler Technologies AG & Co. KG, NTN Corporation, The Timken Company, NSK Corporation, JTEKT Corporation, ABB Group, Fersa Bearings, Mageba SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Bearing Market Strategic Shifts & Innovations
Product evolution is shifting from incremental improvements in bearing materials to the integration of multi-functional sensing and communication capabilities. This transforms the component's role from a simple mechanical rotator into an active, intelligent data source for automated and predictive systems.
Multi-functional sensing technology combines speed, temperature, vibration, and load measurement into a single, compact bearing unit. End-users in heavy machinery and industrial automation are adopting these integrated solutions to simplify equipment design, reduce wiring complexity, and lower the total component count. This convergence of sensing functions into one physical part is consolidating the market's value proposition around intelligent, data-rich components rather than discrete sensors.
The EU Machinery Directive, enforced via mandatory CE marking, establishes rigorous performance and reliability requirements for components used in industrial equipment sold across Europe. This framework compels manufacturers to validate the operational safety and lifecycle of critical parts, directly impacting component selection. Consequently, the industrial automation sector in Europe increasingly favors pre-certified sensor bearings that provide compliance assurance and streamline the CE marking process for the final machine.
A distinct behavioral change is evident as large OEMs move from sourcing discrete components to establishing single-source partnerships for fully integrated sensor bearing assemblies. This procurement model replaces transactional purchasing with collaborative, long-term agreements where the supplier provides data and reliability expertise. This trend is most visible among multinational automotive and wind turbine manufacturers seeking to ensure product consistency and simplify supply chain management across their global facilities.
Sensor Bearing Market Segmentation
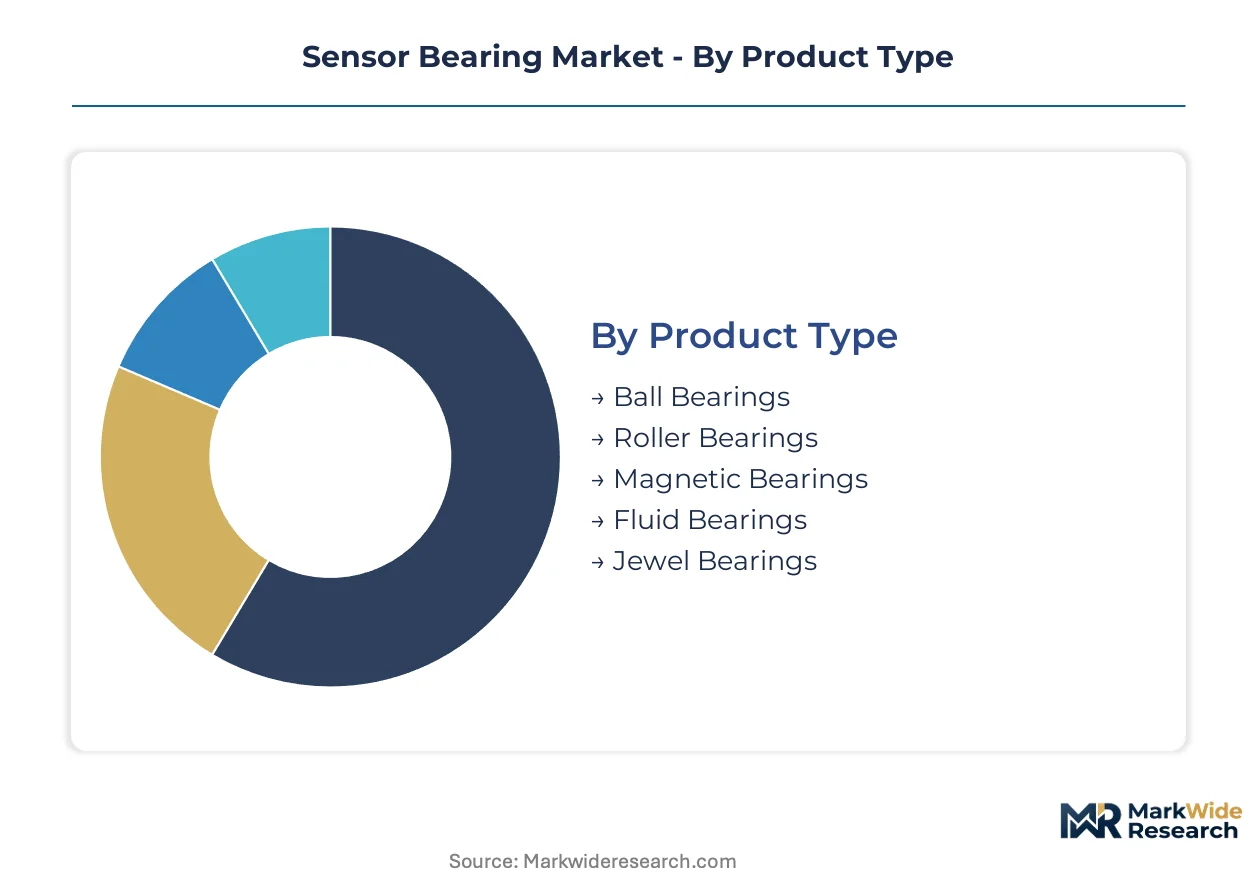
The sensor bearing market's segmentation highlights the varied technical requirements and regulatory compliance burdens across different industry verticals. Understanding these distinctions is crucial for manufacturers to tailor product development and market entry strategies effectively. Each segment presents unique opportunities and challenges for advanced sensor integration.
Product Type:
The selection of sensor bearing product types often depends on the specific operational environment and the level of regulatory scrutiny applied to the machinery. Aerospace applications, for instance, mandate certified components, increasing the cost and development time for specialized bearing types.
- Ball Bearings:These bearings incorporate measurement components directly into their standard assembly, typically featuring an inductive sensor ring for rotational data. Demand concentrates in manufacturing machinery upgrades across China's industrial clusters, driven by predictive maintenance initiatives.
- Roller Bearings:Designed to handle higher radial and axial loads, roller sensor bearings provide robust data collection in heavy-duty applications. Their use in wind turbine drivetrains is expanding, enabling advanced condition monitoring for renewable energy systems.
- Magnetic Bearings:Utilizing magnetic fields for levitation and rotation, these bearings offer friction-free operation and precise control for specialized applications. They are increasingly adopted in high-speed industrial compressors requiring exceptional accuracy.
- Fluid Bearings:These bearings operate on a thin film of fluid, providing very low friction and high precision in sensitive instruments. Fluid bearings find niche applications within advanced laboratory equipment.
- Jewel Bearings:Characterized by low friction and high precision from synthetic sapphire or ruby, jewel sensor bearings serve in small, high-accuracy devices. Their primary use is in scientific instruments and medical devices.
Ball bearings sit at the top of the volume ranking, with magnetic bearings climbing the fastest.
Technology:
Technological choices in sensor bearings are primarily dictated by the required measurement precision, environmental resilience, and integration complexity for the target application. Each technology offers distinct advantages for specific data acquisition needs.
- Inductive:Inductive sensors detect changes in magnetic fields, commonly integrated into a bearing ring to monitor speed, direction, and angular position. This technology forms the standard for industrial automation, providing robust performance in varied conditions.
- Optical:Optical sensors utilize light to detect precise rotational movements, offering high accuracy for angular position and speed. Their demand is accelerating in high-precision robotics, including automated guided vehicles (AGVs), for critical motion control.
- Capacitive:These sensors measure changes in capacitance to detect displacement, pressure, or other physical parameters with high sensitivity. Capacitive technology is often employed in specialized measurement instruments where fine resolution is critical.
- Piezoelectric:Piezoelectric sensors generate an electrical charge in response to mechanical stress, making them suitable for vibration and load monitoring. They are integrated into bearings for condition monitoring in heavy machinery.
- Ultrasonic:Ultrasonic sensors use sound waves to detect proximity, distance, or material flaws, offering non-contact measurement capabilities. These are explored for advanced diagnostic functions in complex industrial systems.
Inductive technology holds the largest market share, while optical sensors are gaining traction most rapidly.
Application:
The specific application dictates the performance requirements, durability, and certification needs for sensor bearings, influencing design and adoption rates. Different industries prioritize distinct operational parameters and data outputs from these integrated units.
- Manufacturing Machinery:Sensor bearings enable real-time condition monitoring and predictive maintenance for automated production lines and industrial robots. Demand is particularly strong in China's industrial clusters, which are upgrading manufacturing capabilities.
- Renewable Energy Systems:These systems require sensor bearings for monitoring drivetrain health in wind turbines and ensuring precise positioning for solar trackers. The EU's Corporate Sustainability Reporting Directive (CSRD) boosts their adoption in this sector.
- Aerospace Equipment:Sensor bearings in aerospace applications provide critical data for flight control systems and engine health monitoring, necessitating stringent FAA certifications. This segment demands verified reliability and performance assurance.
- Robotics:Compact sensor bearings provide precise angular position and speed data for motion control in collaborative robots and automated guided vehicles. High-precision robotics applications drive innovation in smaller, more integrated units.
- Marine Vessels:Sensor bearings monitor shaft rotation and propulsion system health in marine applications, ensuring operational efficiency and safety. They contribute to predictive maintenance strategies for ship engines.
Manufacturing machinery represents the largest end-use segment, with renewable energy systems demonstrating the steepest expansion trajectory.
End User:
The end-user landscape for sensor bearings reflects diverse procurement behaviors, technical integration capabilities, and service requirements. Each end-user type engages with sensor bearing suppliers differently, influencing supply chain dynamics.
- OEMs:Original Equipment Manufacturers integrate sensor bearings into their new machinery during the initial design and production phases. Many multinational OEMs are shifting toward single-source partnerships for fully integrated sensor units, simplifying their supply chains.
- Automation Providers:These companies specialize in designing and implementing automated systems for various industries, requiring advanced sensor bearings for control and data acquisition. They often seek wireless integration capabilities to streamline installation.
- Machine Shops:Machine shops typically purchase sensor bearings for replacement parts or for retrofitting existing equipment to improve performance. Cost-effectiveness remains a significant factor for these buyers.
- Research Labs:Research institutions utilize sensor bearings for developing new technologies, testing prototypes, and gathering precise data for scientific studies. They often require highly customized solutions for unique experimental setups.
- Aftermarket Service Providers:These providers supply replacement sensor bearings and offer maintenance services for installed equipment. They focus on product availability and ease of installation for their clients.
OEMs account for the largest volume of sensor bearing procurement, while automation providers are expanding their installations most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs in some regions are prompting a re-evaluation of manufacturing footprints, influencing the global distribution of sensor bearing production. This shift encourages investment in regions balancing advanced manufacturing capabilities with favorable regulatory environments. Operators are seeking efficiency gains through data-driven solutions across diverse industrial applications.
China
China's industrial automation clusters drive substantial demand for sensor bearings, particularly in manufacturing machinery upgrades. The country's GB standards for industrial equipment emphasize performance and reliability, influencing component selection. Major industrial hubs like the Yangtze River Delta are rapidly adopting predictive maintenance technologies for enhanced operational efficiency.
Germany
Germany, a hub for advanced manufacturing and renewable energy, requires sensor bearings for wind turbine drivetrains and high-precision robotics. The EU Machinery Directive and Corporate Sustainability Reporting Directive (CSRD) compel operators to invest in certified, data-rich components. Industrial regions such as Bavaria are integrating these intelligent units into automated production lines.
United States
The United States market sees significant demand from aerospace equipment and high-precision robotics applications. FAA imposes stringent requirements for sensor components in aviation, necessitating certified and reliable bearings. Clusters in the Pacific Northwest and Silicon Valley are at the forefront of integrating advanced sensor bearings into critical systems.
Japan
Japan's focus on advanced material science and precision manufacturing generates demand for sensor bearings in high-speed and high-accuracy machinery. JIS standards ensure the quality and longevity of industrial components, influencing procurement decisions. The Kanto and Chubu regions lead in developing and deploying these specialized bearings for sophisticated industrial equipment.
India
India's expanding manufacturing sector and renewable energy initiatives are driving the adoption of sensor bearings for machinery upgrades and wind turbine monitoring. The Bureau of Indian Standards (BIS) promotes quality and reliability in industrial components. Industrial corridors in Maharashtra and Gujarat are increasingly implementing predictive maintenance solutions with integrated sensors.
Sensor Bearing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-precision robotics and wireless integration capabilities. The sensor bearing market exhibits a tiered structure, with a few large integrated manufacturers alongside specialized technology providers. Strategic archetypes include full-system providers offering consistent product quality, customized solution specialists for demanding applications, and advanced material science innovators focusing on bearing longevity. Geographic expansion and technology licensing represent dominant competitive moves among these diverse players.
Within the full-system provider archetype, SKF exemplifies global manufacturing footprints and consistent product quality for multinational OEMs. Schaeffler Technologies AG & Co. KG occupies a position as a specialist in customized solutions for demanding applications in aerospace and industrial automation. NTN Corporation represents innovators focusing on advanced material science and bearing longevity, particularly in high-speed environments. These companies anchor different segments of the market, influencing product development and supply chain relationships through their distinct strategic approaches.
| Leading Market Players |
|---|
| SKF |
| Schaeffler Technologies AG & Co. KG |
| NTN Corporation |
| The Timken Company |
| NSK Corporation |
| JTEKT Corporation |
| ABB Group |
| Fersa Bearings |
| Mageba SA |
| Others |
Cost & Logistics Intelligence
Skilled engineering talent in specialized regions like Germany influences the premium pricing of high-precision sensor bearings, contrasting with more cost-effective units from high-volume manufacturing hubs. This divergence reflects labor-cost differentials and the value placed on advanced design capabilities within the market.
Pricing Analysis
Direct-to-OEM discounts significantly influence the per-unit transactional pricing model for sensor bearings. Price differentiation stems from certification levels, particularly FAA approvals for aerospace, and the degree of customization required for specialized applications. Pricing softness is evident in standard industrial segments due to substitution from external sensors, while high-performance, certified units maintain firm pricing. Machine shops typically exhibit higher price sensitivity compared to aerospace OEMs, who prioritize reliability over cost.
Supply Chain Analysis
Distribution channels for sensor bearings largely involve direct-to-OEM relationships, complemented by specialized distributors serving aftermarket demand. Supply originates primarily from manufacturing hubs in China, high-end engineering centers in Germany, and advanced material science facilities in Japan. Production relies on high-grade steel alloys, specific magnetic materials, and specialized microelectronics. Single-source vulnerability for fully integrated sensor units represents a structural supply chain risk, particularly for highly customized components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensor bearing market presents itself as a stable compounder, with steady growth driven by the continuous expansion of predictive maintenance adoption across industrial sectors. This foundational demand ensures consistent market expansion.
For Market Incumbents: Extend multi-functional sensing integration to combine speed, temperature, and vibration data into compact units. Invest in obtaining stringent certifications like FAA approval, which protects against lower-cost substitutes and new entrants lacking regulatory compliance. Defend market share by leveraging global manufacturing footprints and deepening R&D into advanced material science for bearing longevity.
For New Entrants and Emerging Players: Launch via specialized automation providers, targeting high-precision robotics and automated guided vehicles (AGVs) where compact units are critical. Focus on developing wireless integration capabilities using protocols like LoRaWAN to simplify installation and data collection in difficult-to-access equipment. The automation providers segment is most penetrable by offering solutions that streamline system integration and provide immediate data value.
For Investors and Strategic Acquirers: Industrial automation providers are the most active acquirers in this space, seeking to expand their integrated solutions portfolios. The market offers strong long-term viability over the next 5-10 years, driven by sustained Industry 4.0 initiatives and renewable energy expansion. Seek acquisition targets that possess unique intellectual property in optical sensing or wireless communication technologies. Increased M&A activity from large industrial conglomerates integrating sensor capabilities signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Wireless Communication Modules | Simplifies data collection for automation providers in remote or mobile equipment. |
| Pursue Aerospace Component Certification | Opens high-margin markets requiring verified reliability and performance data for FAA compliance. |
| Expand Multi-functional Sensor Integration | Reduces component count and wiring complexity for OEMs in heavy machinery. |
| Invest in Advanced Material Science R&D | Enhances bearing longevity and performance in high-speed industrial environments for NTN Corporation. |
| Establish Single-Source OEM Partnerships | Secures long-term procurement agreements and ensures consistent product quality for multinational OEMs. |
Research Approach
Bottom-up manufacturing machinery end-use modeling reconciled against top-down bearing supplier tracking forms the analytical core for this study. Primary interviews with plant engineers, OEM procurement leads, automation specialists, and maintenance directors provided qualitative insights. These insights were validated against secondary sources including industry association reports, SEC filings of public companies, and government trade statistics. This approach ensures robust data triangulation.
An input-output matrix underpins the quantitative forecast framework, mapping demand drivers to supply capabilities across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market forces. Key forecast inputs include global Industry 4.0 investment rates and renewable energy capacity additions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme geopolitical disruption or raw material price volatility. This forecast reflects current market assumptions regarding technological development and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
North America Acoustic Sensors Market