
 Industrial Combustion Control Components and Systems Market | 2026-2036
Industrial Combustion Control Components and Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Combustion Control Components and Systems Market Foresight
Modular system bundling is rebalancing procurement economics for large industrial buyers. ABB Group leverages its integrated automation portfolio to anchor turnkey combustion control deployments across European process industries. Siemens AG competes through deep domain expertise in burner management systems, while Honeywell International, Inc. sustains technology leadership in flame safeguard instrumentation.
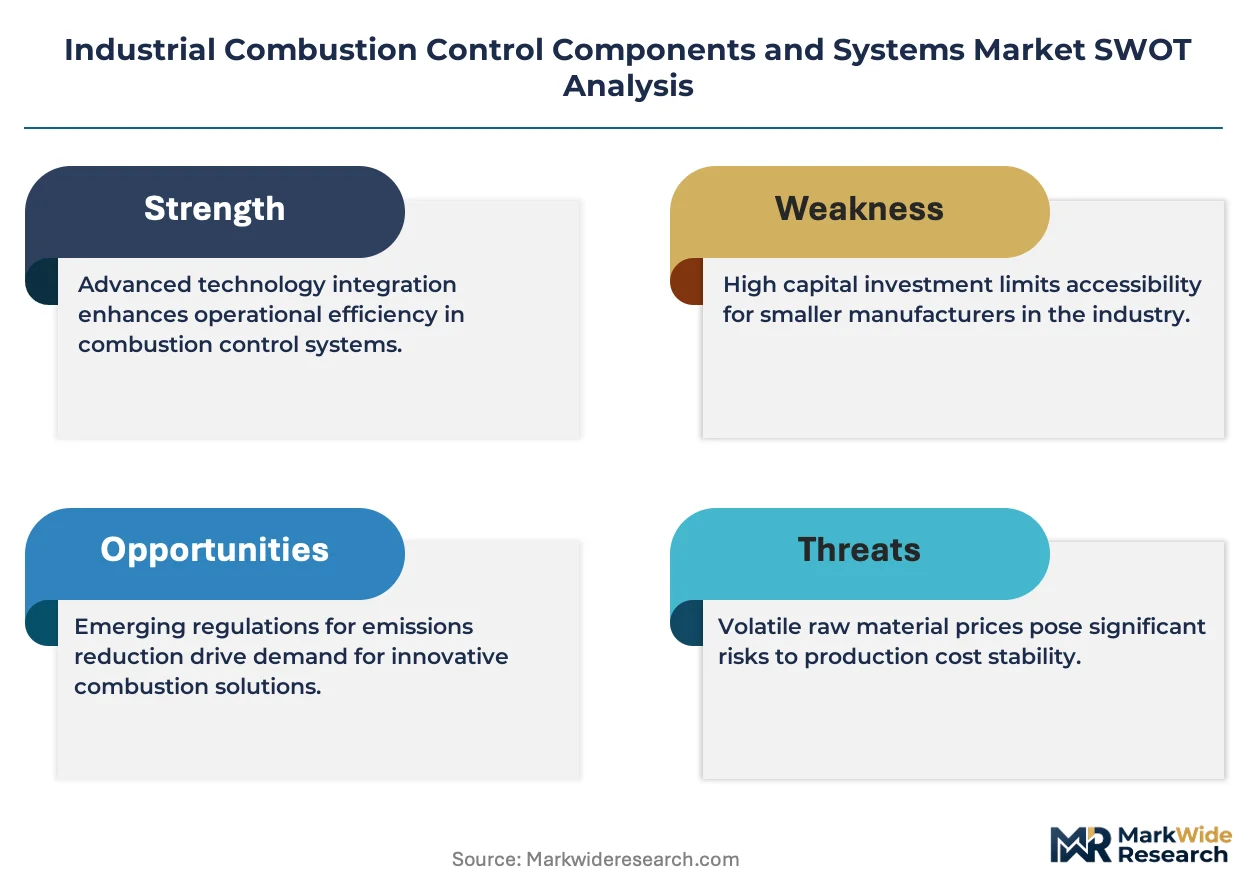
Industrial combustion control components and systems encompass fuel-air ratio regulators, flame detection sensors, programmable safety relays, and distributed control interfaces engineered to maintain thermal efficiency within plus-or-minus two percent deviation across variable load conditions. These assemblies enable precise oxidation management in boilers, furnaces, and incinerators while limiting NOx and CO formation. Burners and sensors command the largest installed base, though integrated solutions are capturing margin pools as facilities consolidate vendor relationships. Emission control technology is expanding fastest, driven by tightening stack gas limits and continuous emissions monitoring mandates.
The EPA enforces Maximum Achievable Control Technology standards for industrial boilers, compelling retrofit cycles that sustain replacement demand for valves and control panels. The EU Green Deal's Fit for 55 framework extends carbon border adjustments that favor combustion optimization investments in export-oriented manufacturing. Stakeholders must weigh captive maintenance capabilities against outsourced integrated service contracts as system complexity escalates.
Market Dynamics
Integrated combustion control architectures are displacing point-solution procurement as power generation operators and process manufacturers consolidate vendor relationships to reduce interface complexity and compliance risk.
Growth Catalysts
- EPA Maximum Achievable Control Technology:Boiler retrofit mandates in the United States sustain replacement demand for valves, sensors, and distributed control interfaces across aging industrial infrastructure.
- Steel and cement sectors:Carbon-intensive industries face EU carbon border adjustment pressures, compelling investments in burner optimization and continuous emissions monitoring systems.
- India's PLI scheme:Production-linked incentives for domestic manufacturing scale are accelerating local assembly of flame detection sensors and programmable safety relays.
Market Restraints
- Specialized alloy supply:Inconel and Hastelloy price volatility for high-temperature valve components compresses margins for control system integrators.
- Technical skill scarcity:Combustion tuning expertise resides with a shrinking cohort of veteran technicians, constraining deployment velocity for advanced burner management systems.
- Legacy asset lock-in:Decades-old boiler installations in North American manufacturing bases resist control architecture upgrades due to mechanical incompatibility.
Strategic Opportunities
- Indonesia power expansion:State-owned utility procurement of integrated combustion control systems for new coal and gas-fired capacity offers white-space penetration for bundled solution providers.
- AI-driven predictive maintenance:Machine learning convergence with flame safeguard instrumentation enables condition-based service contracts that capture recurring revenue streams.
- EU Green Deal industrial decarbonization benchmarks:Fit for 55 framework incentives favor hydrogen-ready burner retrofits in export-oriented German and Dutch chemical clusters.
Industry Challenges
- BIS certification timelines:Indian Bureau of Standards approval cycles for imported safety relays extend project delivery schedules by six to twelve months.
- Multi-vendor integration complexity:Facilities blending ABB, Siemens, and Honeywell subsystems encounter protocol mismatches in fuel-air ratio control loops.
- Combustion engineering talent pipeline:Universities in Europe and North America have shuttered specialized thermal engineering programs, narrowing recruitment pools for system commissioning roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Combustion Control Components and Systems Market |
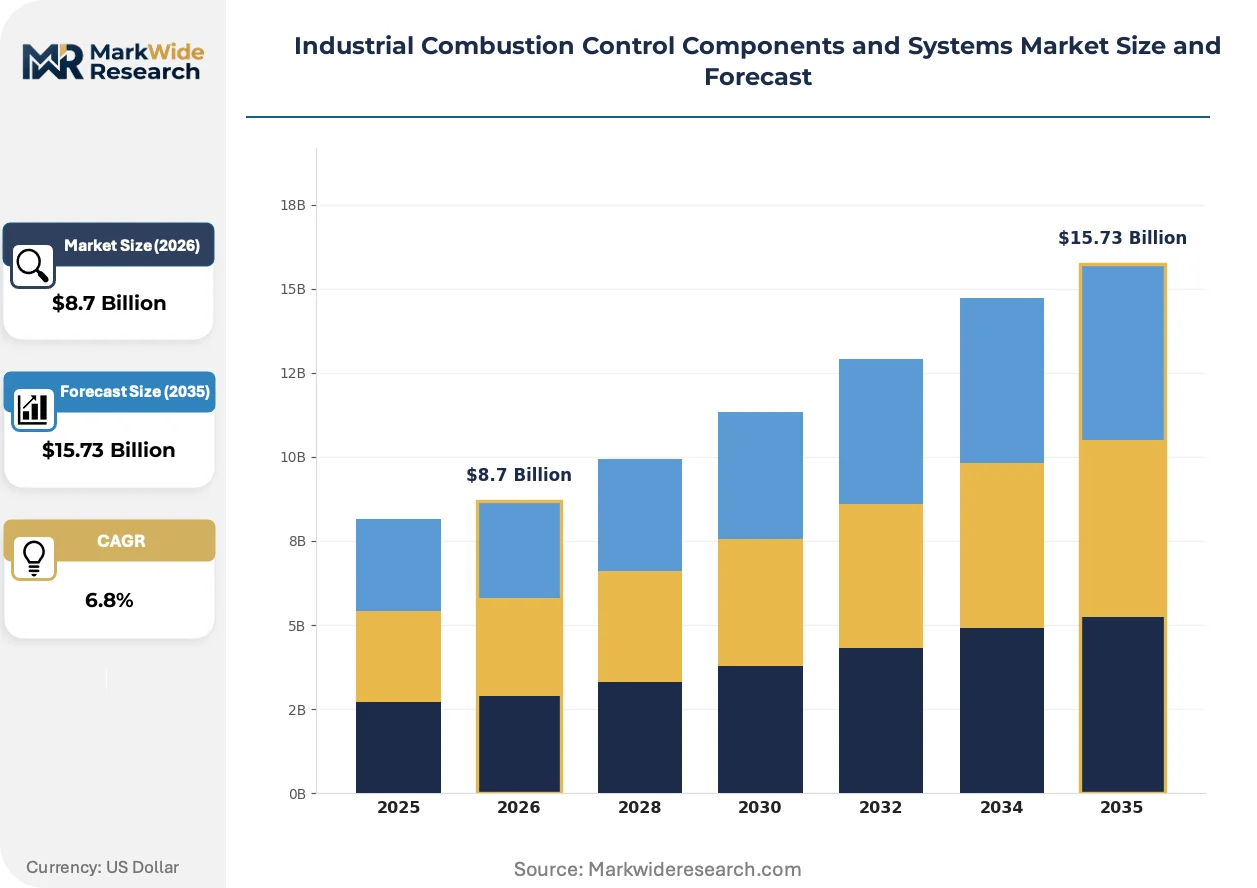
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burners, Sensors, Valves, Control Panels Technology: Combustion Optimization, Emission Control, Automated Systems, Integrated Solutions End User: Manufacturing, Power Generation, Oil & Gas, Petrochemical Application: Process Heating, Waste Management, Energy Generation, Heating Systems |
| Companies Covered | ABB Group, Emerson Electric Company, Honeywell International, Inc., Rockwell Automation, Inc., Siemens AG, Alfa Laval AB, Yokogawa Electric Corporation, Mitsubishi Heavy Industries Ltd., Applied Control Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Combustion Control Components and Systems Market Shifts & Advancements
Digital twin modeling and edge-computing architectures are compressing commissioning timelines and enabling real-time combustion optimization that was previously confined to laboratory conditions.
Optical flame detection using ultraviolet and infrared sensor fusion is overtaking traditional flame rod and thermocouple arrangements in hazardous environment applications. Offshore platform operators and chemical process facilities are adopting these solid-state systems for faster response and reduced maintenance. The technology is overtaking electromechanical alternatives in safety-critical installations where false-trip tolerance approaches zero.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based fire suppression is redirecting capital toward inert gas and water mist systems integrated with combustion control safety loops. Industrial boiler operators must revalidate flame safeguard logic to accommodate modified suppression trigger thresholds. German and Polish manufacturing clusters are front-running compliance through preemptive burner management system upgrades.
Long-term service agreements are supplanting transactional component sales as the dominant commercial model for large combustion control deployments. Power generation utilities in Thailand and Vietnam are bundling fifteen-year maintenance contracts with initial system procurement, transferring operational risk to original equipment providers. This reconfiguration concentrates margin capture with vendors possessing captive service networks.
Industrial Combustion Control Components and Systems Market Segmentation
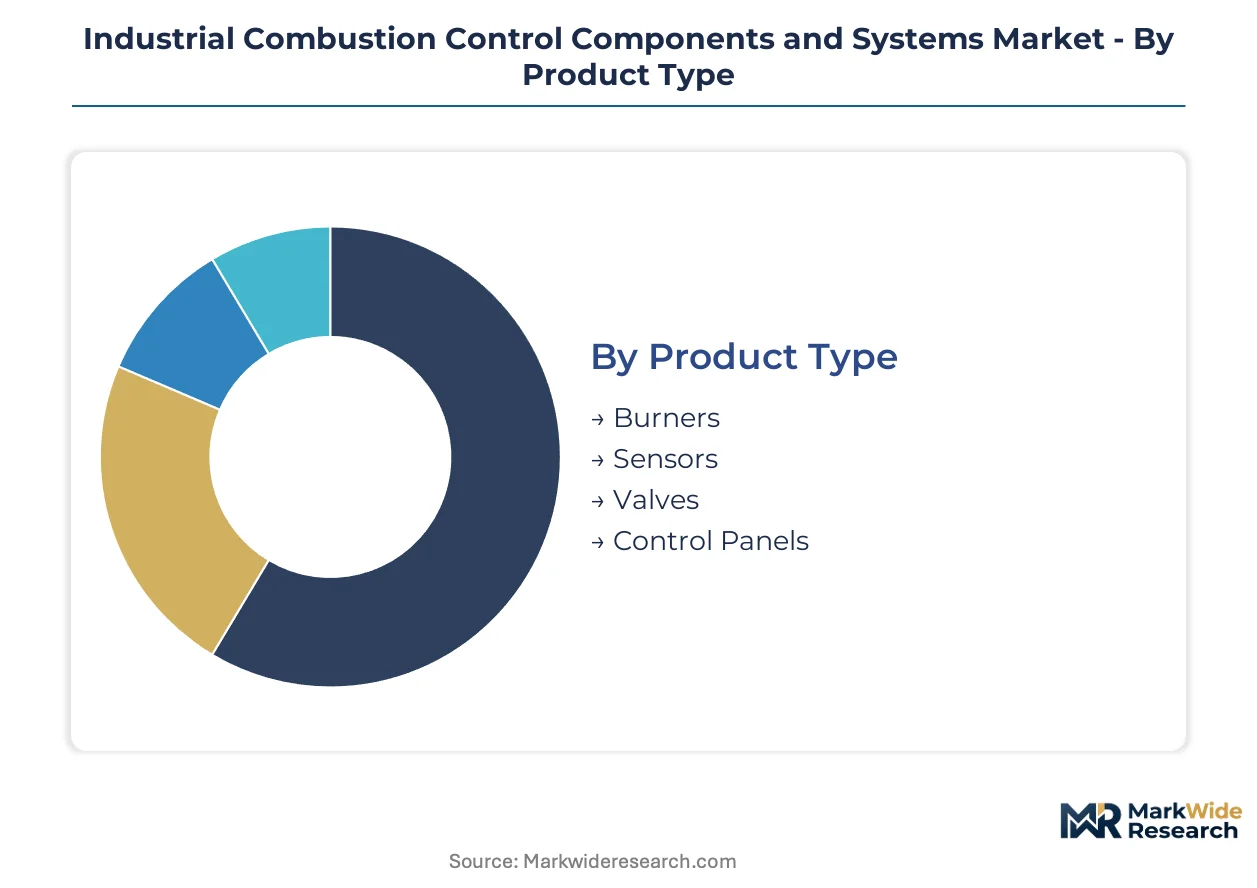
Segmentation in combustion control markets reveals distinct procurement patterns across technology maturity levels and regulatory exposure. Buyers in carbon-intensive sectors prioritize integrated architectures over point solutions, while power operators emphasize service bundling and long-term maintenance contracts.
Product Type:
Capital deployment intensity and replacement cycle frequency separate buyers in this category, with process manufacturers favoring durable components and utilities seeking modular upgrade paths.
- Burners:High-temperature alloy assemblies regulate fuel-air mixing ratios across variable thermal loads. Steel mills in Germany and cement kilns in India drive procurement volume as EU carbon border adjustments and BIS certification protocols force efficiency retrofits.
- Sensors:Ultraviolet-infrared flame detection arrays replace electromechanical rods in hazardous environments. Offshore platforms in the North Sea and chemical complexes in Rotterdam adopt solid-state configurations for faster response and reduced false-trip incidence.
- Valves:Inconel and Hastelloy pressure regulators manage fuel flow precision in high-temperature zones.
- Control Panels:Distributed interfaces integrate burner management logic with facility-wide automation networks.
Volume sits with Burners; growth tilts toward Sensors.
Technology:
Regulatory stringency and emissions liability exposure create divergent adoption timelines across technology tiers.
- Integrated Solutions:Unified architectures consolidate vendor relationships and reduce interface complexity. Power generation operators in Thailand and Vietnam bundle fifteen-year service contracts with initial procurement, transferring operational risk to equipment providers.
- Emission Control:Continuous monitoring systems and NOx reduction technologies address tightening stack gas limits. German chemical clusters front-run EU F-Gas Regulation compliance through preemptive burner management upgrades.
- Combustion Optimization:Real-time fuel-air ratio adjustment algorithms maximize thermal efficiency.
- Automated Systems:Programmable safety relays execute flame safeguard sequences with deterministic response timing.
Revenue concentrates with Integrated Solutions; Emission Control climbs the fastest as decarbonization mandates tighten.
End User:
Process intensity and carbon exposure dictate specification requirements and procurement authority structures.
- Power Generation:Coal and gas-fired capacity expansion in Indonesia drives procurement of turnkey combustion control architectures. State-owned utilities specify bundled solutions with captive maintenance networks to mitigate operational risk.
- Manufacturing:Export-oriented facilities face EU carbon border adjustment pressures compelling burner optimization investments. Steel and cement sectors in Poland and the Netherlands prioritize hydrogen-ready retrofits.
- Oil & Gas:Refinery and upstream operators require explosion-proof flame detection in hazardous zone classifications.
- Petrochemical:Cracker furnaces and reformer units demand precise temperature uniformity across extended reaction zones.
Installed base favors Power Generation; Manufacturing captures the steepest expansion trajectory as carbon pricing extends.
Application:
Thermal uniformity requirements and emissions visibility determine system complexity and monitoring intensity.
- Process Heating:Industrial furnaces and kilns require plus-or-minus two percent temperature deviation control across variable load conditions. Metal treatment facilities in Japan and glass manufacturers in Italy deploy advanced burner management to maintain product quality specifications.
- Energy Generation:Utility boilers sustain baseload and cycling operations with emissions-compliant combustion profiles. EPA Maximum Achievable Control Technology mandates drive retrofit demand across aging US industrial infrastructure.
- Waste Management:Incineration systems destroy hazardous byproducts while capturing thermal energy.
- Heating Systems:Commercial and district heating networks prioritize reliability and remote diagnostics capability.
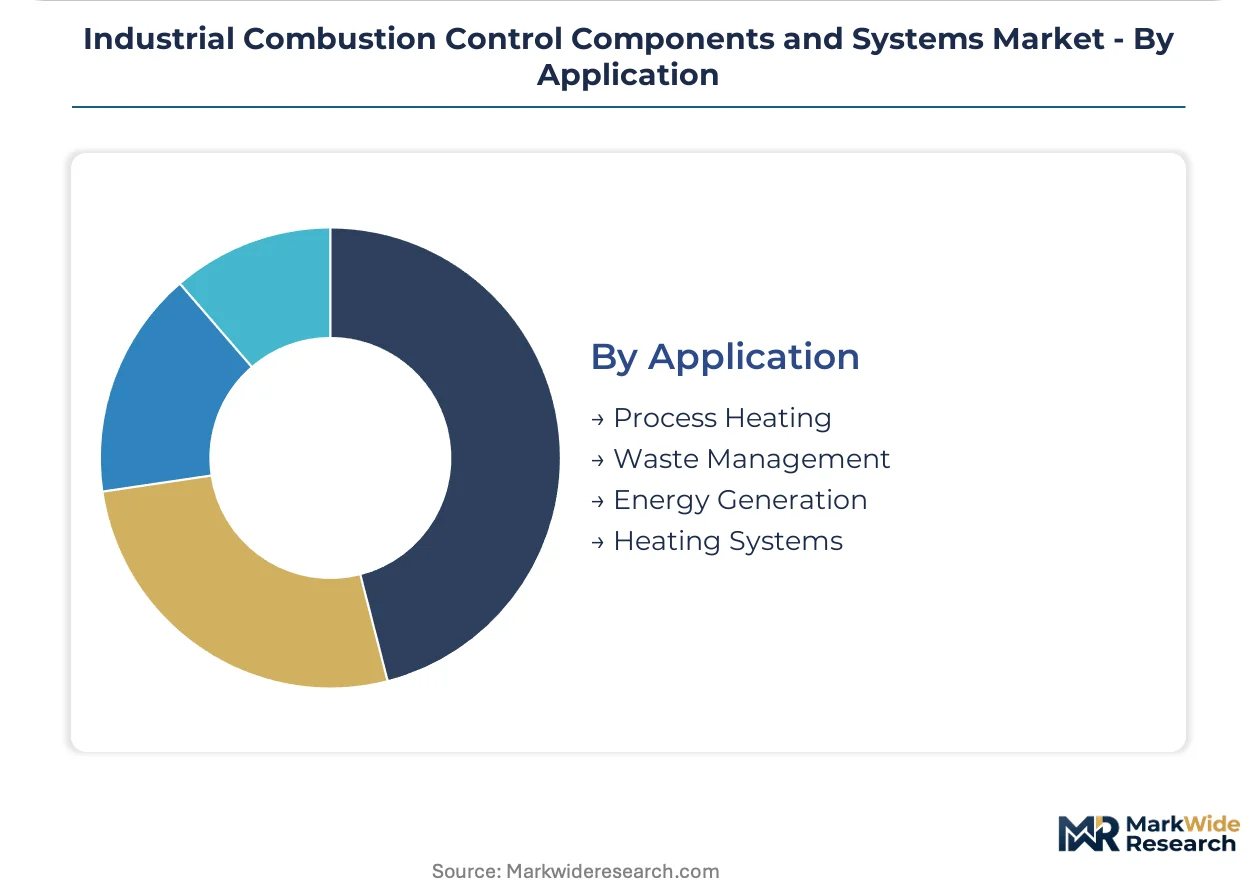
Process Heating dominates current procurement; Energy Generation gains share fastest as grid decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions and China's Yangtze River Delta special economic zones concentrate combustion control procurement through state-backed manufacturing incentives. Tax-advantaged industrial corridors in Germany and Indonesia's Batang Integrated Industrial Estate drive similar clustering effects.
United States
Power utilities and petrochemical refineries sustain replacement demand for burner management systems across aging Gulf Coast infrastructure. EPA Maximum Achievable Control Technology standards compel retrofit cycles for industrial boilers in Texas and Louisiana. Houston's energy corridor hosts concentrated procurement of flame safeguard instrumentation for offshore platform applications.
Germany
Export-oriented chemical clusters face EU carbon border adjustment pressures requiring hydrogen-ready burner retrofits. The EU F-Gas Regulation's hydrofluorocarbon phasedown redirects capital toward integrated safety loops in BASF's Ludwigshafen complex and Bayer's Leverkusen operations. North Rhine-Westphalia's steel sector leads preemptive compliance investments.
India
BIS certification protocols and PLI scheme incentives accelerate domestic assembly of flame detection sensors and programmable safety relays. Reliance Industries' Jamnagar refinery and Tata Steel's Jamshedpur operations anchor demand for integrated combustion architectures. Gujarat's Dahej PCPIR zone concentrates new capacity deployment.
Indonesia
State-owned utility PLN's procurement of integrated systems for new coal and gas-fired capacity creates white-space opportunities for bundled solution providers. National energy security programs prioritize captive maintenance networks to mitigate operational risk. The Batang Integrated Industrial Estate in Central Java concentrates metallurgical and power generation investments.
Japan
METI's industrial decarbonization roadmaps drive precision combustion investments in steel and glass manufacturing. JIS-certified safety systems dominate procurement specifications for Tokyo Bay petrochemical complexes. Chiba and Kawasaki industrial zones sustain demand for advanced burner management in cracker furnace applications.
Industrial Combustion Control Components and Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered technology segments. The market structure concentrates margin capture with vendors possessing integrated automation portfolios and captive service networks. Three archetypes dominate: full-stack automation providers, combustion-specific engineering houses, and component-specialist fabricators. Strategic moves center on long-term service contract bundling and AI-driven predictive maintenance capability acquisition.
Among diversified automation conglomerates, ABB Group and Siemens AG exemplify full-stack positioning through turnkey deployment capabilities. Honeywell International, Inc. anchors the instrumentation-specialist tier with flame safeguard expertise. These three occupy positions that reward vertical integration depth and multi-decade service relationships over transactional component sales.
| Leading Market Players |
|---|
| ABB Group |
| Emerson Electric Company |
| Honeywell International, Inc. |
| Rockwell Automation, Inc. |
| Siemens AG |
| Alfa Laval AB |
| Yokogawa Electric Corporation |
| Mitsubishi Heavy Industries Ltd. |
| Applied Control Engineering, Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in German valve fabrication and Japanese sensor assembly anchor tier-two supply tiers, disciplining spot-market pricing through captive alloy inventories and multi-year OEM contracts that resist volatility.
Pricing Analysis
Margin tightening in standard-grade burner assemblies reflects Inconel and Hastelloy price volatility transmitted from specialty alloy foundries. Project-based pricing dominates integrated system procurement, with premium differentiation resting on SIL-certified safety ratings and fifteen-year service bundling. Cost-down pressure accelerates in economy-tier components as Indian PLI-scheme entrants scale domestic flame relay assembly. Power generation utilities exhibit lowest price sensitivity due to operational risk transfer requirements, while independent process manufacturers negotiate hardest on upfront capital outlays.
Supply Chain Analysis
Combustion engineering talent scarcity in North Rhine-Westphalia and Osaka industrial corridors constrains final assembly velocity for complex burner management systems. Supply concentrates in Germany for high-precision valves, Japan for optical sensor arrays, and India for programmable safety relays. Raw material flows draw from nickel alloy producers in Finland, rare-earth element processors in China, and ceramic substrate fabricators in South Korea. Single-source vulnerability sits with EU F-Gas Regulation compliance components facing redirected capacity. Distribution runs through authorized system integrator networks with captive commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races in this market center on captive service network scale, as fifteen-year maintenance contracts displace transactional component sales and lock in margin pools across successive upgrade cycles.
For Market Incumbents: Deploy AI-driven predictive maintenance capabilities to anchor recurring revenue streams and raise switching costs for power utility accounts. Consolidate distributor relationships in Southeast Asia to preempt emerging entrant channel access. Counter technical skill scarcity through apprenticeship partnerships with shuttered European thermal engineering programs. For New Entrants and Emerging Players: The premium-to-economy price gap in flame detection sensors offers entry traction through BIS-certified domestic assembly in Gujarat PCPIR zones. Target Indonesian state utility procurement cycles with bundled offerings that undercut full-stack automation providers on service response time. Pursue white-label partnerships with German valve specialists lacking Asian maintenance presence. For Investors and Strategic Acquirers: Distressed-cycle entries favor combustion-specific engineering houses with stranded order books in EU carbon border adjustment-exposed steel clusters. Long-term viability hinges on hydrogen-ready burner retrofit capabilities across the next decade. Watch EU F-Gas Regulation enforcement intensity as inflection signal for safety loop upgrade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Temperature Alloys | Captive Inconel supply secures margin protection against commodity volatility for German valve fabricators. |
| Long-Term Service Agreement Bundling | Fifteen-year maintenance contracts with Thai and Vietnamese utilities transfer operational risk to equipment providers. |
| AI-Driven Predictive Maintenance Platform | Machine learning convergence with Honeywell flame safeguard instrumentation enables condition-based revenue capture. |
| Joint Venture in Indian PCPIR Zones | Local assembly partnerships with Reliance Industries anchor BIS-certified supply for domestic refinery demand. |
| Hydrogen-Ready Burner Retrofit Program | Preemptive compliance investments in BASF Ludwigshafen complex front-run EU Green Deal industrial decarbonization benchmarks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary fieldwork incorporated structured interviews with plant maintenance directors, OEM procurement teams at boiler manufacturers, aftermarket service heads, and combustion engineering specialists across European process industries. Secondary sources included EPA Maximum Achievable Control Technology enforcement databases, EU ETS transaction registries, BIS certification publication records, and SEC 10-K disclosures from listed automation conglomerates. Bottom-up installation base counts were reconciled against top-down energy sector capex allocations.
Data-stream reconciliation across shipment volumes, utility procurement announcements, and regulatory compliance deadlines shaped the analytical framework. Segmentation modeling spanned product architecture, technology tier, end-user industry, application thermal intensity, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical retrofit cycle patterns and announced capacity expansion timelines. Hydrogen-ready burner adoption curves and AI-enabled predictive maintenance penetration rates served as industry-specific forecast inputs across the projection horizon.
Inputs from EPA enforcement databases and EU ETS registries were available through the study window; gaps in privately held utility maintenance contract terms introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and alloy price trajectory stability. Material deviation in EU carbon border adjustment implementation timelines or Indian PLI scheme renewal terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
United States Pressure Transmitter Market