
 North America Bulk Acoustic Wave Sensors Market | 2026-2036
North America Bulk Acoustic Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bulk Acoustic Wave Sensors Market Analytics
FCC spectrum reallocation is consolidating the cost-of-entry calculus for new Bulk Acoustic Wave sensor suppliers. Texas Instruments leverages captive fabrication facilities to sustain pricing power across defense and telecom verticals. Qualcomm anchors its position through R&D intensity in RF filter architectures for 5G infrastructure. Honeywell competes by dominating temperature-stable resonator designs for avionics applications.
Bulk Acoustic Wave sensors employ piezoelectric thin films—typically aluminum nitride or zinc oxide—deposited between electrode layers to excite acoustic resonance at frequencies from hundreds of megahertz to several gigahertz, serving precision timing, frequency control, and mass sensing functions in electronic systems. The Film product category leads volume shipments due to compatibility with standard CMOS foundry processes, while the Single Crystal segment commands premium positioning in satellite and military applications where phase noise specifications are tightest. Healthcare applications are expanding fastest among end-use categories, driven by point-of-care diagnostic platforms requiring picogram-scale mass resolution.
NHTSA vehicle-to-everything mandates and FDA medical device electromagnetic compatibility standards are tightening qualification protocols for sensor suppliers seeking automotive and clinical market access. The EPA's hazardous substance restrictions for electronic waste streams are reshaping material selection in piezoelectric layer deposition. Stakeholders must monitor how dual-use export control classifications evolve around resonator frequency thresholds.
Market Dynamics
FCC spectrum reallocation is compressing design cycles for resonator architectures while defense procurement prioritizes temperature-stable timing devices. This dual pressure is forcing suppliers to reconcile commercial CMOS compatibility with military-grade phase noise specifications.
Growth Catalysts
- Defense procurement expansion:Aerospace contractors are accelerating precision timing device orders for next-generation avionics platforms. Pentagon requirements for frequency stability in contested electromagnetic environments are tightening.
- 5G infrastructure buildout:FCC mandates for higher-frequency spectrum utilization are pulling RF filter demand toward bulk acoustic wave architectures. Telecom equipment manufacturers require resonators operating above 3 GHz for millimeter-wave backhaul.
- Point-of-care diagnostic platforms:FDA electromagnetic compatibility standards for portable medical devices are validating picogram-scale mass sensing applications. Clinical instrument makers are integrating film-type resonators into handheld biosensors.
Market Restraints
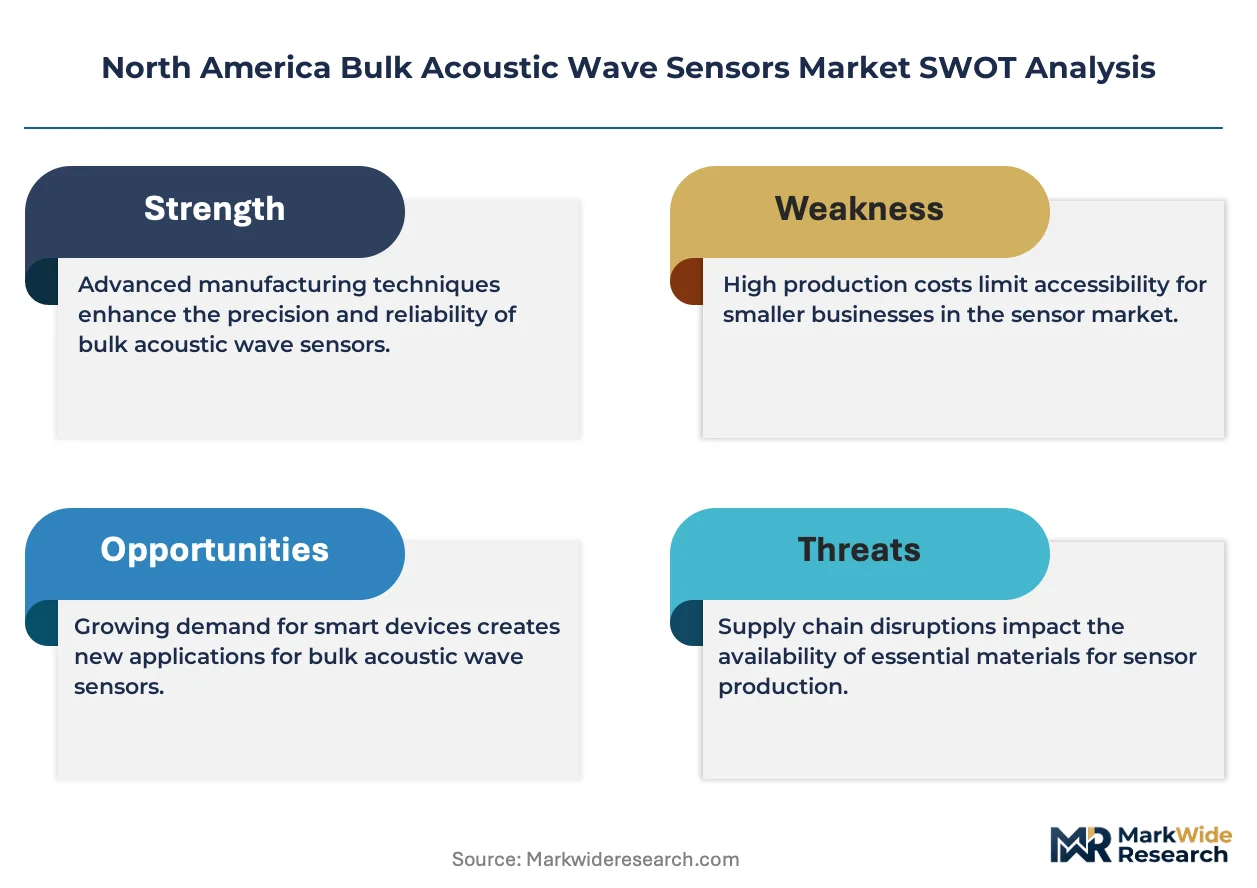
- Aluminum nitride supply concentration:High-purity piezoelectric thin film deposition relies on a concentrated supplier base in East Asian specialty chemical markets. Input cost volatility affects foundry economics for CMOS-integrated resonators.
- Dual-use export controls:Resonator frequency thresholds above 1.5 GHz trigger ITAR and EAR classification reviews. Licensing friction delays commercialization of satellite-grade single crystal devices.
- MEMS oscillator substitution:Silicon-based timing alternatives are capturing cost-sensitive consumer electronics sockets. Bulk acoustic wave sensors face displacement in applications where phase noise tolerance permits relaxed specifications.
Strategic Opportunities
- Texas instrumentation corridor expansion:Defense and energy sector clusters in Houston and Dallas-Fort Worth are concentrating demand for harsh-environment resonators. Localized fabrication partnerships reduce qualification timelines for oilfield instrumentation.
- Vehicle-to-everything integration:NHTSA mandates for connected vehicle communications are opening automotive timing device sockets. Bulk acoustic wave sensors offer frequency stability advantages over crystal oscillators in underhood thermal conditions.
- Scandium-doped aluminum nitride:Piezoelectric coefficient enhancement through dopant engineering is electrifying coupling efficiency in next-generation RF filters. Foundry partnerships with compound semiconductor facilities are accelerating process maturation.
Industry Challenges
- Phonon scattering physics expertise:The intersection of acoustic wave mechanics and thin film deposition requires specialized talent pools concentrated in national laboratory and university research centers. Workforce development lags commercial demand.
- Automotive AEC-Q200 qualification:Temperature cycling and mechanical shock testing for underhood resonator modules extends development timelines by 18-24 months. Tier-1 suppliers demand failure rate data that exceeds current field histories.
- Legacy frequency control integration:Defense platform refresh cycles must accommodate backward compatibility with quartz crystal architectures. Hybrid system designs complicate power budget and board space optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bulk Acoustic Wave Sensors Market |
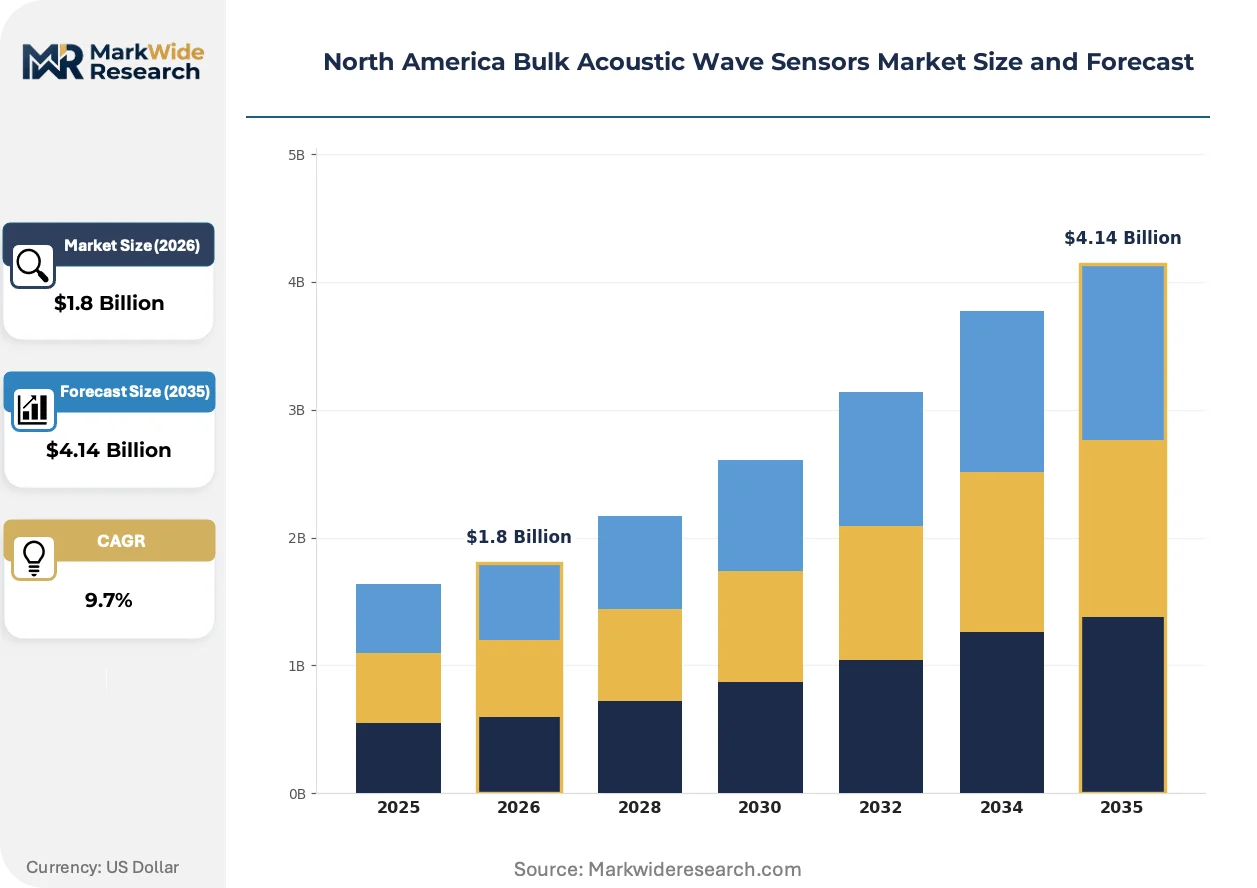
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Piezoelectric, Film, Composite Application: Healthcare, Environmental Monitoring, Industrial Automation, Consumer Electronics End User: Manufacturers, Research Institutions, Government Agencies, Service Providers Technology: Surface Acoustic Wave, Bulk Acoustic Wave, Optical, Wireless |
| Companies Covered | Texas Instruments, Qualcomm, Honeywell, Broadcom, Qorvo, Skyworks Solutions, NXP Semiconductors, Infineon Technologies, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bulk Acoustic Wave Sensors Market Evolving Landscape
Resonator architecture evolution is compressing the boundary between commercial CMOS economics and military performance specifications. Suppliers are converging on platform designs that serve dual-use applications without duplicate qualification tracks.
Scandium-doped aluminum nitride piezoelectric films are electrifying electromechanical coupling coefficients in bulk acoustic wave resonators. RF filter manufacturers for 5G infrastructure are adopting this material platform at accelerated qualification paces. The structural consequence is compression of insertion loss margins that previously separated premium military specifications from commercial telecom products.
NHTSA vehicle-to-everything mandates are forcing resonator suppliers to develop automotive-grade temperature compensation architectures. The regulatory pressure is industrializing AEC-Q200 testing protocols that were previously confined to consumer electronics timing devices. Heavy-duty truck and electric vehicle powertrain segments are responding with procurement specifications that prioritize thermal stability over absolute frequency precision.
Defense prime contractors are consolidating vendor bases around suppliers offering captive thin film deposition and in-house packaging. The channel disruption is displacing merchant resonator distributors from aerospace and satellite procurement workflows. California's semiconductor corridor and Arizona defense manufacturing clusters are exhibiting the most visible concentration of direct OEM-fabricator relationships.
North America Bulk Acoustic Wave Sensors Market Segmentation
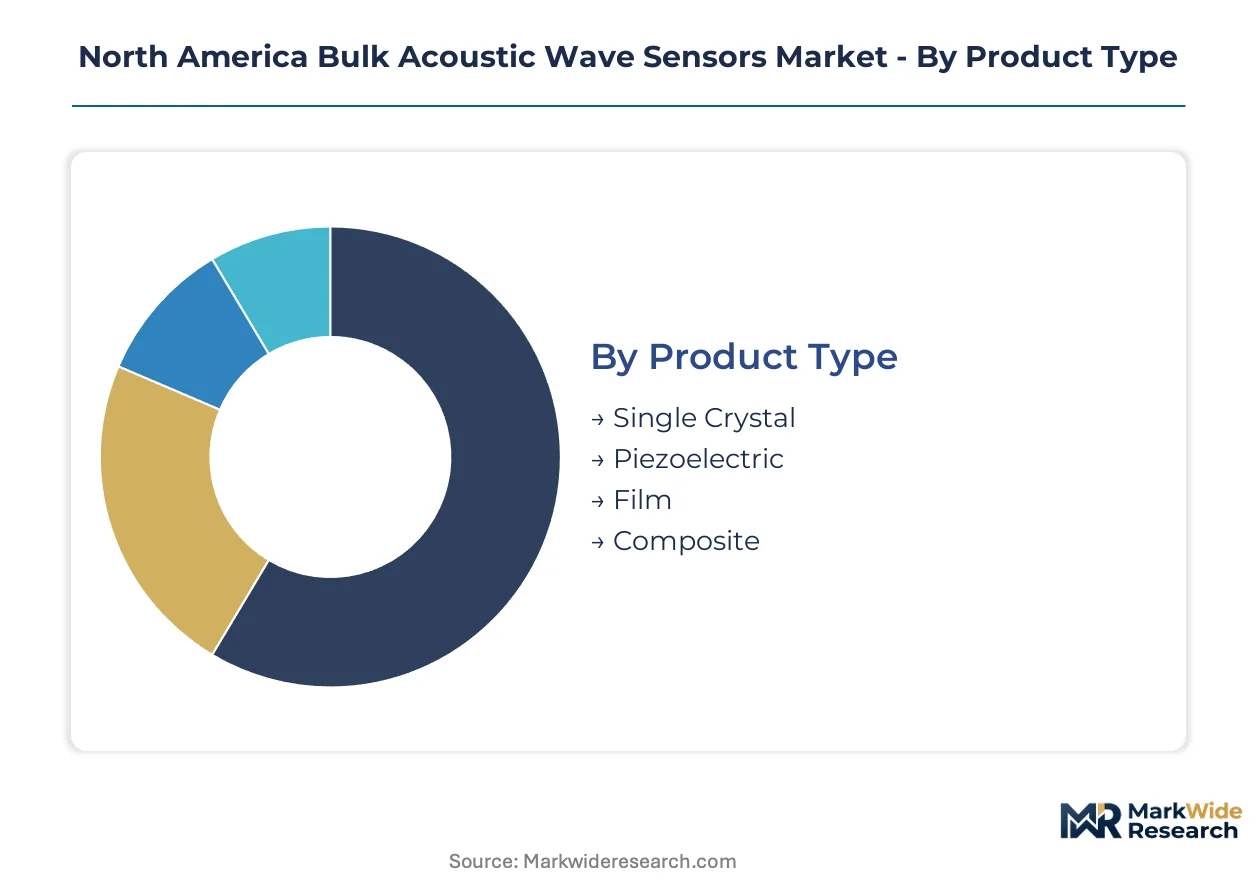
Segmentation in the North America Bulk Acoustic Wave Sensors Market reveals how piezoelectric material choices and application requirements fragment procurement patterns across defense, telecom, and healthcare verticals. Suppliers must align fabrication capabilities with distinct qualification protocols governing each segment.
Product Type:
Thin film deposition expertise concentrates in California's semiconductor corridor and Texas defense manufacturing clusters, creating geographic supply asymmetries that shape customer access.
- Film:Aluminum nitride or zinc oxide layers deposited between electrode pairs enable CMOS-compatible fabrication at frequencies from hundreds of megahertz to several gigahertz. California foundries serving Qualcomm and Broadcom dominate volume production for 5G RF filters, though aluminum nitride supply concentration in East Asian specialty chemical markets introduces input cost volatility.
- Single Crystal:Quartz or lithium niobate substrates deliver the lowest phase noise specifications for precision timing applications. Pentagon procurement for contested electromagnetic environments drives demand through Texas aerospace contractors, with ITAR classification above 1.5 GHz limiting supplier pools.
- Piezoelectric:Ceramic-based resonators balance cost against temperature stability for industrial instrumentation sockets.
- Composite:Hybrid material stacks combining piezoelectric films with passive substrates serve niche harsh-environment applications.
Film absorbs the bulk of installed capacity; Single Crystal is expanding most quickly.
Application:
End-use demand stratifies sharply across cost tiers, with clinical and defense applications commanding premium pricing against commoditized consumer electronics sockets.
- Healthcare:Point-of-care diagnostic platforms exploit picogram-scale mass resolution in film-type resonators for handheld biosensors. FDA electromagnetic compatibility standards validate clinical integration, with procurement concentrating in Boston and San Diego medical device corridors.
- Industrial Automation:Harsh-environment resonators for oilfield instrumentation and process control prioritize temperature stability over absolute frequency precision. Houston and Dallas-Fort Worth energy sector clusters drive qualification requirements.
- Environmental Monitoring:Low-power wireless sensor networks deploy bulk acoustic wave devices for remote air and water quality sensing.
- Consumer Electronics:MEMS oscillator substitution erodes bulk acoustic wave sensor share in cost-sensitive timing applications where phase noise tolerance permits relaxed specifications.
Healthcare commands the steepest expansion trajectory; Industrial Automation anchors current revenue concentration.
End User:
Customer type determines contracting structures, with government procurement mandating captive fabrication visibility while merchant suppliers serve research and commercial manufacturing segments.
- Manufacturers:Telecom equipment makers and automotive tier-1 suppliers integrate resonators into 5G infrastructure and vehicle-to-everything communication modules. NHTSA mandates for connected vehicle timing devices are opening new sockets in Detroit and Tennessee automotive corridors.
- Government Agencies:Pentagon and NASA procurement prioritizes temperature-stable timing for satellite and avionics platforms. Defense prime contractors are consolidating vendor bases around suppliers offering in-house thin film deposition and packaging.
- Research Institutions:National laboratories and university centers advance scandium-doped aluminum nitride process maturation.
- Service Providers:Calibration and maintenance contractors support installed base of precision timing equipment.
Manufacturers absorb the bulk of installed capacity; Government Agencies are expanding procurement fastest.
Technology:
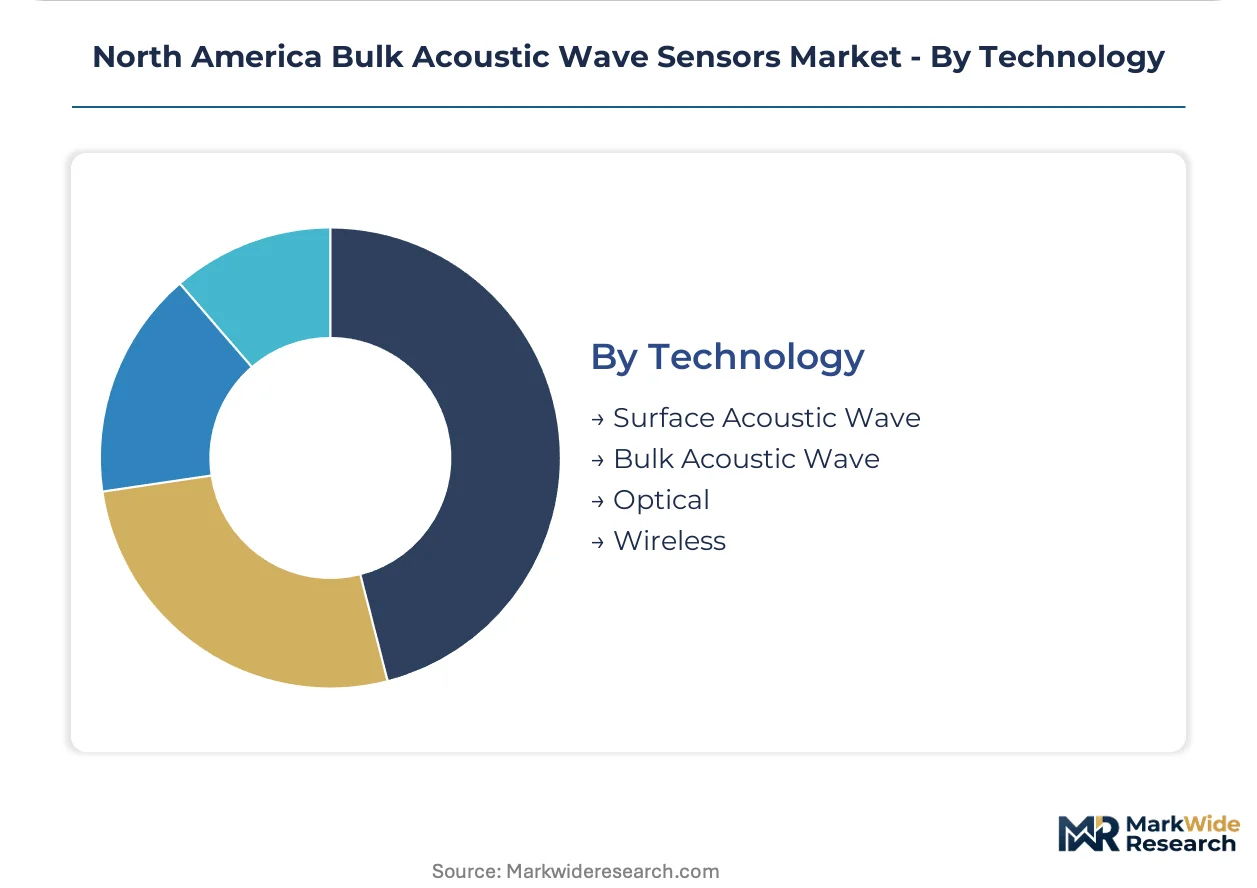
Technology selection reflects the fundamental physics governing acoustic wave excitation, with bulk acoustic wave architectures gaining share in high-frequency applications above 3 GHz.
- Bulk Acoustic Wave:Piezoelectric thin films between electrodes excite thickness-extensional resonance modes. FCC spectrum reallocation toward millimeter-wave backhaul is pulling RF filter demand toward this architecture for 5G infrastructure above 3 GHz.
- Surface Acoustic Wave:Interdigital transducers on piezoelectric substrates serve lower-frequency filtering applications with established cost structures.
- Optical:Photonic integration offers immunity to electromagnetic interference for specialized sensing applications.
- Wireless:RF communication modules incorporating acoustic wave reference oscillators enable distributed sensor networks.
Bulk Acoustic Wave absorbs the bulk of installed capacity; Optical is climbing the fastest in emerging sensing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 74 in El Paso concentrates cross-border resonator assembly operations, while California's semiconductor corridor draws the bulk of thin film deposition investment through state R&D tax credits.
United States
Pentagon procurement for contested electromagnetic environments and FCC spectrum reallocation toward millimeter-wave backhaul drive dual-use demand. ITAR classification above 1.5 GHz limits supplier pools for satellite-grade devices. California's semiconductor corridor hosts Qualcomm and Broadcom fabrication partnerships, while Texas aerospace contractors in Dallas-Fort Worth accelerate precision timing orders.
Canada
Defense procurement through the Department of National Defence prioritizes temperature-stable timing for Arctic surveillance platforms. Health Canada's electromagnetic compatibility standards for medical devices validate clinical resonator integration. Ontario's Waterloo-Toronto tech corridor concentrates RF filter R&D partnerships with US foundries.
Mexico
Automotive tier-1 suppliers near Mexico City integrate resonators for NHTSA-aligned vehicle-to-everything communication modules. The Secretariat of Economy's maquiladora program reduces duty exposure for resonator packaging operations. Baja California's electronics assembly clusters specialize in CMOS-compatible resonator module integration for telecom equipment.
North America Bulk Acoustic Wave Sensors Market Competitive Landscape
California producers anchor one tier; Texas specialists hold defense-aerospace positioning. The vendor base concentrates around three structural groups: integrated semiconductor conglomerates with captive fabrication, defense prime contractor subsidiaries with ITAR-cleared facilities, and merchant foundry operators serving fabless design houses. Consolidation pressures favor M&A activity among mid-scale resonator specialists and strategic partnerships between aluminum nitride suppliers and CMOS foundries.
Among US-based fabricators, Texas Instruments, Qualcomm, and Honeywell exemplify distinct competitive archetypes. Texas Instruments occupies a position defined by captive fabrication depth across defense and telecom verticals. Qualcomm represents R&D-intensive positioning in RF filter architectures for 5G infrastructure buildout. Honeywell sits within the temperature-stable resonator specialization tier for avionics applications. These three entities collectively illustrate how geographic clustering, regulatory clearance status, and material science capabilities segment competitive positioning in precision timing markets.
| Leading Market Players |
|---|
| Texas Instruments |
| Qualcomm |
| Honeywell |
| Broadcom |
| Qorvo |
| Skyworks Solutions |
| NXP Semiconductors |
| Infineon Technologies |
| Teledyne Technologies |
| Others |
Value Network & Pricing Analysis
Pentagon procurement for contested electromagnetic environments is compressing supplier qualification timelines and forcing foundries to prioritize military-grade phase noise specifications over commercial volume economics. This demand-side pressure concentrates pricing power among ITAR-cleared fabricators with captive aluminum nitride deposition capabilities while marginalizing merchant suppliers dependent on spot chemical markets.
Pricing Analysis
Short lead-time premiums of 15-30% apply to single crystal resonators above 1.5 GHz where ITAR classification limits qualified supplier pools. Three-tier pricing structure across ITAR-cleared premium, automotive-qualified standard, and consumer-grade economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from MEMS oscillator substitution eroding share in cost-sensitive consumer electronics sockets. Automotive tier-1 suppliers exhibit highest price sensitivity due to AEC-Q200 qualification cost pass-through demands, while defense primes show lowest sensitivity given mission-critical frequency stability requirements.
Supply Chain Analysis
Workforce availability constraints in California's semiconductor corridor and Texas defense manufacturing clusters are elevating foundry labor costs and extending recruitment cycles for phonon scattering physics specialists. Supply concentrates in Taiwan for high-purity aluminum nitride precursor chemicals, the United States for CMOS-compatible fabrication, and Japan for quartz substrate refining. Raw material dependencies encompass aluminum nitride sputtering targets, lithium niobate wafers, and scandium oxide dopants. Single-source vulnerability in East Asian specialty chemical markets threatens input cost stability. Distribution runs through direct OEM-fabricator relationships that displace traditional merchant distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with captive thin film deposition and ITAR clearance, as FCC spectrum reallocation and defense procurement expansion force weaker players toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into aluminum nitride precursor supply and expansion of AEC-Q200 testing infrastructure. Threats from MEMS oscillator substitution in consumer electronics demand accelerated R&D in scandium-doped piezoelectric films to maintain performance differentiation. Capacity addition in Texas instrumentation corridors reduces exposure to California workforce constraints. For New Entrants and Emerging Players: Begin with vehicle-to-everything timing device sockets where NHTSA mandates are opening procurement specifications before incumbent qualification cycles complete. The most penetrable white-space sits in heavy-duty truck and electric vehicle powertrain segments prioritizing thermal stability. A go-to-market angle through automotive tier-1 supplier partnerships bypasses direct ITAR clearance requirements. For Investors and Strategic Acquirers: The window for entry favors mid-scale resonator specialists with existing thin film deposition assets and pending ITAR certifications. Long-term viability over the next decade hinges on dual-use platform designs serving both commercial telecom and defense applications without duplicate qualification tracks. The signal to watch is Pentagon vendor consolidation announcements indicating which fabrication partnerships defense primes are prioritizing for satellite-grade procurement.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Certification Investment | Unlocks Pentagon procurement for contested electromagnetic environment resonators above 1.5 GHz. |
| Scandium-Doped AlN Process Maturation | Enhances electromechanical coupling efficiency for 5G millimeter-wave RF filter architectures. |
| AEC-Q200 Testing Infrastructure Buildout | Enables automotive timing device qualification for NHTSA vehicle-to-everything mandates. |
| Captive Aluminum Nitride Deposition | Reduces supply concentration risk from East Asian specialty chemical market volatility. |
| Defense Prime Direct Partnership | Bypasses merchant distributor displacement in aerospace and satellite procurement workflows. |
Research Methodology
Multi-period observation of defense procurement award patterns, FCC spectrum auction outcomes, and foundry capacity utilization rates anchored the trend analysis, supplemented by interviews with thin film deposition engineers, RF filter design leads at telecom equipment manufacturers, defense procurement officers, automotive tier-1 supplier quality managers, and biomedical device regulatory specialists. Secondary validation drew from SEC 10-K filings, Pentagon budget justification documents, FDA electromagnetic compatibility guidance, NHTSA connected vehicle rulemaking dockets, and customs trade data for aluminum nitride precursor imports. Bottom-up segment sizing triangulated against top-down semiconductor component demand models.
Segment-weighting across product type, application, end user, and technology dimensions informed volume and value projections throughout the forecast period. Film versus single crystal material splits, healthcare versus industrial automation demand trajectories, and government agency versus manufacturer customer mix were modeled explicitly. CAGRs derived from fitted growth curves applied to segment-level baseline estimates, with cross-checks against 5G infrastructure capex forecasts, defense electronics procurement trends, and point-of-care diagnostic platform deployment rates.
Underlying measurement precision varies by segment; defense procurement and healthcare applications carry tighter precision than emerging environmental monitoring sockets. Forecasts reflect assumptions around FCC spectrum reallocation timelines, ITAR classification threshold stability, and aluminum nitride supply chain continuity. A small set of triggers—Pentagon vendor consolidation announcements, scandium-doped AlN foundry partnership formations, and NHTSA vehicle-to-everything mandate enforcement actions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Piezoelectric Accelerometer Market