
 Thermistor Market | 2026-2036
Thermistor Market Size, Share, and Industry Trends Forecast 2026-2036
Thermistor Market Outlook
China is tilting thermistor manufacturing capacity upward through state-backed semiconductor self-sufficiency programs. Murata Manufacturing leverages ceramic formulation expertise to sustain premium positioning in automotive-grade NTC devices. TE Connectivity anchors North American supply through vertically integrated sensor assembly for industrial and aerospace channels.
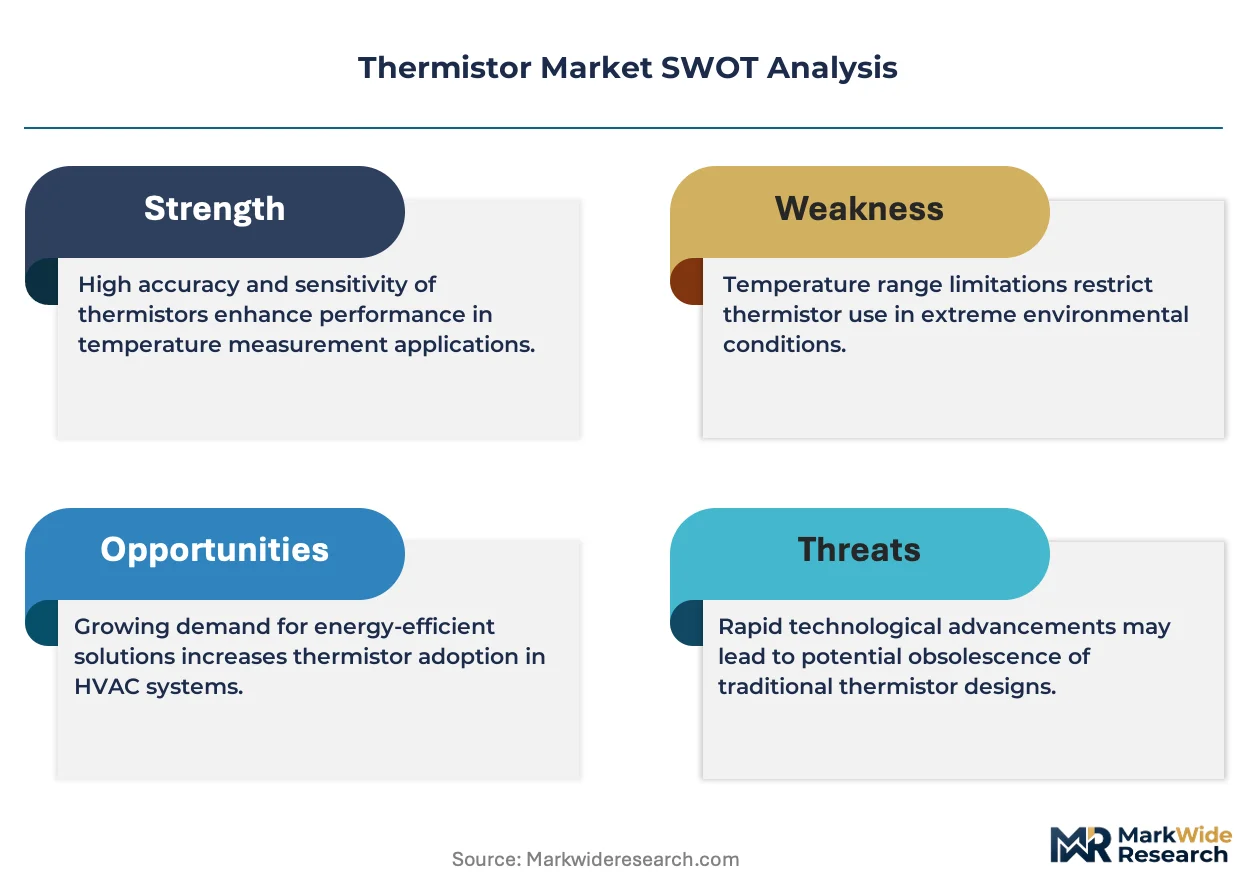
A thermistor is a temperature-sensitive resistor whose electrical resistance varies predictably with temperature, typically manufactured from metal oxide ceramics such as manganese, nickel, and cobalt oxides sintered at controlled temperatures. NTC thermistors dominate volume due to their precision in battery thermal runaway detection and HVAC control systems, while PTC variants command stronger margins in circuit protection roles where self-resetting fuse behavior eliminates replacement costs. Medical device end users increasingly specify digital-output thermistors with integrated signal conditioning, shifting procurement away from analog-only suppliers.
FDA device classification rules for patient-contact temperature sensors and EPA energy conservation standards for appliance control systems jointly elevate barrier-to-entry for uncertified suppliers. CE marking under the EU Medical Device Regulation and RoHS substance restrictions further constrain material choices and testing protocols. Stakeholders must monitor divergence between regional electromagnetic compatibility standards as wireless-enabled thermistors penetrate industrial IoT deployments.
Market Dynamics
Electric vehicle battery thermal management requirements are compressing development cycles and forcing ceramic formulation upgrades across the thermistor supply base. The shift from passive to active thermal monitoring in lithium-ion packs is redrawing procurement specifications and certification requirements simultaneously.
Growth Catalysts
- EU Green Deal appliance efficiency mandates:Stricter energy conservation standards for HVAC and refrigeration systems are mandating precision temperature sensors in compressor controls and defrost circuits across European manufacturing.
- China EV battery production scaling:Domestic electric vehicle output exceeding seven million units annually is creating concentrated demand for automotive-grade NTC thermistors in battery management systems and motor thermal protection.
- Medical device digital integration:Patient-contact temperature monitoring equipment is specifying thermistors with integrated analog-to-digital conversion and signal conditioning to reduce system design complexity.
Market Restraints
- Raw material concentration in cobalt oxide supply:Over sixty percent of refined cobalt originates from the Democratic Republic of Congo, exposing ceramic thermistor manufacturers to price volatility and ethical sourcing compliance costs.
- Automotive qualification timelines:AEC-Q200 stress testing and PPAP documentation requirements extend new product introduction cycles to eighteen months, freezing out smaller suppliers without dedicated validation facilities.
- Thin-film RTD substitution in precision applications:Platinum resistance temperature detectors are displacing NTC thermistors in laboratory and pharmaceutical process control where long-term drift specifications below 0.1°C are mandatory.
Strategic Opportunities
- India industrial automation buildout:The Production-Linked Incentive scheme for electronics manufacturing is attracting sensor assembly investments to serve domestic HVAC, automotive, and process control equipment demand.
- Wireless-enabled thermistor convergence:Integration of Bluetooth Low Energy and LoRaWAN radio modules with temperature sensing elements is opening industrial IoT predictive maintenance applications without wired infrastructure.
- US Inflation Reduction Act clean energy incentives:Domestic content requirements for battery and heat pump manufacturing are creating localized demand for thermistor suppliers with North American ceramic processing capabilities.
Industry Challenges
- Automotive functional safety certification gap:ISO 26262 ASIL-rated thermistor design capabilities remain concentrated among tier-one suppliers, limiting mid-tier participation in safety-critical battery management channels.
- Legacy analog system integration friction:Digital-output thermistors with embedded calibration curves require microcontroller firmware updates that delay adoption in cost-sensitive appliance replacement markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermistor Market |
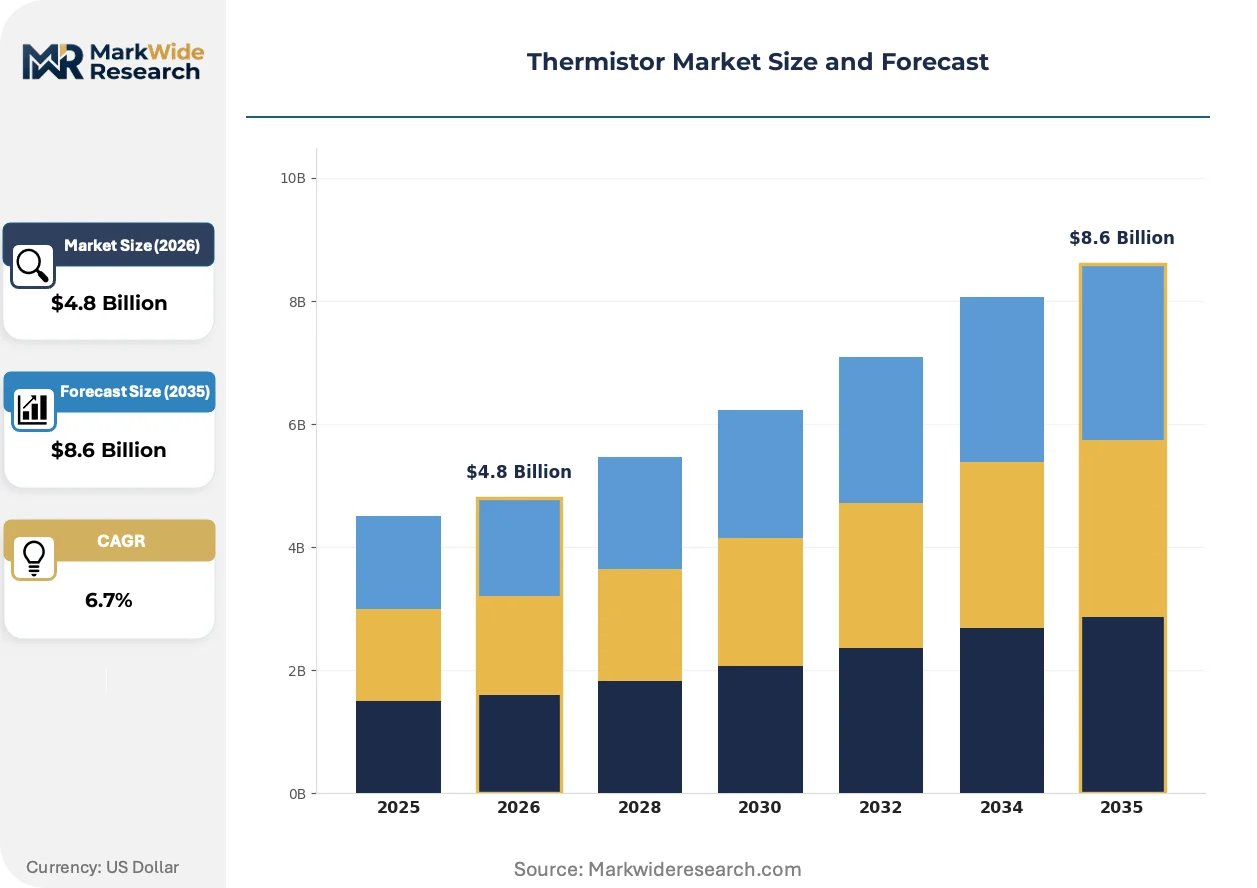
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NTC Thermistor, PTC Thermistor, High-Temperature Thermistor, Low-Temperature Thermistor Application: Temperature Sensing, Circuit Protection, Automotive, HVAC End User: Consumer Electronics, Industrial Appliances, Automotive Solutions, Medical Devices Technology: Analog, Digital, Wireless, Hybrid |
| Companies Covered | Murata Manufacturing, TE Connectivity, Mitsubishi Materials Corporation, Shibaura Electronics, Littelfuse, Vishay Intertechnology, Panasonic Corporation, Bourns, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermistor Market Strategic Shifts
Thermistor technology is bifurcating between commodity analog devices and intelligent sensors with embedded processing. Ceramic processing advances and wireless module miniaturization are enabling form factors that penetrate previously inaccessible installation environments.
Glass-encapsulated NTC thermistors are migrating from traditional epoxy-coated bead constructions to hermetically sealed axial and radial packages. Automotive battery pack manufacturers in Germany and South Korea are specifying these devices for coolant line immersion and cell surface contact applications where moisture ingress resistance exceeds fifteen years. This migration from polymer to glass encapsulation is compressing the addressable market for standard epoxy devices while expanding premium ceramic-to-metal seal capacity.
REACH substance restrictions and RoHS recast directives in Europe are eliminating lead-bearing termination finishes and cadmium-containing stabilizers from thermistor manufacturing processes. Component suppliers are transitioning to pure tin and nickel-palladium-gold plating systems that satisfy environmental compliance without sacrificing solderability in high-temperature automotive reflow profiles. Medical device manufacturers exporting to the European Union are now demanding full material declaration documentation that traces ceramic oxide compositions through the entire sintering and metallization workflow.
Original equipment manufacturers in the appliance and HVAC sectors are consolidating temperature sensor procurement around suppliers offering integrated probe assemblies rather than discrete thermistor elements. This specification shift is displacing component distributors in favor of vertically integrated sensor houses that mold housings, terminate cables, and perform calibration in single-source workflows. The transformation is most visible in China, where domestic white goods manufacturers are qualifying local probe assemblers to reduce import dependency and accelerate design iteration cycles.
Thermistor Market Segmentation
Thermistor procurement cycles vary dramatically across segments. Automotive qualification timelines stretch to eighteen months while consumer electronics refresh quarterly. Understanding these velocity differentials helps suppliers align inventory and certification investments with actual demand patterns.
Product Type:
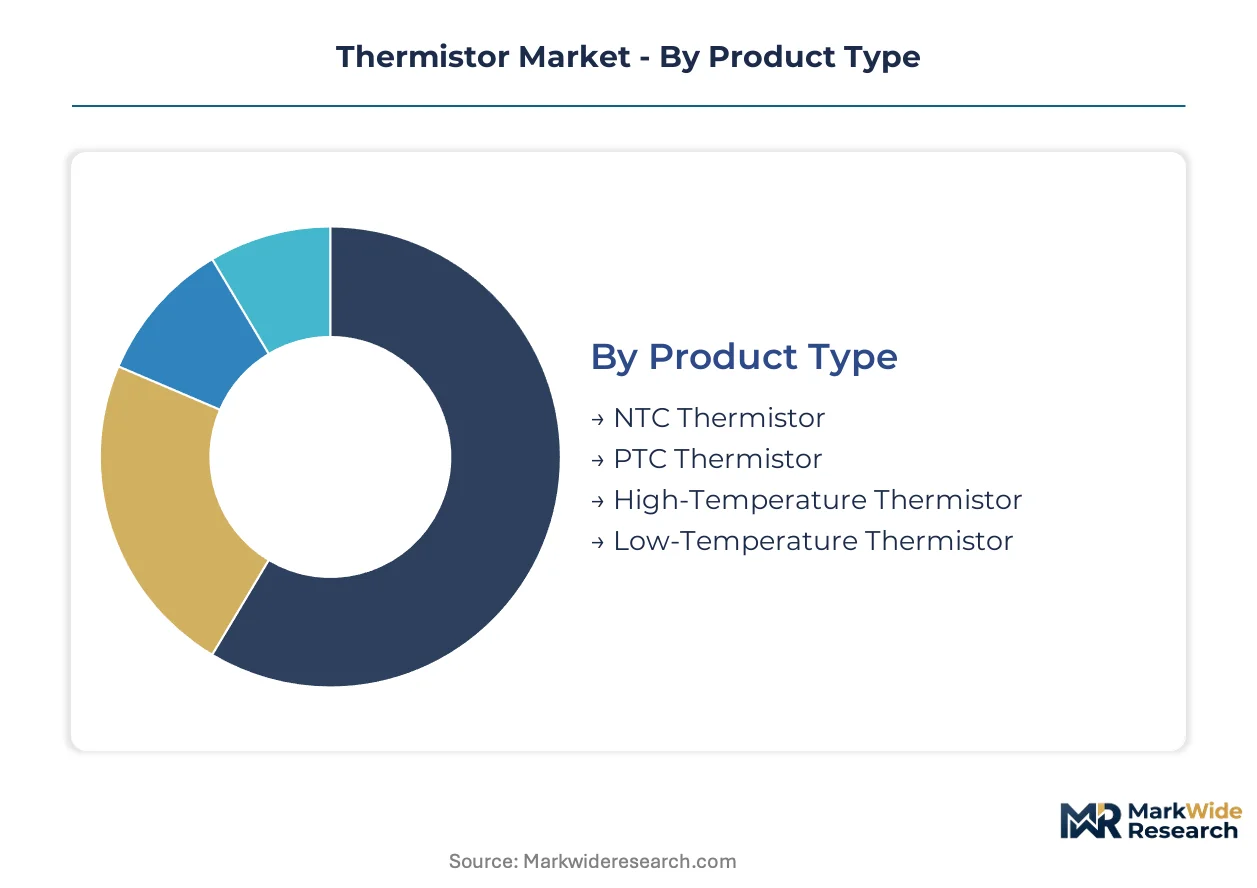
Replacement cycles separate this category sharply. NTC devices in automotive battery systems face decade-long validation horizons. Consumer-grade PTC thermistors in appliance protection roles turn over in two-to-three-year design windows. High-temperature variants for industrial process control occupy intermediate refresh rhythms.
- NTC Thermistor:Metal oxide ceramics of manganese, nickel, and cobalt oxides deliver predictable resistance-temperature curves. Battery management systems in Germany and South Korea specify these for cell surface monitoring and coolant line immersion where precision within 0.1°C prevents thermal runaway. AEC-Q200 stress testing and PPAP documentation extend automotive introduction cycles.
- PTC Thermistor:Barium titanate-based ceramics exhibit sharp positive temperature coefficient transitions enabling self-resetting fuse behavior. Circuit protection applications in HVAC compressor motors and power tool battery packs eliminate replacement costs. Margins exceed NTC equivalents due to formulation complexity and fewer qualified suppliers.
- High-Temperature Thermistor:Alumina-substrate constructions withstand continuous operation above 300°C. Industrial furnace controls and exhaust gas monitoring in Japan specify these where platinum RTDs prove cost-prohibitive.
- Low-Temperature Thermistor:Specialized dopants maintain sensitivity below -40°C. Cryogenic storage monitoring and aerospace fuel systems require these for precision outside standard ceramic operating ranges.
NTC Thermistor anchors the volume base while High-Temperature Thermistor gains share at the steepest rate.
Application:
Margin structures diverge by application based on certification burden and integration depth. Temperature sensing commands commodity pricing unless paired with digital output or wireless modules. Circuit protection sustains premium tiers through safety-critical liability exposure.
- Temperature Sensing:Core function spans HVAC thermostat controls, refrigerator defrost circuits, and medical patient monitoring. Integration with analog-to-digital conversion and signal conditioning is displacing raw thermistor element procurement in EU medical device channels.
- Circuit Protection:Self-resetting overcurrent protection in lithium-ion battery packs and motor windings. IEC 60730 safety standards for appliance controls mandate these in European white goods manufacturing.
- Automotive:Battery thermal management and motor temperature monitoring require ISO 26262 ASIL-rated designs. Functional safety certification gaps limit mid-tier supplier participation.
- HVAC:Compressor protection and refrigerant line monitoring. EPA energy conservation standards for appliance efficiency are mandating precision sensors in North American equipment.
Temperature Sensing generates the highest shipment volumes while Automotive commands the steepest price premiums.
End User:
Procurement sophistication varies dramatically across end user categories. Medical device manufacturers demand full material declaration documentation and digital integration. Industrial appliance buyers consolidate around probe assembly suppliers.
- Consumer Electronics:Smartphones, laptops, and wearables require miniaturized surface-mount devices. China domestic production scaling is reducing import dependency for these high-volume, price-sensitive applications.
- Industrial Appliances:Motor protection, power supply thermal management, and process control equipment. Vertically integrated sensor houses are displacing component distributors through complete probe assembly offerings.
- Automotive Solutions:Electric vehicle battery management and thermal runaway detection. US Inflation Reduction Act domestic content requirements are creating localized demand for North American ceramic processing capabilities.
- Medical Devices:Patient-contact temperature monitoring equipment. FDA device classification rules and EU Medical Device Regulation CE marking elevate barrier-to-entry for uncertified suppliers.
Consumer Electronics anchors the volume base while Automotive Solutions is expanding most quickly.
Technology:
Architecture choices determine system design complexity and supplier value capture. Analog devices face margin compression from digital integration trends. Wireless modules command substantial premiums in industrial IoT predictive maintenance.
- Analog:Raw resistance output requires external signal conditioning and calibration tables. Legacy appliance replacement markets delay adoption due to microcontroller firmware update requirements.
- Digital:Embedded analog-to-digital conversion with factory-calibrated lookup tables. Medical device manufacturers in the European Union increasingly specify these to reduce system design complexity.
- Wireless:Bluetooth Low Energy and LoRaWAN radio module integration. Industrial IoT deployments without wired infrastructure are opening predictive maintenance applications.
- Hybrid:Combined analog and digital outputs for backward compatibility during system transitions. HVAC equipment upgrades favor these for phased modernization.
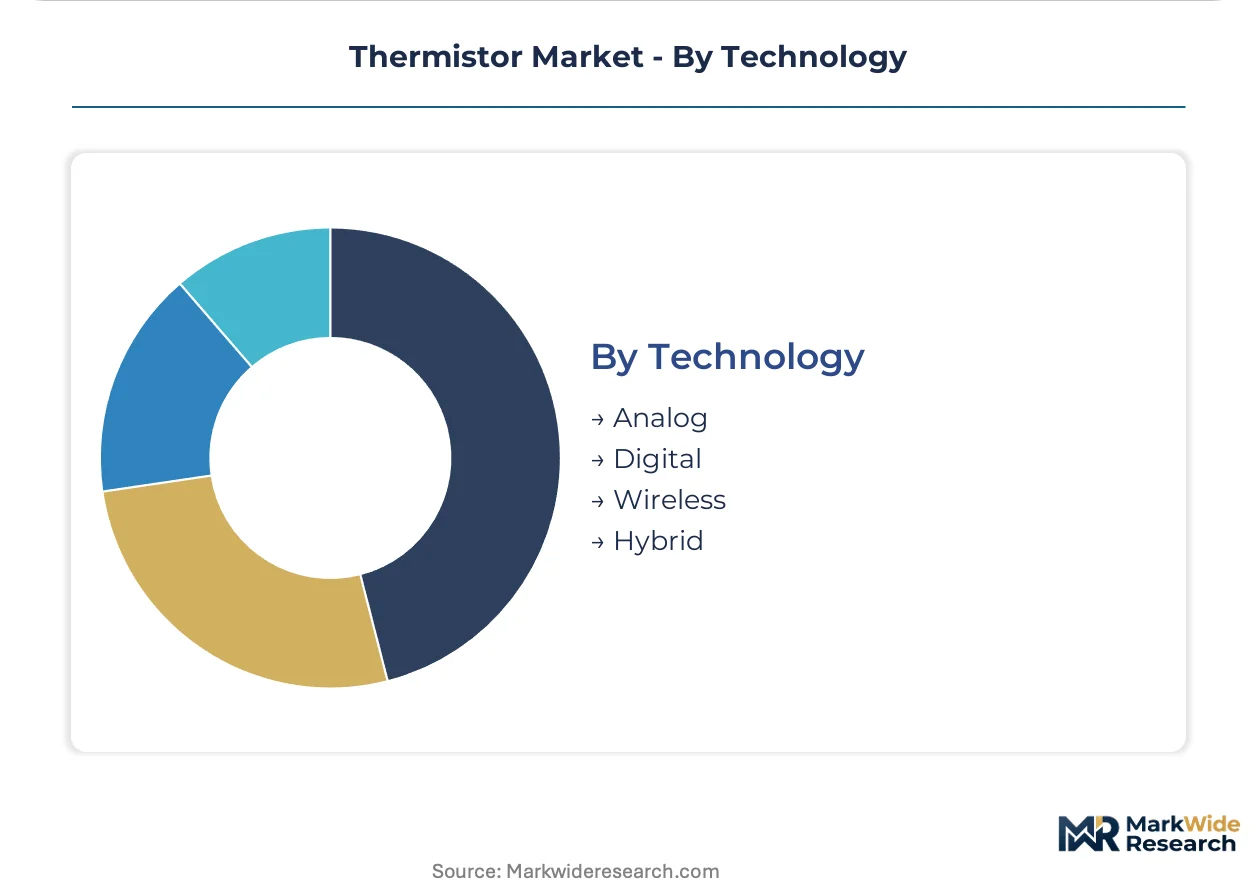
Analog technology anchors the volume base while Wireless is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the majority of thermistor manufacturing capacity through state-backed semiconductor self-sufficiency programs. Japanese and German suppliers anchor premium automotive-grade production through ceramic formulation expertise.
China
Domestic electric vehicle output exceeding seven million units annually drives concentrated demand for automotive-grade NTC thermistors in battery management systems. MIIT dual carbon goals and GB standards for energy efficiency are tightening specifications for HVAC and appliance control sensors. The Yangtze River Delta cluster around Shanghai and Suzhou hosts rapid scaling of ceramic processing facilities serving BYD, CATL, and domestic white goods manufacturers.
Germany
Automotive battery pack manufacturers specify glass-encapsulated NTC thermistors for coolant line immersion and cell surface contact applications. EU Green Deal appliance efficiency mandates and REACH substance restrictions are eliminating lead-bearing termination finishes from thermistor supply chains. The Baden-Württemberg industrial corridor around Stuttgart anchors premium ceramic-to-metal seal capacity for BMW, Mercedes-Benz, and Bosch thermal management programs.
United States
EPA energy conservation standards for appliance controls and US Inflation Reduction Act clean energy incentives are creating localized demand for North American ceramic processing capabilities. Domestic content requirements for battery and heat pump manufacturing are reshaping procurement patterns. The Southeast industrial belt spanning Tennessee and South Carolina is attracting sensor assembly investments to serve automotive and HVAC equipment demand.
Japan
High-temperature thermistor demand for industrial furnace controls and exhaust gas monitoring sustains specialized alumina-substrate production. METI energy efficiency standards and JIS certification requirements elevate barrier-to-entry for uncertified suppliers. The Chubu region around Nagoya maintains concentrated expertise in automotive-grade ceramic formulations serving Toyota and Honda battery thermal management systems.
South Korea
LG Energy Solution and Samsung SDI battery production scaling is driving procurement of precision NTC devices for thermal runaway detection. MFDS medical device regulations and KBA automotive standards are converging on digital-output thermistor specifications. The Busan-Ulsan industrial complex is consolidating probe assembly capacity to reduce import dependency from Japanese ceramic suppliers.
Thermistor Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ceramic formulation and calibration. The supplier base fragments across three capability tiers: multinational conglomerates with captive ceramic processing, mid-scale specialists in automotive qualification, and regional probe assemblers in China and India. Two strategic archetypes dominate: vertically integrated sensor houses consolidating procurement around complete probe assemblies, and pure-play ceramic manufacturers licensing formulations to downstream integrators. Competitive moves center on backward integration into ceramic oxide supply and strategic partnerships for wireless module integration.
Among Japanese ceramic specialists, Murata Manufacturing and TDK Corporation exemplify the premium formulation tier where automotive-grade NTC devices command extended qualification timelines. TE Connectivity anchors the North American platform integrator archetype through sensor assembly capabilities serving industrial and aerospace channels. These three occupy positions that reflect the market's bifurcation between commodity analog devices and intelligent sensors with embedded processing.
| Leading Market Players |
|---|
| Murata Manufacturing |
| TE Connectivity |
| Mitsubishi Materials Corporation |
| Shibaura Electronics |
| Littelfuse |
| Vishay Intertechnology |
| Panasonic Corporation |
| Bourns |
| TDK Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese ceramic processing facilities is compressing margin structures across standard NTC device tiers while simultaneously accelerating qualification investments in automotive-grade segments. This utilization divergence forces suppliers to choose between volume-driven cost absorption and premium positioning through AEC-Q200 certification.
Pricing Analysis
EU Green Deal appliance efficiency mandates dictate the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 automotive devices from industrial-grade units and consumer electronics commodities. Price differentiation hinges on certification grade and ceramic formulation precision. Cost compression in consumer-grade epoxy-coated devices is intensifying because domestic Chinese suppliers are scaling manganese oxide processing capacity. Appliance OEMs exhibit highest price sensitivity, while German automotive battery pack manufacturers demonstrate lowest sensitivity due to thermal runaway liability exposure.
Supply Chain Analysis
Extended payment terms from South Korean battery manufacturers are forcing ceramic suppliers to utilize supply-chain finance facilities for working capital management. Raw material sourcing draws from the Democratic Republic of Congo for cobalt oxide, China for manganese and nickel oxides, and Japan for alumina substrates. Distribution runs through vertically integrated sensor houses in China and Germany rather than component distributors. Single-source vulnerability in refined cobalt concentrates supply chain risk, as over sixty percent originates from one geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. AEC-Q200 and ISO 26262 certification timelines create switching costs that freeze out unqualified competitors.
For Market Incumbents: Pre-empt thin-film RTD substitution in laboratory applications by accelerating digital-output thermistor development with embedded calibration curves. Backward integration into cobalt oxide sourcing mitigates ethical sourcing compliance cost pressure from DRC concentration. Capacity addition in Tennessee and South Carolina captures US Inflation Reduction Act domestic content requirements.
For New Entrants and Emerging Players: Mid-market HVAC probe assembly in India represents the most penetrable entry point given Production-Linked Incentive scheme electronics manufacturing subsidies. Wireless-enabled industrial IoT predictive maintenance applications without wired infrastructure offer second white-space target. Direct qualification with domestic white goods manufacturers in the Yangtze River Delta provides fastest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-grade ceramic processing due to AEC-Q200 validation facility requirements. Long-term viability over the next decade favors tier-one suppliers with captive ceramic formulation expertise. Acquisition target archetype: mid-scale specialists with existing PPAP documentation capabilities but lacking wireless module integration. Monitor divergence between regional electromagnetic compatibility standards as inflection indicator for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Certification Investment | AEC-Q200 qualification opens procurement channels with BMW, Mercedes-Benz, and Bosch thermal management programs. |
| Backward Integration into Ceramic Oxides | Captive manganese and nickel oxide processing insulates margin structures from DRC cobalt price volatility. |
| Wireless Module Integration Partnership | Bluetooth Low Energy convergence enables industrial IoT predictive maintenance without wired infrastructure deployment. |
| Domestic Content Qualification | North American ceramic processing capabilities satisfy US Inflation Reduction Act battery and heat pump manufacturing requirements. |
| Probe Assembly Verticalization | Complete sensor housings with molded cables and calibration displace component distributors in China and India. |
Study Parameters
A standing panel of automotive platform engineers, battery thermal management specialists, HVAC procurement directors, medical device regulatory affairs leads, and ceramic processing plant managers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from SEC filings, EPA energy conservation standard dockets, EU Medical Device Regulation guidance documents, and MIIT dual carbon policy releases. Bottom-up shipment data from ceramic processing facilities triangulated against top-down OEM procurement estimates.
Scenario-bracketing framed analytical approach across the projection horizon, modeling thermistor demand by product type, application, end user, and technology architecture. CAGRs derived from regression analysis of historical qualification timelines and procurement cycle compression. Industry-specific forecast inputs included electric vehicle battery production scaling trajectories and REACH substance restriction implementation schedules.
Practitioners should monitor raw material price volatility, automotive qualification timeline extensions, and wireless standard divergence for early signals of forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Battery Free Wireless Sensor Market