
 Europe Floating Offshore Wind Power Market | 2026-2036
Europe Floating Offshore Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Floating Offshore Wind Power Market Foresight
The capability gap between integrated energy majors and pure-play technology developers is unwinding competitive dynamics across the sector. Equinor ASA leverages its Hywind platform experience to anchor early-mover advantages in deep-water deployments. Principle Power Inc. specializes in WindFloat semisubmersible designs that compete on modularity and port-based assembly. BW Ideol SA differentiates through its damping pool technology, which occupies a niche in harsh-environment suitability.
Floating offshore wind power refers to turbine installations mounted on buoyant substructures anchored to the seabed with mooring lines, enabling electricity generation in water depths exceeding 60 meters where fixed foundations become technically unviable. The primary commercial purpose is harvesting stronger, more consistent wind resources in deep-water zones inaccessible to conventional bottom-fixed arrays. Semisubmersible platforms lead current deployment owing to their stability during towing and installation, while tension leg platforms command attention for minimized motion at turbine level in calmer basins. Spar-buoy designs retain cost advantages where deep draft deployment logistics align with available infrastructure.
The EU Green Deal and REPowerEU framework shape demand by binding member states to offshore wind capacity targets and accelerating environmental permitting timelines. ECHA REACH compliance and CE marking requirements govern composite material specifications and electrical system interoperability across national zones. Stakeholders must monitor how the EU AI Act and forthcoming maritime spatial planning directives interact with project siting algorithms and automated maintenance protocols.
Market Dynamics
The European floating offshore wind sector confronts a capital intensity threshold that is bifurcating developer tiers based on balance sheet capacity and project finance access. Early commercial arrays in Portugal and France are validating semisubmersible platforms while exposing the gap between demonstration-scale learning and multi-gigawatt deployment pipelines.
Growth Catalysts
- REPowerEU acceleration mechanisms:Streamlined permitting timelines and dedicated funding windows compress development cycles for deep-water projects in Scottish and French waters.
- Steel and composite supply localization:Port infrastructure upgrades in Portugal and Norway enable domestic fabrication of substructure components, reducing logistical exposure to Asian heavy-lift vessel markets.
- Utility offtake commitments:European integrated energy majors are contracting floating capacity through corporate power purchase agreements that de-risk construction financing for first commercial arrays.
Market Restraints
- Mooring system cost volatility:Synthetic rope and anchor chain prices fluctuate with specialty polymer and high-grade steel feedstock markets, compressing EPC margin assumptions.
- Installation vessel scarcity:The North Sea and Atlantic coasts face constrained availability of heavy-lift vessels capable of integrating 15 MW+ turbines onto floating substructures.
- Grid connection queuing:National transmission system operators in France and Scotland maintain multi-year interconnection backlogs that delay revenue commencement for consented projects.
Strategic Opportunities
- Spanish Atlantic depths:The Galicia and Canary Islands zones offer untapped water depths exceeding 100 meters with limited competing maritime uses and favorable wind resource profiles.
- Green hydrogen co-location:Electrolyzer integration at floating platforms enables offtake diversification beyond grid injection, targeting industrial demand clusters in Rotterdam and Hamburg.
- EU Innovation Fund deployment:Large-scale project grants covering up to 60 percent of capital costs are de-risking first-of-a-kind commercial arrays in French Mediterranean waters.
Industry Challenges
- Marine warranty surveyor capacity:The limited pool of classification society engineers qualified for floating foundation certification creates bottlenecks in final investment decision timelines.
- Dynamic cable standardization:Absence of unified IEC specifications for floating-to-fixed inter-array cabling forces project-specific engineering that inflates electrical system costs.
- Port assembly footprint constraints:Quayside load-bearing capacity and dry dock dimensions at Scottish and Norwegian fabrication yards restrict parallel substructure construction campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Floating Offshore Wind Power Market |
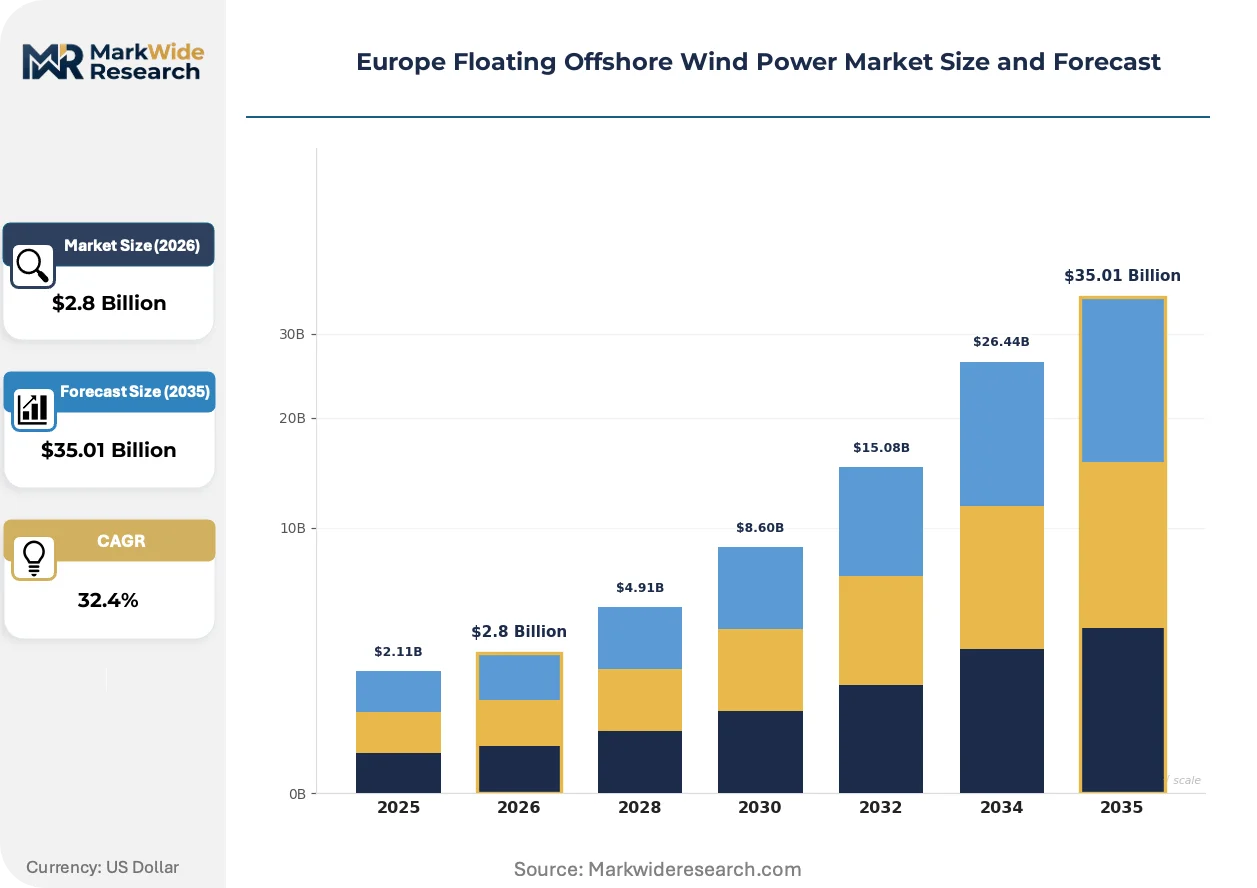
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $35.01 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technological Innovation: Semisubmersible, Tension Leg Platform, Spar-Buoy, Floating Lid Deployment Model: Fixed-Bottom, Floating, Hybrid, Pilot Project End User: Utilities, Independent Power Producers, Offshore Developers, Governments Project Size: Small-Scale, Medium-Scale, Large-Scale, Gigawatt Scale |
| Companies Covered | Equinor ASA, Ørsted A/S, RWE AG, Iberdrola S.A., Siemens Gamesa Renewable Energy, Vestas Wind Systems A/S, GE Vernova, BW Ideol SA, Principle Power Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Floating Offshore Wind Power Market Shifts & Advancements
Technology maturation in the European floating wind sector is compressing the gap between demonstration projects and bankable commercial arrays. Three distinct movements are reshaping how developers approach substructure selection, regulatory navigation, and offtake structuring.
Semisubmersible platform design is bifurcating between steel-heavy conventional configurations favored by established fabricators and lightweight concrete-steel hybrid alternatives pursued by cost-focused entrants. Scottish and French developers are evaluating the latter for serial production at repurposed oil and gas fabrication yards. The structural consequence is a compression in platform-specific capital expenditure assumptions that is enabling project economics in water depths previously considered marginal.
The EU AI Act and forthcoming maritime spatial planning directives are forcing alignment between automated turbine maintenance protocols and algorithmic transparency requirements. Developers deploying drone-based blade inspection and predictive drivetrain analytics must now document decision logic for regulatory review. French project consents are incorporating these compliance milestones as conditions precedent to operational authorization, affecting procurement timelines for intelligent monitoring systems.
Corporate offtakers in the European chemical and data center sectors are demanding delivery structures that bundle floating wind output with guaranteed baseload shaping. Traditional fixed-price power purchase agreements are yielding to volume-firming contracts that allocate balancing responsibility to developer-owned storage or third-party optimization platforms. This restructuring is most visible in Dutch and German procurement programs where industrial buyers prioritize schedule certainty over unit cost minimization.
Europe Floating Offshore Wind Power Market Segmentation
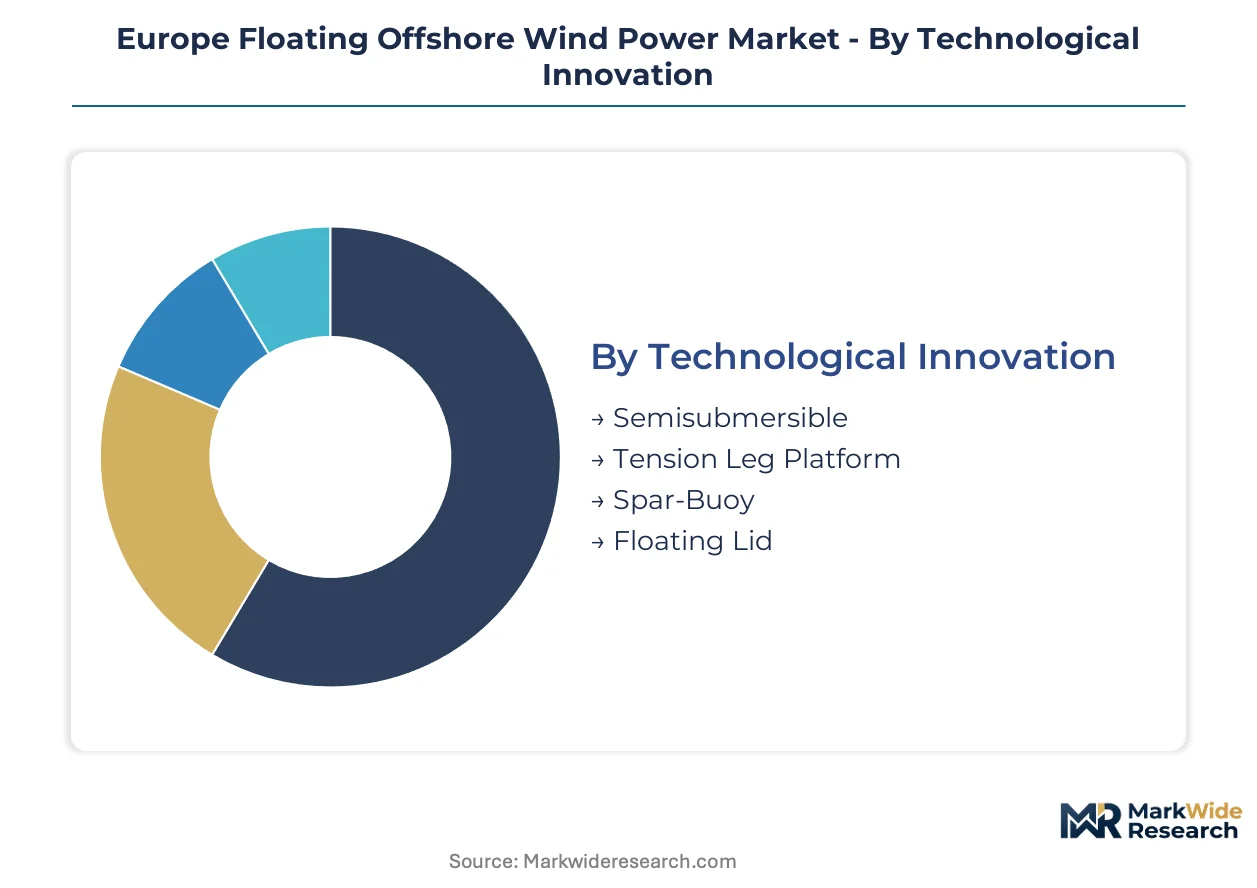
Floating offshore wind segmentation reveals how capital allocation, technology maturity, and regulatory frameworks partition opportunity across distinct development pathways. Platform design choices and project scale thresholds determine which developer profiles can access specific market tiers.
Technological Innovation:
Margin pools concentrate in platform designs that balance fabrication simplicity with motion stability in harsh Atlantic conditions.
- Semisubmersible:Steel or concrete-steel hybrid structures with distributed buoyancy provide inherent stability during towing and turbine integration. Portuguese and Scottish developers favor this architecture for port-based assembly at repurposed oil and gas fabrication yards, where existing heavy-lift infrastructure reduces capital deployment risk.
- Tension Leg Platform:Vertical mooring tethers under tension minimize turbine motion, enabling lighter hull structures in calmer Mediterranean basins. French Mediterranean projects exploit this efficiency for reduced steel intensity, though installation complexity limits deployment to specialized contractor fleets.
- Spar-Buoy:Deep-draft cylindrical hulls achieve stability through ballasted mass, requiring deep-water assembly sites that constrain siting flexibility.
- Floating Lid:Enclosed deck structures with integrated turbine housing reduce wave loading but impose weight penalties that challenge cost competitiveness.
The dominant share belongs to semisubmersible configurations, while tension leg platforms are closing the gap fastest in French waters.
Deployment Model:
Capital intensity and permitting pathways segment developers by their risk tolerance and balance sheet capacity.
- Fixed-Bottom:Conventional monopile and jacket foundations dominate water depths below 60 meters, capturing mature supply chains and standardized installation protocols. Scottish North Sea zones and southern North Sea areas concentrate this infrastructure, with developers leveraging existing vessel fleets and established grid connection frameworks.
- Floating:Buoyant substructures anchored by mooring lines unlock depths beyond fixed-bottom viability, commanding premium capital costs that filter participant pools to integrated energy majors and state-backed utilities. Portuguese Atlantic waters and Scottish west coast developments validate commercial scalability.
- Hybrid:Combined fixed-floating arrays optimize transition zone economics where seabed gradients shift rapidly, requiring bespoke engineering that extends development timelines.
- Pilot Project:Sub-commercial demonstration arrays test novel substructures and installation sequences, absorbing technology risk that strategic investors underwrite for learning curve advantages.
Fixed-bottom arrays retain volume leadership in shallow basins, though floating deployments are expanding most quickly as deep-water zones open to development.
End User:
Offtake structuring and regulatory access differentiate procurement power across buyer categories.
- Utilities:Vertically integrated European energy majors leverage balance sheet capacity to underwrite multi-gigawatt pipelines, securing priority grid connection slots and streamlined permitting through REPowerEU mechanisms. Their procurement concentrates in Scottish and French waters where seabed leasing frameworks favor incumbent players.
- Independent Power Producers:Specialized developers aggregate project finance through corporate power purchase agreements, targeting industrial offtakers in Rotterdam and Hamburg chemical clusters with bundled green hydrogen co-location proposals.
- Offshore Developers:Pure-play floating wind specialists contribute platform innovation and installation expertise, often partnering with utilities for construction risk sharing.
- Governments:State-backed entities in Portugal and Norway direct strategic capacity buildout through sovereign wealth deployment and public tender design.
Utilities command the dominant procurement share, while independent power producers are gaining ground fastest through corporate offtake innovation.
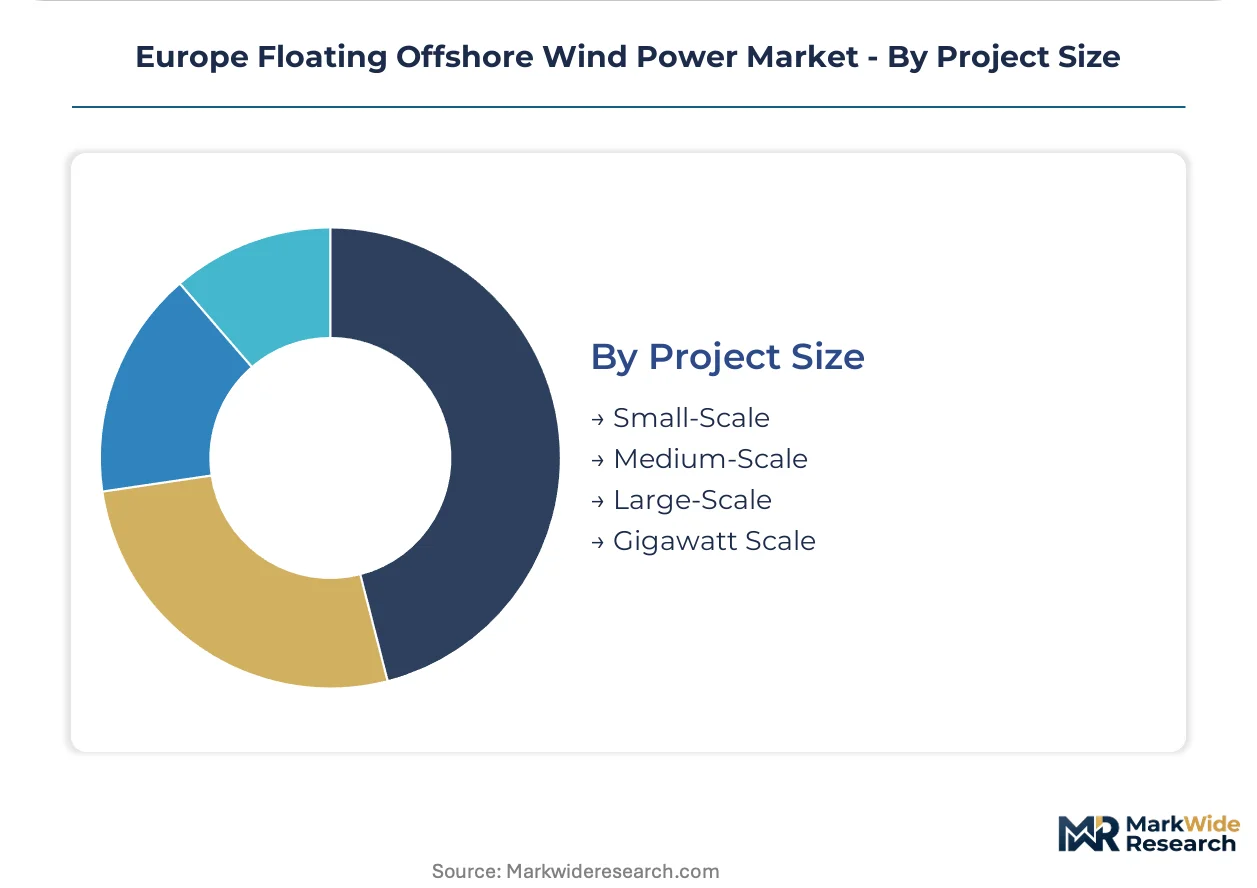
Project Size:
Economies of scale and financing structure availability sort development opportunities by capital deployment thresholds.
- Small-Scale:Sub-50 MW arrays serve demonstration and remote island supply functions, absorbing technology validation costs that strategic investors accept for intellectual property positioning.
- Medium-Scale:50-200 MW commercial arrays represent the current European deployment frontier, with Portuguese WindFloat Atlantic and French EolMed projects establishing bankable precedents for semisubmersible platforms.
- Large-Scale:200-500 MW developments exploit shared mooring infrastructure and consolidated grid connections to compress levelized cost of energy, though multi-source financing complexity extends development timelines.
- Gigawatt Scale:Multi-gigawatt zone development targets Scottish and Norwegian deep-water basins, requiring coordinated transmission buildout and maritime spatial planning alignment that extends planning horizons.
Medium-scale projects anchor current deployment, while gigawatt-scale zones are climbing the fastest as pipeline consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portuguese developers command pricing premiums against Scottish counterparts due to earlier commercial deployment and streamlined maritime leasing frameworks. French project economics sit between these poles, constrained by Mediterranean-specific installation requirements. Norwegian and Spanish entrants are repositioning regional cost curves through fabrication yard specialization and untapped deep-water zone access.
Portugal
WindFloat Atlantic validates semisubmersible platforms at commercial scale, attracting utility offtake from Lisbon-based energy traders. The Portuguese Environment Agency accelerates environmental licensing for projects beyond the 100-meter depth contour. Port of Leixões serves as the Atlantic assembly hub where domestic steel fabrication reduces heavy-lift vessel charter exposure.
Scotland
West coast seabed leasing rounds target 10+ gigawatt floating capacity, drawing construction commitments from Aberdeen oil and gas service clusters. Marine Scotland implements streamlined consenting under REPowerEU alignment for Crown Estate development zones. Cromarty Firth fabrication yards repurpose North Sea offshore infrastructure expertise for floating substructure serial production.
France
Mediterranean tension leg platform pilots exploit calmer wave regimes to minimize hull steel intensity versus Atlantic designs. The French Environment Code incorporates EU AI Act compliance milestones for automated maintenance protocols as operational authorization conditions. Port of Marseille-Fos consolidates substructure assembly for EolMed and subsequent commercial arrays.
Norway
Deep fjord access enables spar-buoy assembly at draft depths unavailable to other European fabrication sites. Equinor ASA leverages state-backed equity participation to anchor Hywind platform learning curve advantages. Stord and Haugesund industrial clusters repurpose offshore oil fabrication capacity for floating wind substructure production.
Spain
Galicia and Canary Islands zones exceed 100-meter depths with minimal competing maritime use, positioning early-mover developers for 2030s pipeline slots. The Spanish Ministry for Ecological Transition coordinates maritime spatial planning with autonomous community permitting to compress development timelines. Port of Ferrol anchors Atlantic coast assembly ambitions through quayside reinforcement investments.
Europe Floating Offshore Wind Power Market Competitive Landscape
Concentration sits with integrated energy majors that balance balance sheet capacity against pure-play technology developers competing on platform innovation. Norwegian and Danish utilities anchor the upper tier through early-mover deployment experience and state-backed equity structures. Mid-tier positioning fragments across specialized platform designers and repurposed oil and gas service contractors. Dominant competitive moves include strategic partnerships between utilities and technology licensors, plus fabrication yard acquisitions that secure port-based assembly capacity.
Among platform technology specialists, Principle Power Inc. and BW Ideol SA exemplify divergent engineering philosophies within the semisubmersible segment. Equinor ASA occupies a distinctive position as the only integrated major with multi-project floating wind operational experience. These three entities represent the spectrum from pure technology licensing through fully integrated development and operations.
| Leading Market Players |
|---|
| Equinor ASA |
| Ørsted A/S |
| RWE AG |
| Iberdrola S.A. |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems A/S |
| GE Vernova |
| BW Ideol SA |
| Principle Power Inc. |
| Others |
Supply & Pricing Matrix
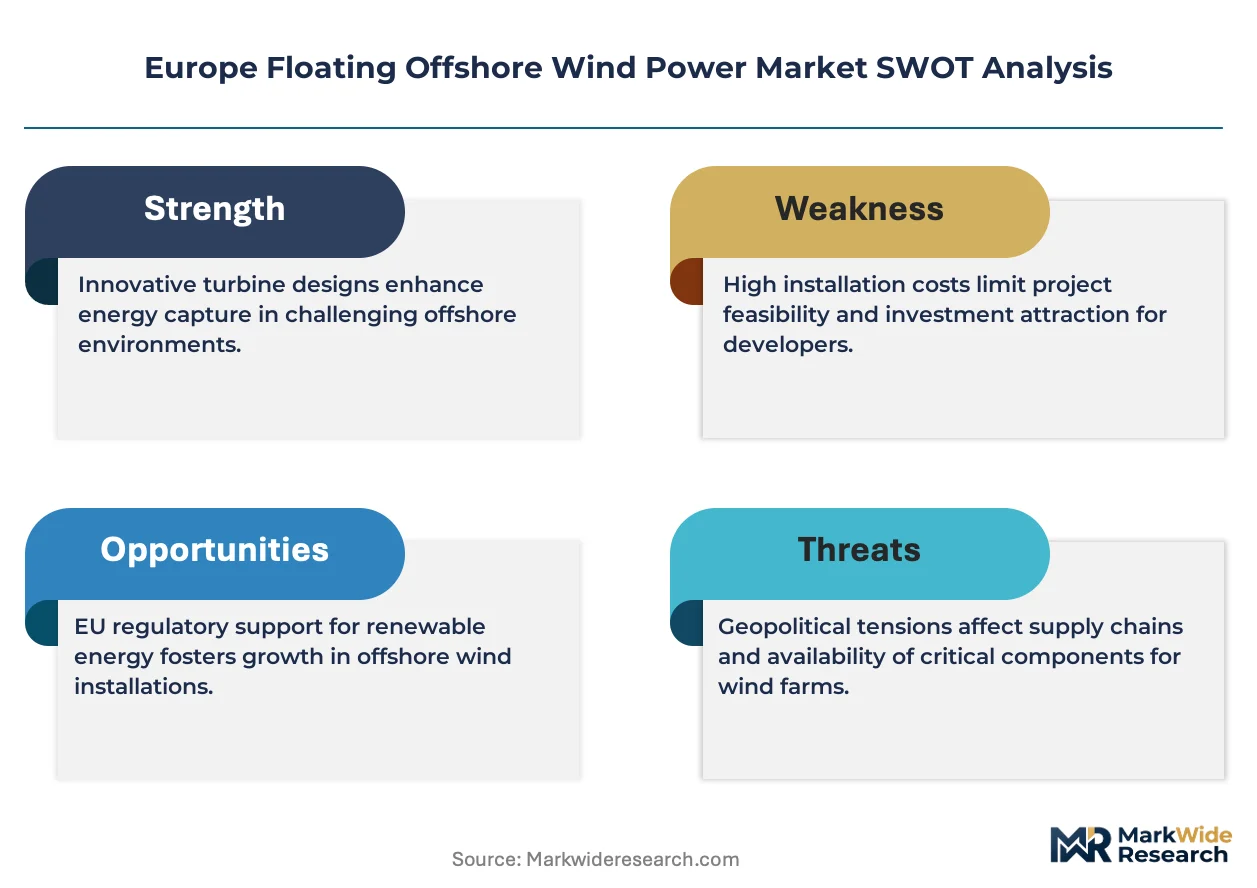
Eighteen-month fabrication yard backlogs for semisubmersible hulls concentrate pricing power with Portuguese and Norwegian port operators, while ECHA REACH compliance costs for composite mooring components widen spreads between certified and uncertified supply tiers. Steel-intensive platform designs face cost compression from scrap price volatility, pushing developers toward concrete-steel hybrid alternatives that exploit localized aggregate sourcing.
Pricing Analysis
Configured-to-order platform engineering commands premiums of 15-25% above standardized semisubmersible designs, reflecting project-specific mooring analysis and turbine integration complexity. Price differentiation rests on CE marking tier and installation vessel availability windows, with Scottish developers absorbing higher logistics premiums due to Cromarty Firth quayside constraints. Cost compression in tension leg platform hulls is intensifying because French Mediterranean projects exploit calmer wave regimes to reduce steel intensity. Utility offtakers demonstrate lowest price sensitivity through corporate power purchase agreements, while independent power producers face margin pressure from multi-source financing complexity.
Supply Chain Analysis
Port congestion at Leixões and Marseille-Fos elevates inbound logistics costs for Korean-manufactured synthetic mooring ropes, compressing EPC margin assumptions on Atlantic coast projects. Geographic supply concentration centers on Portugal, Norway, and France for substructure fabrication, with Spain emerging through Ferrol quayside investments. Raw material dependencies span high-grade steel plate, carbon fiber composite tethers, and zinc-aluminum alloy anchor systems. Single-source vulnerability sits with Asian heavy-lift vessel operators for turbine integration campaigns. Distribution runs through utility-led engineering-procurement-construction contracts that bundle fabrication, transport, and installation risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating offshore wind is approaching a platform-economics inflection where interoperability between semisubmersible designs and standardized mooring interfaces will determine which technology ecosystems capture scale advantages.
For Market Incumbents: Consolidate fabrication yard capacity in Portugal and Norway to anchor supply security against emerging Spanish entrants, while securing marine warranty surveyor relationships that bottleneck competitor project timelines. Backward integration into synthetic rope manufacturing reduces exposure to Korean petrochemical feedstock volatility. Priority certification investment should target EU AI Act compliance for predictive maintenance algorithms ahead of French operational authorization requirements. For New Entrants and Emerging Players: Installation logistics software gaps expose where incumbents under-serve vessel charter optimization and weather window forecasting. Spanish Atlantic depths off Galicia offer the most penetrable geography, with minimal competing maritime use and streamlined autonomous community permitting. Go-to-market positioning should emphasize drone-based blade inspection services bundled with EPC contractor partnerships, bypassing capital-intensive platform ownership. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-transition play because European oil and gas fabrication yard repurposing creates asymmetric upside for holders of quayside real estate and heavy-lift equipment. Acquisition targets should prioritize concrete-steel hybrid platform specialists with French Mediterranean project references. The signal to watch is EU Innovation Fund grant allocation velocity, which indicates political commitment to de-risking first commercial arrays.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Design Standardization | Interoperable mooring interfaces reduce project-specific engineering costs for Scottish developers. |
| Green Hydrogen Co-location | Electrolyzer integration at floating platforms diversifies offtake beyond Rotterdam grid injection. |
| Port Infrastructure Acquisition | Control over Leixões and Ferrol quayside capacity secures Atlantic assembly positioning. |
| Corporate PPA Structuring | Volume-firming contracts with German chemical buyers allocate balancing risk to developer-owned storage. |
| Marine Warranty Surveyor Capacity Expansion | Classification society engineer pipelines accelerate final investment decision timelines for French projects. |
Research Methodology
Desk research of IEA offshore wind databases, EIA project tracking filings, and Crown Estate seabed leasing records preceded structured interviews with utility planning officers, floating wind EPC contractors, marine warranty surveyors, and grid operator interconnection specialists. Primary fieldwork captured installation vessel charter rate dynamics and port assembly capacity constraints. Secondary validation drew from REPowerEU implementation reports, EU Innovation Fund award disclosures, and national maritime spatial planning directives. Bottom-up project pipeline aggregation was cross-checked against top-down capacity target triangulation from member state offshore wind commitments.
Variance decomposition across platform technology, water depth tier, and regulatory framework clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include substructure design category, project capacity scale, and end-user procurement archetype. CAGRs were derived from installed capacity buildout trajectories weighted by commercial operation date probability. Industry-specific forecast inputs incorporated marine warranty surveyor capacity constraints and synthetic rope price elasticity assumptions.
Underlying assumptions cover REPowerEU permitting acceleration continuity, EU Green Deal funding mechanism stability, and Korean heavy-lift vessel availability, with deviation risk concentrated in grid connection queuing timelines and ECHA REACH composite material specification evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market