
 Lidar Ceilometer Market | 2026-2036
Lidar Ceilometer Market Size, Share, and Industry Trends Forecast 2026-2036
Lidar Ceilometer Market Insights
ISO 17025 accreditation for atmospheric measurement instruments is reorganizing supplier eligibility across the Lidar Ceilometer Market. Vaisala Corporation leverages its Finnish manufacturing base and aviation certification heritage to sustain long-term contracts with meteorological agencies. Jenoptik AG anchors its position through in-house diode laser production and precision optics capabilities. Raymetrics competes from Greece with specialized scanning architectures for research-grade deployments.
A lidar ceilometer is a ground-based atmospheric remote sensing instrument that emits pulsed laser light vertically and measures backscatter from aerosols, hydrometeors, and boundary layer structures to derive cloud base height, vertical visibility, and aerosol extinction profiles with typical ranges from 0 to 15 kilometers. Fixed mount systems dominate commercial aviation installations where continuous unattended operation is mandatory, while portable units capture fastest growth in field campaign and emergency response applications. Solid-state technology leads unit shipments due to thermal stability and maintenance intervals, though fiber laser variants command premium positioning in research and military surveillance segments where eye-safe operation at extended ranges is essential.
FAA Terminal Doppler Weather Radar integration requirements and ICAO Annex 3 provisions on automated weather observing systems shape North American procurement specifications, while EASA CS-ADR-DSN standards and EU Green Deal atmospheric monitoring mandates drive European environmental monitoring deployments. China's GB/T 33694 national standard for ground-based remote sensing of clouds and the country's dual carbon goals are expanding domestic ceilometer demand for pollution tracking applications. Stakeholders must monitor evolving certification reciprocity between national aviation authorities and emerging solid-state reliability benchmarks that could reset competitive positioning across supplier tiers.
Market Dynamics
Solid-state laser reliability is compressing replacement cycles across aviation and meteorological installations, forcing incumbent suppliers to recertify platforms faster than historical five-to-seven-year intervals.
Growth Catalysts
- ICAO Annex 3 Visibility Standards:Tightened provisions on automated weather observing systems mandate ceilometer deployment at secondary airports across Germany, Japan, and Brazil.
- East Asian Airport Infrastructure:Greenfield terminal construction in China and South Korea specifies integrated ceilometer-weather radar architectures for simultaneous cloud-base and wind-shear monitoring.
- Fiber Laser Eye-Safety:Extended-range variants enable military surveillance applications previously inaccessible to conventional solid-state units, opening defense procurement channels.
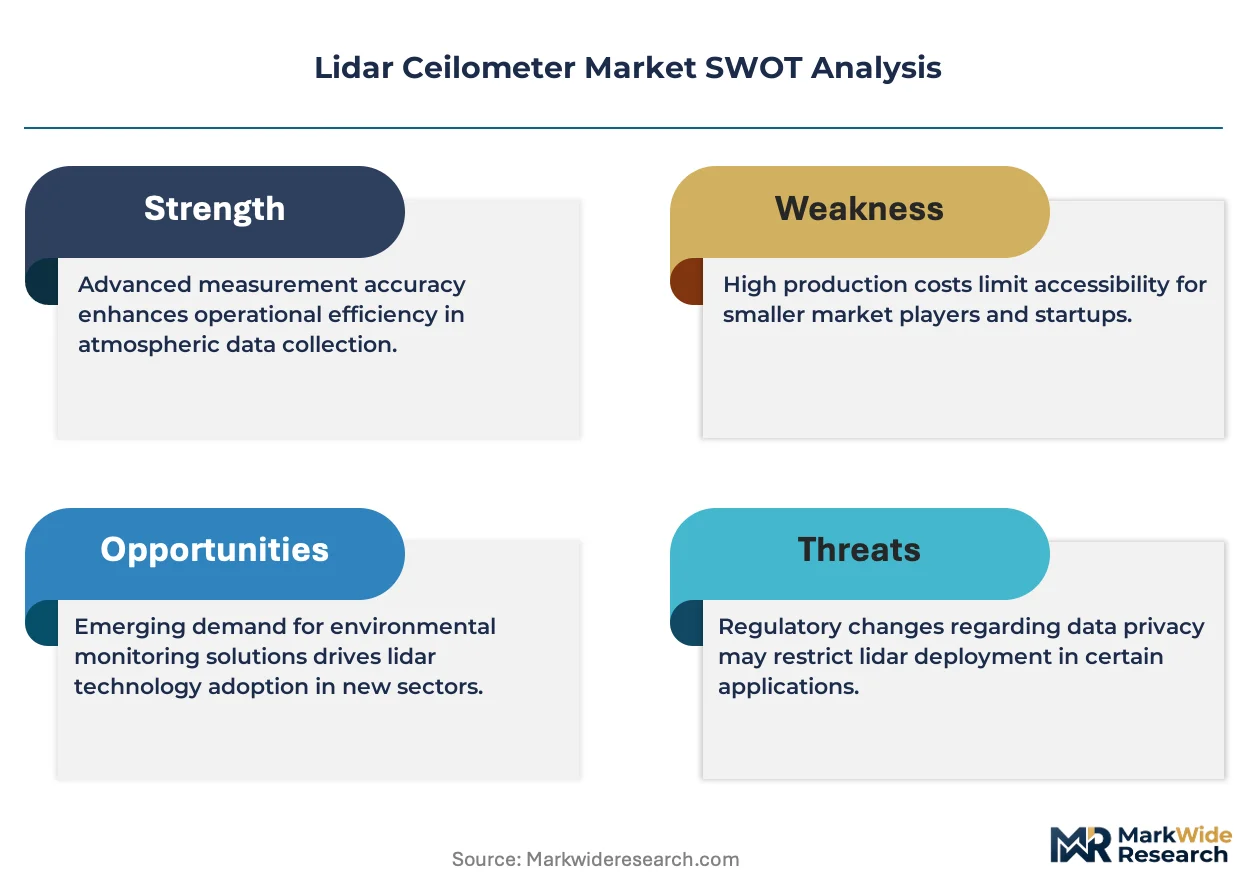
Market Restraints
- Precision Optics Supply Concentration:German and Japanese optical component suppliers control critical diode laser substrate availability, exposing downstream assemblers to allocation risk.
- ISO 17025 Recertification Burden:Atmospheric measurement instrument accreditation requires 18-24 month validation cycles that freeze supplier eligibility during network expansion tenders.
- Terminal Doppler Weather Radar Substitution:FAA-integrated TDWR systems at major US hubs reduce standalone ceilometer demand for primary visibility measurement.
Strategic Opportunities
- EU Green Deal Atmospheric Grids:National environmental monitoring networks across France, Poland, and Spain require ceilometer densification for aerosol tracking and carbon verification protocols.
- Portable Emergency Response:Wildfire management agencies in Australia and California are procuring trailer-mounted units for rapid smoke plume height assessment.
- China Dual Carbon Monitoring:GB/T 33694-compliant ceilometer networks track industrial pollution dispersion, aligning with provincial emissions accounting requirements.
Industry Challenges
- Atmospheric Physicist Talent Scarcity:Interpretation of backscatter profiles requires specialized expertise that outpaces university program output in lidar remote sensing.
- Aviation Authority Certification Reciprocity Gaps:Divergent FAA, EASA, and CAAC test protocols force redundant validation for multi-national supplier contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidar Ceilometer Market |
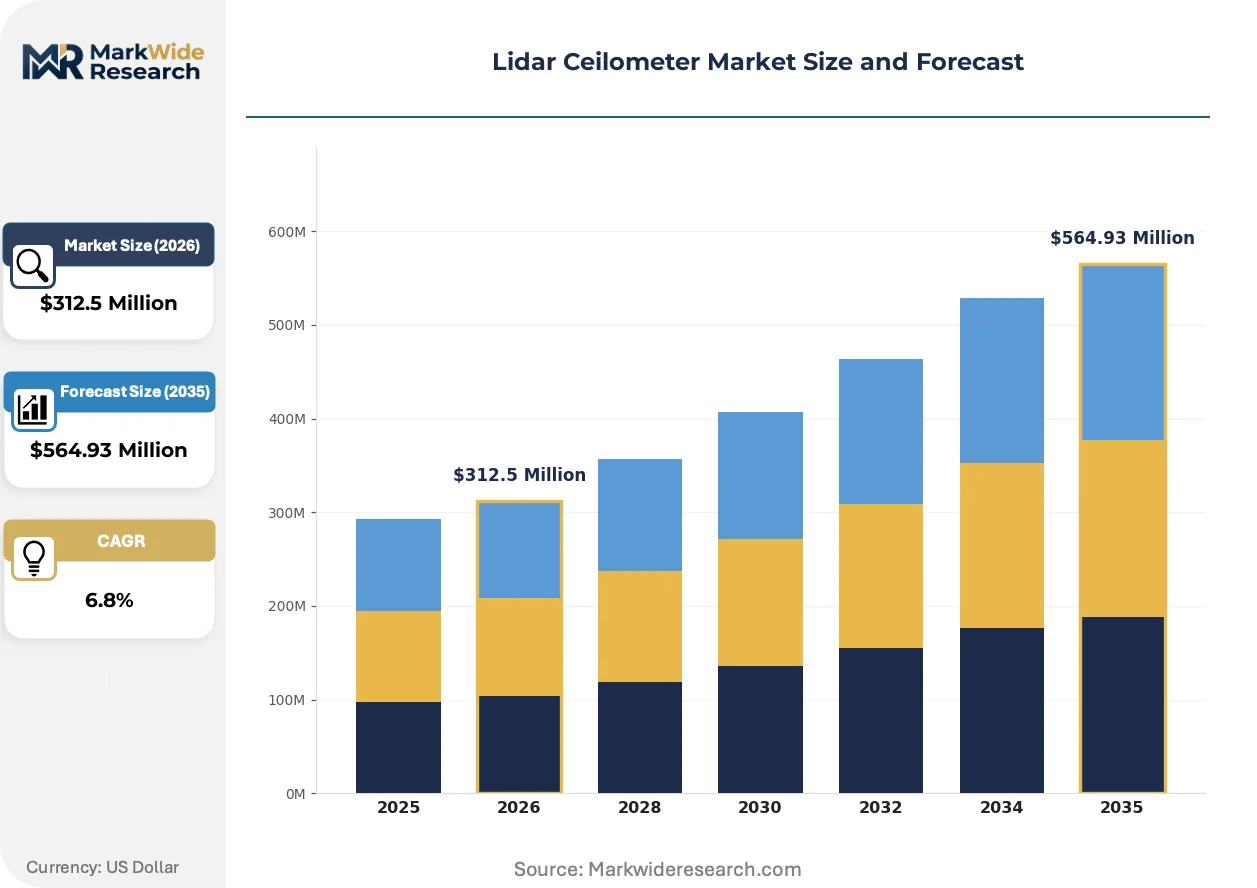
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Mount, Portable, Scanning, Targeted Beam Technology: Solid State, Fiber Laser, Diode Laser, Microelectromechanical Systems Application: Air Traffic Control, Meteorological Research, Environmental Monitoring, Military Surveillance End User: Meteorological Agencies, Aviation Authorities, Defense Organizations, Academic Institutions |
| Companies Covered | Jenoptik AG, Raymetrics, Vaisala Corporation, OTT HydroMet, Biral, Campbell Scientific, Leosphere, Teledyne Optech, Lufft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidar Ceilometer Market Trends and Innovations
Three concurrent shifts are restructuring competitive advantage: laser source architecture, regulatory harmonization pressure, and procurement centralization among national meteorological services.
Fiber laser transmitters are displacing flashlamp-pumped solid-state sources in research-grade deployments. Atmospheric science institutes in Switzerland and the Netherlands specify eye-safe 1.5-micron operation for unattended urban monitoring. This wavelength migration is compressing price premiums between aviation-certified and research-tier hardware.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent cooling system obsolescence in legacy ceilometer designs. Manufacturers must redesign thermal management around thermoelectric or passive architectures to maintain CE marking eligibility. German environmental monitoring tenders now exclude equipment with synthetic refrigerant circuits.
Consolidated procurement by national meteorological services is eliminating distributor intermediaries across European and East Asian markets. Direct manufacturer contracting with Deutscher Wetterdienst, Japan Meteorological Agency, and China Meteorological Administration now governs volume allocation and service-level agreements. This channel compression rewards in-house calibration capability and penalizes assembly-only suppliers.
Lidar Ceilometer Market Segmentation
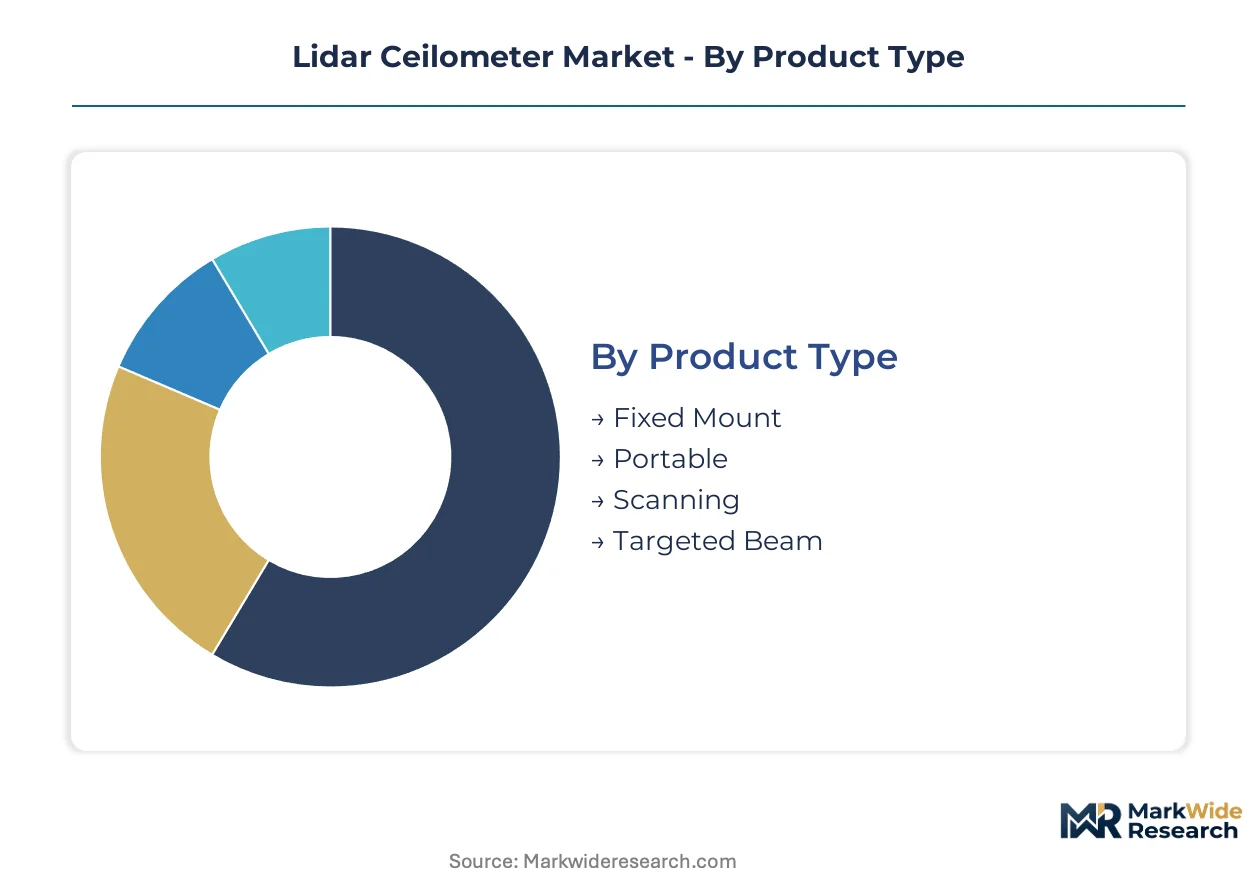
Lidar ceilometer procurement patterns diverge sharply across installation permanence, laser architecture, and institutional end-use. Regulatory certification requirements from FAA, EASA, and CAAC create distinct eligibility tiers that reshape competitive positioning within each segment.
Product Type:
ICAO Annex 3 mandates differentiate procurement specifications between permanent aviation installations and deployable field units.
- Fixed Mount:Permanent installations integrate with automated weather observing systems at commercial airports. Demand concentrates in Germany and Japan where meteorological agencies are modernizing secondary airport networks under tightened visibility standards.
- Portable:Trailer-mounted or vehicle-integrated units enable rapid deployment for wildfire smoke assessment and emergency response. Australian and California agencies are expanding procurement for plume height monitoring during active fire seasons.
- Scanning:Articulated beam architectures support research-grade atmospheric boundary layer studies. Academic institutions in the Netherlands and Switzerland specify these for urban climate monitoring.
- Targeted Beam:Narrow divergence optics focus on specific atmospheric layers for specialized aerosol tracking applications. China's provincial environmental bureaus deploy these for industrial dispersion modeling under dual carbon accounting protocols.
Established volume favors Fixed Mount; emerging adoption favors Portable.
Technology:
Thermal stability and maintenance intervals determine total cost of ownership across aviation and environmental monitoring contracts.
- Solid State:Flashlamp-pumped Nd:YAG sources dominate commercial aviation installations due to proven reliability. FAA-integrated Terminal Doppler Weather Radar specifications favor these for primary visibility measurement at US hubs.
- Fiber Laser:Eye-safe 1.5-micron operation enables unattended urban monitoring and extended-range military surveillance. Defense procurement channels in South Korea and Japan are expanding for perimeter security applications.
- Diode Laser:Compact semiconductor sources reduce footprint for portable and drone-integrated deployments. Field campaign coordinators prioritize these for rapid atmospheric profiling.
- Microelectromechanical Systems:MEMS-based beam steering miniaturizes optical assemblies for distributed sensor networks. Research consortia are piloting these for high-density urban air quality grids.
Aviation certification concentrates procurement toward Solid State; research and defense budgets are climbing fastest for Fiber Laser.
Application:
End-use requirements determine range specifications, data output formats, and integration complexity with existing infrastructure.
- Air Traffic Control:Continuous unattended operation with real-time cloud base reporting integrates with airport meteorological systems. Brazil's ANAC is expanding ceilometer networks at regional airports under ICAO compliance programs.
- Meteorological Research:High-resolution backscatter profiling supports numerical weather prediction validation. Deutscher Wetterdienst operates research-grade scanning ceilometers for boundary layer process studies.
- Environmental Monitoring:Aerosol extinction measurements track pollution dispersion and carbon verification. EU Green Deal atmospheric grids in France, Poland, and Spain are driving densification tenders.
- Military Surveillance:Extended-range detection of low-altitude threats and chemical plume identification requires eye-safe operation. Procurement runs through national defense ministries with classified performance specifications.
Air Traffic Control captures the largest installed base; Environmental Monitoring is expanding most quickly under EU regulatory mandates.
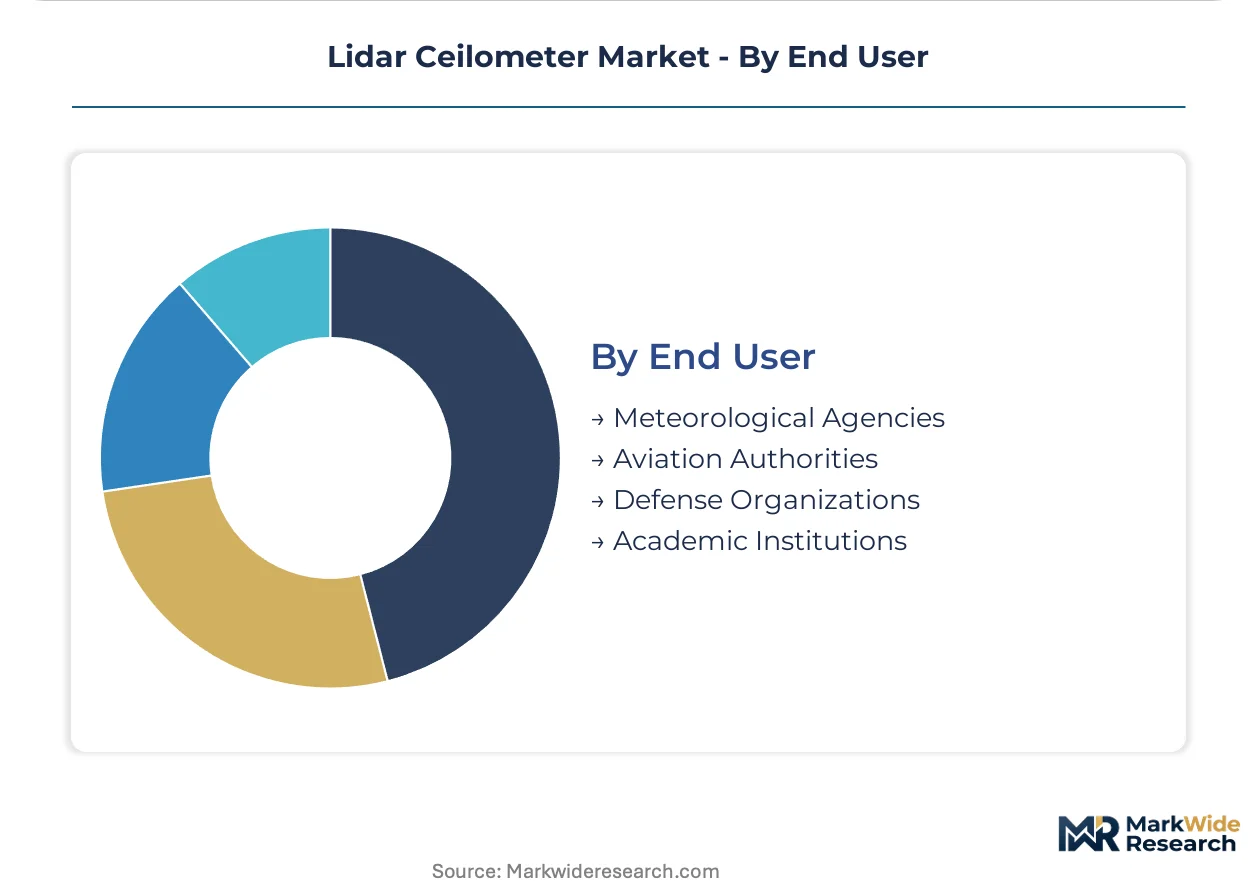
End User:
Procurement centralization among national services is eliminating distributor intermediaries and reshaping contract structures.
- Meteorological Agencies:Consolidated purchasing by Deutscher Wetterdienst, Japan Meteorological Agency, and China Meteorological Administration governs volume allocation. Direct manufacturer contracting now mandates in-house calibration capability.
- Aviation Authorities:FAA, EASA, and CAAC certification reciprocity gaps force redundant validation for multi-national supplier contracts. Secondary airport modernization in Germany and Brazil is accelerating replacement cycles.
- Defense Organizations:Classified range requirements and security clearance protocols limit supplier eligibility. Fiber laser eye-safety specifications are opening new procurement channels previously closed to conventional solid-state units.
- Academic Institutions:Research grants from atmospheric science programs fund specialized scanning architectures. Universities in Switzerland and the Netherlands specify 1.5-micron operation for unattended urban monitoring stations.
Meteorological Agencies anchor procurement volume; Defense Organizations are gaining share fastest as fiber laser reliability meets surveillance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meteorological agencies and aviation authorities concentrate procurement across Germany, Japan, China, the United States, and Brazil, with each market shaped by distinct certification regimes and infrastructure investment cycles.
Germany
Deutscher Wetterdienst modernization of secondary airport networks drives fixed-mount ceilometer deployment under tightened ICAO Annex 3 visibility standards. The EU F-Gas Regulation accelerates thermal management redesigns for CE marking eligibility. Bavarian precision optics clusters supply critical diode laser substrates to domestic and European assemblers.
Japan
Japan Meteorological Agency expansion of automated weather observing systems at regional airports creates sustained demand for solid-state units. METI procurement guidelines emphasize domestic manufacturing content and long-term service agreements. Tokyo-Osaka aviation corridors concentrate installation activity for integrated ceilometer-weather radar architectures.
China
China Meteorological Administration procurement aligns with GB/T 33694 national standards for ground-based cloud remote sensing and provincial dual carbon monitoring mandates. MEE atmospheric grids in the Yangtze River Delta and Pearl River Delta deploy targeted-beam configurations for industrial pollution tracking. State-directed tendering favors domestic certification reciprocity with CAAC aviation specifications.
United States
FAA Terminal Doppler Weather Radar integration requirements shape procurement at major hubs, while secondary airports sustain standalone ceilometer demand. EPA environmental monitoring grants fund portable units for wildfire smoke assessment in California and Pacific Northwest field campaigns. Midwest research institutions anchor academic scanning ceilometer deployment for boundary layer studies.
Brazil
ANAC regional airport modernization under ICAO compliance programs accelerates replacement cycles for legacy visibility measurement systems. National environmental monitoring expansion in São Paulo and Rio de Janeiro industrial corridors drives aerosol tracking applications. Procurement runs through consolidated meteorological agency tenders with emphasis on tropical climate operational reliability.
Lidar Ceilometer Market Competitive Landscape
Player mix skews toward vertically integrated European and East Asian specialists with in-house laser source and precision optics capabilities. Market structure concentrates around three archetypes: aviation-certified system integrators with meteorological agency heritage, research-grade scanning architecture specialists, and portable deployment innovators serving emergency response agencies. Dominant competitive moves include backward integration into diode laser substrate production and direct manufacturer contracting with national meteorological services that eliminates distributor intermediaries.
Among aviation-certified system integrators, Vaisala Corporation and Jenoptik AG exemplify the vertically integrated archetype with in-house manufacturing bases and long-term agency contract structures. Raymetrics occupies a specialist position within the research-grade scanning segment, anchoring competitive positioning through articulated beam architectures for atmospheric boundary layer studies. These three entities represent the tiering between mass-deployment aviation contracts and precision research instrumentation.
| Leading Market Players |
|---|
| Jenoptik AG |
| Raymetrics |
| Vaisala Corporation |
| OTT HydroMet |
| Biral |
| Campbell Scientific |
| Leosphere |
| Teledyne Optech |
| Lufft |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Bavarian precision optics clusters shapes both diode laser substrate availability and floor prices for downstream assemblers. German and Japanese optical component suppliers leverage scale economies to enforce minimum order quantities that compress margin flexibility for assembly-only competitors.
Pricing Analysis
Cost-plus contracts with diode laser substrate indexation dominate long-term meteorological agency agreements. Three-tier pricing structure across aviation-certified, research-grade, and portable emergency-response levels separates procurement tiers by ISO 17025 validation burden and thermal management complexity. Cost compression in solid-state aviation units is intensifying because FAA-EASA certification reciprocity gaps force redundant validation spend. National meteorological services exhibit lowest price sensitivity due to consolidated tender structures, while portable emergency-response agencies in Australia and California prioritize acquisition cost over total cost of ownership.
Supply Chain Analysis
Strait of Hormuz transit exposure for rare-earth optical dopants underwrites supply fragility in Nd:YAG crystal feedstock. German, Japanese, and Chinese suppliers concentrate diode laser substrate, precision optical coatings, and thermoelectric cooling module production. Raw material dependencies rest on yttrium aluminum garnet boules, fused silica optics, and indium phosphide laser diodes. Single-source vulnerability in flashlamp-pumped solid-state transmitter assemblies creates allocation risk during aviation network expansion cycles. Distribution runs through direct manufacturer contracting with Deutscher Wetterdienst, Japan Meteorological Agency, and China Meteorological Administration that eliminates distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lidar ceilometer deployment sits in early-cycle expansion as EU Green Deal atmospheric monitoring mandates and ICAO Annex 3 visibility standard tightening create simultaneous aviation and environmental procurement channels.
For Market Incumbents: Secure long-term calibration service agreements with national meteorological services to lock out assembly-only competitors. Deepen backward integration into diode laser substrate production to reduce exposure to German and Japanese optical component allocation risk. Fiber laser reliability advances threaten flashlamp-pumped solid-state incumbent positions in research-grade segments. For New Entrants and Emerging Players: Lead with portable emergency-response configurations for wildfire management agencies in Australia and California where procurement cycles are fastest and certification barriers lowest. Target trailer-mounted rapid-deployment units for plume height assessment applications. Partner with atmospheric science institutes for research-grade validation that transfers to aviation certification pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated specialists with in-house laser source and precision optics capabilities. Five-to-ten-year viability favors suppliers with captive calibration infrastructure and direct meteorological agency contract structures. Watch fiber laser reliability benchmarks crossing aviation certification thresholds as the inflection signal for technology substitution risk in solid-state incumbent positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Laser Substrates | Captive supply of precision optics reduces allocation exposure from German and Japanese component suppliers. |
| Direct Manufacturer Contracting with National Meteorological Services | Eliminates distributor intermediaries and locks in volume allocation through multi-year service-level agreements. |
| Fiber Laser Aviation Certification Investment | Eye-safe 1.5-micron operation opens military surveillance and unattended urban monitoring procurement channels. |
| Portable Emergency Response Product Line Expansion | Trailer-mounted configurations capture fastest-growing demand from Australian and California wildfire management agencies. |
| In-House Calibration Capability Development | ISO 17025 accreditation enables eligibility for consolidated meteorological agency tenders across Europe and East Asia. |
Research Methodology
Cross-validation between primary interviews with meteorological agency procurement officers, aviation authority certification engineers, and atmospheric science researchers anchors the qualitative findings. Secondary validation draws from ICAO Annex 3 implementation reports, EU Green Deal atmospheric monitoring tender databases, GB/T 33694 standard documentation, and national meteorological service capital expenditure disclosures. Bottom-up unit deployment tracking triangulates against top-down market sizing derived from laser source manufacturer shipment data.
Sensitivity analysis across solid-state versus fiber laser adoption trajectories tests forecast robustness over the projection horizon. Segmentation dimensions modeled include installation permanence, laser architecture, application end-use, and institutional buyer type. CAGRs derive from fitted adoption curves calibrated to historical aviation certification cycle timing and environmental monitoring grid densification patterns. Forecast inputs incorporate ICAO visibility standard implementation schedules and EU F-Gas Regulation thermal management redesign requirements.
Forecasts assume regulatory continuity in FAA, EASA, and CAAC certification regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as fiber laser reliability benchmarks and aviation authority certification reciprocity negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Global Pressure Calibrators Market