
 MEMS Pressure Sensors Market | 2026-2036
MEMS Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Pressure Sensors Market Outlook
EU F-Gas Regulation is pivoting refrigerant system monitoring requirements toward leak-detection-grade pressure fidelity. Bosch Sensortec leverages captive MEMS foundry capacity to anchor automotive absolute pressure supply chains. Infineon Technologies differentiates through ASIL-compliant automotive qualification protocols. STMicroelectronics sustains broad industrial diversification across gauge and differential product lines.
MEMS pressure sensors integrate micromachined silicon diaphragms with piezoresistive or capacitive transduction elements to measure fluid or gas pressure differentials across ranges from millibars to hundreds of bars. These devices fabricate through bulk micromachining or surface micromachining processes on silicon wafers, enabling batch production at semiconductor-scale economies. Absolute sensors dominate automotive intake manifold and barometric applications where vacuum-referenced measurement supports engine control algorithms. Capacitive technology captures altitude-critical aerospace and weather monitoring deployments demanding superior long-term stability. Digital sensors with integrated signal conditioning are displacing analog outputs in HVAC and industrial equipment where microcontroller direct interfacing reduces bill-of-material complexity.
FDA device classification for implantable pressure monitors shapes healthcare segment entry pathways and clinical trial obligations. EPA emissions enforcement in the United States and MEE air quality mandates in China both tighten automotive on-board diagnostic thresholds, directly expanding sensor specification requirements. ISO 26262 functional safety standards govern automotive supplier qualification, filtering non-compliant vendors from tier-one procurement lists. Stakeholders must monitor evolving automotive electrification thermal management architectures, as battery pack pressure balancing introduces sensor count multiplication distinct from legacy internal combustion paradigms.
Market Dynamics
Automotive electrification is compressing sensor specification cycles as battery thermal management architectures demand manifold-grade pressure fidelity across cooling loops previously absent in combustion drivetrains.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant leak-detection mandates in commercial HVAC systems are mandating sub-millibar resolution sensors for environmental compliance monitoring across European climate zones.
- Silicon piezo-resistive technology:Mature foundry compatibility in Taiwan and South Korea enables cost-down trajectories for automotive absolute pressure modules at semiconductor-scale economies.
- China MEE air quality enforcement:On-board diagnostic thresholds for evaporative emissions are tightening specification windows for fuel tank pressure sensors in domestic vehicle production.
Market Restraints
- 300mm wafer supply concentration:MEMS-specific silicon processing capacity clusters in East Asian foundry networks, exposing automotive supply chains to geographic risk concentration.
- ISO 26262 ASIL-D certification timelines:Functional safety qualification protocols for brake-system pressure sensors extend development cycles by 18-24 months versus industrial-grade equivalents.
- Capacitive transduction cost premium:Superior long-term stability in aerospace barometric applications comes at 3-4x unit cost versus piezoresistive alternatives, limiting addressable market expansion.
Strategic Opportunities
- India PLI scheme for automotive components:Production-linked incentives for advanced driver-assistance systems are creating domestic manufacturing pull for tire pressure monitoring sensors.
- Digital output integration:I2C and SPI protocol sensors with onboard signal conditioning are capturing HVAC controller sockets previously served by analog-output discrete components.
- Battery pack pressure balancing:Thermal runaway detection architectures in electric vehicles are introducing redundant sensor nodes per module, multiplying unit counts beyond legacy engine bay densities.
Industry Challenges
- MEMS process engineer scarcity:Bulk micromachining expertise for diaphragm formation concentrates in legacy semiconductor hubs, constraining foundry expansion in emerging manufacturing regions.
- FDA 510(k) pathway complexity:Implantable pressure monitor submissions require clinical evidence packages that extend healthcare segment entry timelines versus industrial qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Pressure Sensors Market |
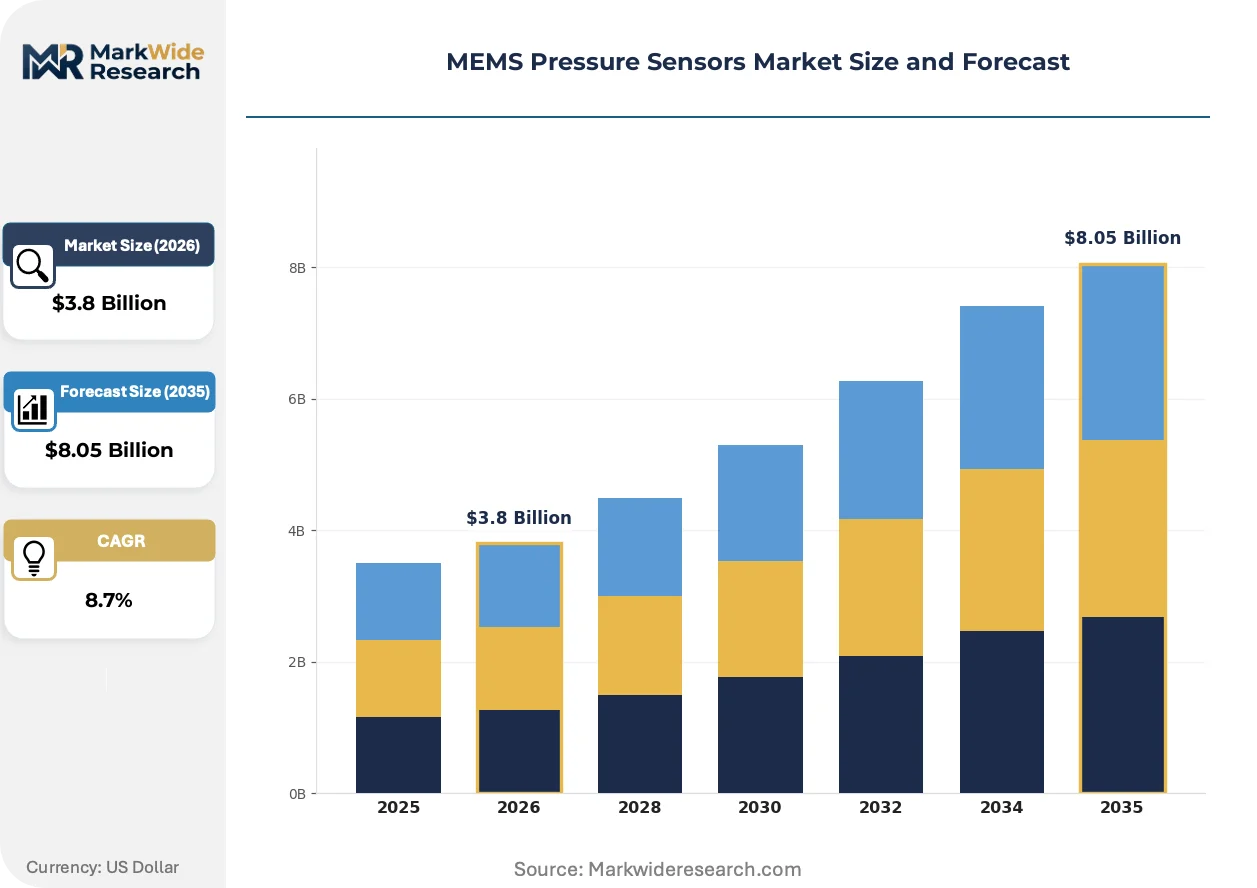
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Gauge Sensors, Differential Sensors, Digital Sensors Technology: Silicon Piezo-resistive, Capacitive, Piezoresistive, Optical End User: Aerospace, Automotive, Healthcare, Industrial Equipment Application: Oil & Gas, Weather Monitoring, Manufacturing, HVAC |
| Companies Covered | ROHM Semiconductor, Bosch Sensortec, Infineon Technologies, Analog Devices, Sensata Technologies, Murata Manufacturing Co. Ltd., STMicroelectronics, TDK Corporation, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Pressure Sensors Market Strategic Shifts
Sensor fusion architectures and edge-native signal processing are compressing the value chain between raw transduction and system-level control decisions.
Capacitive MEMS pressure sensing is electrifying altitude-critical applications through superior temperature coefficient performance. Aerospace barometric systems and weather monitoring stations are adopting these devices for 10-year stability specifications. The technology is electrifying long-haul drone navigation and stratospheric balloon payloads where drift tolerance exceeds piezoresistive capabilities.
EPA emissions enforcement is tightening evaporative system monitoring thresholds for light-duty vehicles. Manufacturers must deploy higher-fidelity fuel tank pressure sensors to detect 0.5mm leak equivalents under OBD-II diagnostics. The mandate is compressing specification windows for domestic Tier-1 suppliers serving Detroit automotive programs.
Direct microcontroller interfacing is displacing analog signal conditioning chains in building automation controllers. HVAC original equipment manufacturers are specifying digital-output pressure sensors to eliminate operational amplifier stages from printed circuit board designs. This pattern concentrates in European commercial heating system retrofits where controller replacement cycles accelerate hardware refresh timelines.
MEMS Pressure Sensors Market Segmentation
MEMS pressure sensor procurement patterns diverge sharply across certification regimes. ISO 26262 ASIL grades govern automotive supplier qualification, while FDA 510(k) pathways filter healthcare entrants. Understanding segment-specific compliance burdens clarifies margin structures and competitive moats.
Product Type:
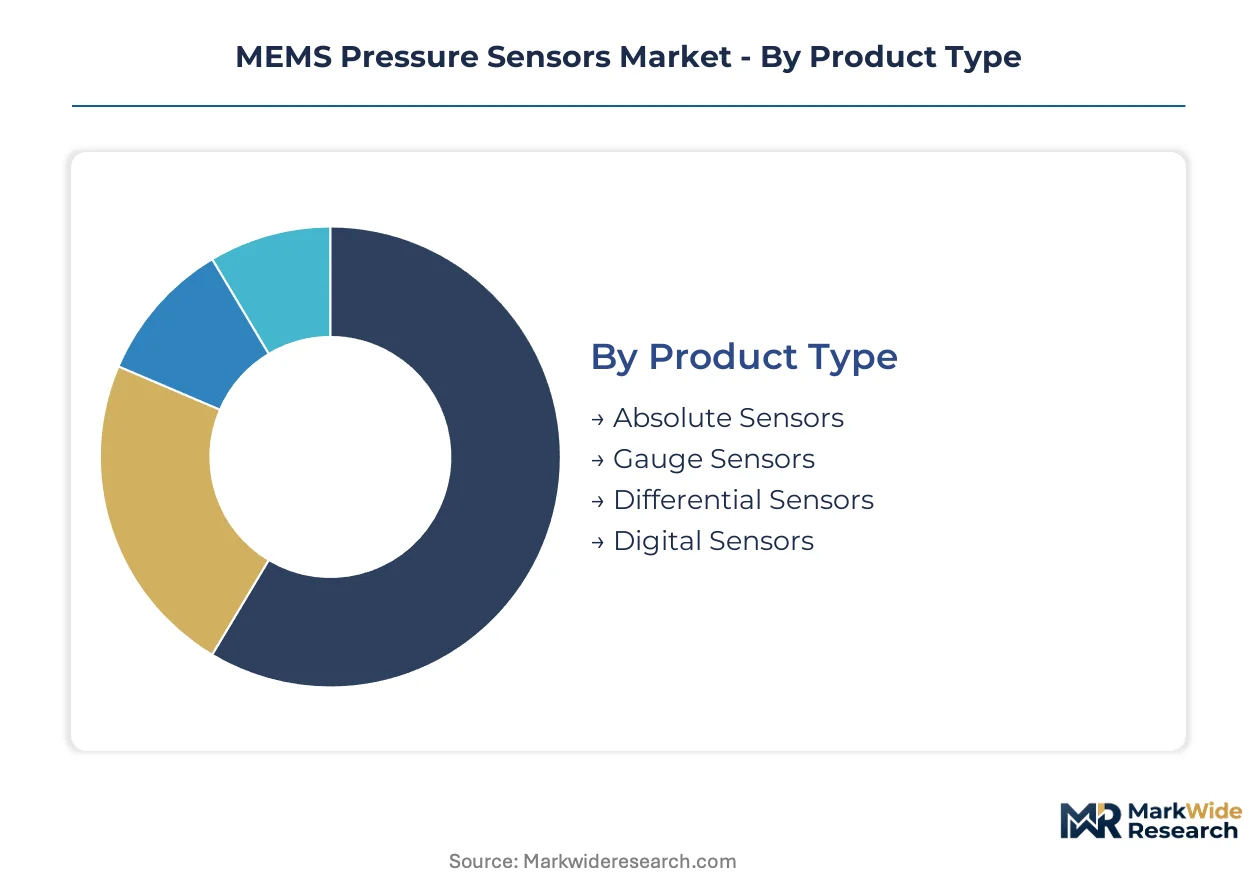
Certification intensity varies dramatically across product architectures. Absolute sensors face the steepest automotive functional safety requirements, while digital variants encounter FCC and CE electromagnetic compliance testing.
- Absolute Sensors:Vacuum-referenced diaphragms measure pressure against sealed cavities. Automotive intake manifold and barometric applications in Germany and China concentrate demand, driven by electrification thermal management architectures requiring manifold-grade fidelity.
- Digital Sensors:Integrated signal conditioning outputs I2C or SPI protocols directly to microcontrollers. HVAC controller sockets across European commercial heating retrofits are displacing analog-output discrete components to eliminate operational amplifier stages from PCB designs.
- Gauge Sensors:Ambient-pressure-referenced devices serve industrial process monitoring where atmospheric baseline compensation suffices.
- Differential Sensors:Twin-port architectures measure pressure gradients across flow restrictions in medical ventilators and HVAC air handling units.
Absolute sensors sit at the top of the volume ranking, with digital sensors climbing the fastest.
Technology:
Cost tier stratification separates mature foundry-compatible processes from precision aerospace alternatives. Taiwan and South Korea foundry networks anchor volume economics for silicon-based approaches.
- Silicon Piezo-resistive:Boron-doped strain gauges on micromachined diaphragms leverage CMOS-compatible processing. Mature 200mm foundry capacity in Taiwan enables cost-down trajectories for automotive absolute pressure modules at semiconductor-scale economies.
- Capacitive:Electrostatic gap variation between diaphragm and fixed electrode achieves superior temperature coefficient performance. Aerospace barometric systems and weather monitoring stations in Japan and Switzerland specify these devices for 10-year stability requirements.
- Piezoresistive:Polysilicon or metal strain elements on ceramic or steel substrates serve industrial applications demanding media compatibility beyond silicon limits.
- Optical:Fiber Bragg grating or interferometric readouts isolate electronics from hazardous media in oil & gas downhole monitoring.
Silicon piezo-resistive technology commands the dominant share, though capacitive approaches gain share fastest in altitude-critical deployments.
End User:
Application-specific qualification protocols create divergent entry barriers. Automotive ASIL-D certification timelines extend 18-24 months beyond industrial-grade equivalents.
- Automotive:Manifold absolute pressure, fuel tank evaporative emissions, and tire pressure monitoring systems face tightening EPA and China MEE diagnostic thresholds. Battery pack pressure balancing in electric vehicles multiplies sensor counts beyond legacy engine bay densities.
- Healthcare:Implantable pressure monitors require FDA 510(k) clinical evidence packages. Non-invasive applications such as ventilator flow sensing face shorter regulatory pathways but stringent biocompatibility standards.
- Industrial Equipment:Process automation and hydraulic monitoring demand IP67+ ingress protection and chemical compatibility certifications.
- Aerospace:DO-160 environmental qualification and long-term stability specifications filter supplier bases to established avionics component manufacturers.
Automotive end-use dominates current procurement volumes, with healthcare applications expanding most quickly through minimally invasive surgical device adoption.
Application:
Geographic regulatory enforcement patterns concentrate demand in specific climate zones and industrial corridors. EU F-Gas Regulation mandates drive European HVAC specifications distinct from North American or Asian requirements.
- HVAC:Commercial refrigerant leak-detection systems require sub-millibar resolution sensors for EU F-Gas environmental compliance monitoring. Building automation controllers specify digital-output variants to enable microcontroller direct interfacing.
- Manufacturing:Pneumatic system pressure monitoring and quality control leak testing consume gauge and differential sensors across automotive and electronics assembly lines in Germany, Japan, and South Korea.
- Oil & Gas:Downhole pressure monitoring and pipeline integrity sensing deploy ruggedized piezoresistive or optical technologies rated for high-temperature hydrocarbon exposure.
- Weather Monitoring:Barometric pressure stations and radiosonde balloon payloads specify capacitive MEMS for minimal drift over stratospheric temperature excursions.
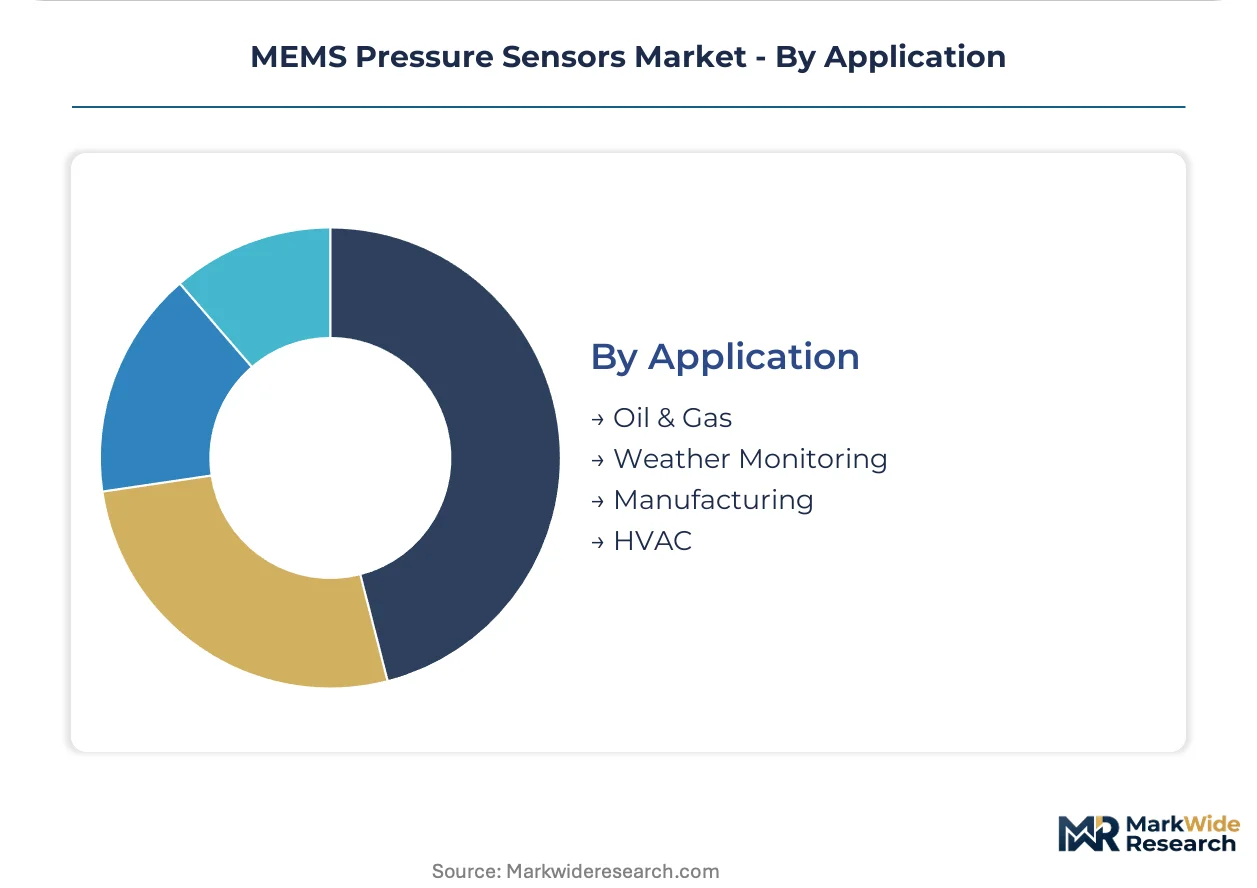
HVAC applications lead in unit volume terms, with weather monitoring gaining share fastest through long-haul drone and high-altitude balloon navigation system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMS pressure sensor fabrication traces its industrial lineage to 1980s silicon micromachining breakthroughs at Stanford University and subsequent scaling through Japanese electronics conglomerates. Taiwan and South Korea later captured foundry economics, anchoring contemporary supply chains. Geographic demand patterns now reflect automotive electrification corridors and HVAC regulatory enforcement zones.
Germany
Automotive electrification programs in Baden-Württemberg and Bavaria accelerate demand for manifold absolute pressure modules in battery thermal management systems. KBA enforcement of EU F-Gas Regulation drives refrigerant leak-detection sensor specifications for commercial HVAC retrofits. Stuttgart and Munich industrial clusters host tier-one supplier engineering centers calibrating ASIL-compliant automotive qualification protocols.
China
Domestic vehicle production in Shanghai and Guangdong provinces tightens evaporative emissions monitoring under MEE air quality mandates. MIIT industrial policy directs semiconductor manufacturing investment toward MEMS-specific 200mm wafer capacity in Jiangsu and Zhejiang foundry networks. Yangtze River Delta electronics corridors concentrate sensor packaging and test operations serving domestic automotive OEM procurement.
United States
EPA emissions enforcement compresses OBD-II diagnostic thresholds for fuel tank pressure sensors in Detroit automotive programs. FDA device classification pathways shape healthcare segment entry for implantable pressure monitors developed in Massachusetts and Minnesota medical device corridors. Silicon Valley fabless design houses specialize in digital-output sensor architectures for HVAC controller sockets.
South Korea
MFDS regulatory frameworks govern biocompatibility standards for minimally invasive surgical device adoption in Seoul medical technology clusters. Captive MEMS foundry capacity at Samsung and SK Hynix anchors cost-down trajectories for automotive absolute pressure modules. Busan-Ulsan industrial zones supply tire pressure monitoring sensors under India PLI scheme production-linked incentives.
Japan
METI industrial standards capacitive MEMS specifications for aerospace barometric systems demanding 10-year stability. Nagoya automotive supplier networks integrate pressure sensors into thermal runaway detection architectures for electric vehicle battery packs. Tokyo and Osaka precision manufacturing clusters serve weather monitoring station deployments through long-haul drone and stratospheric balloon navigation systems.
MEMS Pressure Sensors Market Competitive Environment
The competitive structure tilts toward diversified semiconductor conglomerates with captive MEMS foundry capacity. Market concentration reflects ASIL-D certification barriers that filter non-compliant vendors from tier-one automotive procurement lists. Three archetypes dominate: integrated device manufacturers with in-house silicon processing, fabless specialists licensing proprietary transduction architectures, and industrial sensor conglomerates diversifying through acquisition. Competitive moves center on backward integration into wafer-level processing and geographic expansion into India PLI scheme jurisdictions.
Among diversified European semiconductor manufacturers, Bosch Sensortec, Infineon Technologies, and STMicroelectronics exemplify integrated-device-manufacturer positioning with automotive qualification depth. Bosch Sensortec occupies a captive-foundry position in Reutlingen. Infineon Technologies anchors ASIL-compliant supply chains through Villach and Dresden manufacturing. STMicroelectronics represents broad industrial diversification across gauge and differential product lines through Agrate and Crolles facilities. Japanese conglomerates Murata Manufacturing and TDK Corporation sit within ceramic-packaging-specialist archetypes. US-based Analog Devices and Sensata Technologies exemplify fabless-plus-test or industrial-automation diversification strategies. ROHM Semiconductor and NXP Semiconductors represent mixed-model competitors with regional foundry partnerships and automotive tier-one relationships.
| Leading Market Players |
|---|
| ROHM Semiconductor |
| Bosch Sensortec |
| Infineon Technologies |
| Analog Devices |
| Sensata Technologies |
| Murata Manufacturing Co. Ltd. |
| STMicroelectronics |
| TDK Corporation |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Captive foundry ownership among diversified semiconductor conglomerates anchors pricing discipline through in-house silicon processing control, insulating tier-one automotive suppliers from spot-market wafer volatility while compressing margin capture for fabless competitors dependent on Taiwan and South Korea foundry slots.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive modules from industrial-grade gauge sensors and unqualified discrete components. Price differentiation hinges on ISO 26262 certification grade and volume scale, with Detroit OEM procurement contracts commanding 40-60% unit cost reductions at million-piece annual offtakes. Cost compression in standard-tier piezoresistive sensors is intensifying because Taiwan foundry capacity expansion outpaces automotive demand growth. Healthcare implantable applications show least price sensitivity due to FDA 510(k) pathway barriers filtering low-cost entrants.
Supply Chain Analysis
India PLI scheme domestic-content mandates are reshaping sourcing patterns for tire pressure monitoring sensors, pulling packaging and test operations from Yangtze River Delta clusters toward Gujarat and Tamil Nadu automotive corridors. MEMS fabrication draws from Taiwan, South Korea, and eastern China foundry networks, with 200mm silicon wafer supply and ceramic packaging substrates constituting critical input dependencies. Single-source vulnerability concentrates in Bosch Reutlingen and Infineon Villach captive facilities serving German OEM absolute pressure demand. Distribution runs through tier-one automotive supplier engineering centers co-located with Stuttgart, Munich, and Shanghai OEM headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas regulatory enforcement tightening HVAC sensor specifications and China MIIT industrial policy subsidizing domestic MEMS foundry investment at 30-40% cost differentials versus European captive production.
For Market Incumbents: Hedge ASIL-D certification concentration risk by qualifying secondary foundry sources in Jiangsu and Zhejiang networks, insulating against Taiwan Strait logistics disruption. Deepen backward integration into ceramic packaging substrate production to capture margin leakage from Murata and TDK ceramic-specialist suppliers facing alumina supply constraints. For New Entrants and Emerging Players: Tier-two HVAC controller manufacturers in Poland and Czech Republic represent the most penetrable channel partner type, as European commercial heating retrofits displace analog-output discrete components. Target digital-output sensor sockets with I2C protocol integration to eliminate operational amplifier stages from PCB designs, exploiting specification windows where incumbent automotive qualification overhead proves uneconomical. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless design houses with proprietary capacitive transduction architectures serving aerospace barometric niches, as long-term stability specifications create 10-year revenue visibility unmatched in industrial segments. Watch MFDS biocompatibility standard acceleration in Seoul medical technology clusters as inflection indicator for minimally invasive surgical device adoption multiplying sensor counts per procedure.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Filters non-compliant vendors from Bosch and Infineon automotive procurement lists. |
| Digital Output Integration | Captures HVAC controller sockets previously served by analog discrete components. |
| India PLI Scheme Manufacturing | Pulls tire pressure monitoring sensor production toward Gujarat automotive corridors. |
| Capacitive Technology Licensing | Addresses 10-year stability specifications in Japan METI aerospace barometric systems. |
| Battery Pack Pressure Balancing | Multiplies sensor counts per electric vehicle module beyond legacy engine bay densities. |
Study Parameters
Multiple input streams — primary interviews with MEMS process engineers and tier-one automotive procurement managers, secondary validation through EPA OBD-II diagnostic filings and China MEE air quality enforcement records, customs data on 200mm wafer trade flows — were reconciled through bottom-up and top-down triangulation. Semiconductor foundry capacity utilization reports, FDA 510(k) submission databases, and ISO 26262 certification registries provided secondary anchors. Stakeholder roles engaged included MEMS fabrication directors, HVAC controller OEM technical specification leads, and implantable device regulatory affairs specialists.
Data-stream reconciliation across product type, technology node, end-use industry, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups cross-checked against foundry capacity expansion schedules and OEM platform sensor count assumptions. Electric vehicle battery thermal management architecture sensor penetration and EU F-Gas refrigerant leak-detection mandate compliance timelines constituted industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan Strait logistics disruption and MIIT industrial policy subsidy continuity. Automotive electrification thermal management specification evolution and FDA implantable device clinical trial obligation tightening represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Europe Air Purifier Market