
 Europe Air Purifier Market | 2026-2036
Europe Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Purifier Market Intelligence
The EU Green Deal is rebalancing procurement priorities across commercial real estate portfolios toward certified air quality systems. Daikin Industries leverages its HVAC integration depth to capture bundled building ventilation contracts. Koninklijke Philips anchors its position through connected-home ecosystems that embed air purification into broader wellness platforms. IQAir specializes in medical-grade filtration architectures that differentiate it in clinical and laboratory verticals.
Air purifiers are electromechanical devices that force ambient air through multi-stage filtration media—typically comprising pre-filters, HEPA layers rated at 99.97% efficiency for 0.3-micron particles, and activated carbon beds—to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed spaces. The residential segment dominates unit volume as European households respond to wildfire smoke intrusions and pollen load intensification. HEPA technology leads the type category due to its established efficacy credentials and regulatory alignment with EN 1822 testing protocols. Activated carbon filtration is gaining share in industrial applications where chemical pollutant removal commands premium pricing.
The European Environment Agency coordinates cross-border air quality monitoring that indirectly validates purification investment returns for building operators. ECHA administers REACH restrictions on filter material chemistries, while CE marking under the MDR framework governs devices marketed with health claims. Stakeholders must monitor how the EU AI Act intersects with emerging smart-purifier algorithms that autonomously adjust filtration intensity based on real-time sensor telemetry.
Market Dynamics
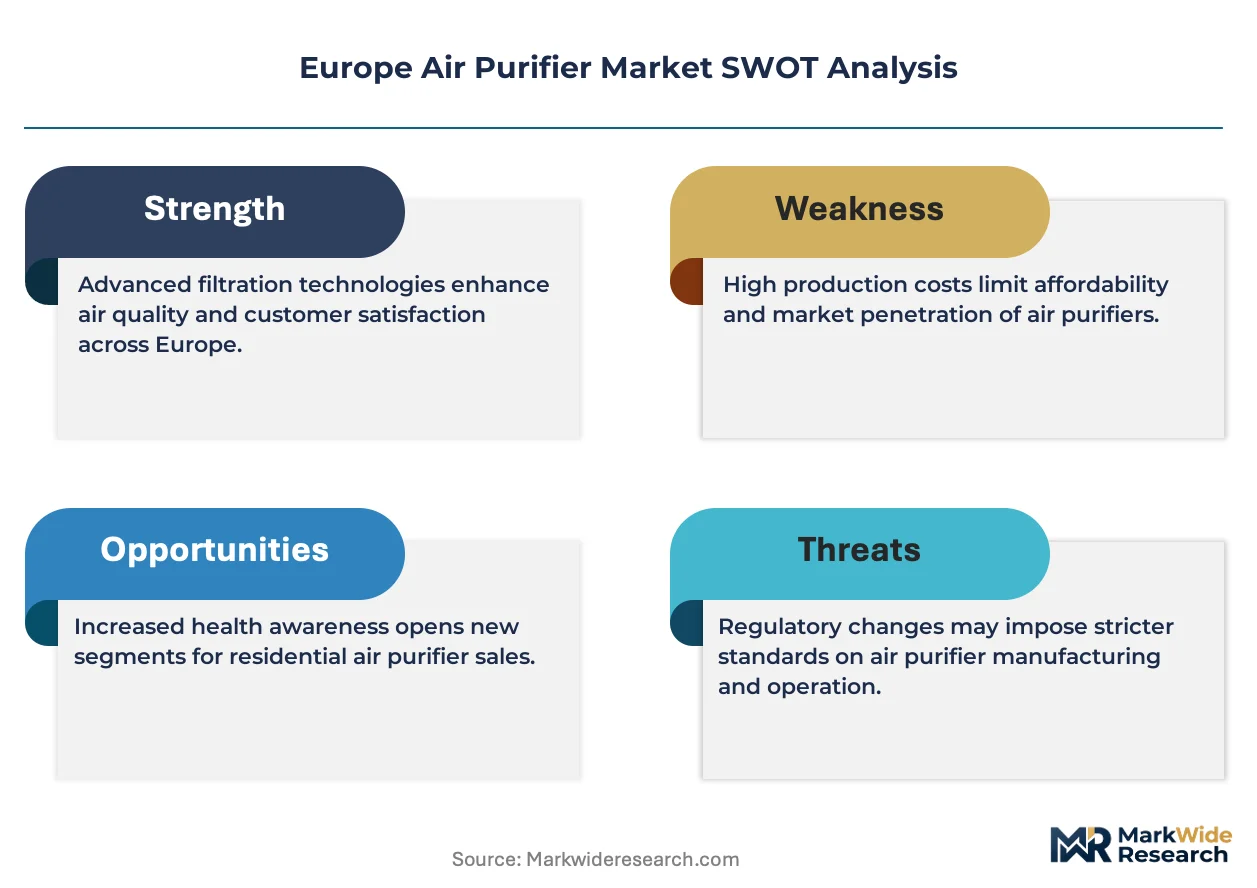
The EU Green Deal's tightening indoor air quality benchmarks are restructuring procurement across European commercial real estate, forcing building operators to retrofit HVAC systems with certified filtration architectures that demonstrate measurable pollutant reduction.
Growth Catalysts
- Wildfire smoke intrusions:Southern European households in Spain and Italy are installing residential units following repeated cross-border smoke events from Iberian and Balkan fire clusters.
- EN 1822 protocol alignment:HEPA filtration systems gain automatic market access across EU member states, eliminating retesting costs for manufacturers.
- Pollen load intensification:German and Austrian urban centers report extended allergy seasons, driving replacement cycles for outdated filtration equipment.
Market Restraints
- Activated carbon input volatility:Coconut shell charcoal supply from Southeast Asian processors faces price instability due to agricultural yield fluctuations.
- Filter material chemistry restrictions:ECHA REACH compliance adds 12-18 month certification timelines for novel nanofiber media.
- Electromechanical component concentration:Fan motor and sensor supply clusters in Chinese manufacturing regions create single-source vulnerability for European assemblers.
Strategic Opportunities
- Netherlands commercial retrofits:Amsterdam and Rotterdam office stock built 1960-1990 requires ventilation upgrades to meet 2030 energy performance standards.
- Sensor-telemetry convergence:Integration of particulate matter and VOC detection with building management systems enables autonomous filtration adjustment.
- EU AI Act alignment:Smart purifiers with algorithmic intensity control can claim regulatory pre-certification for health-claim marketing under MDR frameworks.
Industry Challenges
- CE marking complexity:Devices with health claims require MDR conformity assessment, extending time-to-market by 8-14 months compared to general wellness positioning.
- Legacy HVAC integration:Retrofit installations in Paris and Milan commercial buildings face spatial constraints and ductwork incompatibility with modular purification units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Purifier Market |
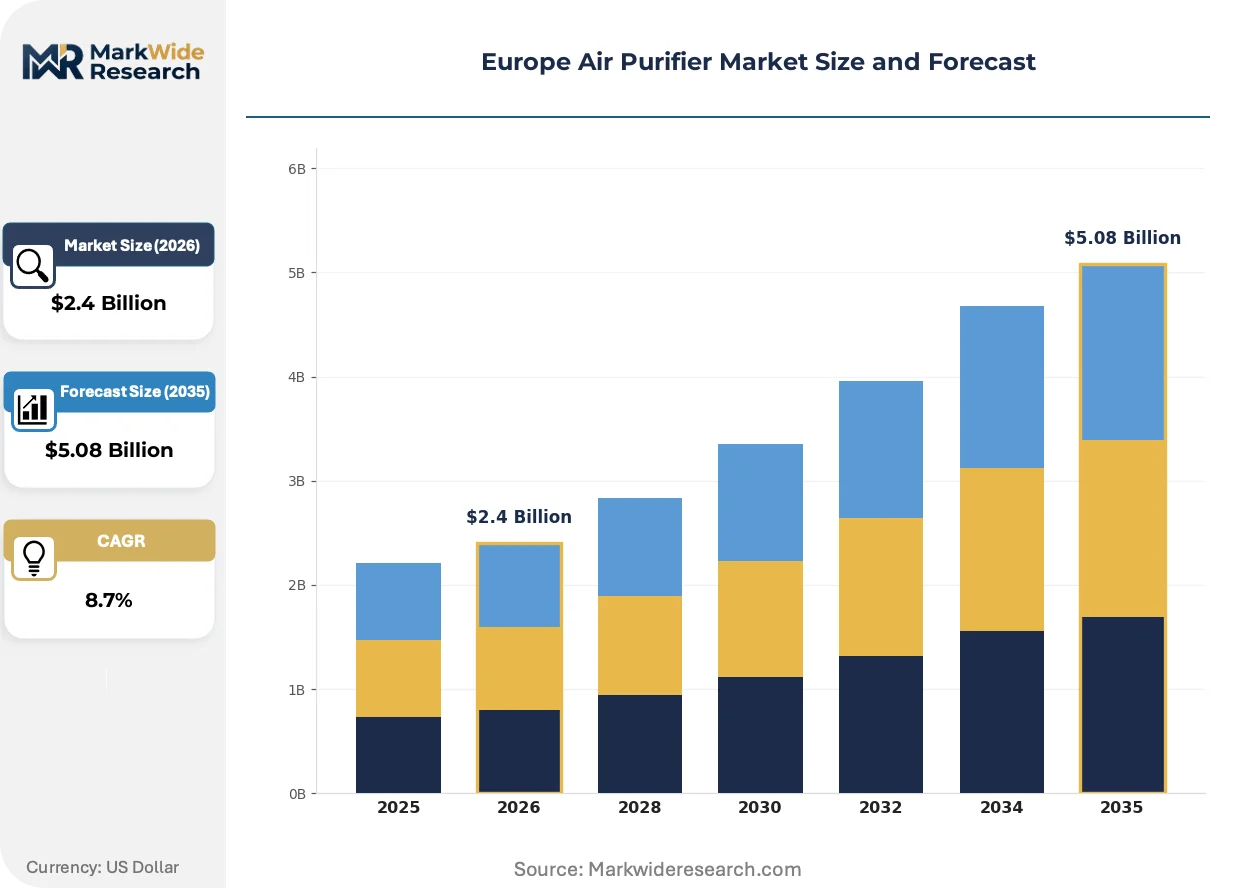
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Usage: Residential, Commercial, Industrial, Automotive Type: HEPA, Activated Carbon, Ionizer, UV-C Technology: Electrostatic, Filtration, Photocatalytic, Ozone Application: Smoke Removal, Allergy Relief, Odor Elimination, Chemical Pollutants |
| Companies Covered | Daikin Industries, Samsung Electronics, Honeywell International, Sharp Corporation, Blueair (Unilever), Koninklijke Philips, IQAir, LG Electronics, Dyson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Purifier Market Strategic Shifts & Innovations
Filtration architectures are converging with building automation systems, creating demand for devices that communicate air quality data directly to facility management platforms rather than operating as standalone appliances.
Photocatalytic oxidation is consolidating as a secondary stage in premium residential units, breaking down formaldehyde and benzene compounds that escape activated carbon adsorption. French and Belgian households in new-construction zones adopt these systems at twice the rate of replacement purchasers. The technology is consolidating market share around chemical-sensitive buyer segments willing to absorb 40-60% unit premiums.
The EU AI Act's risk classification framework is forcing recalibration of smart-purifier algorithm documentation. Manufacturers marketing autonomous sensor-driven adjustment must maintain technical files demonstrating decision transparency and bias mitigation. German and Dutch building operators now require AI Act compliance attestations before specifying connected units for commercial installations.
Facility managers in Nordic countries are unbundling air quality monitoring from equipment procurement, purchasing standalone sensor networks that inform rental decisions rather than owning purification hardware. Stockholm and Copenhagen commercial landlords lead this shift, treating filtration as a utility service contracted through energy performance guarantees. The model compresses equipment sales cycles while extending service contract durations to 7-10 year terms.
Europe Air Purifier Market Segmentation
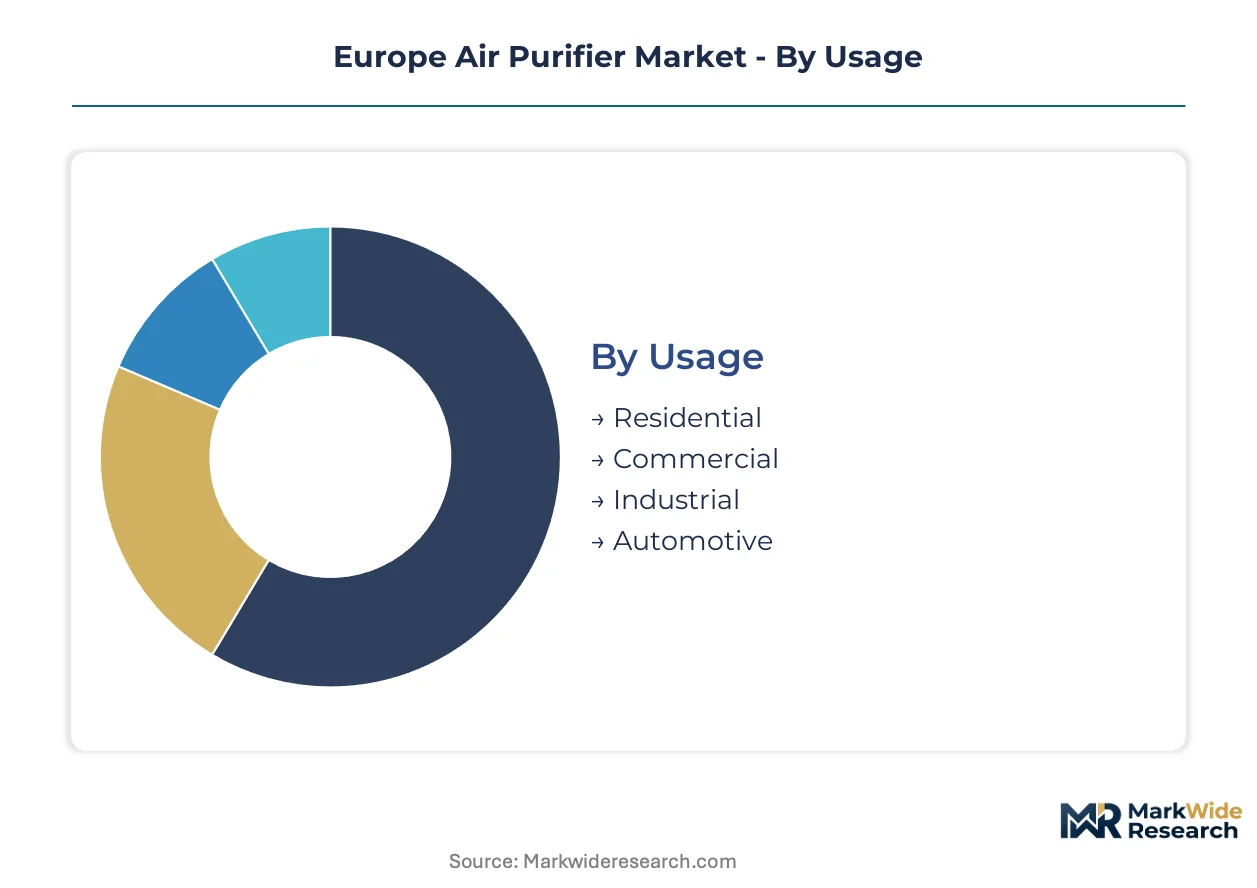
European procurement patterns diverge sharply across usage contexts, with residential buyers prioritizing allergen control while commercial operators optimize for building certification compliance. Industrial purchasers emphasize chemical abatement capabilities that command premium pricing tiers. Understanding these segment boundaries clarifies where technology investments concentrate and which regulatory frameworks govern each buyer class.
Usage:
Cost tier separates these segments more than any other dimension, with capital intensity and operating expenditure profiles diverging by an order of magnitude.
- Residential:Compact electromechanical units designed for single-room coverage, typically employing HEPA-13 filtration with activated carbon pre-stages. German and Austrian urban households drive replacement cycles amid extended pollen seasons and intermittent wildfire smoke intrusions from Iberian fire clusters.
- Commercial:Centralized or distributed systems integrated with building HVAC infrastructure, sized for open-plan offices, retail footprints, and hospitality venues. French and Dutch building operators retrofit 1960-1990 office stock to meet EU Green Deal indoor air quality benchmarks and 2030 energy performance standards.
- Industrial:High-capacity scrubbers and containment systems for manufacturing environments, laboratories, and chemical processing facilities. ECHA REACH compliance for filter material chemistries extends certification timelines but creates barrier-to-entry protection for qualified suppliers.
- Automotive:Cabin air filtration modules factory-integrated or aftermarket-installed, combining particulate and gas-phase removal for enclosed vehicle environments. Cabin air quality regulations under UNECE R122 and consumer sensitivity to urban traffic pollution sustain specification upgrades across European OEM supply chains.
Residential leads volumes today; commercial retrofits are gaining share fastest.
Type:
Technology maturity and regulatory alignment separate these categories, with established standards conferring automatic market access versus emerging approaches facing certification friction.
- HEPA:Fibrous media filters tested to EN 1822 protocols, capturing 99.97% of 0.3-micron particles through mechanical interception and diffusion. Automatic EU-wide recognition eliminates retesting costs, cementing dominance in clinical, laboratory, and premium residential applications where efficacy documentation is mandatory.
- Activated Carbon:Porous carbonaceous media adsorbing VOCs, formaldehyde, and odor compounds through physisorption and chemisorption. Coconut shell charcoal supply volatility from Southeast Asian processors creates input price instability, compressing margins for manufacturers without long-term offtake agreements or alternative feedstock qualification.
- Ionizer:Corona discharge or needle-point electrodes generating charged particles that precipitate onto collection surfaces. Ozone emission concerns under EU biocidal products regulation limit deployment in occupied spaces, restricting application to unoccupied industrial zones and specialized remediation scenarios.
- UV-C:Germicidal ultraviolet irradiation at 253.7 nanometers disrupting microbial DNA in bypass or direct-exposure configurations. Healthcare and food processing verticals specify UV-C stages for pathogen control, though lamp replacement cycles and mercury content regulations under RoHS constrain design flexibility.
HEPA filtration anchors current revenue; photocatalytic-integrated systems are climbing the fastest.
Technology:
Application environment dictates selection, with airborne contaminant chemistry and concentration levels determining which physical mechanisms prove cost-effective.
- Electrostatic:Corona charging of particles followed by collection on oppositely charged plates or grounded surfaces. Washable collection components reduce filter replacement costs in high-dust industrial environments, though ozone generation and maintenance labor requirements limit residential penetration.
- Filtration:Physical barrier separation using fibrous, membrane, or granular media without phase change or chemical reaction. EN 1822 alignment provides regulatory certainty across EU member states, supporting specification in public procurement and healthcare settings where traceable performance documentation is obligatory.
- Photocatalytic:Titanium dioxide or alternative semiconductor surfaces activated by UV or visible light, generating hydroxyl radicals that mineralize organic compounds. French and Belgian new-construction households adopt at twice replacement-purchaser rates, absorbing 40-60% unit premiums for formaldehyde and benzene decomposition capabilities.
- Ozone:Deliberate ozone generation for unoccupied-space remediation of smoke damage, mold, and persistent odors. EU biocidal products regulation and occupational exposure limits restrict commercial deployment to specialized service providers with controlled application protocols.
Filtration technology commands installed base dominance; photocatalytic oxidation shows steepest expansion trajectory.
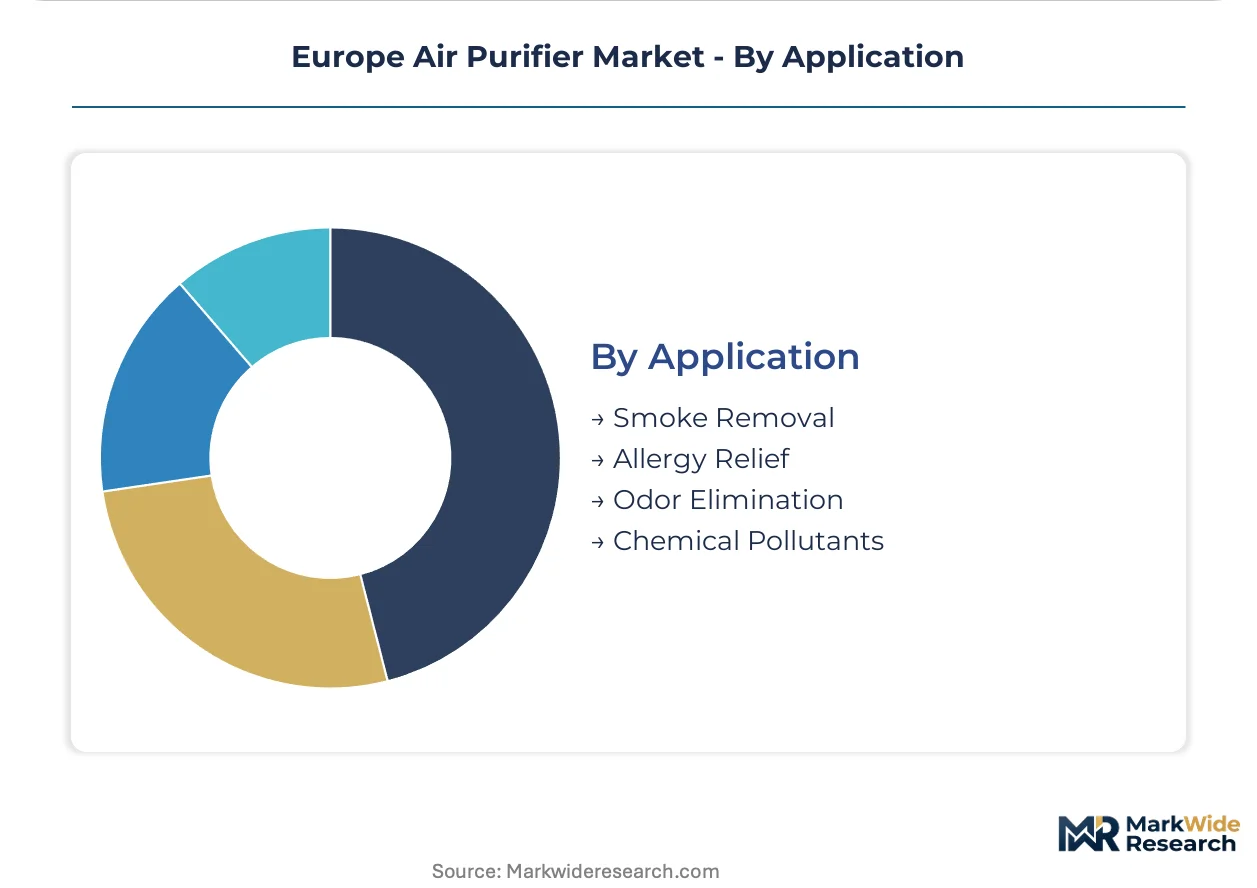
Application:
Customer pain point severity and measurable outcome requirements differentiate these use cases, with medical necessity commanding price inelasticity versus comfort-driven purchases.
- Smoke Removal:Systems engineered for particulate and gas-phase components of combustion aerosols, including wildfire smoke and tobacco residue. Southern European households in Spain and Italy install dedicated units following repeated cross-border smoke events, with activated carbon bed sizing determining efficacy against phenolic and aldehyde compounds.
- Allergy Relief:HEPA-based pollen, dust mite allergen, and pet dander capture optimized for bedroom and living space deployment. German and Austrian urban centers report clinically significant symptom reduction correlating with filtration intensity, sustaining premium positioning for medical-grade certified units.
- Odor Elimination:Activated carbon and zeolite media targeting malodorous volatile compounds from cooking, pets, and environmental sources. Hospitality and residential kitchen applications prioritize rapid adsorption kinetics and media replacement indicators over particulate efficiency metrics.
- Chemical Pollutants:Multi-stage architectures combining particulate pre-filtration with deep-bed activated carbon, impregnated media, or photocatalytic oxidation for formaldehyde, benzene, and solvent vapor abatement. Industrial facilities and new-construction residences in high-VOC emission zones specify these configurations despite substantial cost premiums.
Allergy relief applications generate highest unit volumes; chemical pollutant systems exhibit strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled HVAC engineering clusters across Germany and the Netherlands anchor European air purification R&D capacity. Technical workforce concentration in Swiss precision manufacturing and Italian industrial design shapes competitive differentiation. Regulatory expertise pools in Brussels and Strasbourg influence compliance architecture across member states.
Germany
Extended pollen seasons and intermittent wildfire smoke from Iberian fire clusters drive residential replacement cycles in Munich and Berlin. The EU Green Deal's indoor air quality benchmarks force commercial building retrofits. Bavaria's industrial automation corridor hosts sensor-telemetry integration labs serving building management system convergence.
Netherlands
Amsterdam and Rotterdam office stock built 1960-1990 requires ventilation upgrades to meet 2030 energy performance standards. ECHA REACH compliance timelines for novel nanofiber media extend certification cycles. Eindhoven's high-tech systems cluster concentrates smart-purifier algorithm development for EU AI Act alignment.
France
New-construction households in Île-de-France adopt photocatalytic oxidation systems at twice replacement-purchaser rates for formaldehyde abatement. CE marking under MDR frameworks governs health-claim marketing. Paris commercial buildings face spatial constraints and ductwork incompatibility with modular purification retrofits.
Italy
Cross-border smoke events from Balkan fire clusters sustain Southern European household installations in Milan and Rome. EN 1822 protocol alignment eliminates retesting costs for manufacturers. Lombardy's precision mechanics district supplies fan motor components to European assemblers managing Chinese supply concentration risk.
Switzerland
Medical-grade filtration demand from clinical and laboratory verticals commands premium positioning in Zurich and Geneva. Swissmedic oversight intersects with MDR conformity assessment for cross-border device marketing. Basel's pharmaceutical corridor specifies IQAir-grade architectures for cleanroom environments.
Europe Air Purifier Market Key Industry Players
Capital-heavy HVAC integrators compete with asset-light connected-home specialists for building ventilation contracts. The vendor base stratifies across three tiers: diversified electromechanical conglomerates bundling purification with climate control, consumer electronics brands embedding air quality into wellness platforms, and filtration purists commanding clinical-grade premiums. Strategic moves concentrate on M&A for sensor-telemetry capabilities and vertical integration into filter media production.
Within the diversified electromechanical tier, Daikin Industries and LG Electronics anchor positions through HVAC integration depth that captures bundled building contracts. Koninklijke Philips exemplifies the connected-home archetype, embedding purification into broader wellness ecosystems. IQAir occupies the medical-grade specialization vector, differentiating through clinical and laboratory verticals where efficacy documentation commands price inelasticity.
| Leading Market Players |
|---|
| Daikin Industries |
| Samsung Electronics |
| Honeywell International |
| Sharp Corporation |
| Blueair (Unilever) |
| Koninklijke Philips |
| IQAir |
| LG Electronics |
| Dyson |
| Others |
Cost & Logistics Intelligence
Photocatalytic oxidation module integration is compressing cost curves for premium residential units while simultaneously concentrating production know-how in French and Belgian engineering clusters. This dual effect tightens margin structures for manufacturers lacking captive semiconductor or UV-source supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified units from connected-home wellness platforms and basic HEPA appliances. Price differentiation hinges on EN 1822 certification tier and sensor-telemetry bundling for building management integration. Pricing pressure stems from coconut shell charcoal input volatility squeezing activated carbon margins. Commercial building operators exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while economy-tier residential buyers face acute substitution risk from unbranded imports.
Supply Chain Analysis
Technical workforce scarcity in Lombardy's precision mechanics district and Eindhoven's high-tech systems cluster constrains European fan motor and sensor assembly capacity. Component sourcing draws from Chinese manufacturing regions for electromechanical parts, Southeast Asian processors for coconut shell charcoal, and German specialty chemical producers for nanofiber media. Single-source vulnerability in Chinese fan motor supply creates disruption exposure. Distribution runs through HVAC integrator channels for commercial contracts and consumer electronics retail for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Air Purifier Market compounds steadily as regulatory ratchets under the EU Green Deal and EU AI Act perpetually reset baseline compliance requirements. This structural force sustains replacement demand across all buyer segments.
For Market Incumbents: Anticipate margin compression from unbranded economy-tier imports by securing long-term offtake agreements for coconut shell charcoal feedstock. Deepen backward integration into nanofiber media production to circumvent ECHA REACH certification delays. Prioritize M&A for sensor-telemetry capabilities that enable building management system convergence.
For New Entrants and Emerging Players: EU AI Act alignment in Germany and the Netherlands opens a window for algorithm-native purifier developers to capture commercial specification share. Target Amsterdam and Rotterdam office retrofit pipelines where 1960-1990 building stock requires ventilation upgrades. Pursue energy performance guarantee contracting models that compress equipment sales cycles while extending service durations.
For Investors and Strategic Acquirers: Valuations sit cheapest among filtration purists lacking HVAC bundling scale but commanding clinical-grade premium positioning. Long-term viability favors specialists with EN 1822 protocol mastery and ECHA regulatory navigation expertise. Watch for EU Green Deal indoor air quality benchmark tightening as the inflection signal triggering accelerated commercial retrofit procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Telemetry Integration | Enables autonomous filtration adjustment under EU AI Act compliance frameworks for Dutch and German building operators. |
| Filter Media Backward Integration | Circumvents ECHA REACH certification delays and secures nanofiber supply for medical-grade HEPA production. |
| Photocatalytic Oxidation Launch | Captures formaldehyde-sensitive buyers in French and Belgian new-construction zones at 40-60% unit premiums. |
| Energy Performance Guarantee Contracting | Compresses equipment sales cycles while extending service durations to 7-10 year terms for Nordic facility managers. |
| CE Marking MDR Pathway Investment | Accelerates time-to-market for health-claim marketing against 8-14 month conformity assessment delays. |
Research Approach
Coverage spans Western Europe, Northern Europe, and Southern Europe, with primary inputs from each regional cluster. The research combines structured interviews with HVAC engineering directors, facility management procurement leads, filter media R&D specialists, and regulatory affairs managers with secondary validation against ECHA REACH filings, EU Green Deal implementation documents, EN 1822 test protocols, and customs trade data for electromechanical components. Bottom-up unit shipment modeling and top-down value estimation triangulate market size across the analysis window.
Segmentation granularity extends to usage context, filtration technology type, and application environment, with additional modeling for sensor-telemetry integration intensity and EU AI Act compliance tier. CAGRs derive from regression analysis of historical replacement cycles, regulatory phase-in schedules, and building stock age distributions. Forecast inputs include pollen load trajectory projections for German urban centers and wildfire smoke intrusion frequency for Southern European households.
Revisions become necessary when ECHA REACH restrictions tighten on novel filter chemistries, EU AI Act enforcement patterns diverge from draft guidance, or coconut shell charcoal supply disruptions exceed historical volatility bands. Material deviation in these triggers warrants pause and re-evaluation of installed base and replacement timing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Dew Point Thermometer Market