
 Window Sensors Market | 2026-2036
Window Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Window Sensors Market Intelligence
Residential installer networks is tilting toward wireless retrofit kits as homeowners bypass traditional alarm dealers. Honeywell International Inc. leverages its legacy dealer channel to sustain recurring monitoring revenue. Panasonic Corporation anchors supply for Japanese multi-family developers through integrated building management contracts. Eve Systems GmbH competes in direct-to-consumer channels with HomeKit-native positioning.
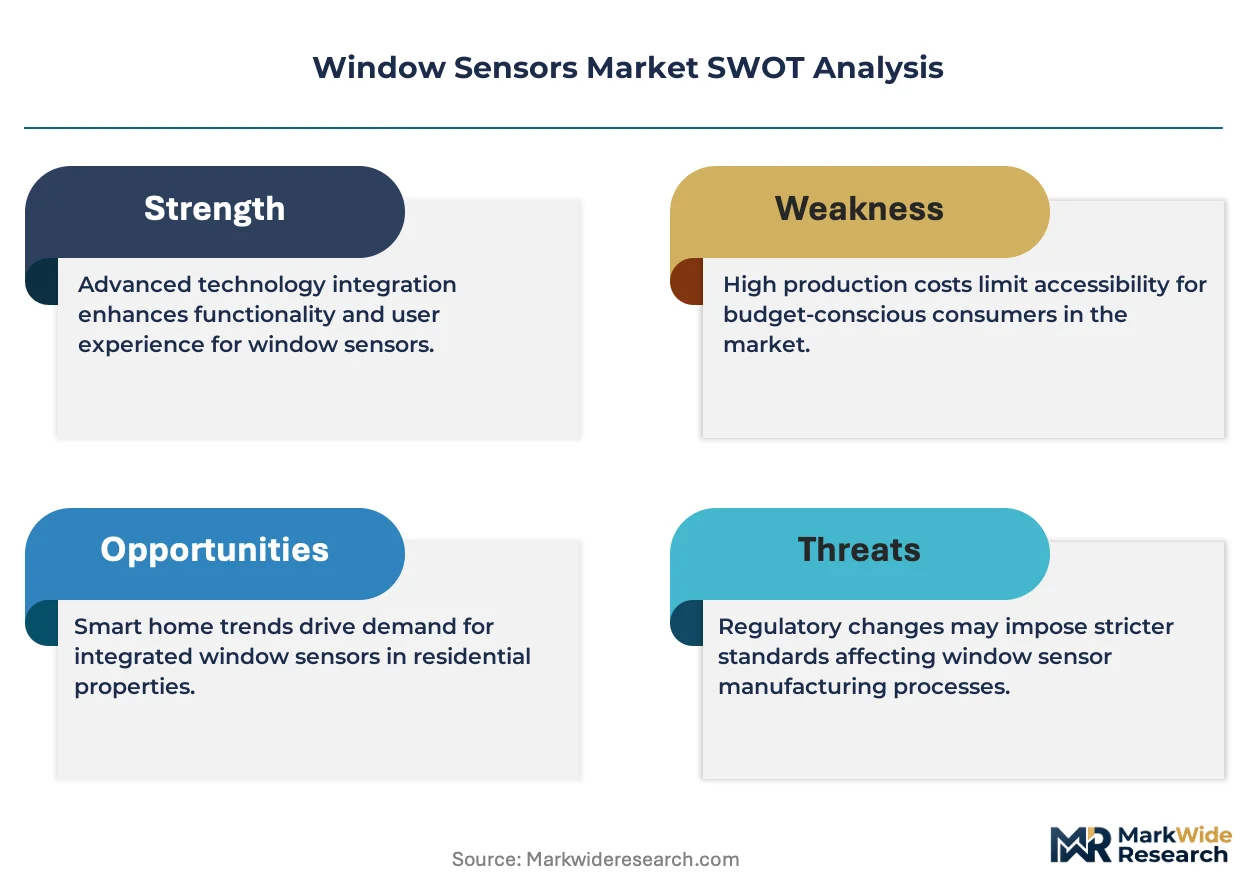
Window sensors detect frame displacement, glass breakage, or proximity intrusion using reed switches, piezoelectric elements, or passive infrared arrays operating between 3.3V and 12V DC. These devices feed central panels or cloud platforms to trigger alarms, notify mobile applications, or automate lighting and climate responses. Magnetic sensors dominate unit shipments in legacy alarm systems where simple open-close loops satisfy insurance underwriting requirements. IoT Technology segments capture expanding margin pools through subscription analytics and over-the-air firmware updates that extend hardware lifecycles.
FCC Part 15 governs wireless transmission power for US-manufactured units, while CE marking under the EU Radio Equipment Directive mandates interoperability testing for European distribution. Japan's METI enforces Building Energy Efficiency Act provisions that treat sensor-enabled automated shading as compliance pathways. Stakeholders must monitor evolving cybersecurity labeling requirements that could bifurcate product roadmaps between basic intrusion detection and encrypted smart home platforms.
Market Dynamics
Wireless retrofit protocols are compressing installation timelines from hours to minutes, eroding the traditional alarm dealer channel that built its recurring revenue model on hardwired infrastructure and multi-year service contracts.
Growth Catalysts
- Insurance Incentive Programs:Underwriters in the United States now mandate connected sensor networks for premium discounts on homeowner policies, accelerating replacement of standalone magnetic contacts.
- Building Energy Efficiency Act:METI compliance pathways in Japan treat automated shading sensors as mandatory efficiency credits, forcing integration of intrusion and environmental monitoring into single devices.
- Reed Switch Miniaturization:Surface-mount magnetic sensing elements now operate at sub-milliwatt power draws, extending battery life beyond five years and eliminating wired power requirements for retrofits.
Market Restraints
- Lithium Supply Concentration:Battery cell production concentrates in Chinese and South Korean facilities, exposing sensor OEMs to input cost volatility and export control risks.
- CE Marking Complexity:EU Radio Equipment Directive interoperability testing adds twelve to eighteen weeks to product launch timelines, compressing first-mover advantage windows.
- Camera-Based Substitution:Edge AI visual monitoring systems are displacing perimeter sensors in commercial installations where single-device coverage reduces hardware counts.
Strategic Opportunities
- German Multi-Family Housing:Building automation codes now require sensor-enabled climate response in new construction, creating bundled security-environmental procurement contracts.
- Matter Protocol Convergence:Thread and Wi-Fi 6 radio stacks are unifying previously fragmented smart home ecosystems, enabling cross-platform sensor deployment without hub lock-in.
- Direct-to-Consumer Channels:HomeKit-native positioning bypasses traditional installer networks, capturing margin pools previously allocated to dealer commissions and monitoring fees.
Industry Challenges
- RF Engineering Talent Scarcity:FCC Part 15 compliance testing requires specialized electromagnetic interference expertise that concentrates in coastal US and German engineering consultancies.
- Legacy Panel Integration:Decades-old central alarm systems use proprietary communication protocols that resist cloud-platform bridging without hardware middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Sensors Market |
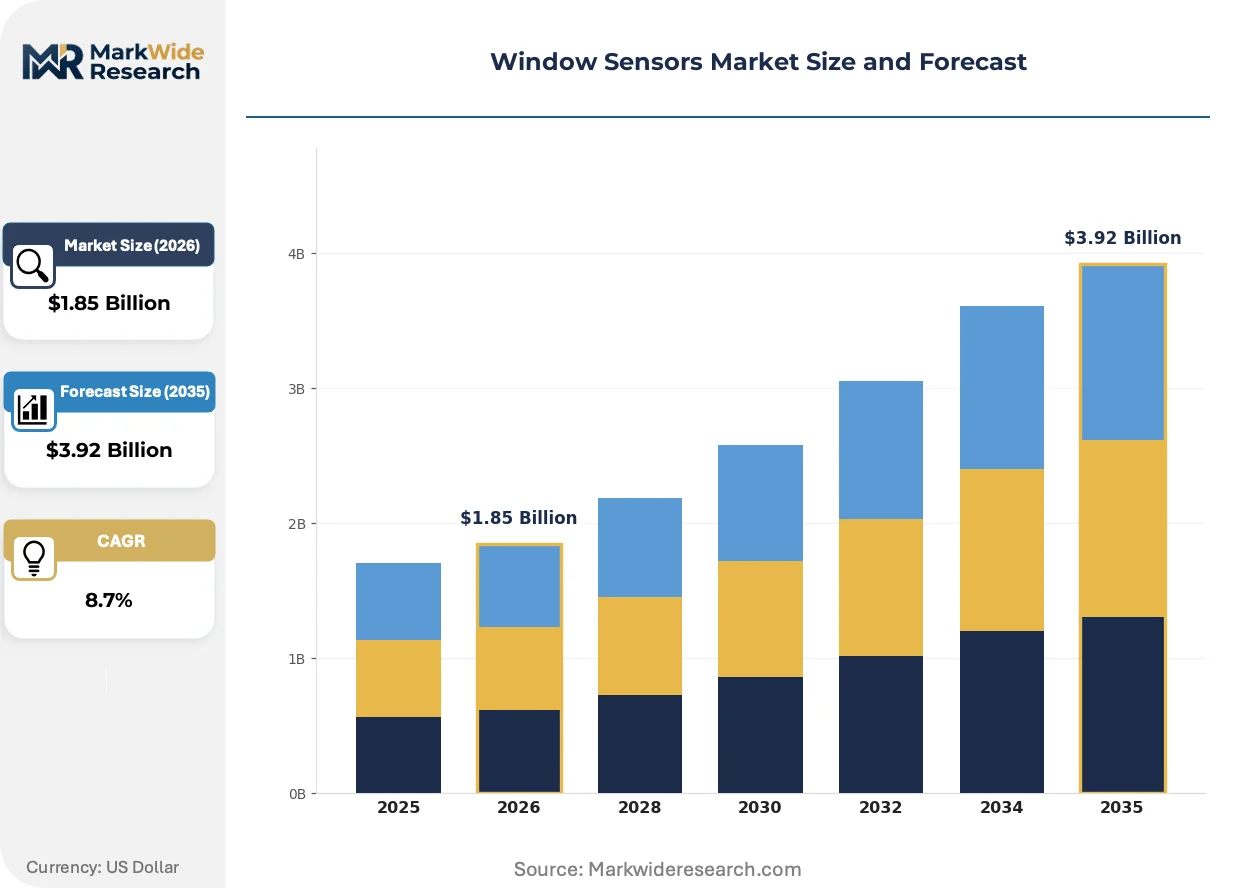
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Sensors, Ultrasonic Sensors, Vibration Sensors, Infrared Sensors Technology: Wired Technology, Wireless Technology, IoT Technology, Smart Home Technology End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Educational Institutions Installation: Surface Mount, Recessed Mount, Wireless Installation, Integrated Systems |
| Companies Covered | Honeywell International Inc., Panasonic Corporation, Optex Group Co. Ltd., Pepperl+Fuchs SE, Eve Systems GmbH, SABRE - Security Equipment Corp., SecurityMan Inc., Bosch Security Systems Inc., Hotron Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Sensors Market Strategic Shifts & Innovations
Sensor architectures are fusing environmental monitoring with security functions, collapsing the historical separation between intrusion detection and building automation into unified edge devices.
Multi-sensor fusion is hybridizing reed switch displacement detection with passive infrared proximity arrays and piezoelectric glass-break vibration sensing into single surface-mounted enclosures. Multi-family developers in Japan and Germany are specifying these consolidated units to reduce wiring complexity and satisfy both security underwriting and energy compliance requirements. This convergence is compressing SKU counts for OEMs while raising firmware complexity and validation costs.
FCC Part 15 transmission power limits are tightening enforcement for sub-gigahertz wireless protocols used in legacy alarm systems, forcing migration to 2.4 GHz mesh networks that interoperate with smart home ecosystems. Equipment manufacturers are redesigning radio modules to satisfy both legacy panel compatibility and modern cloud-platform connectivity. North American residential retrofits face the steepest compliance transition as older 433 MHz hardware loses certification grandfathering.
Homeowner purchasing patterns are fragmenting across self-install wireless kits and professional monitored services, with no dominant channel emerging. Retailers capture margin from hardware sales while SaaS platforms extract recurring revenue from firmware-enabled feature unlocks. This bifurcation is most visible in United States suburban markets where insurance discounts favor monitored systems but consumer preference favors unmonitored privacy.
Window Sensors Market Segmentation
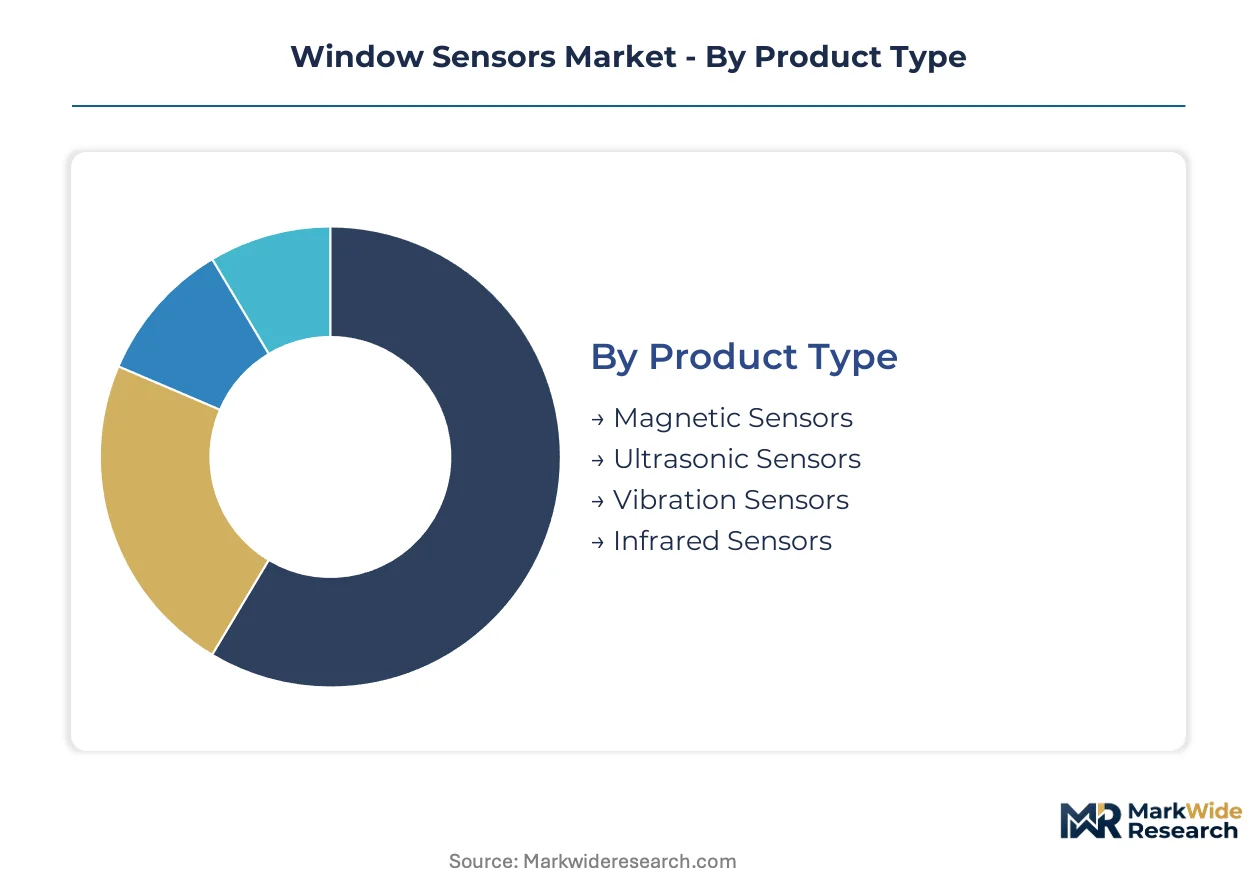
Window sensor procurement patterns diverge sharply across application contexts, with replacement cycles spanning from five-year battery-driven residential units to fifteen-year hardwired commercial installations. Understanding these temporal rhythms helps suppliers align inventory turns, warranty reserves, and R&D roadmaps to the segments that dominate their revenue mix.
Product Type:
Magnetic sensors turn over fastest in residential retrofit channels where homeowners replace batteries and upgrade aesthetics on three-to-five year cycles, while industrial vibration sensors persist for a decade or more in factory automation deployments.
- Magnetic Sensors:Reed switch mechanisms detect frame separation through magnetic field disruption, drawing sub-milliwatt power from coin-cell batteries. Demand concentrates in United States suburban single-family homes where insurance underwriters mandate open-loop monitoring for premium discounts. Replacement rates accelerate as smart home ecosystems drive aesthetic upgrades and protocol migrations.
- Vibration Sensors:Piezoelectric elements translate glass fracture frequencies into electrical signals, requiring calibration for frame material and glass thickness. German commercial property managers specify these for storefront protection in historic districts where facade preservation limits camera deployment. Long replacement cycles reflect durable encapsulation and minimal moving parts.
- Ultrasonic Sensors:Time-of-flight measurement detects proximity intrusion through air displacement sensing, common in Japanese multi-family entryways where METI energy codes favor combined security-environmental units.
- Infrared Sensors:Passive thermal arrays identify body heat signatures near window surfaces, deployed in United States educational institutions where gunshot detection systems integrate perimeter monitoring.
Magnetic sensors anchor the volume base while vibration sensors gain share at the steepest rate in commercial hardening applications.
Technology:
Cost tiers separate legacy wired infrastructure from premium IoT platforms, with wireless retrofit kits capturing mid-market margin pools previously allocated to dealer installation labor.
- Wired Technology:Low-voltage DC loops connect to central alarm panels through proprietary protocols, dominating United States commercial installations built before 2015. Replacement demand concentrates in facilities upgrading to IP-based monitoring without full infrastructure teardown.
- IoT Technology:Cloud-connected architectures enable over-the-air firmware updates, subscription analytics, and third-party platform integration. Japanese building automation contractors specify these for METI compliance tracking and automated shading coordination. Margin structures shift toward recurring SaaS revenue.
- Wireless Technology:Sub-gigahertz and 2.4 GHz mesh radios eliminate conduit runs, accelerating German residential retrofit timelines from days to hours.
- Smart Home Technology:Matter-native and HomeKit-certified devices bypass professional installation, capturing direct-to-consumer channels in United States metropolitan markets.
Wired technology retains installed-base dominance while IoT platforms expand most quickly in new construction specifications.
End User:
Customer type determines procurement authority, with residential homeowners prioritizing smartphone integration and facilities managers emphasizing centralized monitoring dashboards.
- Residential Buildings:Single-family and multi-family dwellings drive unit volume through retail and e-commerce channels. German rental housing associations bundle sensors with smart thermostats to satisfy building automation codes. Homeowner associations in United States sunbelt states specify wireless kits for seasonal residents.
- Commercial Buildings:Office towers, retail centers, and hospitality properties require monitored systems with UL certification. Japanese property developers integrate sensors with building management systems for energy credit compliance. Procurement runs through security integrators with multi-year service contracts.
- Industrial Facilities:Manufacturing plants and warehouses specify explosion-rated housings and vibration-hardened mounting for perimeter protection.
- Educational Institutions:K-12 districts and university campuses prioritize lockdown system integration and mass notification triggering.
Residential buildings supply the volume foundation while commercial buildings deliver the steepest expansion trajectory in code-driven new construction.
Installation:
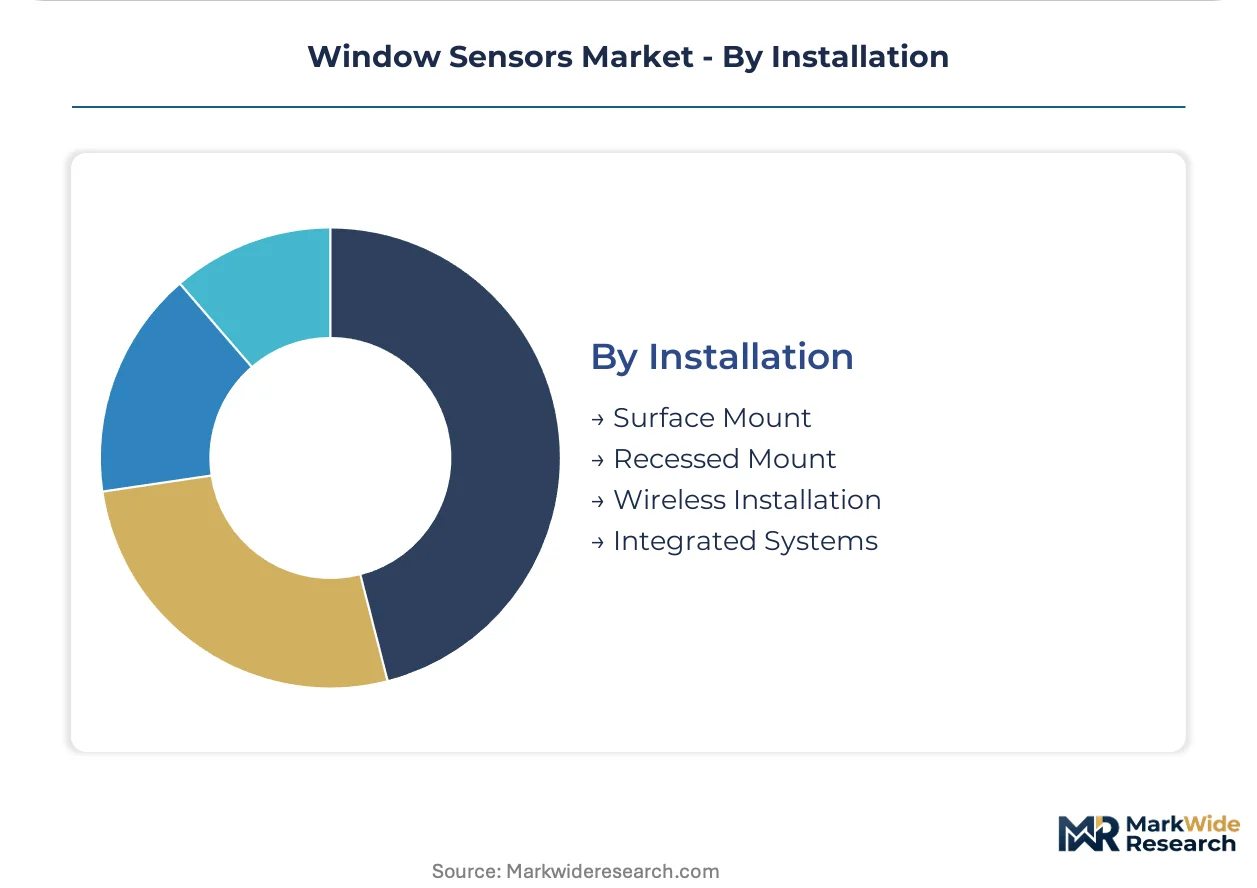
Application context dictates mounting methodology, with surface-mount retrofits dominating residential replacement demand and integrated systems capturing new construction specifications.
- Surface Mount:Adhesive or screw-fixed enclosures attach to existing window frames without carpentry modification. United States big-box retailers stock these for same-day pickup by homeowners responding to break-in incidents. Fastest replacement cycles reflect damage during removal and aesthetic obsolescence.
- Integrated Systems:Factory-installed sensor wiring routes through window frames during manufacturing, specified by German multi-family developers seeking single-contractor accountability. Highest upfront cost offset by eliminated field labor and seamless aesthetic integration.
- Recessed Mount:Concealed installation within frame cavities requires precise machining, common in historic preservation projects.
- Wireless Installation:Peel-and-stick mounting with battery power eliminates electrical permits, accelerating deployment in rental properties.
Surface mount configurations dominate replacement volume while integrated systems climb fastest in prefabricated construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States homeowners pay premium hardware prices while German rental housing associations capture economies through bundled procurement contracts. This pricing-power asymmetry reflects divergent channel structures and regulatory incentive frameworks across developed markets.
United States
Insurance underwriters mandate connected sensor networks for homeowner policy discounts, accelerating replacement of standalone magnetic contacts. FCC Part 15 governs wireless transmission power limits for sub-gigahertz protocols. Atlanta and Dallas suburbs concentrate self-install wireless kit demand among seasonal residents bypassing traditional alarm dealers.
Germany
Building automation codes require sensor-enabled climate response in new multi-family construction, creating bundled security-environmental procurement contracts. CE marking under the EU Radio Equipment Directive mandates twelve-to-eighteen week interoperability testing. Munich and Frankfurt developers specify integrated factory-installed systems to satisfy single-contractor accountability requirements.
Japan
METI enforces Building Energy Efficiency Act provisions treating automated shading sensors as mandatory efficiency credits. Japanese multi-family developers integrate intrusion and environmental monitoring into single devices through building management contracts. Osaka and Nagoya metropolitan areas anchor supply concentration for Panasonic Corporation's integrated systems.
United Kingdom
Historic preservation districts limit camera deployment, sustaining demand for vibration sensors in storefront protection applications. GDPR compliance requirements shape data handling specifications for cloud-connected architectures. London security integrators specify UL-certified monitored systems for commercial office towers with multi-year service obligations.
South Korea
Smart city initiatives in Seoul and Busan drive municipal procurement of multi-sensor fusion devices for public building automation. MFDS-equivalent national standards govern electromagnetic compatibility for wireless retrofit protocols. Daegu-Gyeongbuk industrial corridor concentrates manufacturing of surface-mount reed switch components for export markets.
Window Sensors Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying magnetic sensing elements and radio modules. The vendor base spans legacy alarm equipment manufacturers, consumer electronics conglomerates, and direct-to-consumer smart home specialists. Three archetypes dominate: dealer-channel incumbents with recurring monitoring revenue, building automation contractors with integrated specification control, and HomeKit-native challengers capturing retail margin pools. Competitive moves concentrate on protocol convergence through Matter certification and geographic expansion via distributor partnerships in code-driven European markets.
Among legacy-channel incumbents, Honeywell International Inc. and Panasonic Corporation exemplify divergent regional strategies. Honeywell International Inc. leverages established dealer networks to sustain recurring monitoring revenue streams in North American suburban markets. Panasonic Corporation anchors supply relationships with Japanese multi-family developers through integrated building management contracts. Eve Systems GmbH occupies a position within the direct-to-consumer tier, competing through HomeKit-native certification that bypasses professional installation channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Panasonic Corporation |
| Optex Group Co. Ltd. |
| Pepperl+Fuchs SE |
| Eve Systems GmbH |
| SABRE - Security Equipment Corp. |
| SecurityMan Inc. |
| Bosch Security Systems Inc. |
| Hotron Ltd. |
| Others |
Cost & Logistics Intelligence
The Shenzhen-Rotterdam maritime corridor carries surface-mount reed switch components and lithium coin cells from Chinese manufacturing clusters to European distribution hubs, with freight cost volatility compressing margins for mid-tier OEMs while amplifying price spreads between standard magnetic contacts and configured-to-order multi-sensor fusion units.
Pricing Analysis
The customization-premium spread separates configured-to-order multi-sensor units with METI compliance tracking from standard magnetic contacts stocked by big-box retailers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because of lithium supply concentration and retail channel margin demands. Residential homeowners in United States suburban markets exhibit highest price sensitivity, while Japanese multi-family developers accepting integrated building management contracts show lowest sensitivity due to single-contractor accountability requirements.
Supply Chain Analysis
Upstream feedstock for piezoelectric elements and magnetic sensing components draws from Chinese rare earth processing facilities, South Korean battery cell manufacturing, and Japanese precision component specialists. Raw material dependencies center on neodymium magnets, lithium manganese dioxide cells, and surface-mount ceramic substrates. Single-source vulnerability concentrates in Chinese rare earth separation capacity. Distribution runs through building automation contractors in Germany, security integrators in the United States, and direct-to-consumer channels for HomeKit-native devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Window Sensors Market is reshaping around protocol convergence through Matter certification and regulatory mandates from METI and FCC Part 15 enforcement, creating inflection points for both defensive consolidation and white-space entry.
For Market Incumbents: Harden recurring revenue streams by deepening firmware-enabled feature unlocks and subscription analytics capabilities against camera-based substitution threats. Prioritize backward integration into lithium cell supply through South Korean or Japanese partnerships to offset input cost volatility. Secure dealer channel exclusivity in United States suburban markets where insurance discount programs favor monitored systems. For New Entrants and Emerging Players: Build out HomeKit-native and Matter-certified direct-to-consumer portfolios targeting United States metropolitan markets where professional installation bypass captures retail margin pools. The German rental housing association segment offers most penetrable white-space through bundled smart thermostat and sensor procurement contracts. Emphasize peel-and-stick wireless installation simplicity to accelerate same-day purchase conversion. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core security electronics divisions with established FCC Part 15 compliance expertise and Japanese building management relationships. Long-term viability favors platforms with recurring SaaS revenue over pure hardware transactional models. Monitor Matter protocol certification velocity as inflection indicator for ecosystem lock-in potential.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Enables cross-platform sensor deployment without hub lock-in across fragmented smart home ecosystems. |
| Backward Integration into Battery Supply | Captures lithium cell cost stability through South Korean or Japanese manufacturing partnerships. |
| Direct-to-Consumer Channel Expansion | Bypasses dealer commissions and monitoring fees in United States metropolitan retail markets. |
| Multi-Sensor Fusion R&D Investment | Collapses intrusion detection and building automation into single devices for Japanese METI compliance. |
| Geographic Expansion via Distributor Partnerships | Accelerates CE marking pathway access for German multi-family housing bundled procurement contracts. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with building automation contractors, security integrators, smart home platform engineers, and lithium battery procurement specialists. Secondary validation drew from FCC equipment authorization databases, METI building energy efficiency filings, CE marking notification records, and customs trade data for magnetic sensing component flows. Bottom-up unit shipment estimates triangulated against top-down construction permit and insurance policy discount data.
Calibration against historical protocol migration cycles and regulatory compliance timelines anchored volume and value outputs across the modeling period. Segmentation dimensions modeled include product type, technology tier, end-user category, and installation methodology alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics and new construction code adoption rates. Industry-specific forecast inputs encompassed battery chemistry evolution and wireless radio stack migration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer electronics conglomerates entering through acquisition would shift outcomes beyond modeled ranges. Cross-checking against building permit issuance data and insurance underwriter policy filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
India Industrial Sensors and Transmitters Market