
 HVAC Sensor Market | 2026-2036
HVAC Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Sensor Market Analysis
Buyer concentration across commercial real estate portfolios is rebalancing as institutional property managers consolidate vendor relationships for smart building retrofits. Honeywell International leverages its building automation platform to anchor sensor-to-controller integration across North American portfolios. Siemens AG competes through its digital twin architecture for HVAC optimization in European commercial towers. Sensirion AG specializes in miniature gas and particulate sensors that extend its reach into compact duct-mounted applications.
An HVAC sensor is an electromechanical or solid-state device that measures thermal, pressure, humidity, or air quality parameters within heating, ventilation, air conditioning, and refrigeration systems, typically operating across calibrated ranges such as minus forty to one hundred twenty degrees Celsius for temperature variants. These devices feed real-time environmental data to building management systems to optimize energy consumption, occupant comfort, and equipment longevity. Temperature sensors occupy the largest installed base due to universal deployment across all HVAC functions, while air quality sensors represent the fastest-expanding category as ventilation standards tighten and indoor environmental quality gains priority in commercial leases. Smart sensors command premium positioning through embedded edge-computing capabilities that reduce controller dependency and enable predictive maintenance protocols.
The US EPA refrigerant management rules and the EU F-Gas Regulation mandate leak detection systems with calibrated sensor thresholds, directly expanding replacement demand across existing installations. China's GB standards for building energy efficiency and India's BIS certification requirements for electronic control devices further shape product specifications and market access conditions for international suppliers. Stakeholders must monitor evolving refrigerant-phase-down schedules and corresponding sensor calibration mandates to align R&D roadmaps with compliance-driven procurement cycles.
Market Dynamics
The HVAC sensor market is being fundamentally restructured by refrigerant-phase-down mandates that require facility operators to retrofit leak detection infrastructure across existing building stock, converting compliance expenditure into sustained replacement demand.
Growth Catalysts
- EU F-Gas Regulation:Mandatory sensor-based leak detection systems for commercial refrigeration and air conditioning equipment are forcing systematic hardware upgrades across European commercial portfolios.
- Smart building retrofits:Institutional property managers are consolidating vendor relationships for integrated environmental monitoring, pulling multi-parameter sensors into single procurement contracts.
- Particulate sensing miniaturization:Advances in MEMS fabrication are enabling duct-mounted air quality sensors that previously required centralized station architecture.
Market Restraints
- Semiconductor input volatility:MEMS die and signal conditioning chips face concentrated sourcing from East Asian foundries, exposing sensor manufacturers to supply disruption.
- Calibration infrastructure gaps:Field recertification of refrigerant leak sensors requires specialized technician networks that remain underdeveloped in secondary urban markets.
- Passive building envelope substitution:Ultra-low-energy construction standards in Germany and Scandinavia are reducing mechanical HVAC tonnage and corresponding sensor counts per square meter.
Strategic Opportunities
- India BIS certification pathway:Mandatory electronic control device standards for commercial buildings are creating first-mover advantage for suppliers establishing local calibration partnerships.
- Predictive maintenance convergence:Edge-computing sensors combining vibration, temperature, and pressure data are opening subscription revenue streams independent of equipment OEMs.
- Healthcare ventilation standards:Post-pandemic ICU and surgical suite air change requirements are expanding demand for high-accuracy differential pressure sensors.
Industry Challenges
- Embedded firmware talent scarcity:Sensor manufacturers compete with automotive and consumer electronics for engineers skilled in ultra-low-power wireless stacks.
- Multi-protocol integration friction:BACnet, Modbus, and emerging MQTT implementations require redundant hardware variants that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Sensor Market |
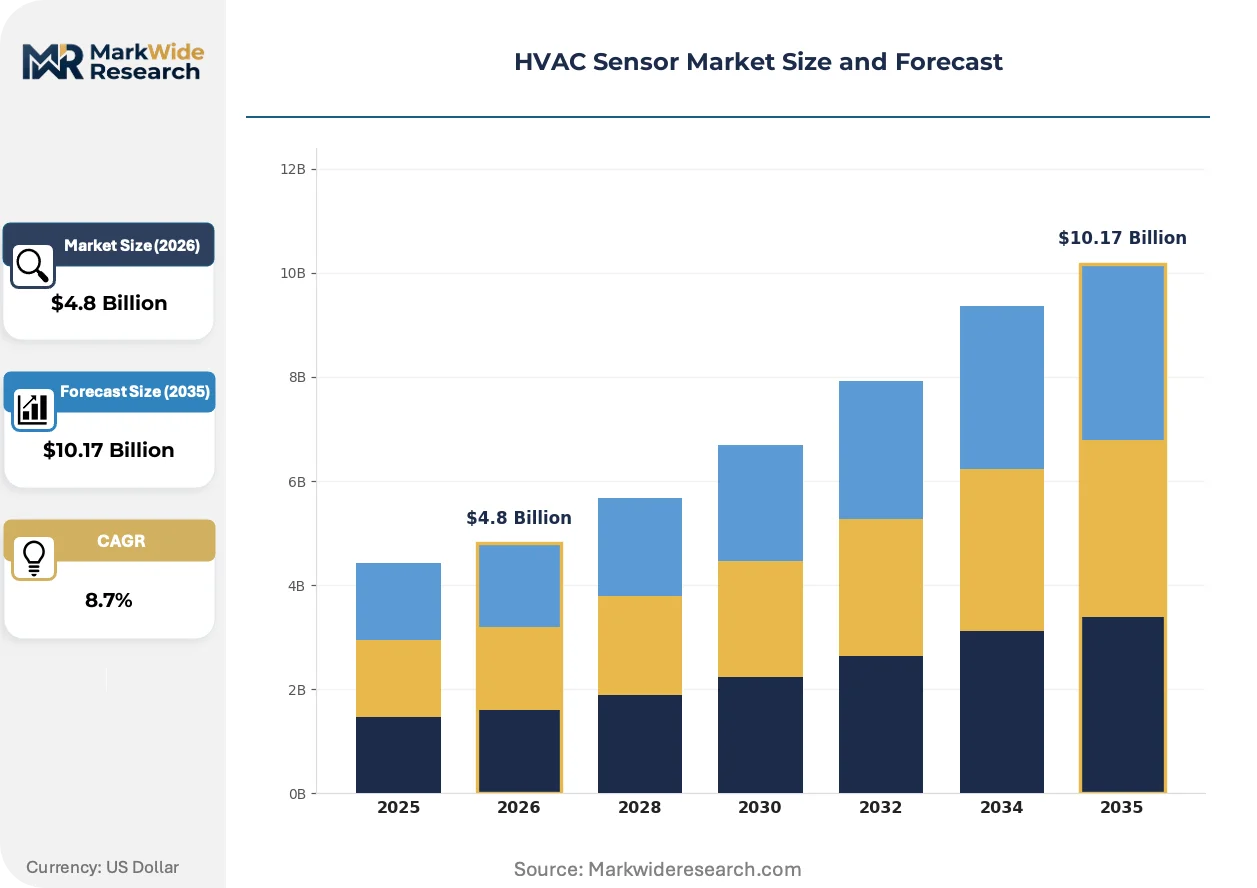
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Humidity Sensors, Pressure Sensors, Air Quality Sensors Technology: Wired Sensors, Wireless Sensors, Smart Sensors, Analog Sensors End User: Residential, Commercial, Industrial, Institutional Application: Heating, Ventilation, Air Conditioning, Refrigeration |
| Companies Covered | Honeywell International, Siemens AG, Johnson Controls, Schneider Electric, Emerson Electric Co., Sensirion AG, TE Connectivity Ltd., Sensata Technologies, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Sensor Market Emerging Trajectories
Sensor architecture is fragmenting into distributed edge nodes that preprocess environmental data locally, reducing controller bandwidth requirements while enabling real-time anomaly detection that previously demanded cloud latency.
MEMS-based multi-gas sensing arrays are modularizing around interchangeable cartridge designs that allow facility operators to swap detection chemistries without replacing entire hardware units. Commercial real estate portfolios in Germany and the Netherlands are piloting these platforms to adapt sensor configurations as refrigerant chemistries evolve under phase-down schedules. The approach is compressing replacement cycles from full hardware obsolescence to cartridge refresh intervals.
China's GB standards for building energy efficiency are mandating real-time energy consumption disclosure that requires granular HVAC submetering. Property developers in Shanghai and Shenzhen are specifying sensors with integrated power monitoring to satisfy both environmental and regulatory reporting obligations. The requirement is pulling sensor specifications toward higher sampling frequencies and onboard data logging.
Long-term service contracts are displacing transactional hardware procurement as institutional buyers seek guaranteed uptime rather than capital equipment ownership. Facility management firms in Singapore and Dubai are bundling sensor maintenance, calibration, and replacement into per-square-meter facility charges. The shift is transferring inventory risk to manufacturers while locking in decade-long revenue streams.
HVAC Sensor Market Segmentation
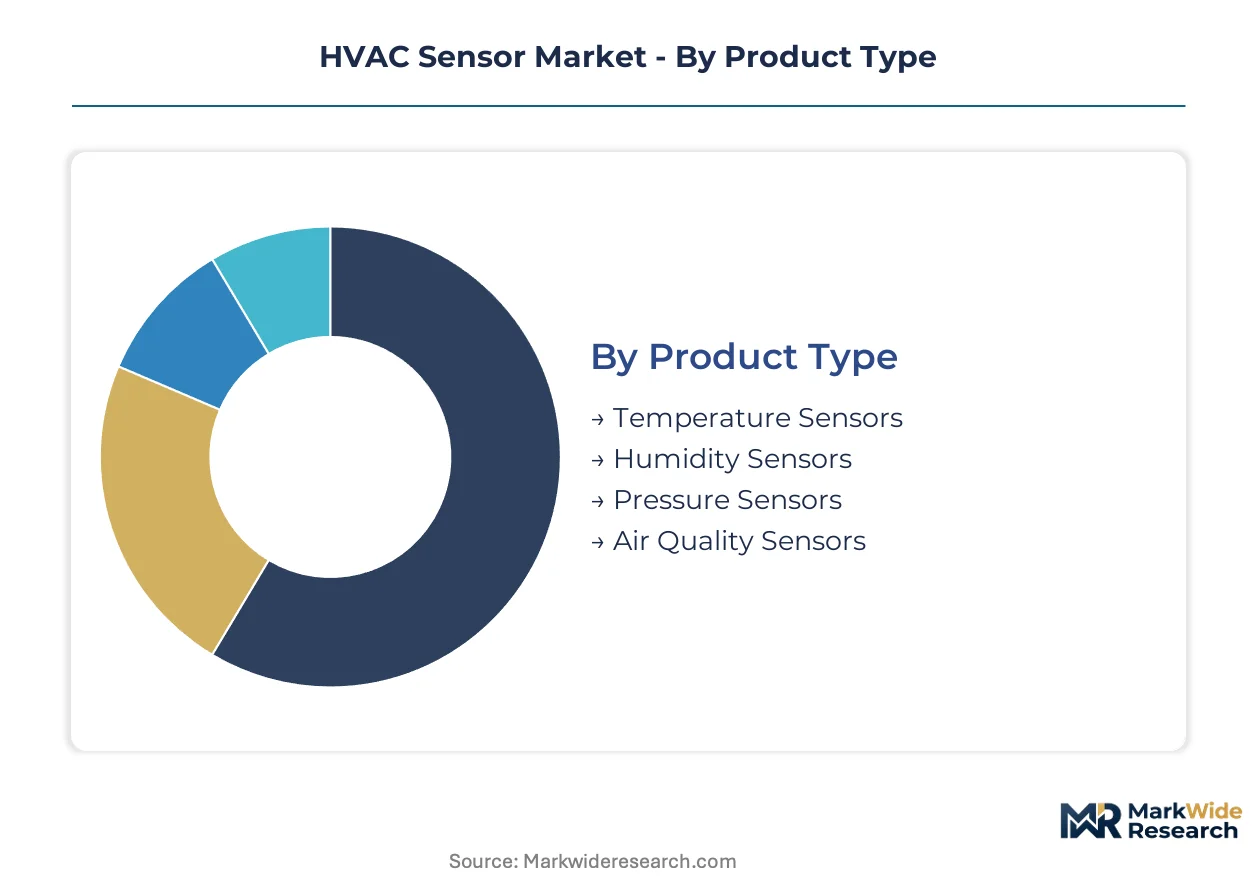
HVAC sensor procurement patterns diverge sharply across building types and system architectures, with specification requirements varying by refrigerant monitoring mandates, network infrastructure maturity, and energy disclosure obligations. Understanding these segmentation boundaries enables suppliers to align calibration service networks and firmware development roadmaps with concentrated demand pockets.
Product Type:
Temperature sensing dominates unit economics through universal deployment across all HVAC functions, while air quality monitoring commands premium positioning as ventilation standards tighten.
- Temperature Sensors:Thermistors, RTDs, and thermocouples measure thermal gradients across minus forty to one hundred twenty degrees Celsius calibrated ranges. Demand concentrates in commercial building retrofits across Germany and the Netherlands, where heat pump integration mandates dual-point sensing for defrost cycles and efficiency optimization.
- Air Quality Sensors:MEMS-based particulate and gas detection arrays monitor PM2.5, CO2, and volatile organic compounds in duct-mounted configurations. Deployment is accelerating in Shanghai and Shenzhen commercial towers, where China's GB standards mandate real-time energy consumption disclosure tied to ventilation performance.
- Humidity Sensors:Capacitive polymer and resistive thin-film elements track relative humidity for dew point control and mold prevention in climate-sensitive facilities.
- Pressure Sensors:Piezoelectric and MEMS differential devices measure refrigerant line pressures and airflow static pressure across filter banks and coils.
Mature deployment sits with temperature sensors. Newer deployment is concentrated in air quality sensors.
Technology:
Network architecture choices fragment procurement patterns between legacy building stock requiring hardwired reliability and new construction favoring flexible wireless topologies.
- Smart Sensors:Edge-computing devices with embedded microcontrollers preprocess environmental data locally, enabling predictive maintenance protocols independent of centralized building management systems. Singapore facility management firms bundle these into per-square-meter service contracts spanning decade-long calibration and replacement obligations.
- Wireless Sensors:Battery-powered or energy-harvesting nodes using LoRaWAN, Zigbee, or proprietary mesh protocols eliminate conduit installation costs. Demand clusters in Dubai commercial portfolios, where rapid tenant turnover favors reconfigurable sensing infrastructure without structural modification.
- Wired Sensors:Hardwired 4-20mA or 0-10V analog outputs deliver deterministic latency for safety-critical refrigerant leak detection circuits.
- Analog Sensors:Basic resistive or voltage-output devices serve cost-constrained replacement markets with minimal signal conditioning requirements.
Smart sensors are climbing the fastest as institutional buyers shift from capital procurement to guaranteed-uptime service models.
End User:
Building ownership structures determine specification authority, with consolidated property managers driving standardization across multi-site portfolios.
- Commercial:Office towers, retail centers, and hospitality properties with centralized facility management mandate multi-parameter environmental monitoring. India's BIS certification requirements for electronic control devices are reshaping procurement specifications for commercial building developers in Mumbai and Bangalore.
- Industrial:Manufacturing facilities and cold chain logistics require ruggedized housings and extended calibration intervals for harsh operating environments. EU F-Gas Regulation compliance drives systematic hardware upgrades across European industrial refrigeration installations.
- Residential:Single-family and multi-family dwellings favor low-cost, self-contained thermostats with integrated sensing.
- Institutional:Healthcare, education, and government facilities balance public procurement transparency with specialized air change requirements for infection control.
Commercial end users anchor current volume. Industrial deployment is expanding most quickly under refrigerant-phase-down compliance schedules.
Application:
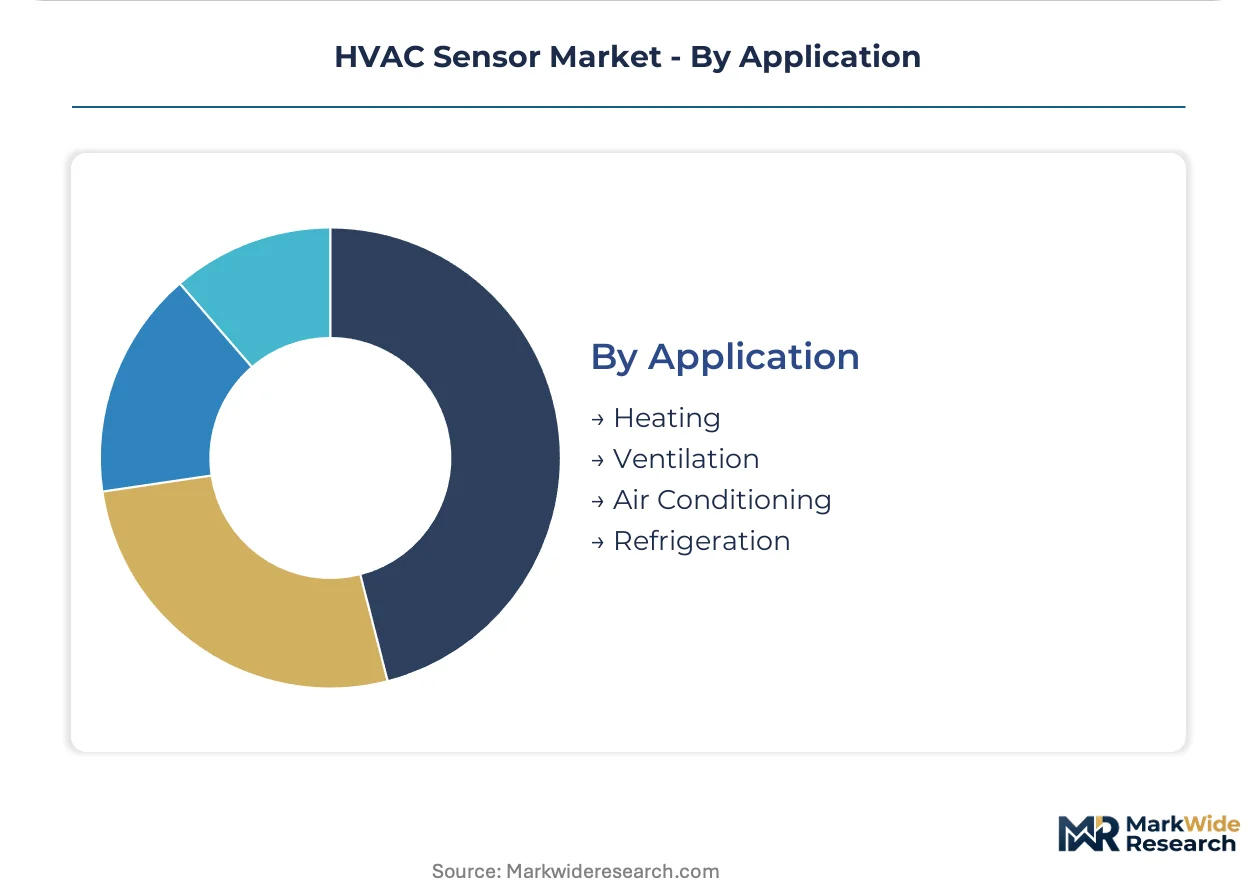
System function dictates sensor density and accuracy requirements, with refrigeration applications commanding the most stringent leak detection thresholds.
- Refrigeration:Commercial and industrial cooling systems require calibrated refrigerant leak sensors with alarm thresholds mandated by EPA rules in the United States and EU F-Gas Regulation phase-down frameworks. Retrofit demand converts compliance expenditure into sustained replacement cycles across existing European building stock.
- Ventilation:Air handling units and energy recovery ventilators deploy differential pressure and air quality sensors to optimize outdoor air intake against energy consumption. Post-pandemic ICU and surgical suite standards in healthcare facilities are expanding demand for high-accuracy differential pressure monitoring.
- Heating:Boilers, furnaces, and heat pumps rely on temperature and pressure sensing for combustion safety and efficiency modulation.
- Air Conditioning:Split systems, chillers, and packaged rooftop units integrate multi-point sensing for capacity staging and fault detection.
Heating and air conditioning represent mature application bases. Refrigeration and ventilation are gaining share fastest under tightening environmental and health regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China, Germany, and India where construction codes mandate real-time environmental monitoring. Institutional property managers across these markets consolidate vendor relationships for smart building retrofits. Regulatory phase-down schedules for refrigerants drive systematic hardware upgrades.
China
Commercial tower development in Shanghai and Shenzhen accelerates sensor deployment for GB standards compliance. The country's MIIT enforces building energy efficiency disclosure requirements that pull specifications toward higher sampling frequencies. Property developers specify integrated power monitoring sensors to satisfy dual environmental and regulatory reporting obligations.
Germany
Heat pump integration mandates dual-point temperature sensing for defrost cycle optimization across commercial portfolios. The EU F-Gas Regulation compels facility operators to retrofit leak detection infrastructure, converting compliance expenditure into sustained replacement demand. Industrial clusters in Bavaria and North Rhine-Westphalia pilot modular gas sensing arrays with interchangeable cartridges.
India
Commercial building developers in Mumbai and Bangalore reshape procurement specifications under BIS certification requirements for electronic control devices. The country's CEA mandates real-time energy consumption disclosure that drives granular HVAC submetering. First-mover suppliers establish local calibration partnerships to capture standardization-driven procurement cycles.
United States
EPA refrigerant management rules mandate calibrated sensor thresholds for leak detection systems across existing building stock. Institutional property managers consolidate multi-parameter environmental monitoring into single procurement contracts. Facility management firms in Texas and California bundle sensor maintenance into decade-long service agreements.
United Arab Emirates
Rapid tenant turnover in Dubai commercial portfolios favors reconfigurable wireless sensing infrastructure without structural modification. The country's MOHAP oversees healthcare ventilation standards that expand demand for high-accuracy differential pressure sensors in ICU and surgical suites. Facility management firms bundle sensor maintenance into per-square-meter facility charges.
HVAC Sensor Market Vendor Landscape
North American producers anchor one tier; European specialists hold differentiated positioning through digital architecture integration. The vendor base spans consolidated building automation platforms and focused component suppliers. Three archetypes dominate: full-stack building automation providers, miniature sensor specialists, and connectivity-focused component manufacturers. Competitive moves concentrate on strategic partnerships for calibration service networks and portfolio diversification into predictive maintenance subscriptions.
Within the building automation tier, Honeywell International and Siemens AG exemplify platform-centric positioning that anchors sensor-to-controller integration across commercial portfolios. Sensirion AG occupies a specialist position among miniature gas and particulate sensor fabricators, extending reach into compact duct-mounted applications where MEMS fabrication advances enable new form factors. These three companies represent the spectrum from integrated systems to component-level specialization that defines competitive boundaries.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens AG |
| Johnson Controls |
| Schneider Electric |
| Emerson Electric Co. |
| Sensirion AG |
| TE Connectivity Ltd. |
| Sensata Technologies |
| Amphenol Corporation |
| Others |
Supply Flow & Price Mechanics
Institutional property managers consolidating multi-site procurement contracts anchor pricing power toward volume-tiered structures with embedded calibration service bundles. This buyer concentration compresses margins on transactional hardware while elevating recurring revenue streams for suppliers offering decade-long uptime guarantees.
Pricing Analysis
Volume procurement by facility management firms in Singapore and Dubai commands standard-tier pricing, while edge-computing smart sensors with predictive maintenance capabilities capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade refrigerant leak detection from basic temperature sensing. Cost compression in analog sensor tiers is intensifying because MEMS fabrication advances enable multi-parameter integration at lower unit costs. Residential retrofit channels exhibit highest price sensitivity; healthcare ICU specifications show lowest.
Supply Chain Analysis
CE marking and BIS certification requirements gate market access for international suppliers, forcing localized calibration partnerships before downstream distribution. MEMS die fabrication concentrates in Taiwan and South Korea; signal conditioning chip packaging centers on Malaysia and Vietnam. The supply chain draws from silicon wafers, polymer sensing films, and rare-earth magnet components. Single-source vulnerability runs through East Asian foundry concentration for specialized gas sensing arrays. Distribution runs through building automation OEM direct channels and specialized HVAC component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC sensor market functions as a vertical-integration race where captive control over MEMS fabrication and calibration service networks determines margin retention. Suppliers are pursuing backward integration into semiconductor die production to secure supply continuity.
For Market Incumbents: Extend platform stickiness by bundling sensor hardware into decade-long facility management contracts that transfer calibration liability from building operators. Consolidate vendor relationships across European commercial portfolios before refrigerant-phase-down mandates accelerate replacement cycles. Deepen in-house production of MEMS gas sensing arrays to reduce foundry dependency.
For New Entrants and Emerging Players: Capture first-mover positioning in India's BIS certification pathway by establishing local calibration partnerships ahead of standardized procurement specifications. Target secondary urban markets in Mumbai and Bangalore where technician networks for field recertification remain underdeveloped. Pursue white-label supply agreements with regional building automation integrators lacking sensor fabrication capabilities.
For Investors and Strategic Acquirers: The window for entry favors miniature sensor specialists with proven MEMS fabrication scale and established regulatory certification portfolios. Long-term viability hinges on subscription revenue conversion from transactional hardware models. Watch for inflection signals in healthcare ventilation standards expansion across Gulf Cooperation Council markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Enables subscription revenue independent of equipment OEMs like Honeywell and Siemens. |
| Modular Gas Sensing Cartridge Development | Compresses replacement cycles from hardware obsolescence to cartridge refresh intervals. |
| Local Calibration Partnership Establishment | Secures BIS certification pathway access for India commercial building mandates. |
| Edge-Computing Firmware Acquisition | Addresses embedded talent scarcity competing with automotive and consumer electronics. |
| Multi-Protocol Hardware Consolidation | Reduces production fragmentation from redundant BACnet, Modbus, and MQTT variants. |
Methodological Framework
Independent corroboration across facility management executives, HVAC system integrators, and calibration service technicians underwrites the qualitative findings in this study. Primary interviews with building automation procurement leads, MEMS fabrication engineers, and regulatory compliance officers combined with secondary validation from EPA refrigerant management filings, EU F-Gas Regulation implementation reports, and BIS certification databases. Bottom-up sensor shipment estimates triangulated against top-down building retrofit spending projections.
Rate-of-change decomposition across technology adoption curves, regulatory compliance schedules, and construction code evolution frames the analytical approach. Segmentation dimensions modeled include product type, network architecture, building ownership structure, and system application function throughout the forecast period. CAGRs derived from installed base growth, replacement cycle compression, and premium sensor mix expansion. Forecast inputs incorporate refrigerant-phase-down timeline acceleration and healthcare ventilation standard tightening.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEMS supply disruption, technician network development lags, and passive building envelope substitution effects. Model assumptions reflect documented regulatory schedules and disclosed construction code trajectories. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down velocity or China GB standards enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Digital Angle Gauge Market