
 Global Fruit and Vegetable Seeds Market | 2026-2036
Global Fruit and Vegetable Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit and Vegetable Seeds Market Analysis
Project finance and leasing arrangements for precision breeding infrastructure is tilting competitive advantage toward firms with balance-sheet capacity to fund multi-year development cycles. Bayer AG leverages its crop science division's integrated germplasm libraries to sustain R&D pipelines across temperate and tropical vegetable categories. Sakata Seeds Corporation anchors its position through specialized melon and brassica breeding programs that dominate Asian export supply chains.
Fruit and vegetable seeds are sexually or vegetatively propagated reproductive units containing embryonic plants, genetic material, and nutrient reserves, typically specified by germination rate, genetic purity percentage, and pathogen load thresholds; they function as the foundational biological input for commercial food crop production systems. Vegetable seeds generate the dominant revenue pool within product type segmentation due to shorter breeding cycles and higher replacement rates among commercial growers. Organic seeds represent the fastest-expanding seed treatment category as certification bodies in the European Union and North America tighten allowable input lists for certified organic operations.
The EU Seed Marketing Regulations and OECD Seed Schemes establish cross-border varietal certification and genetic identity standards that govern market access for seed exporters into European markets. The United States Department of Agriculture and China's Ministry of Agriculture and Rural Affairs enforce parallel phytosanitary and biotech approval frameworks that shape product registration timelines and trait commercialization pathways. Stakeholders must monitor divergence between regional gene-editing regulatory classifications to anticipate which breeding technologies will face accelerated or delayed approval timelines.
Market Dynamics
Gene-editing regulatory divergence between jurisdictions is fragmenting breeding technology investment, forcing seed developers to maintain parallel trait pipelines for markets with incompatible approval frameworks.
Growth Catalysts
- EU Seed Marketing Regulations:Harmonized varietal certification across member states reduces registration duplication costs for breeders seeking multi-country market access.
- Vertical farming clusters:Controlled-environment agriculture facilities in the Netherlands and United States are contracting directly with breeders for cultivars optimized for artificial light spectra and hydroponic substrates.
- CRISPR-Cas12a systems:Multiplexed gene-editing platforms accelerate trait stacking for disease resistance in solanaceous vegetables, compressing development timelines relative to conventional backcrossing.
Market Restraints
- Phytosanitary certificate backlogs:USDA Animal and Plant Health Inspection Service processing delays for cross-border seed shipments extend inventory holding periods for exporters targeting multiple markets.
- Hybrid parent line concentration:Inbred germplasm for major vegetable categories concentrates among three to five proprietary breeding programs, creating supply vulnerability for second-tier seed companies.
- Organic seed availability gaps:Certified organic vegetable seed stocks remain insufficient for full substitution of conventional inputs in high-volume crops like tomato and pepper.
Strategic Opportunities
- India's seed subsidy restructuring:The government's move toward direct benefit transfers for vegetable seeds opens procurement channels bypassing state agricultural universities.
- Biostimulant-coated priming:Convergence of biological inoculant formulations with precision seed coating equipment creates premium positioning for stress-tolerance claims.
- Drone-enabled phenotyping:High-throughput aerial imaging of breeding trials compresses selection cycles for quantitative traits in open-field vegetables.
Industry Challenges
- Quantitative geneticist scarcity:Breeding programs compete for talent capable of integrating genomic selection models with field validation protocols.
- Trait stewardship compliance:Insect-resistant vegetable varieties require refuge planting mandates that conflict with intensive greenhouse production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit and Vegetable Seeds Market |
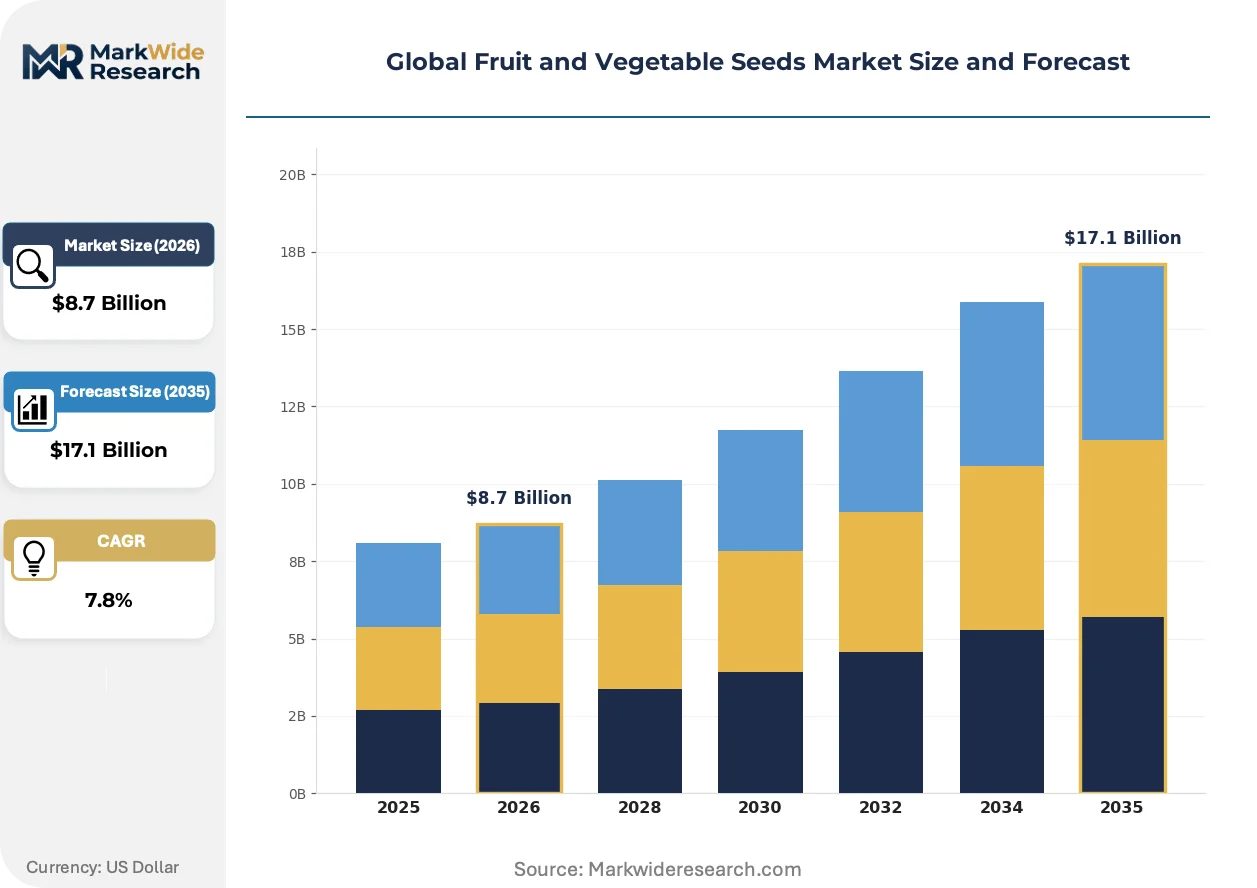
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Seeds, Vegetable Seeds, Herb Seeds, Flower Seeds Application: Agriculture, Horticulture, Home Gardening, Commercial Cultivation Distribution Channel: Online Retail, Agricultural Stores, Garden Centers, Wholesalers Seed Treatment: Organic Seeds, Conventional Seeds, Treated Seeds, Untreated Seeds |
| Companies Covered | Syngenta Group, Sakata Seeds Corporation, Bayer AG, Bejo Zaden BV, Enza Zaden BV, BASF SE, Rijk Zwaan Zaadteelt en Zaadhandel BV, Corteva Agriscience, Groupe Limagrain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit and Vegetable Seeds Market Emerging Trajectories
Speed breeding protocols and computational trait prediction are compressing variety development cycles, while regulatory fragmentation around gene-edited products is forcing geographic specialization in breeding program locations.
Speed breeding is hybridizing conventional photoperiod manipulation with LED spectrum tuning to compress generation times in long-day vegetable crops. Greenhouse operators in the Netherlands and China are adopting these protocols for rapid cultivar turnover. The technology is hybridizing breeding program economics by enabling multi-environment testing within single calendar years.
EU F-Gas Regulation phase-down schedules are accelerating breeder investment in heat-tolerant vegetable genetics for southern European production zones. Seed companies are relocating thermogenesis-sensitive crossing blocks to higher-latitude facilities. Mediterranean open-field tomato and pepper breeding is most affected, with programs shifting parent line maintenance to Denmark and Poland.
Direct-to-grower digital seed procurement is displacing traditional distributor networks for large-scale vegetable operations. E-commerce platforms with cultivar performance databases and climate-matching algorithms are capturing contract farming accounts in California's Central Valley and Spain's Almería province. This channel shift is most visible among greenhouse consortia purchasing tomato rootstock seeds in volume tiers exceeding 500,000 units annually.
Global Fruit and Vegetable Seeds Market Segmentation
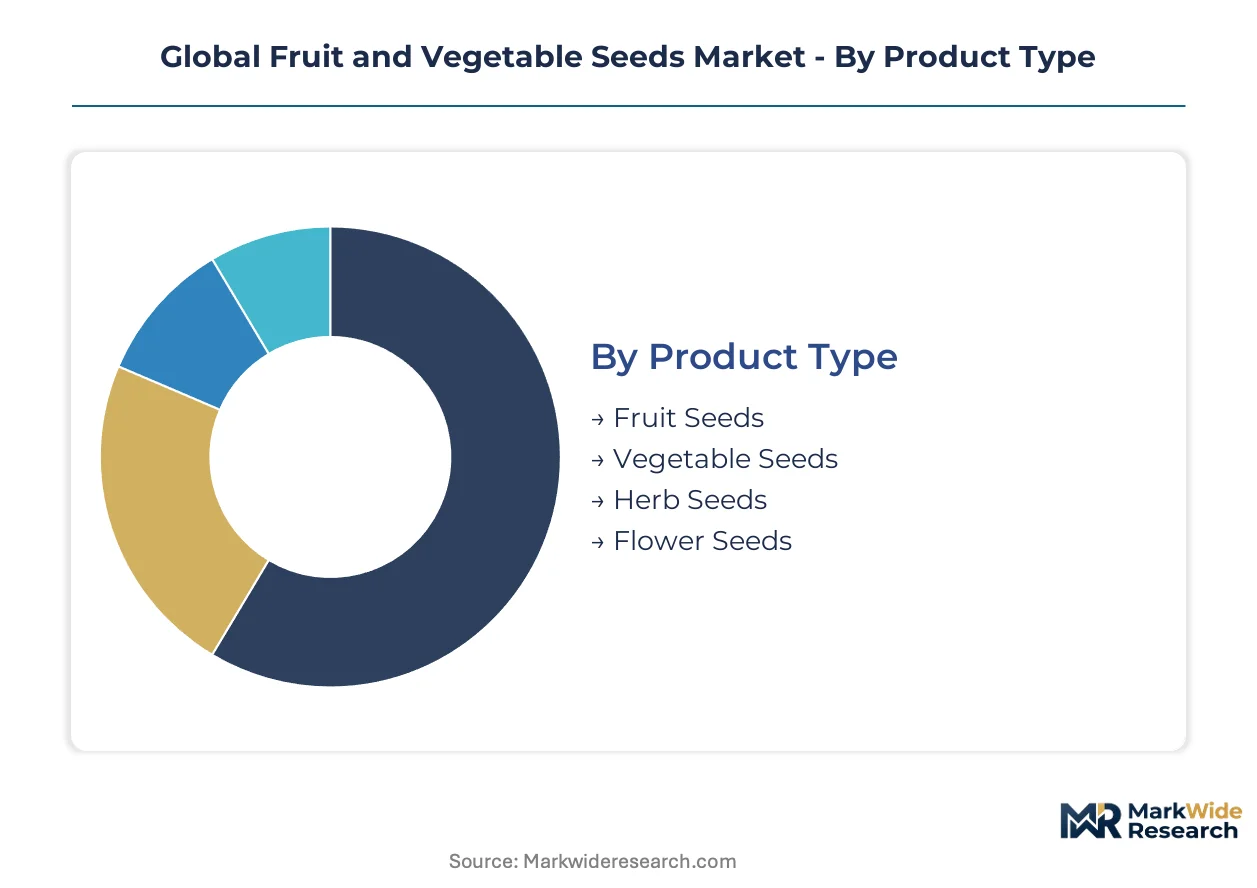
Segmentation in fruit and vegetable seeds reflects divergent breeding cycles, certification requirements, and buyer procurement behaviors. Each dimension shapes investment allocation across germplasm development, treatment technologies, and channel infrastructure.
Product Type:
Mature categories dominate procurement volumes while emerging segments reshape portfolio priorities for breeders.
- Vegetable Seeds:Brassica, solanaceous, and cucurbit seeds with specified germination rates and genetic purity percentages. Commercial greenhouse operators in the Netherlands and Almería province contract directly for hybrid tomato and pepper cultivars optimized for artificial light spectra, compressing replacement cycles.
- Fruit Seeds:Sexually propagated units for watermelon, melon, and strawberry propagation with pathogen load thresholds. Demand concentrates in China's Shouguang cluster and California's Central Valley, where seedless watermelon breeding programs face pollenizer management constraints.
- Herb Seeds:Small-seeded propagules for basil, cilantro, and parsley with rapid emergence requirements.
- Flower Seeds:Ornamental propagules with extended dormancy protocols for bedding and cut flower production.
Vegetable seeds handle the majority of throughput; herb seeds are the fastest mover on share as controlled-environment agriculture expands.
Application:
Cost tier differentiation separates capital-intensive operations from low-input cultivation systems.
- Commercial Cultivation:Large-scale contract farming and greenhouse consortia purchasing volume tiers exceeding 500,000 units annually. Netherlands-based vertical farming facilities source cultivars with hydroponic substrate compatibility, while USDA phytosanitary certificates govern cross-border seed shipments.
- Agriculture:Open-field row crop production with mechanized planting and harvest timing constraints.
- Horticulture:Nursery stock propagation and landscape installation with varietal trademark requirements.
- Home Gardening:Small-package retail sales through garden centers and e-commerce platforms with climate-matching algorithms.
Commercial cultivation commands the premium tier; home gardening is gaining share fastest through direct-to-grower digital procurement.
Distribution Channel:
Channel selection tracks buyer scale and technical support requirements across the customer base.
- Wholesalers:Volume aggregation for multi-regional seed companies with inventory holding and credit extension capabilities. EU Seed Marketing Regulations harmonize varietal certification, reducing registration duplication for breeders accessing multiple member states through distributor networks.
- Agricultural Stores:Rural supply points with seasonal demand concentration and extension service linkages.
- Online Retail:E-commerce platforms capturing California Central Valley contract farming accounts with cultivar performance databases.
- Garden Centers:Point-of-sale displays for home gardening segments with impulse purchase dynamics.
Wholesalers maintain the deepest penetration; online retail is climbing the fastest as greenhouse consortia bypass traditional distributor networks.
Seed Treatment:
Certification standards and input allowances fragment the treatment landscape across regulatory jurisdictions.
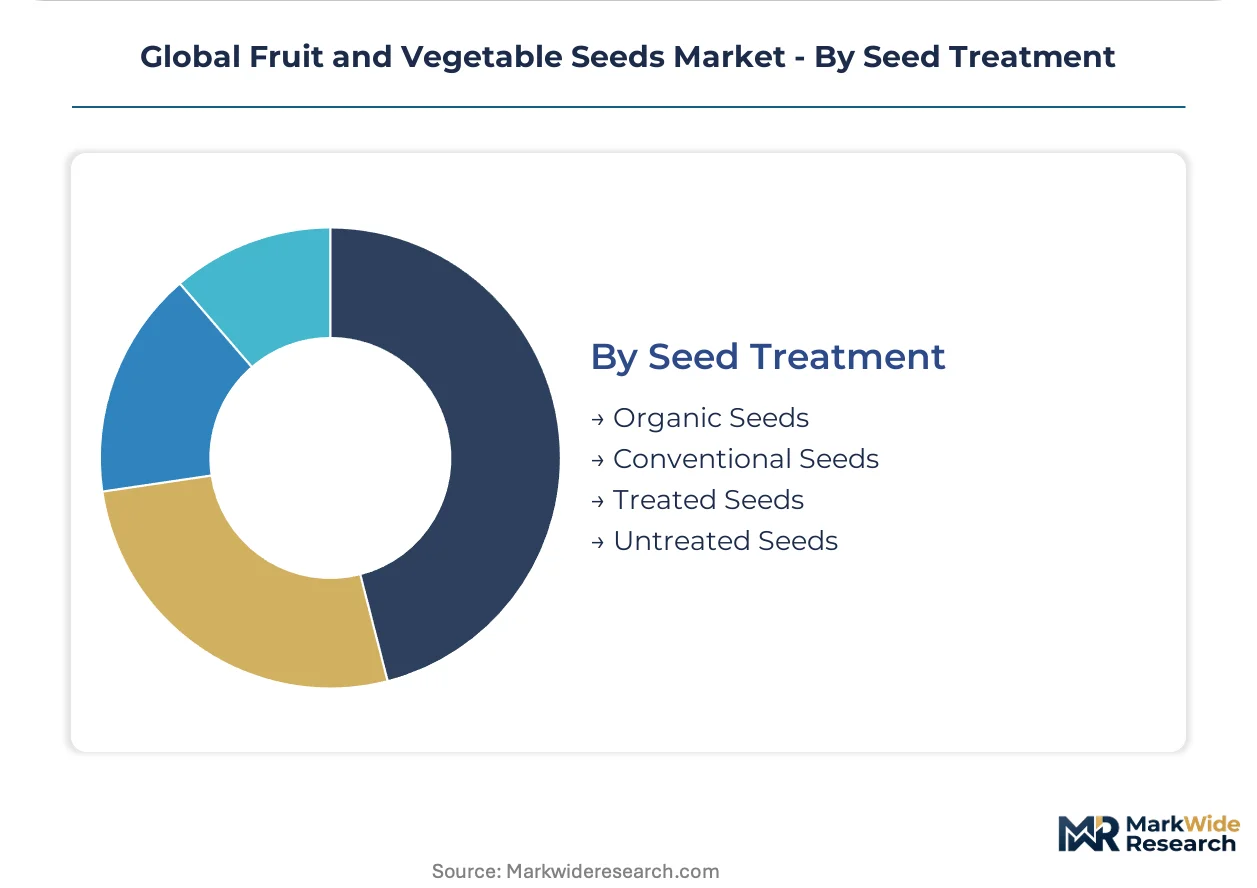
- Organic Seeds:Certified propagules meeting EU and North American organic certification body allowable input lists. Availability gaps persist for high-volume tomato and pepper substitution, constraining full conversion of certified organic operations.
- Conventional Seeds:Standard untreated propagules without biological or chemical enhancement.
- Treated Seeds:Coated units with biostimulant inoculants or protective chemistries for stress tolerance claims.
- Untreated Seeds:Raw propagules for markets with restrictive residue thresholds or farmer-applied treatment preferences.
Conventional seeds represent the volume foundation; organic seeds show the steepest expansion trajectory as certification bodies tighten input restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fruit and vegetable seeds track breeding program locations against cultivation demand centers. The Netherlands maintains surplus positions in hybrid vegetable genetics while China and India remain net importers of proprietary germplasm.
Netherlands
Wageningen University accelerates speed breeding protocols for greenhouse tomato cultivars. The EU Seed Marketing Regulations harmonize varietal certification across member states, reducing registration costs for Dutch breeders. Westland greenhouse consortia contract directly with seed houses for hydroponic-optimized rootstocks.
United States
California Central Valley contract farming operations drive volume procurement of melon and pepper hybrids. The USDA Animal and Plant Health Inspection Service enforces phytosanitary certificate requirements for cross-border shipments. Davis, California anchors public-private breeding partnerships for heat-tolerant solanaceous varieties.
China
Shouguang vegetable cluster demand concentrates procurement of watermelon and brassica seeds. The Ministry of Agriculture and Rural Affairs operates parallel biotech approval frameworks alongside OECD Seed Scheme alignment efforts. Yangtze River Delta greenhouse operators source hybrid tomato cultivars optimized for humid subtropical conditions.
India
Maharashtra and Karnataka contract farming networks expand vegetable seed procurement under subsidy restructuring. The government's direct benefit transfer program opens procurement channels bypassing state agricultural universities. Nashik district greenhouse consortia negotiate volume contracts for protected cultivation tomato varieties.
Spain
Almería province greenhouse operators import hybrid pepper and cucumber seeds at volume tiers exceeding 500,000 units annually. The EU F-Gas Regulation phase-down accelerates breeder investment in heat-tolerant genetics for southern European zones. Murcia breeding stations relocate thermogenesis-sensitive crossing blocks to northern latitudes.
Global Fruit and Vegetable Seeds Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in germplasm development and trait licensing. The vendor base concentrates among ten to fifteen proprietary breeding programs with integrated biotechnology pipelines. Strategic archetypes span multinational agrochemical-seed conglomerates, family-held regional specialists, and public-private research partnerships. Consolidation through germplasm library acquisitions and technology licensing agreements defines competitive maneuvering.
Within the multinational tier, Bayer AG and Syngenta Group occupy positions spanning temperate and tropical vegetable categories. Sakata Seeds Corporation exemplifies the specialized regional archetype through concentrated melon and brassica breeding programs. BASF SE and Corteva Agriscience sit within the integrated input platform segment, combining seed genetics with crop protection portfolios.
| Leading Market Players |
|---|
| Syngenta Group |
| Sakata Seeds Corporation |
| Bayer AG |
| Bejo Zaden BV |
| Enza Zaden BV |
| BASF SE |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Corteva Agriscience |
| Groupe Limagrain |
| Others |
Supply Flow & Price Mechanics
Parent line concentration in Dutch and Japanese breeding programs concentrates pricing power with germplasm owners, while downstream margin pools fragment across distributors, coating facilities, and direct-to-grower digital platforms.
Pricing Analysis
Commercial greenhouse consortia anchor seed pricing through volume-tier contracts exceeding 500,000 units annually. Pricing stratifies across premium hybrid genetics, certified organic propagules, and untreated commodity grades. Cost compression in conventional untreated tiers intensifies as Chinese state-backed breeding programs expand output. Home gardening segments exhibit highest price sensitivity, while vertical farming operators prioritize performance premiums over unit cost.
Supply Chain Analysis
Contract multiplication capacity concentrates with Dutch greenhouse operators, Chinese state seed stations, and Indian contract farming networks. Parent seed production draws from the Netherlands, Japan, and the United States, while coating and priming services cluster in Germany and China. Single-source vulnerability runs through proprietary inbred lines held by three to five breeding programs. Distribution runs through wholesaler networks with EU Seed Marketing Regulations harmonizing cross-border certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward greenhouse consortia and vertical farming operators as procurement scales concentrate demand among fewer volume-tier accounts.
For Market Incumbents: Harden germplasm control through exclusive parent line maintenance agreements with Dutch and Japanese multiplication facilities. Deepen backward integration into biostimulant coating technologies to capture premium positioning. Defensive patent filings around CRISPR-Cas12a trait stacks will deter emerging gene-editing specialists from encroaching on solanaceous vegetable categories. For New Entrants and Emerging Players: Establish a beachhead in certified organic vegetable seed supply, where availability gaps in tomato and pepper constrain full market conversion. India's direct benefit transfer subsidy restructuring opens procurement channels bypassing entrenched state university networks. A drone-enabled phenotyping service model offers asset-light entry with rapid breeding cycle compression for open-field vegetable programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with family-held regional specialists in melon and brassica genetics across East Asia. Long-term viability hinges on regulatory navigation capacity across divergent gene-editing approval frameworks. Watch for EU F-Gas Regulation acceleration as signal for heat-tolerant genetics valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Speed Breeding Infrastructure Investment | Wageningen University protocols compress generation times for Netherlands greenhouse operators. |
| Gene-Editing Trait Pipeline Diversification | Parallel CRISPR-Cas12a stacks accommodate regulatory divergence between USDA and EU frameworks. |
| Direct-to-Grower Digital Platform Launch | E-commerce with climate-matching algorithms captures California Central Valley contract farming accounts. |
| Organic Seed Certification Expansion | EU and North American allowable input list alignment opens premium positioning for treated organic propagules. |
| Heat-Tolerant Genetics Development | Mediterranean open-field tomato breeding shifts parent line maintenance to Denmark and Poland facilities. |
Methodological Framework
Desk research of OECD Seed Scheme documentation, EU Seed Marketing Regulations, USDA APHIS phytosanitary filings, and China Ministry of Agriculture biotech approval records preceded structured interviews with vegetable breeding program directors, greenhouse operations managers, seed coating facility engineers, and organic certification body technical reviewers. Bottom-up variety-level volume estimates triangulated against top-down national seed import statistics.
Assumptions held regulatory classification of gene-edited products constant across jurisdictions while varying subsidy program penetration rates and vertical farming capacity buildout speeds. Segmentation modeling crossed product type, application tier, distribution channel, and seed treatment certification with regional regulatory cluster assignments. CAGRs derived from logistic diffusion curves fitted to historical replacement rates and projected breeding cycle compression from speed breeding adoption.
Sensitivities concentrate around gene-editing regulatory reclassification timelines and organic certification input list revisions. Forecasts reflect these assumption sets without claiming predictive certainty. Quarterly review of EU F-Gas Regulation implementation pace and USDA APHIS certificate processing backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Onion Seed Market
Seeds
Europe Amaranth Market
Seeds
South America Forage Seed Market
Seeds
Ghana Seed Extract Market
Seeds
South America Quinoa Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Commercial Seed Market
Seeds
North America Tomato Seed Market
Seeds
Bangladesh Seed Market
Seeds
Garlic Chive Seeds Market
Seeds
Global Vegetable Seed Market
Seeds
Seed Cracker Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Tomato Seed Market
Seeds
Flax Seed Market
Seeds
Asia-Pacific Maize Seed Market