
 Global AI in Agriculture Market | 2026-2036
Global AI in Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Agriculture Market Foresight
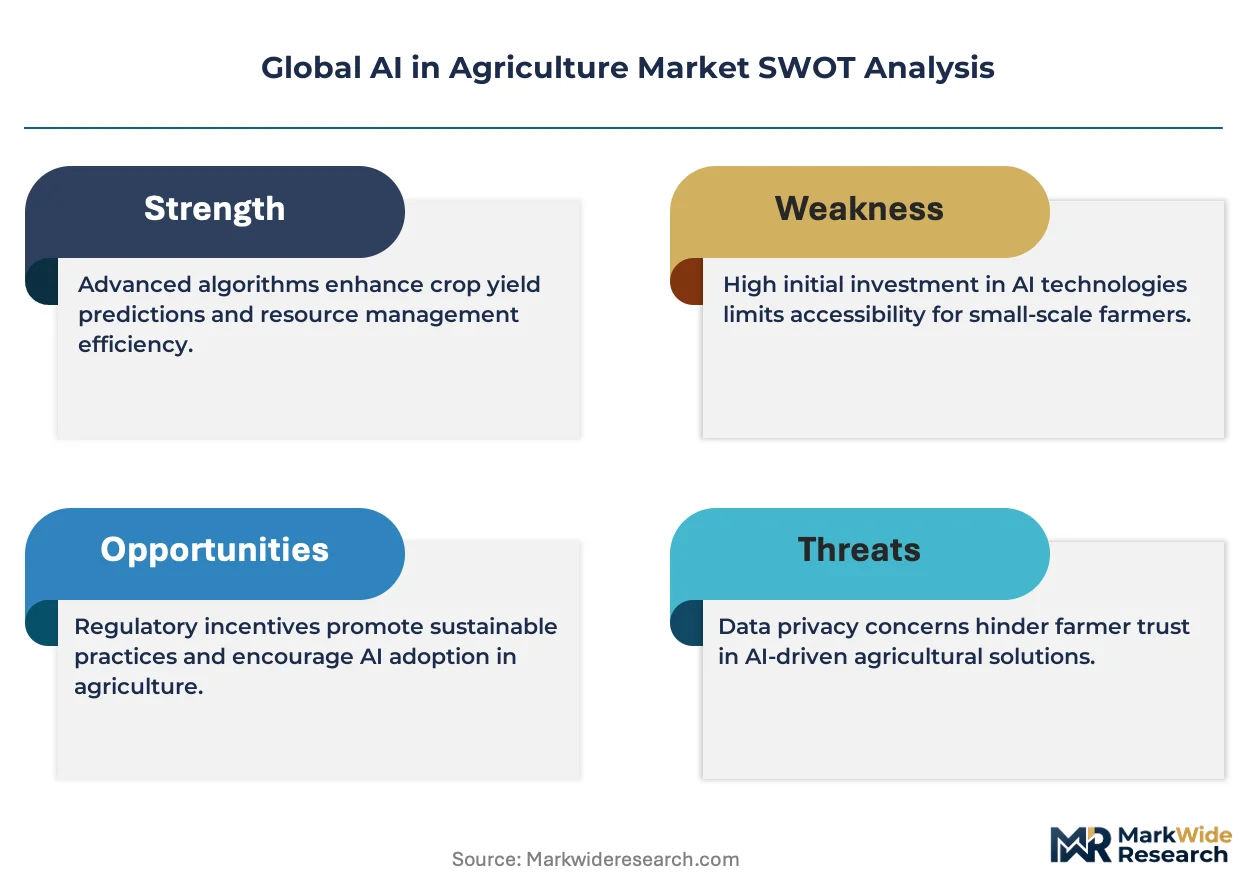
Platform licensing revenue is tilting from perpetual software sales toward recurring subscription models for farm management systems. John Deere leverages its proprietary Operations Center to lock in equipment-software bundling across North American dealer networks. Microsoft anchors cloud infrastructure demand through Azure FarmBeats, which competes with IBM's Watson Decision Platform for crop modeling services.
Artificial intelligence in agriculture encompasses machine learning algorithms, computer vision systems, and autonomous robotics deployed to optimize planting schedules, detect crop stress, and automate harvesting decisions with sub-centimeter GPS accuracy. The primary commercial purpose centers on reducing input waste while maximizing yield per hectare through real-time field data processing. Machine learning applications in yield prediction command the deepest margin pools due to their direct linkage to crop insurance and commodity trading decisions, while edge computing deployments are expanding fastest among mid-size farms seeking low-latency automation without persistent broadband connectivity.
The EPA regulates pesticide application rates that AI-guided sprayers must respect, while the EU AI Act imposes risk-classification requirements on autonomous farming equipment operating near populated areas. USDA conservation programs increasingly tie cost-share eligibility to documented precision agriculture adoption, channeling subsidy flows toward sensor-equipped operations. Stakeholders must monitor whether emerging data sovereignty frameworks fragment cross-border agricultural data lakes or preserve the interoperability that underpins multi-continental farm management platforms.
Market Dynamics
Platform licensing revenue is tilting from perpetual software sales toward recurring subscription models for farm management systems, locking equipment-software bundling across dealer networks and cloud infrastructure providers.
Growth Catalysts
- EU Green Deal:Mandatory sustainability reporting requirements are forcing European farming cooperatives to adopt sensor-based compliance tracking systems.
- Computer vision:Drone-mounted multispectral cameras now enable sub-centimeter weed detection, cutting herbicide application volumes by targeted spot-spraying.
- Brazil:Large-scale soy and sugarcane operations are deploying autonomous harvest fleets to offset seasonal labor shortages during peak windows.
Market Restraints
- Semiconductor supply:GPU and edge-AI chip shortages from Taiwan-based foundries are extending equipment delivery timelines for precision agriculture OEMs.
- EU AI Act:Risk-classification requirements for autonomous equipment operating near populated areas are adding certification costs and deployment restrictions.
- Broadband infrastructure:Persistent connectivity gaps in rural Australia and central US states limit cloud-dependent analytics adoption on mid-size farms.
Strategic Opportunities
- India:Subsidy programs under the PLI scheme for agricultural mechanization are channeling public capital toward domestic AI-enabled equipment manufacturing.
- Carbon credit verification:Blockchain-anchored soil carbon measurement protocols are opening new revenue streams for regenerative farming operations.
- Edge-LiDAR convergence:Fusion of low-cost LiDAR sensors with on-device ML inference is enabling real-time orchard canopy management without cellular uplink.
Industry Challenges
- Agronomic data science talent:The shortage of practitioners who combine crop physiology expertise with machine learning engineering is constraining solution development cycles.
- Interoperability standards:Proprietary data formats from John Deere Operations Center, Climate FieldView, and Granular platforms are fragmenting multi-vendor farm management workflows.
- Capex intensity:Retrofit kits for autonomous tractor guidance require upfront investments that stretch payback periods beyond typical three-year equipment financing terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Agriculture Market |
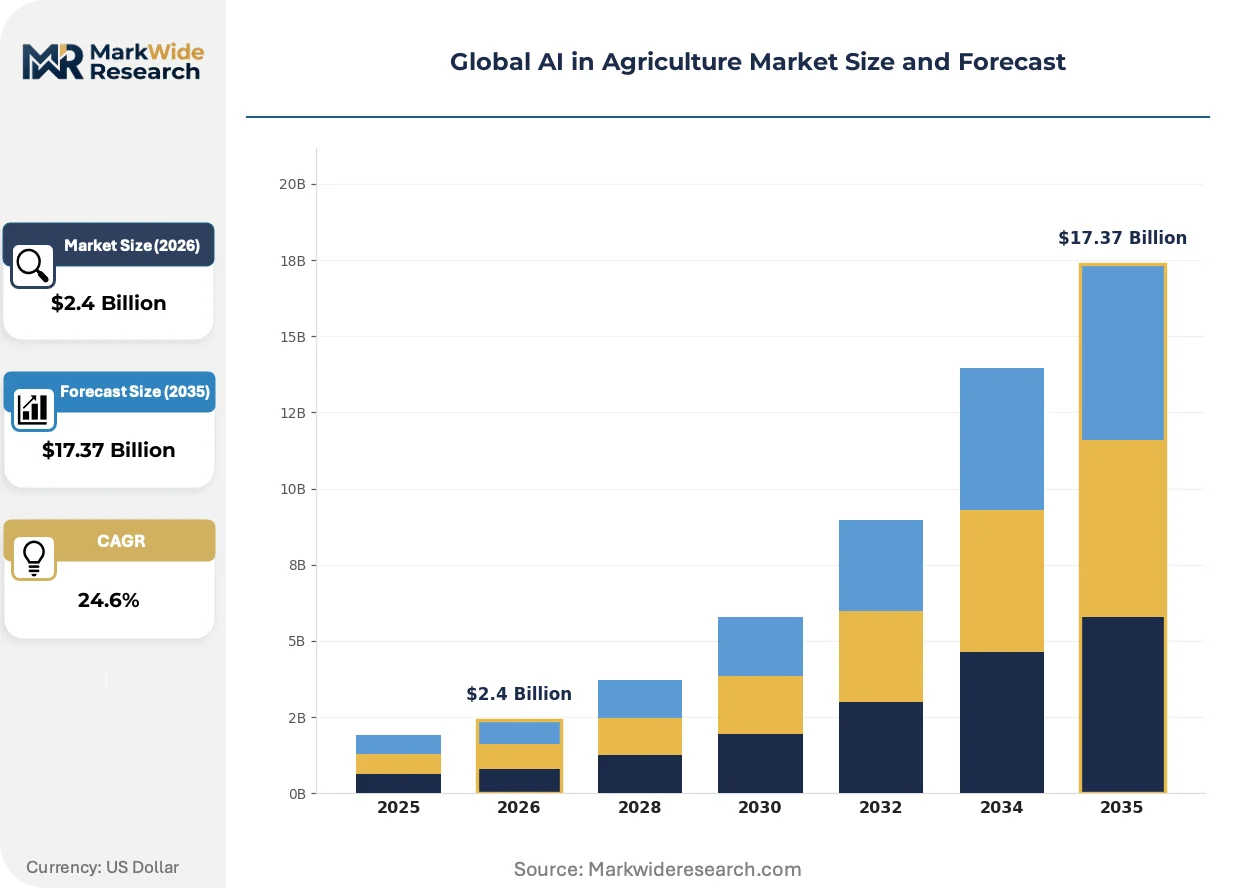
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.37 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, Robotics, Natural Language Processing, Predictive Analytics Application: Precision Farming, Crop Monitoring, Soil Analysis, Pest Detection, Yield Prediction End User: Farmers, Agronomists, Agricultural Consultants, Research Institutions, Food Producers Deployment: Cloud-based, On-Premise, Edge Computing, Hybrid Models |
| Companies Covered | John Deere, Microsoft, IBM, Bayer Crop Science, Corteva, Trimble, Syngenta Group, Taranis, Valmont Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Agriculture Market Shifts & Advancements
Digital twin technology is virtualizing field-level agricultural operations, compressing the feedback loop between sensing and actuation while enabling scenario modeling for input optimization.
Hyperspectral imaging systems mounted on unmanned aerial vehicles are virtualizing crop health assessment by capturing narrow-band reflectance data invisible to standard RGB cameras. Mid-size vegetable growers in California's Central Valley are adopting these systems at accelerating pace to detect early-stage disease pressure. This virtualization of scouting labor is compressing the timeline between stress detection and targeted intervention from weeks to hours.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in controlled-environment agriculture, forcing greenhouse operators to retrofit climate control systems with natural refrigerant alternatives. This regulatory pressure is redirecting capital toward AI-optimized HVAC systems that maintain precision growing conditions with lower refrigerant volumes. Dutch greenhouse clusters are responding fastest, integrating predictive climate algorithms with geothermal exchange infrastructure.
Consolidated buying cooperatives in the US Corn Belt are unbundling after-sales service contracts from equipment purchases, demanding à-la-carte software subscriptions and third-party maintenance options. This disintermediation of OEM service networks is pressuring traditional dealer margin structures. The pattern is most visible across Iowa and Illinois, where multi-thousand-acre operations now negotiate direct cloud infrastructure contracts independent of machinery financing packages.
Global AI in Agriculture Market Segmentation
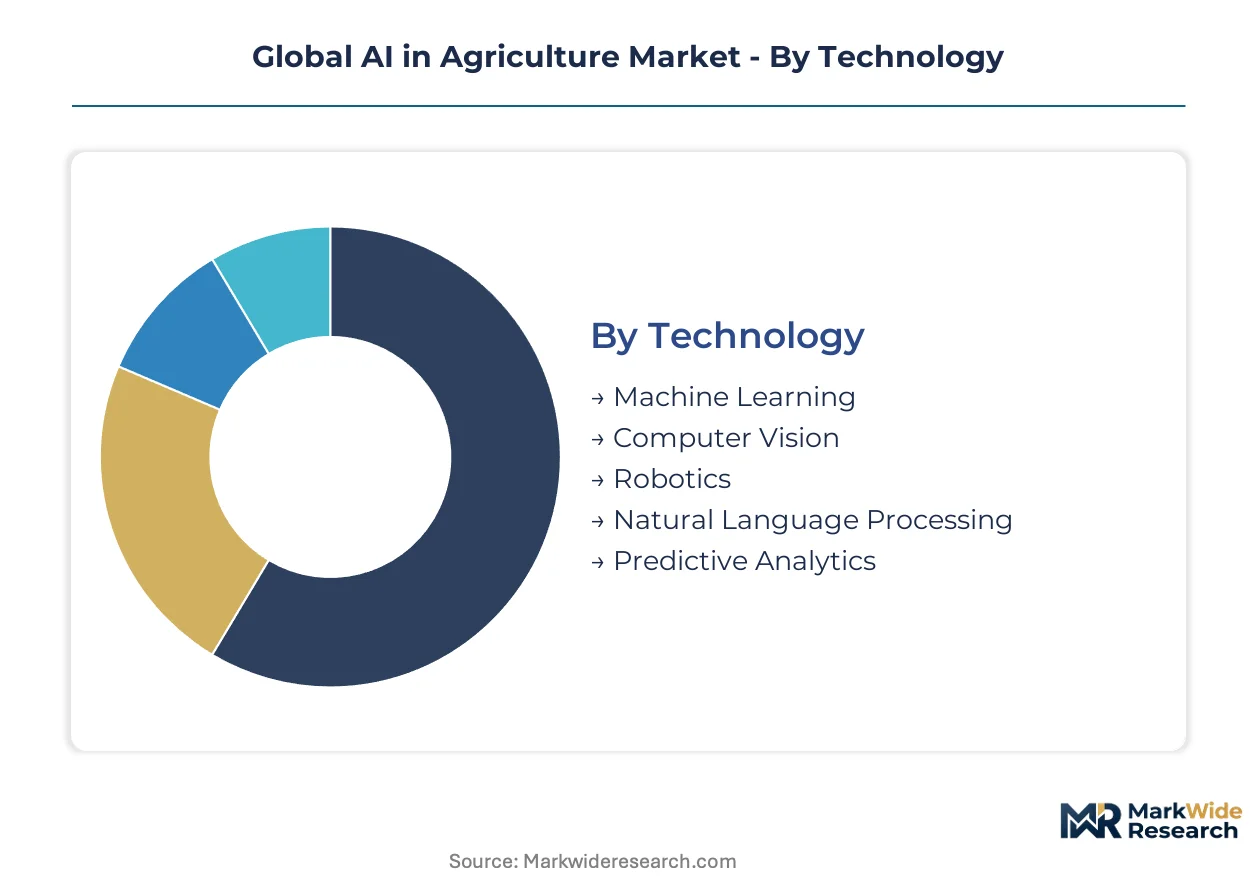
Segmentation of the Global AI in Agriculture Market reveals how technology maturity, deployment economics, and end-user sophistication create divergent investment profiles across the value chain. Understanding these fault lines enables targeted platform development and channel strategy calibration.
Technology:
Mature algorithmic approaches now compete with emerging modalities for capital allocation and talent attention.
- Machine Learning:Supervised learning models trained on historical yield datasets power commodity price forecasting and crop insurance underwriting. Demand concentrates among North American grain traders and Brazilian soy cooperatives seeking basis risk reduction.
- Computer Vision:Convolutional neural networks process multispectral drone imagery to detect early-stage crop stress and weed infestations with sub-centimeter resolution. California vegetable growers and Dutch greenhouse operators deploy these systems to compress scouting-to-intervention timelines from weeks to hours.
- Robotics:Autonomous harvesters and precision sprayers integrate LiDAR with real-time kinematic GPS for unmanned field operations.
- Natural Language Processing:Voice-enabled farm management interfaces and automated regulatory compliance documentation tools serve multilingual agricultural workforces.
- Predictive Analytics:Time-series forecasting engines synthesize weather, soil, and market data for input timing optimization.
Machine Learning retains volume leadership; Computer Vision holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive field automation from software-centric monitoring services.
- Precision Farming:Variable-rate application systems adjust seeding density and fertilizer placement using real-time soil sensor feedback. Large-scale operations in Iowa and Mato Grosso justify equipment costs through input savings exceeding 15% on nitrogen and phosphorous.
- Crop Monitoring:Satellite and drone-based surveillance platforms track phenological development across thousands of hectares. Australian broadacre wheat producers and Ukrainian sunflower operations subscribe to these services for drought early warning.
- Soil Analysis:Electrochemical sensor arrays and spectroscopic probes map macro and micronutrient distribution at tillage depth.
- Pest Detection:Pheromone trap cameras and acoustic sensors identify invasive species before threshold populations establish.
- Yield Prediction:Ensemble models combining remote sensing with ground-truth sampling inform commodity hedging and storage logistics.
Precision Farming commands the premium pricing tier; Crop Monitoring scales fastest among mid-size operations.
End User:
Customer type determines solution complexity, with technical sophistication and capital access creating distinct purchasing patterns.
- Farmers:Owner-operators managing 500-5,000 hectares prioritize intuitive dashboards and dealer-supported implementation. Demand clusters in US Corn Belt counties and Punjab's rice-wheat belt where smartphone penetration enables mobile-first platform adoption.
- Agronomists:Crop consultants leverage prescription algorithms to differentiate advisory services and justify per-hectare retainers.
- Agricultural Consultants:Multi-client service providers require white-label analytics and cross-farm benchmarking capabilities.
- Research Institutions:Universities and national agricultural laboratories source experimental platforms with open API architectures for algorithm publication.
- Food Producers:Integrated processors and retailers demand traceability-linked compliance documentation for ESG reporting and consumer transparency.
Farmers represent the installed base anchor; Food Producers are expanding procurement most aggressively.
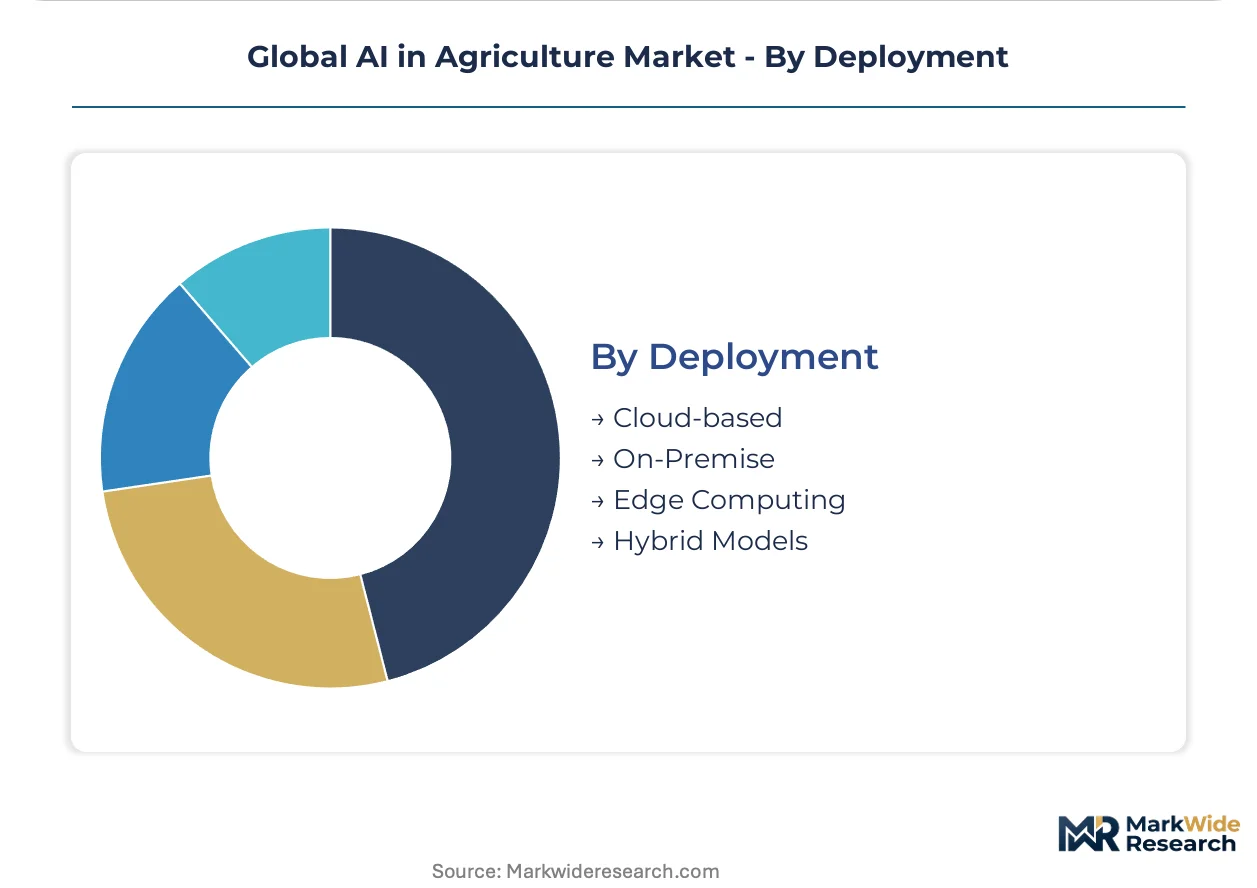
Deployment:
Connectivity infrastructure and data sovereignty preferences shape architecture selection across geographies.
- Cloud-based:Centralized data lakes enable model retraining on aggregated field observations and seamless software updates. German and Danish farming cooperatives favor this architecture for cross-member analytics and EU Green Deal compliance reporting.
- On-Premise:Local server installations satisfy data residency requirements and eliminate subscription dependencies. Chinese state farms and Saudi Arabian mega-projects specify this model for operational security and long-term cost control.
- Edge Computing:On-device inference processors execute real-time decisions without cellular uplink. Rural Australian stations and central US counties with spotty broadband deploy edge-LiDAR and autonomous guidance with minimal latency.
- Hybrid Models:Tiered architectures process sensitive telemetry locally while pushing aggregated insights to cloud analytics engines.
Cloud-based deployments dominate new contract value; Edge Computing is climbing fastest where connectivity gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture infrastructure investment varies sharply across geographies. Brazilian soy operations prioritize autonomous fleet deployment for labor substitution, while Dutch greenhouse clusters emphasize AI-optimized climate systems for regulatory compliance. Indian smallholders adopt mobile-first platforms through subsidy channels, diverging from North American equipment-centric models.
United States
Large-scale corn and soybean operations in Iowa and Illinois drive autonomous tractor guidance and variable-rate application adoption. USDA conservation programs tie cost-share eligibility to documented precision agriculture implementation, channeling subsidy flows toward sensor-equipped farms. The Corn Belt's consolidated buying cooperatives now negotiate direct cloud infrastructure contracts independent of machinery financing packages.
Brazil
Mato Grosso soy operations and São Paulo sugarcane estates deploy autonomous harvest fleets to offset seasonal labor shortages during peak windows. The country's national agricultural regulator enforces equipment safety standards for unmanned machinery operating near populated areas. Precision agriculture OEMs face extended delivery timelines due to semiconductor supply constraints from Asian foundries.
China
State farms in Heilongjiang and Xinjiang specify on-premise server installations for data residency and operational security, diverging from cloud-first architectures elsewhere. The Ministry of Industry and Information Technology sets GB standards for agricultural IoT device interoperability. Yangtze River Delta greenhouse operators integrate AI-optimized HVAC systems with geothermal exchange infrastructure to meet dual carbon goals.
Germany
Bavarian and Lower Saxony farming cooperatives favor centralized data lakes for cross-member analytics and EU Green Deal compliance reporting. The EU AI Act imposes risk-classification requirements on autonomous equipment, adding certification costs for OEMs. German greenhouse clusters lead retrofit adoption of natural refrigerant climate systems under F-Gas Regulation phase-down mandates.
Australia
Broadacre wheat producers in New South Wales and Queensland subscribe to satellite-based crop monitoring for drought early warning. Persistent connectivity gaps in rural stations limit cloud-dependent analytics adoption, accelerating edge-LiDAR and autonomous guidance deployment with minimal latency. The country's national agricultural regulator oversees pesticide application rates that AI-guided sprayers must respect.
Global AI in Agriculture Market Competitive Landscape
Capability concentration sits with precision equipment OEMs and cloud infrastructure providers; scale advantage sits with agricultural input conglomerates and software platforms. The market structures around three tiers: integrated machinery-software bundlers, standalone analytics specialists, and input-chemistry players extending into digital services. Dominant competitive moves include equipment-software bundling across dealer networks and strategic cloud partnerships for farm data aggregation.
Within the integrated machinery tier, John Deere exemplifies equipment-software lock-in through proprietary operations platforms. Microsoft and IBM anchor cloud infrastructure demand through agricultural data lake services, competing for crop modeling and predictive analytics contracts. Among input-chemistry conglomerates, Bayer Crop Science and Corteva represent the extension of seed and crop protection portfolios into digital agronomy advisory services.
| Leading Market Players |
|---|
| John Deere |
| Microsoft |
| IBM |
| Bayer Crop Science |
| Corteva |
| Trimble |
| Syngenta Group |
| Taranis |
| Valmont Industries |
| Others |
Supply & Pricing Matrix
Taiwan's semiconductor foundry clusters anchor global edge-AI chip supply for precision agriculture OEMs, with capacity allocation decisions rippling through equipment lead times and downstream subscription pricing power for farm management platforms.
Pricing Analysis
Long-term offtake contracts dominate GPU and edge-AI processor procurement, while farm management software shifts toward recurring SaaS tiers. Price differentiation rests on data interoperability certifications and after-sales service bundling. Cost compression in mid-tier precision equipment is intensifying because Brazilian and Australian buyers demand unbundled software subscriptions. Smallholder segments in India exhibit highest price sensitivity; large-scale Iowa and Mato Grosso operations show lowest.
Supply Chain Analysis
Contract manufacturing concentrates with TSMC and Samsung Foundry for AI inference chips, plus Foxconn and Jabil for sensor assembly. Taiwan, South Korea, and China feed critical GPU, LiDAR, and electrochemical sensor inputs. Single-source vulnerability in advanced node semiconductors threatens equipment delivery timelines. Distribution runs through John Deere and CNH Industrial dealer networks in North America, with direct cloud contracts emerging among consolidated US cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gap between agronomic domain expertise and machine learning engineering talent constrains solution development velocity, creating bottlenecks that favor organizations with captive data science capabilities.
For Market Incumbents: Pre-empt disintermediation of dealer service networks by unbundling software subscriptions before cooperative buyers force the issue. Invest in backward integration into edge-AI chip supply through strategic foundry partnerships to offset Taiwan concentration risk. Lock in agronomic data science talent through university pipeline programs. For New Entrants and Emerging Players: Pursue white-space opportunity in edge-LiDAR orchard management for rural Australian and central US counties with persistent broadband gaps. Target India's PLI-subsidized equipment manufacturing ecosystem for domestic production partnerships. Lead with mobile-first platforms bypassing dealer infrastructure entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized computer vision platforms with proven sub-centimeter weed detection accuracy over horizontal farm management suites. Five-to-ten year viability hinges on data interoperability standard adoption. Watch EU AI Act certification timelines as inflection signal for autonomous equipment deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures break John Deere and Climate FieldView data silos for multi-vendor workflows. |
| Edge-LiDAR Product Launch | Real-time canopy management without cellular uplink captures Australian station and US rural county demand. |
| Strategic Partnership | Microsoft Azure FarmBeats and IBM Watson alliances determine cloud infrastructure winners in crop modeling. |
| Acquisition of Specialist Firm | Computer vision startups with proven sub-centimeter resolution command premium in precision spraying applications. |
| Geographic Expansion | India PLI scheme channels public capital toward domestic AI-enabled tractor and harvester manufacturing. |
Research Methodology
Cross-validation between primary interviews with precision agriculture OEM product managers, farm cooperative procurement officers, and agronomic data scientists and secondary validation through USDA conservation program filings, EU Green Deal compliance databases, and SEC equipment manufacturer disclosures anchors the qualitative findings. Bottom-up farm-level adoption modeling triangulates against top-down cloud infrastructure capex tracking.
Calibration against historical precision agriculture equipment shipment data and SaaS subscription renewal rates informs the analytical framework across the projection horizon. Segmentation dimensions span technology modality, application cost tier, end-user sophistication, and deployment architecture. CAGRs derive from installed base expansion curves and input cost elasticity estimates, with weather volatility and commodity price cycles feeding scenario bounds.
Macroeconomic conditions sit as an overlay; deviation in farm credit availability and grain commodity prices would shift the trajectory. Forecasts reflect documented assumptions on broadband infrastructure buildout pace and EU AI Act enforcement intensity. Quarterly review of semiconductor foundry utilization rates and precision agriculture OEM order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Planting Agriculture Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Irrigation Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Fertigation Monitoring Market