
 Cameroon Fruits and Vegetables Market | 2026-2036
Cameroon Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Cameroon Fruits and Vegetables Market Outlook
Plastic packaging is consolidating around biodegradable alternatives in Cameroon's produce supply chain, cutting unit costs for exporters. Boh Plantations Limited leverages integrated farming to control banana quality from field to port. CAS Cameroon Ltd. anchors its position through pineapple specialization for European buyers. Ndawara Farms differentiates via high-altitude vegetable cultivation in the Northwest.
Cameroon fruits and vegetables encompass fresh and minimally processed plant products grown across agro-ecological zones from coastal lowlands to western highlands, typically harvested at physiological maturity and handled under temperature-controlled conditions to preserve shelf life and nutritional content. These products serve domestic food security, regional trade within Central Africa, and premium export markets demanding phytosanitary compliance. Root vegetables and citrus fruits occupy the largest volume share due to year-round cultivation feasibility and established processing infrastructure. Online marketplaces represent the fastest-expanding sales channel as urban connectivity improves and payment digitization spreads. Export-grade packaging commands superior margins through compliance with EU sanitary standards and retailer-specific traceability requirements.
Cameroon's Ministry of Agriculture and Rural Development, the national phytosanitary regulator, and CODEX-aligned food safety standards govern pesticide residue limits and export certification. The country's central bank and trade ministry shape foreign exchange access and cross-border logistics financing for agricultural exporters. Stakeholders must monitor evolving EU deforestation regulation implementation and its documentation demands on supply chain provenance.
Market Dynamics
Urban supermarket chains in Douala and Yaoundé are consolidating procurement around certified produce, forcing upstream suppliers to adopt traceability systems and sanitary protocols that reshape competitive positioning across the entire supply chain.
Growth Catalysts
- EU Deforestation Regulation:Cameroon's national standards body is accelerating documentation infrastructure for supply chain provenance, creating compliance-ready export capacity for European buyers.
- Biodegradable packaging:Plastic alternatives are cutting unit logistics costs for exporters serving cross-border trade corridors.
- Online marketplaces:Urban connectivity improvements and payment digitization are unlocking direct farmer-to-consumer channels in major processing corridors.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress margins for smallholder operations dependent on imported agrochemicals.
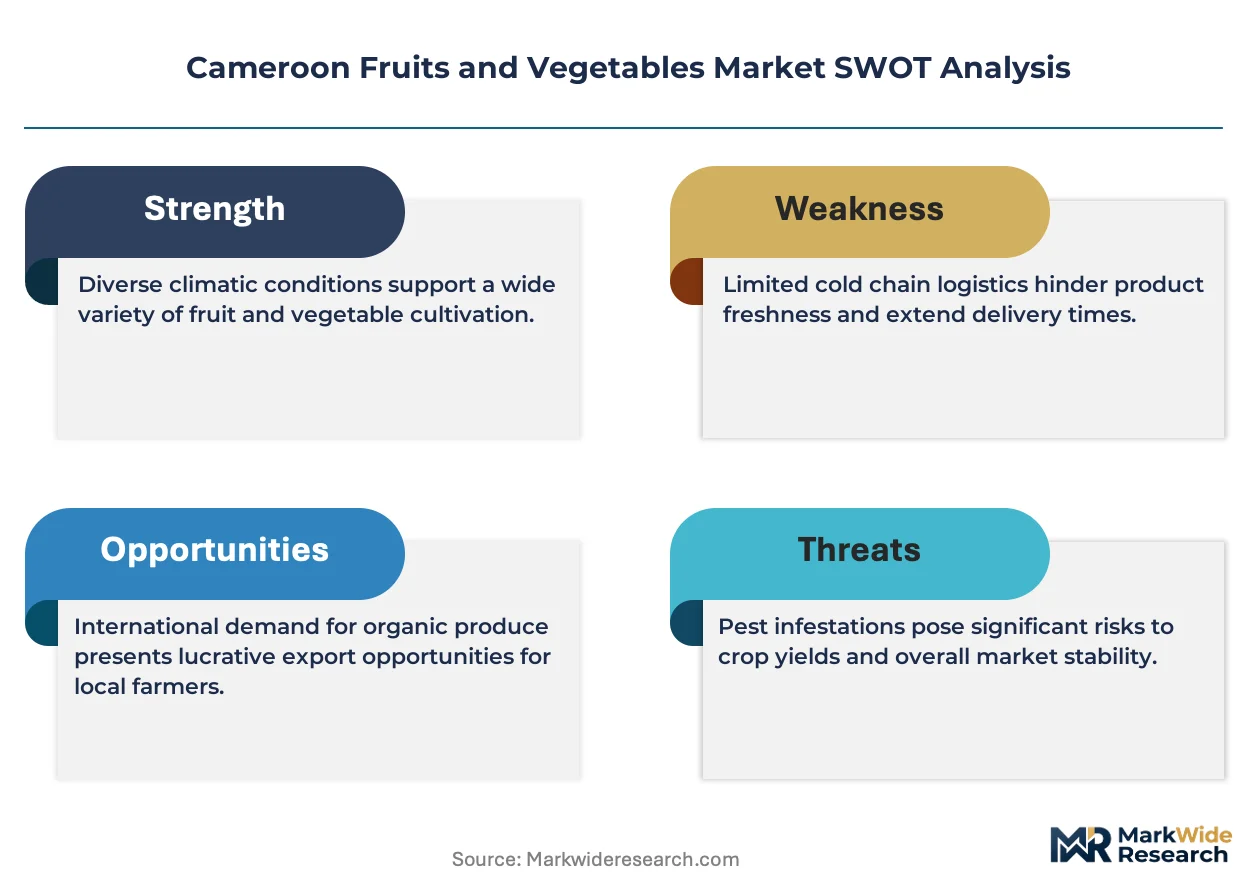
- Phytosanitary infrastructure gaps:Limited cold chain coverage between Northwest highlands and coastal ports restricts shelf-life extension for perishable vegetables.
- Regional trade fragmentation:Non-tariff barriers within Central African Economic and Monetary Community delay cross-border produce movements.
Strategic Opportunities
- High-altitude specialization:Northwest region vegetable cultivation commands premium pricing through extended growing seasons and distinct quality profiles.
- CODEX-aligned certification:Alignment with international food safety standards opens access to Middle Eastern and Asian import markets beyond traditional European focus.
- Integrated farming models:Field-to-port quality control systems are expanding into pineapple and banana value chains, capturing margin typically lost to intermediaries.
Industry Challenges
- Traceability system deployment:Smallholder aggregation networks struggle with digitized record-keeping required for retailer-specific compliance documentation.
- Refrigerated logistics capex:Temperature-controlled transport fleet expansion demands capital access that remains constrained by agricultural lending risk profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cameroon Fruits and Vegetables Market |
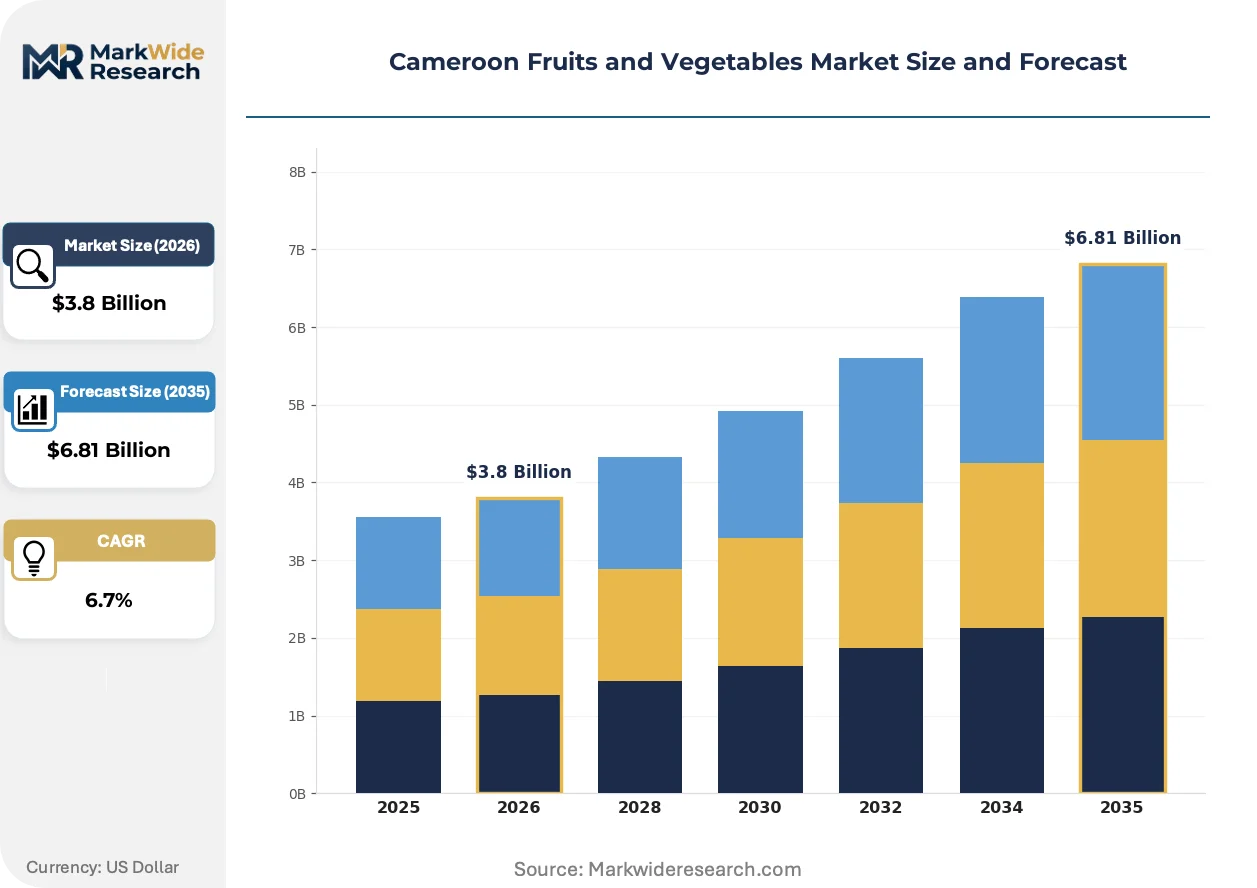
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Root Vegetables, Leafy Greens, Stone Fruits, Citrus Fruits Sales Channel: Direct Sales, Wholesalers, Retail Outlets, Online Marketplaces Usage Type: Fresh Consumption, Processed Products, Export, Local Markets Packaging Type: Baskets, Boxes, Plastic Wraps, Bulk Containers |
| Companies Covered | Carrefour Cameroun, CamElite Commodities, Cameroon Development Corporation, Aworld Exports, Ndawara Farms, Boh Plantations Limited, CAS Cameroon Ltd., Pamol Plantations, Agrofy Cameroon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cameroon Fruits and Vegetables Market Strategic Shifts
Digital traceability platforms and sustainable packaging materials are converging with evolving import-market regulations to reshape how Cameroonian produce reaches end consumers.
Blockchain-enabled provenance tracking is expanding into export-grade banana and pineapple consignments. European supermarket buyers are mandating real-time shipment monitoring for deforestation compliance. This visibility infrastructure is expanding into domestic supply chains, compressing information asymmetry between farmers and urban retailers.
Cameroon's national standards body is enforcing CODEX-aligned pesticide residue protocols for cross-border certification. The Ministry of Agriculture and Rural Development is aligning inspection capacity with EU sanitary requirements. Export-oriented processors in Douala and Yaoundé corridors are restructuring supplier relationships around documented compliance timelines.
Urban consumers are consolidating purchases through mobile-enabled marketplace platforms that bypass traditional wholesale intermediaries. Younger demographics in Yaoundé are driving demand for pre-packaged, traceable produce with origin labeling. This channel rotation is most visible in middle-income neighborhoods where payment digitization has achieved critical mass.
Cameroon Fruits and Vegetables Market Segmentation
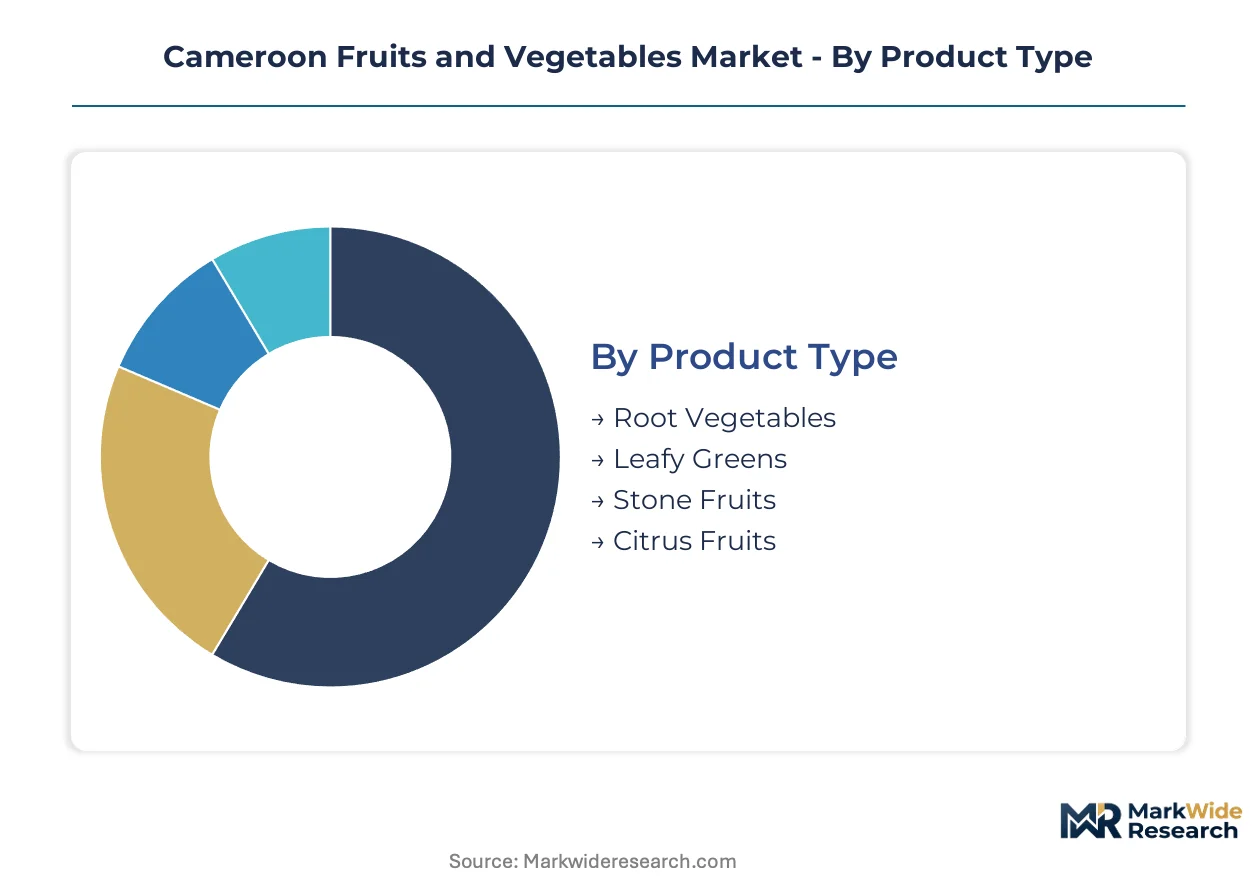
Cameroon's fruits and vegetables market fragments across four distinct dimensions that reshape procurement patterns from the Northwest highlands to Douala's export corridors. Each segmentation layer exposes different margin structures and compliance burdens for producers navigating domestic supermarket consolidation and European phytosanitary requirements.
Product Type:
Supply concentration varies sharply across agro-ecological zones, with coastal lowlands and western highlands specializing in distinct crop categories that determine cold chain investment and shelf-life extension strategies.
- Root Vegetables:Cassava, yams, and cocoyams dominate volume flows through year-round cultivation feasibility across southern forest zones. Demand concentrates around Douala processing corridors where established infrastructure supports starch extraction and flour milling operations serving regional food security programs.
- Citrus Fruits:Oranges, mandarins, and grapefruits from the Littoral and Southwest regions command premium export pricing through established phytosanitary certification pathways. European supermarket buyers mandate documented provenance compliance that favors consolidated plantation-scale suppliers over fragmented smallholder networks.
- Leafy Greens:Amaranth, eru, and bitter leaf cultivation clusters around peri-urban zones serving Yaoundé's wet markets with minimal cold chain requirements.
- Stone Fruits:Mango and avocado production from the Adamawa plateau supplies both domestic fresh consumption and limited cross-border trade into Gabon and Equatorial Guinea.
Root vegetables absorb the bulk of installed processing capacity; citrus fruits are expanding most quickly through export-grade certification investments.
Sales Channel:
Channel economics diverge between traceability-intensive supermarket procurement and traditional wholesale arbitrage, with digitization compressing intermediary margins in urban corridors.
- Online Marketplaces:Mobile-enabled platforms bypass traditional wholesale intermediaries through direct farmer-to-consumer connectivity. Yaoundé's middle-income neighborhoods drive adoption where payment digitization has achieved critical mass and origin labeling commands price premiums.
- Retail Outlets:Urban supermarket chains in Douala and Yaoundé consolidate procurement around certified produce with documented compliance timelines. These buyers enforce traceability systems that reshape upstream supplier relationships and sanitary protocol adoption.
- Wholesalers:Traditional aggregators dominate inter-regional movements between Northwest production zones and coastal consumption centers.
- Direct Sales:Farm-gate transactions persist in rural corridors with limited cold chain infrastructure and weak payment system penetration.
Retail outlets capture the steepest margin expansion through compliance premiums; online marketplaces are climbing the fastest on urban connectivity improvements.
Usage Type:
End-use segmentation determines certification intensity and capital requirements, with export orientation demanding disproportionate documentation infrastructure relative to revenue contribution.
- Export:EU-bound consignments require CODEX-aligned pesticide residue documentation and deforestation regulation compliance that favors integrated field-to-port operators. The national standards body accelerates infrastructure investment to maintain market access against tightening European sanitary protocols.
- Processed Products:Juice concentrates, dried fruits, and canned vegetables supply regional industrial buyers with less stringent traceability requirements than fresh export channels. Processing infrastructure concentrates in Douala and Yaoundé corridors with reliable power and port access.
- Fresh Consumption:Domestic households prioritize price accessibility over origin documentation in traditional wet market transactions.
- Local Markets:Regional trade within Central Africa faces non-tariff barriers that delay cross-border movements and compress supplier margins.
Fresh consumption dominates transaction volume; export usage is gaining share fastest on compliance-ready capacity expansion.
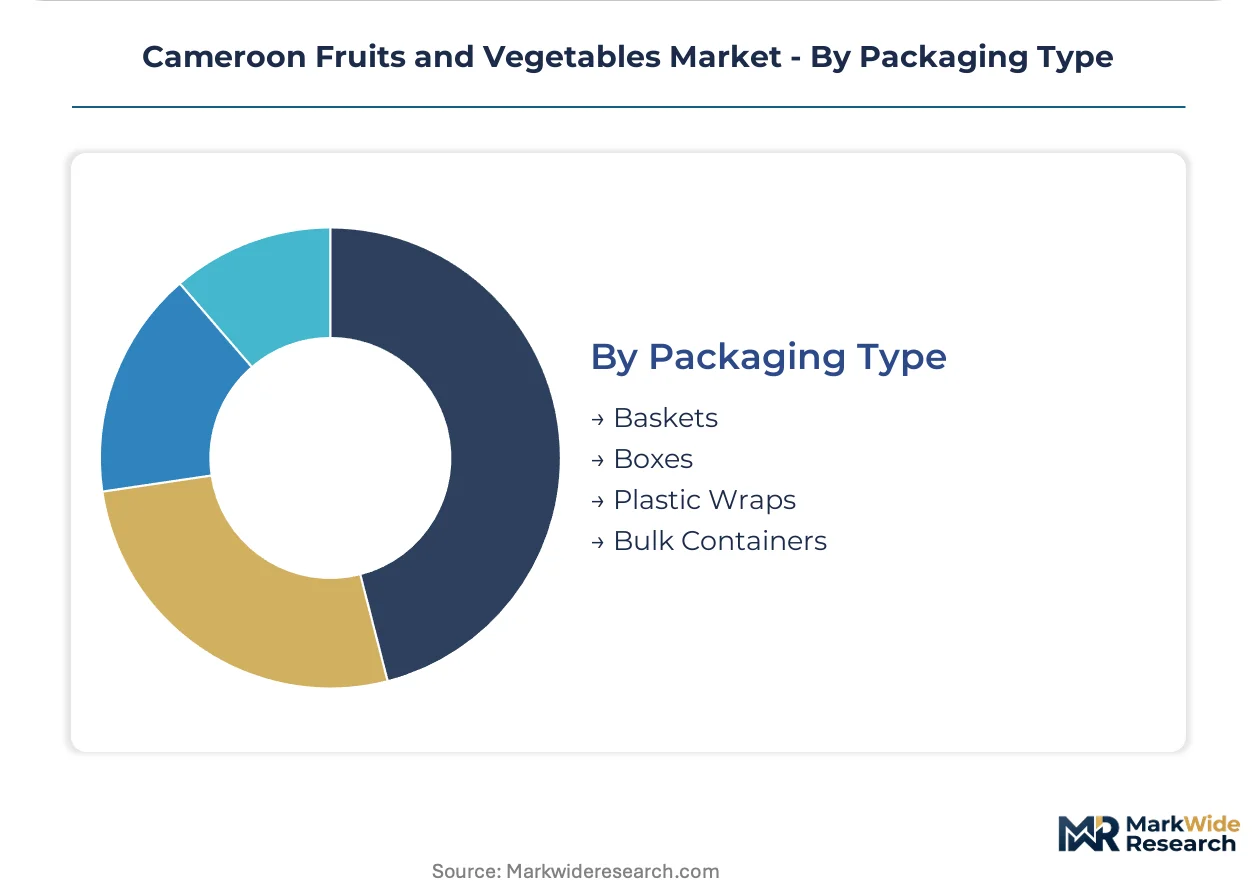
Packaging Type:
Packaging selection reflects a tension between unit cost minimization for bulk commodity flows and premium differentiation through sustainable materials compliance.
- Biodegradable Alternatives:Emerging paper-based and compostable materials cut unit logistics costs for exporters serving cross-border trade corridors while satisfying EU retailer sustainability mandates. Adoption concentrates among pineapple and banana specialists targeting European supermarket private label programs.
- Boxes:Corrugated fiberboard dominates export-grade consignments requiring stackability and moisture resistance through extended supply chains. Standardized dimensions align with refrigerated container specifications for maritime transport to European ports.
- Baskets:Woven materials persist in domestic wet markets with minimal branding requirements and short distribution cycles.
- Plastic Wraps:Conventional films retain cost advantage for local market distribution despite regulatory pressure.
- Bulk Containers:Returnable plastic crates serve closed-loop supermarket supply chains with reverse logistics infrastructure.
Boxes absorb the bulk of export-oriented packaging investment; biodegradable alternatives are expanding most quickly on EU regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates around Douala and Yaoundé processing corridors where urban supermarket chains drive certified produce procurement. Cameroon's national standards body enforces sanitary protocols for cross-border trade. Northwest highland vegetable cultivation and coastal lowland fruit production create distinct agro-ecological specialization zones.
Littoral Region
Douala's port infrastructure anchors export-grade banana and pineapple shipments to European buyers. The Ministry of Agriculture and Rural Development operates inspection facilities aligned with EU sanitary requirements. Processing clusters around the Wouri estuary concentrate juice concentrate and dried fruit operations serving regional industrial buyers.
Centre Region
Yaoundé's urban supermarket chains consolidate procurement around traceable produce with documented compliance timelines. The national phytosanitary regulator maintains certification capacity for CODEX-aligned pesticide residue protocols. Peri-urban cultivation zones supply leafy greens to wet markets with minimal cold chain requirements.
Northwest Region
High-altitude vegetable cultivation commands premium pricing through extended growing seasons and distinct quality profiles. The national standards body accelerates documentation infrastructure for supply chain provenance compliance. Ndawara Farms anchors production clusters around Bamenda serving domestic and cross-border markets.
Southwest Region
Citrus fruit plantations from the Littoral and Southwest regions supply export markets through established phytosanitary certification pathways. Boh Plantations Limited leverages integrated field-to-port quality control systems. Coastal lowland banana production feeds maritime container traffic through Douala port facilities.
Cameroon Fruits and Vegetables Market Competitive Environment
Integrated farming investments dominate the current landscape as operators capture margin typically lost to intermediaries. The vendor base spans plantation-scale integrated operators, specialized export traders, and emerging digital marketplace platforms. Three archetypes define competitive positioning: field-to-port quality controllers, certification-specialized exporters, and urban retail consolidators. Capacity expansion in refrigerated logistics and strategic partnerships with European supermarket buyers represent the dominant competitive moves reshaping supplier relationships.
Among plantation-scale integrated operators, Boh Plantations Limited exemplifies field-to-port quality control systems spanning banana value chains. CAS Cameroon Ltd. occupies a position within the certification-specialized exporter tier through pineapple specialization for European buyers. Ndawara Farms represents the high-altitude differentiation archetype via Northwest vegetable cultivation commanding premium pricing through extended growing seasons.
| Leading Market Players |
|---|
| Carrefour Cameroun |
| CamElite Commodities |
| Cameroon Development Corporation |
| Aworld Exports |
| Ndawara Farms |
| Boh Plantations Limited |
| CAS Cameroon Ltd. |
| Pamol Plantations |
| Agrofy Cameroon |
| Others |
Value Chain & Pricing Dynamics
Fertilizer import costs cascade through Cameroon's produce value chain, compressing margins for smallholder cassava and cocoyam cultivators in southern forest zones while plantation-scale banana operators in the Southwest absorb volatility through forward contracting with European buyers. This input-cost tension stratifies pricing power across the three-tier structure separating export-grade certified produce from domestic wet-market commodities.
Pricing Analysis
Volume flows concentrate in root vegetables where price competition is fiercest, while citrus and high-altitude vegetables from the Northwest capture superior margins through CODEX-aligned certification and extended growing-season scarcity. Three-tier pricing structure across premium, standard, and economy levels reflects EU sanitary compliance grades, with export-bound pineapple and banana consignments commanding certification premiums that domestic wet-market leafy greens cannot access. Cost compression in the standard tier is intensifying because fertilizer price volatility and fuel cost swings erode smallholder profitability. Wet-market traders in Yaoundé's peri-urban zones exhibit highest price sensitivity, while Douala-based export processors serving Carrefour Cameroun and European supermarket private-label programs demonstrate lowest sensitivity due to compliance-locked contract structures.
Supply Chain Analysis
Cameroon's national standards body enforcement of sanitary protocols for cross-border trade is accelerating domestic-content documentation requirements that reshape sourcing patterns toward traceable Northwest highland vegetable clusters and Littoral region citrus plantations. Geographic supply concentration centers on Cameroon itself for banana and pineapple exports, with secondary sourcing from Gabon and Equatorial Guinea for regional cross-border stone fruit trade. Raw material dependencies rest on imported agrochemicals, fuel for refrigerated transport, and corrugated fiberboard for export packaging. Single-source vulnerability runs through Douala port container traffic, where congestion or inspection delays cascade through temperature-sensitive perishable consignments. Distribution runs through three channels: field-to-port integrated operators like Boh Plantations Limited, wholesale aggregators serving domestic wet markets, and emerging digital platforms connecting Northwest farmers to Yaoundé consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Deforestation Regulation compliance deadlines are forcing consolidation across Cameroon's fragmented smallholder aggregation networks, eliminating operators unable to deploy digitized traceability systems while rewarding integrated field-to-port players with documented supply chain provenance.
For Market Incumbents: Anticipate margin compression from emerging digital marketplace platforms by securing exclusive supply agreements with Northwest highland vegetable clusters and accelerating biodegradable packaging adoption ahead of EU retailer sustainability mandates. Reinforce competitive moats through CODEX-aligned certification investments that lock in European supermarket buyer relationships before compliance deadlines reshape supplier qualification criteria. For New Entrants and Emerging Players: EU Deforestation Regulation in Europe opens a window for traceability-technology providers and cold-chain logistics specialists to capture share from traditional wholesale aggregators struggling with digitized record-keeping requirements. Target the online marketplace channel in Yaoundé's middle-income neighborhoods where payment digitization and origin-labeling premiums are achieving critical mass. Pursue a go-to-market angle anchored in direct farmer-to-consumer connectivity, bypassing intermediary layers that currently absorb margin in domestic supply chains. For Investors and Strategic Acquirers: Accelerated documentation infrastructure investment by Cameroon's national standards body is the leading indicator that compliance-ready export capacity will command acquisition premiums over the coming decade. Long-term viability favors integrated operators with captive high-altitude production in the Northwest and established European buyer relationships. Target acquisition archetypes include field-to-port banana and pineapple specialists with existing CODEX-aligned protocols and refrigerated logistics assets. Monitor cold-chain fleet expansion announcements as the signal to watch for inflection in perishable vegetable export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Fleet Expansion | Temperature-controlled transport capacity unlocks Northwest highland vegetable export competitiveness through Douala port. |
| Biodegradable Packaging Transition | EU retailer sustainability mandates favor Cameroonian exporters with compostable materials compliance and cost advantages. |
| Digital Traceability Platform Deployment | Blockchain-enabled provenance tracking satisfies European supermarket deforestation compliance and compresses information asymmetry. |
| High-Altitude Specialization Investment | Northwest region vegetable cultivation commands premium pricing through extended growing seasons and distinct quality profiles. |
| Supermarket Supply Chain Integration | Direct procurement relationships with Carrefour Cameroun and urban chains lock in volume commitments and compliance premiums. |
Study Parameters
Trade databases, phytosanitary certification records, and agricultural ministry production statistics formed the secondary backbone, cross-referenced with primary interviews spanning plantation operations managers, cold-chain logistics providers, European supermarket procurement officers, and Ministry of Agriculture and Rural Development officials. This study combined bottom-up farmer-level production estimates with top-down export value triangulation to construct segment-level market sizing across product type, sales channel, usage type, and packaging format dimensions.
Historical trendline analysis of certified export volumes and domestic consumption patterns established baseline growth trajectories, with projections calibrated against EU regulatory implementation timelines and urban connectivity improvement curves. The analytical framework modeled segmentation across root vegetables, citrus fruits, leafy greens, and stone fruits by product type; online marketplaces, retail outlets, wholesalers, and direct sales by channel; and export, processed products, fresh consumption, and local markets by usage orientation. CAGRs were derived from regression analysis of historical export certification growth rates and urban supermarket procurement consolidation trends, incorporating fertilizer price volatility and cold-chain infrastructure deployment as industry-specific forecast inputs.
The model assumes a particular technology adoption path for digital traceability platforms; alternative pathways for blockchain-enabled provenance tracking would alter the outlook for smallholder aggregation network competitiveness and compliance cost structures. Forecasts reflect assumptions around EU Deforestation Regulation enforcement intensity, regional trade barrier resolution within the Central African Economic and Monetary Community, and refrigerated logistics capital access conditions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Artichokes Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Qatar Greenhouse Market
Vegetables
Yams Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Garlic Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Spain Avocado Market
Vegetables
Dry Onion Market
Vegetables
Squash Market
Vegetables
Dried Vegetable Market