
 Chile Commercial Vehicle Market | 2026-2036
Chile Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Commercial Vehicle Market Insights
Aftermarket service revenue is reconfiguring margin capture across the Chile commercial vehicle ecosystem. Volvo Group leverages its dealer network density in Antofagasta and Santiago to control parts fulfillment and scheduled maintenance contracts. Scania AB anchors its position through captive financing and long-haul fleet management services. Mercedes-Benz differentiates via premium chassis platforms targeting mining and intermodal logistics operators.
Commercial vehicles encompass motorized transport equipment engineered for goods carriage or passenger movement exceeding light-duty thresholds, with gross vehicle weight ratings typically surpassing 3.5 tonnes and powertrains calibrated for continuous-duty cycles, torque demand, and payload efficiency across Andean topography and coastal highway corridors. Heavy trucks lead unit volume due to copper mining logistics and cross-border freight to Peru and Argentina, while electric powertrains represent the fastest-expanding fuel type segment as Chile's renewable electricity surplus enables grid-dependent fleet charging economics. Buses retain structural importance in Santiago's Transantiago public transport renewal and intercity corridors.
Chile's Ministry of Transport enforces Euro VI-equivalent emissions compliance through Supreme Decree 13, accelerating scrappage of pre-2018 diesel fleets and reshaping OEM product certification requirements. The National Electrical Coordinator and Ministry of Energy coordinate grid capacity allocation for depot charging infrastructure, directly influencing electric truck and bus deployment feasibility in metropolitan zones. Stakeholders must monitor regulatory timing for zero-emission zone declarations in Santiago and Antofagasta against charging infrastructure build-out schedules and power purchase agreement availability.
Market Dynamics
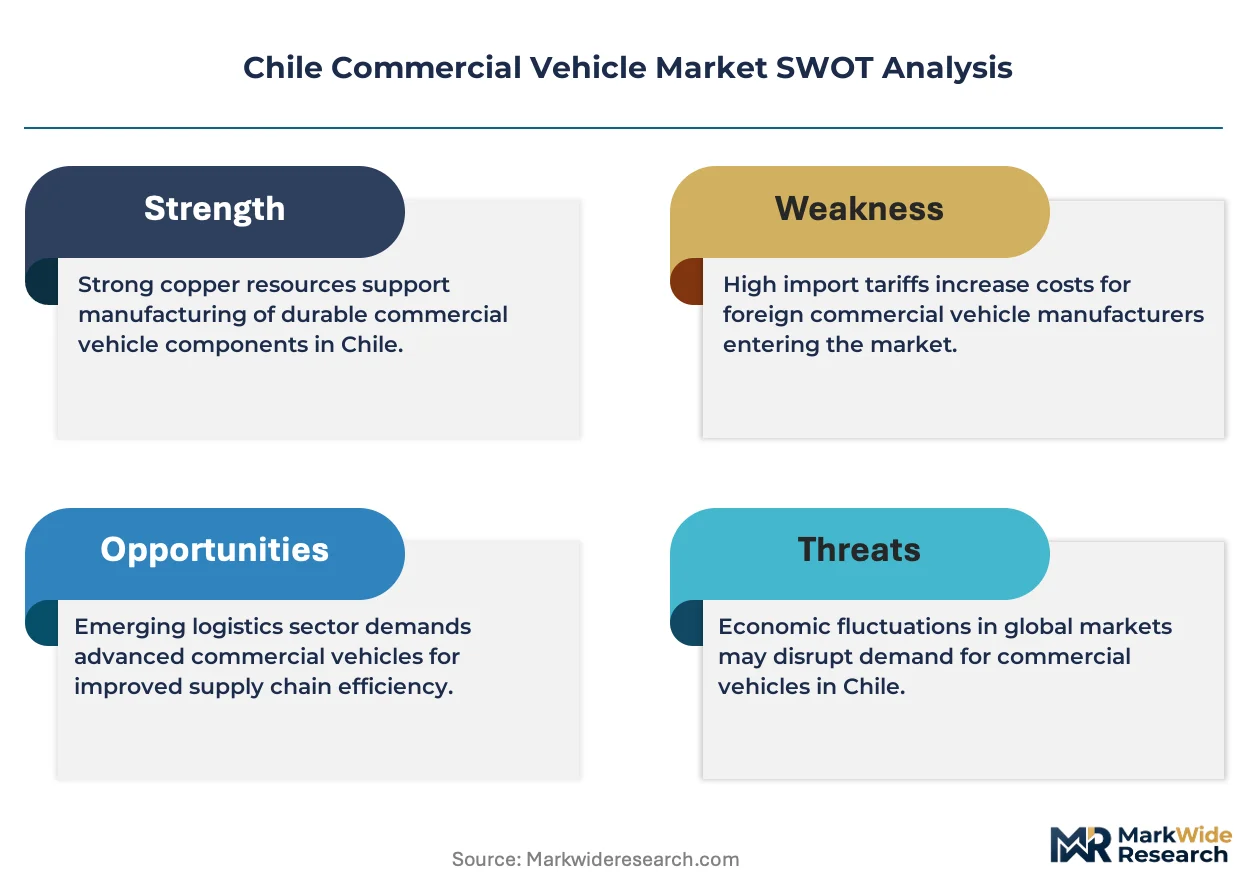
Supreme Decree 13's Euro VI-equivalent emissions mandate is forcing fleet turnover across Chile's heavy-duty segments, compressing diesel truck residual values while accelerating alternative powertrain certification timelines for mining and logistics operators.
Growth Catalysts
- Copper mining corridor expansion:Mineral transport demand in Atacama and Antofagasta regions is pulling heavy truck procurement from fleet operators serving state-owned and private extraction sites.
- Supreme Decree 13 compliance deadlines:Pre-2018 diesel fleet scrappage requirements are creating replacement demand for cleaner powertrains across Santiago's logistics hubs.
- Grid surplus charging economics:Chile's renewable electricity abundance from solar and wind installations is enabling depot charging feasibility for electric truck and bus operators in metropolitan zones.
Market Restraints
- Battery mineral input volatility:Lithium and cobalt price fluctuations are compressing electric powertrain total cost of ownership calculations for fleet procurement committees.
- Charging infrastructure concentration risk:Grid capacity allocation decisions by the National Electrical Coordinator are bottlenecking depot charging deployment in Valparaíso and Santiago distribution corridors.
- Andean topography technical limitation:High-altitude torque degradation and thermal management constraints are limiting electric truck payload ratings on mining access routes above 3,000 meters.
Strategic Opportunities
- Antofagasta zero-emission zone preparation:Pending municipal declarations for low-emission freight corridors are creating first-mover positioning for electric truck and hydrogen fuel cell fleet trials.
- Transantiago bus renewal waves:Santiago's public transport authority procurement cycles are opening dedicated channels for electric bus OEMs with local assembly partnerships.
- Cross-border freight electrification:Bi-national corridor agreements with Peru are enabling pilot programs for electric trucks on the Pan-American Highway freight axis.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance and battery management system diagnostics require specialized training that Chilean technical institutes have not yet scaled to fleet operator demand.
- Homologation timeline compression:Supreme Decree 13 certification requirements for alternative fuel vehicles are extending product approval cycles beyond traditional diesel platform timelines.
- Legacy fleet integration friction:Mixed-powertrain operations combining Euro VI diesel and electric units are complicating maintenance scheduling and parts inventory management for multi-brand fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Commercial Vehicle Market |
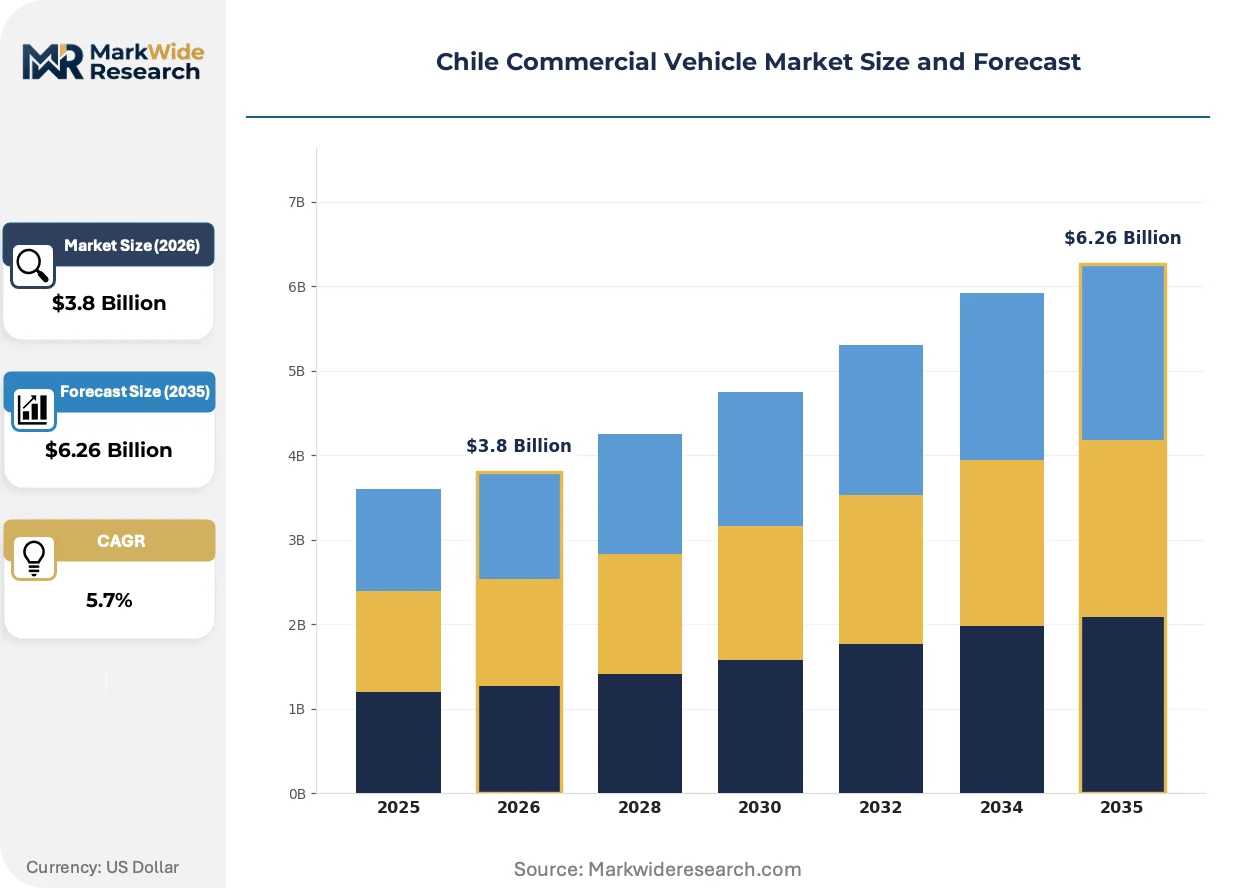
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Trucks, Heavy Trucks, Buses, Vans Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Logistics, Construction, Public Transport, Agriculture Body Type: Box, Flatbed, Refrigerated, Tipper |
| Companies Covered | Traton SE, Foton Motor, Mercedes-Benz, FUSO Trucks, Freightliner Trucks, Volvo Group, JAC Group, Hino Motors, Scania AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Commercial Vehicle Market Trends and Innovations
Digital fleet management platforms are virtualizing traditional maintenance and route optimization functions, compressing the value capture of aftermarket service providers while enabling real-time payload and energy consumption monitoring across Chile's mining and logistics corridors.
Telematics and predictive maintenance software is virtualizing scheduled service intervals into condition-based interventions. Mining fleet operators in the Atacama region are adopting these platforms fastest, drawn by uptime guarantees on mineral transport routes where downtime costs scale with copper price volatility. This virtualization is compressing traditional parts-and-labor revenue models toward subscription-based fleet management contracts.
Supreme Decree 13's enforcement protocol is mandating onboard diagnostics and remote emissions monitoring for all heavy-duty registrations. The Ministry of Transport's compliance verification system is requiring OEMs to integrate telematics hardware at factory specification. Santiago-based logistics operators are responding by consolidating procurement toward platforms with embedded compliance architecture.
Service contract unbundling is separating powertrain maintenance from chassis and bodywork coverage. Fleet operators in the Valparaíso port corridor are negotiating component-specific agreements with independent service providers rather than captive dealer networks. This shift is most visible among refrigerated transport operators where refrigeration unit uptime carries distinct penalty clauses from vehicle availability terms.
Chile Commercial Vehicle Market Segmentation
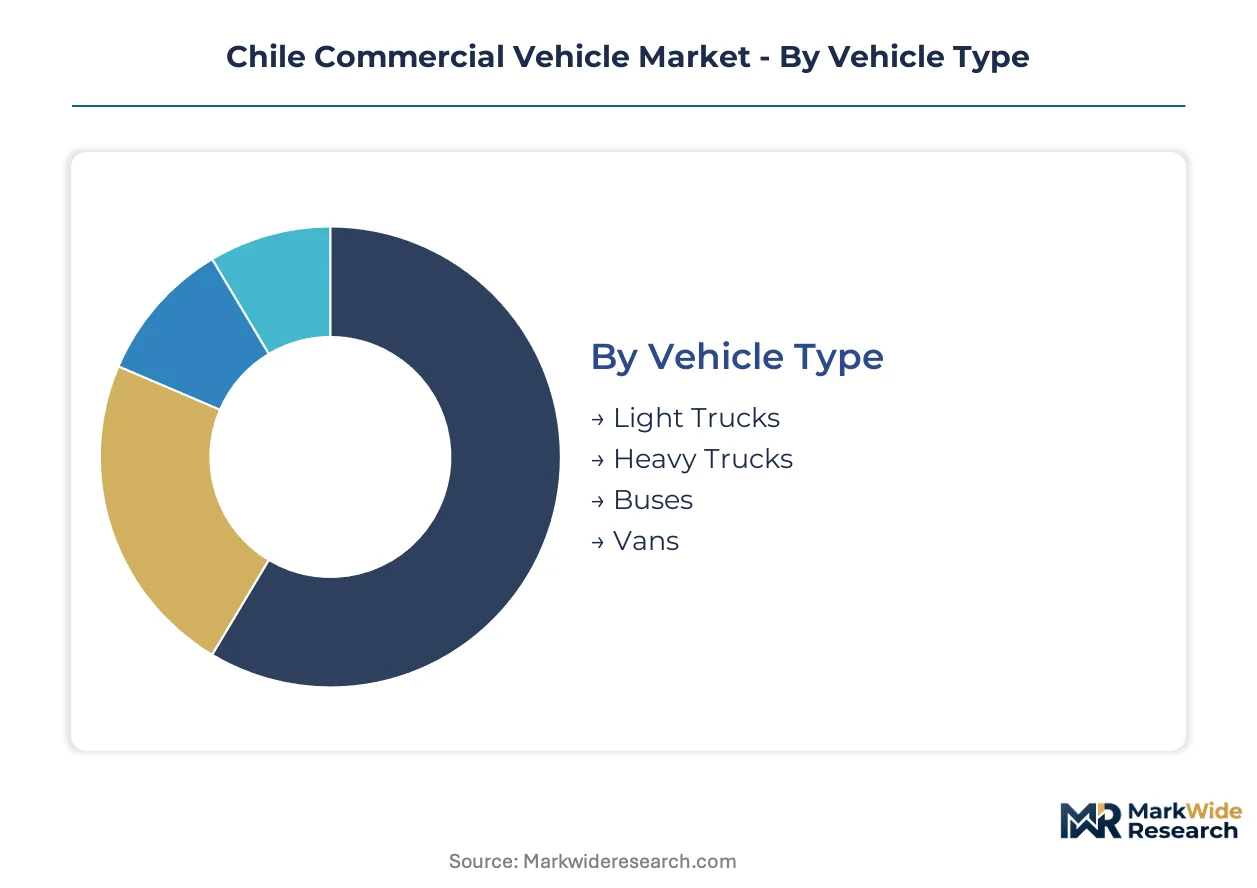
Chile's commercial vehicle segmentation reflects the country's dual economic engines: copper mining corridors demanding heavy-duty durability and metropolitan logistics requiring emissions compliance. Understanding these divisions reveals where procurement budgets concentrate and where regulatory pressure is reshaping fleet composition.
Vehicle Type:
Mature heavy-duty platforms dominate mining procurement while emerging electric configurations penetrate urban distribution.
- Heavy Trucks:Engineered for gross vehicle weight ratings exceeding 16 tonnes with reinforced chassis and high-torque powertrains calibrated for Andean ascents. Demand concentrates in the Atacama and Antofagasta mining corridors where mineral transport operators prioritize payload capacity and engine braking reliability on high-altitude routes.
- Buses:Configured for high-floor urban transit and intercity coach specifications with standing passenger capacity optimization. Santiago's Transantiago renewal cycles and provincial intercity concessions are driving procurement toward low-entry electric platforms with depot charging compatibility.
- Light Trucks:Ranging from 3.5 to 7.5 tonnes GVWR, serving last-mile distribution from Valparaíso port to Santiago's ring road logistics parks.
- Vans:Compact cargo configurations for urban parcel delivery and service technician transport in metropolitan zones.
Heavy Trucks handle the majority of throughput; Buses are gaining share fastest on electrification mandates.
Fuel Type:
Cost tier stratification separates established diesel infrastructure from emerging premium powertrain economics.
- Diesel:Compression-ignition engines meeting Euro VI-equivalent emissions through selective catalytic reduction and diesel particulate filtration. Mining fleet operators in northern regions continue procurement due to refueling infrastructure density and thermal efficiency at altitude, though Supreme Decree 13 compliance is compressing residual values for pre-2018 units.
- Electric:Battery-electric powertrains with lithium-ion packs sized for depot charging cycles and regenerative braking on descent corridors. Metropolitan logistics operators in Santiago and Valparaíso are piloting electric trucks where grid surplus pricing and municipal zero-emission zones align total cost of ownership calculations.
- Gasoline:Spark-ignition engines predominating in light truck and van segments for urban delivery duty cycles.
- Hybrid:Parallel and series-hybrid architectures bridging diesel efficiency with electric torque supplementation for variable terrain.
Diesel retains volume leadership across mining applications; Electric is climbing the fastest on grid economics and regulatory pressure.
End User:
Application-specific duty cycles determine chassis specification and service contract structuring across Chile's economic zones.
- Logistics:Fleet operators managing containerized freight from Valparaíso port through Santiago's distribution hub and cross-border corridors to Peru and Argentina. Procurement prioritizes telematics integration and fuel efficiency metrics for long-haul routes with penalty clauses for delivery window failures.
- Construction:Contractors requiring tipper configurations and all-wheel-drive capability for infrastructure projects in mountainous terrain and coastal development zones.
- Public Transport:Municipal and concessionaire operators serving Transantiago urban networks and provincial intercity routes with accessibility compliance and passenger throughput specifications.
- Agriculture:Vineyard and fruit export operations in Central Valley regions utilizing refrigerated and flatbed configurations for harvest logistics and cold chain connectivity.
Logistics commands the largest procurement volumes; Public Transport is seeing the steepest specification shifts on electrification timelines.
Body Type:
Margin structure varies with fabrication complexity and thermal management requirements across cargo categories.
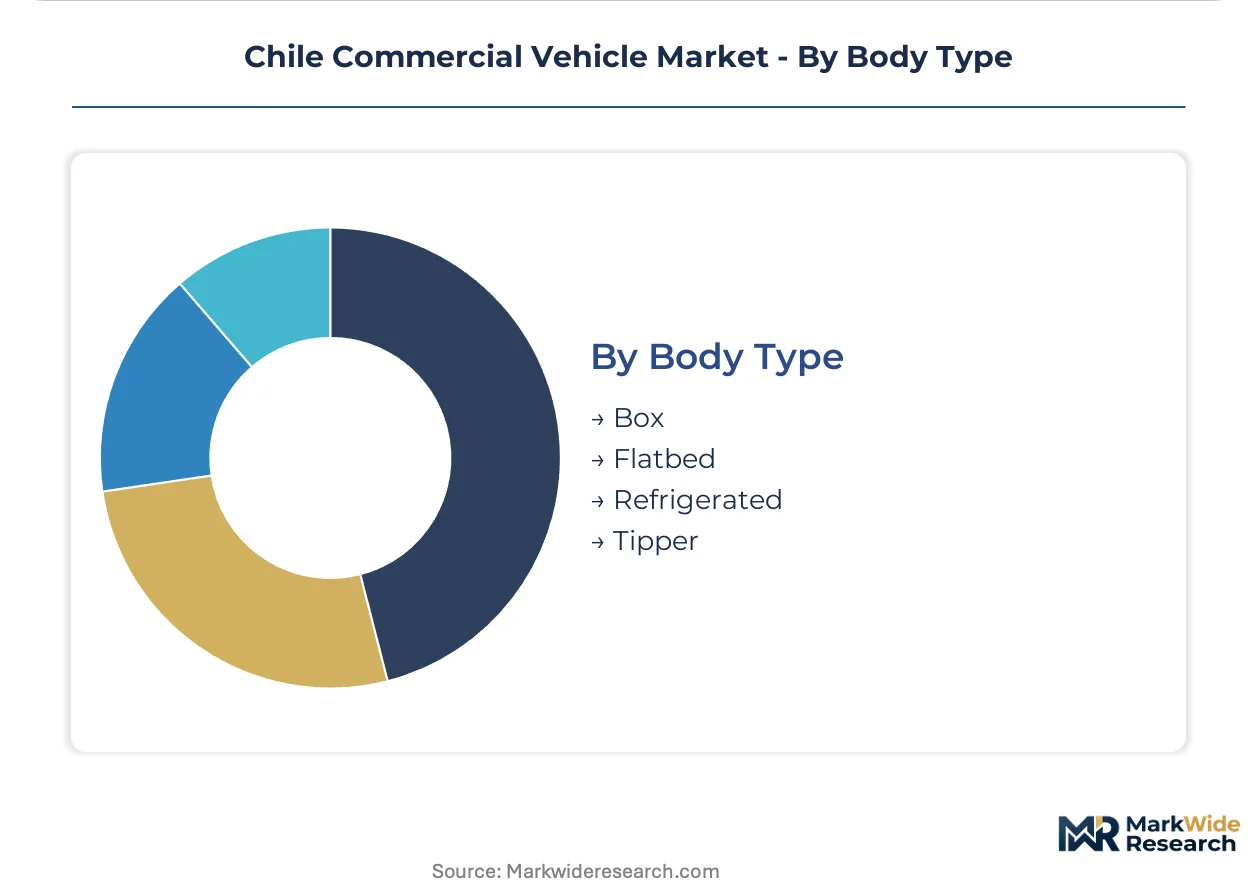
- Refrigerated:Insulated box bodies with integrated refrigeration units maintaining temperature corridors for agricultural exports and pharmaceutical distribution. Operators in Central Valley fruit corridors and Santiago cold chain logistics are specifying electric standby capabilities and multi-temperature zone configurations.
- Flatbed:Open deck configurations with stake sides or container twistlocks for construction materials and mining equipment transport. Northern mining suppliers favor reinforced decks with high payload ratings for irregular cargo profiles.
- Box:Enclosed dry freight bodies for parcel and palletized cargo protection in urban and intercity distribution.
- Tipper:Hydraulic lift mechanisms for aggregate and mineral transport in construction and mining support operations.
Box bodies handle standard freight volume; Refrigerated units are expanding most quickly on export agriculture and cold chain growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's commercial vehicle demand concentrates in mining corridors where payload efficiency outweighs emissions compliance, while metropolitan operators prioritize zero-emission compatibility over torque ratings. This consumption-mix differential separates northern mineral transport procurement from Santiago-Valparaíso logistics fleet planning.
Atacama Region
Copper extraction operators in the Calama mining cluster are expanding heavy truck fleets for mineral transport corridors connecting extraction sites to Antofagasta port facilities. Supreme Decree 13's Euro VI-equivalent emissions deadlines are compressing residual values for pre-2018 diesel units while extending homologation timelines for alternative powertrain certification. The Antofagasta-Calama highway corridor is seeing accelerated procurement of high-torque powertrains calibrated for high-altitude ascents above 3,000 meters.
Antofagasta Region
Port logistics operators and mining suppliers are coordinating fleet turnover to align with pending municipal zero-emission zone declarations for freight corridors. The National Electrical Coordinator's grid capacity allocation decisions are bottlenecking depot charging deployment in port-adjacent distribution parks. Antofagasta city and surrounding mining service clusters are emerging as pilot locations for hydrogen fuel cell truck trials serving short-haul mineral transport routes.
Metropolitan Santiago
Transantiago public transport authority procurement cycles are driving electric bus deployment through dedicated channels requiring local assembly partnerships. The Ministry of Transport's compliance verification system mandates onboard diagnostics and remote emissions monitoring for all heavy-duty registrations. Santiago's ring road logistics parks and Lastarria distribution hub are consolidating procurement toward platforms with embedded telematics architecture for real-time route optimization.
Valparaíso Region
Containerized freight operators managing port connectivity to Santiago are prioritizing telematics integration and fuel efficiency metrics with penalty clauses for delivery window failures. Grid surplus pricing from renewable electricity installations is enabling depot charging feasibility for electric truck pilots in metropolitan-adjacent distribution corridors. The Valparaíso port cold chain logistics cluster is specifying refrigerated units with electric standby capabilities for agricultural export cargo.
Central Valley
Vineyard and fruit export operations are utilizing refrigerated and flatbed configurations for harvest logistics connecting to Valparaíso cold chain infrastructure. Agricultural fleet operators are negotiating component-specific service agreements separating powertrain maintenance from refrigeration unit coverage. The Rancagua-Talca corridor is seeing procurement of light trucks for last-mile distribution from centralized packing facilities to port rail terminals.
Chile Commercial Vehicle Market Competitive Landscape
Capability concentration sits with European OEMs holding emissions certification expertise and mining sector relationships; scale advantage sits with Asian manufacturers leveraging cost-optimized platforms for light-duty and entry segments. The market structures around three tiers: premium European brands with integrated service networks, mid-tier Asian producers with volume positioning, and specialized mining equipment fabricators with altitude-rated specifications. Dominant competitive moves include captive financing bundling and telematics platform integration to secure fleet management contracts.
Among European-based OEMs, Volvo Group and Scania AB exemplify the premium-tier archetype through dense dealer networks controlling parts fulfillment and scheduled maintenance contracts. Mercedes-Benz occupies a position emphasizing chassis platform differentiation for mining and intermodal logistics applications. Traton SE represents the consolidated multi-brand approach spanning volume and premium positioning through subsidiary marques. These manufacturers anchor the emissions-compliant heavy-duty segment where Supreme Decree 13 certification requirements favor established regulatory navigation capabilities.
| Leading Market Players |
|---|
| Traton SE |
| Foton Motor |
| Mercedes-Benz |
| FUSO Trucks |
| Freightliner Trucks |
| Volvo Group |
| JAC Group |
| Hino Motors |
| Scania AB |
| Others |
Pricing and Supply Chain Analysis
The Antofagasta-Calama mineral transport corridor concentrates procurement volume for heavy-duty powertrains, where long-term fleet contracts anchor pricing stability while spot-market parts availability creates tiered service cost differentiation across mining and logistics buyer segments.
Pricing Analysis
Long-term offtake agreements dominate procurement for mining fleet operators, with contract structures spanning powertrain lifecycle coverage and scheduled maintenance bundling. Price differentiation separates Euro VI-certified platforms from pre-compliant legacy units, with volume scale and after-sales service integration as secondary tiering factors. Pricing pressure stems from battery mineral input volatility compressing electric powertrain total cost calculations. Logistics operators in Santiago's distribution hub exhibit highest price sensitivity due to thin margin structures, while mining incumbents prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Upstream steel and aluminum feedstock sourcing draws from Brazil, China, and domestic Chilean smelters, with lithium carbonate supply anchored in Atacama salar extraction operations. Critical component dependencies include high-voltage battery packs, selective catalytic reduction systems, and telematics hardware modules. Single-source vulnerability concentrates in semiconductor chips for engine control units and battery management systems. Distribution runs through Antofagasta and Santiago dealer networks controlling parts fulfillment and captive service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's commercial vehicle market sits in early-cycle expansion on Supreme Decree 13 compliance deadlines forcing fleet turnover and grid surplus economics enabling electric powertrain pilot feasibility.
For Market Incumbents: Pre-empt emerging Asian OEM encroachment in light-duty segments by tightening captive financing terms and expanding depot charging infrastructure partnerships in Valparaíso distribution corridors. Deepen vertical integration into high-voltage technician training through technical institute partnerships to address service capacity constraints. Secure long-term lithium supply agreements to stabilize electric powertrain cost positioning against battery mineral volatility. For New Entrants and Emerging Players: Electric bus procurement channels in Santiago's Transantiago renewal cycles represent the most penetrable entry point, given local assembly partnership requirements creating structural openings for new OEMs. Antofagasta zero-emission zone pilot programs offer second-mover positioning for hydrogen fuel cell truck trials serving short-haul mining routes. Go-to-market execution should prioritize Ministry of Transport homologation navigation capabilities to compress certification timelines. For Investors and Strategic Acquirers: Regional aftermarket service networks with high-voltage diagnostic capabilities present priority acquisition targets, given technician scarcity and service contract unbundling trends. Long-term viability frames around 5-10 year electrification penetration curves tied to grid capacity allocation decisions by the National Electrical Coordinator. Monitor zero-emission zone declaration timing in Santiago and Antofagasta as inflection indicators for electric truck deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Grid capacity allocation agreements with the National Electrical Coordinator unlock depot feasibility in metropolitan zones. |
| Local Assembly Partnership | Transantiago procurement requirements mandate domestic fabrication, creating structural entry barriers for pure importers. |
| High-Voltage Technician Training Program | Technical institute scaling addresses fleet operator service capacity constraints for electric powertrain maintenance. |
| Battery Supply Agreement | Long-term lithium carbonate offtake from Atacama salar operations stabilizes electric truck total cost positioning. |
| Telematics Platform Integration | Supreme Decree 13 compliance verification mandates onboard diagnostics, embedding hardware at factory specification. |
Research Methodology
Cross-validation between fleet operator procurement committees and OEM platform engineering directors anchors the qualitative findings, with secondary validation drawing from Ministry of Transport registration databases, National Electrical Coordinator grid planning documents, and mining sector capital expenditure disclosures. Primary interviews encompassed logistics fleet managers in Santiago and Valparaíso, mining procurement leads in Antofagasta and Atacama, aftermarket service directors, and high-voltage technician training institute administrators. Bottom-up unit shipment modeling triangulates against top-down GDP elasticity and copper price correlation frameworks.
Calibration against historical fleet turnover patterns and Supreme Decree 13 phase-in schedules shapes the projection methodology across vehicle class, fuel type, end-use application, and regional demand cluster dimensions. CAGRs derive from segment-specific adoption curve modeling incorporating regulatory compliance deadlines, grid infrastructure build-out timelines, and battery cost trajectory assumptions. Industry-specific inputs include copper mining production forecasts, Transantiago procurement cycle phasing, and cross-border freight corridor electrification pilot timelines.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, peso-dollar exchange rates, or renewable electricity pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and charging infrastructure deployment pace. Cross-checking against National Electrical Coordinator transmission expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Service Truck Market