
 Electric Truck Chassis Market | 2026-2036
Electric Truck Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Truck Chassis Market Foresight
Software-defined chassis management is decoupling hardware sales from recurring revenue streams across the electric truck chassis sector. Volvo Trucks leverages its embedded telematics platform to sustain long-term service contracts with fleet operators. PACCAR Inc. anchors its competitive stance through proprietary battery management integration. Tesla, Inc. differentiates via over-the-air performance updates that extend vehicle capability without physical retrofit.
An electric truck chassis comprises the structural frame, powertrain mounting architecture, energy storage housing, and thermal management subsystems engineered to support gross vehicle weights from 3.5 to 44 tonnes with battery capacities ranging from 100 kWh to over 1,000 kWh. Its primary purpose is to provide a standardized platform for cab, body, and equipment integration while optimizing weight distribution and crashworthiness for zero-emission commercial duty cycles. Battery electric technology dominates current production volumes, though hydrogen fuel cell configurations are gaining traction in heavy-duty chassis above 200 kW where energy density and refueling speed dictate operational viability. Light-duty chassis serves delivery services with the shortest payback periods, while heavy-duty variants command concentrated R&D investment from manufacturers targeting long-haul displacement.
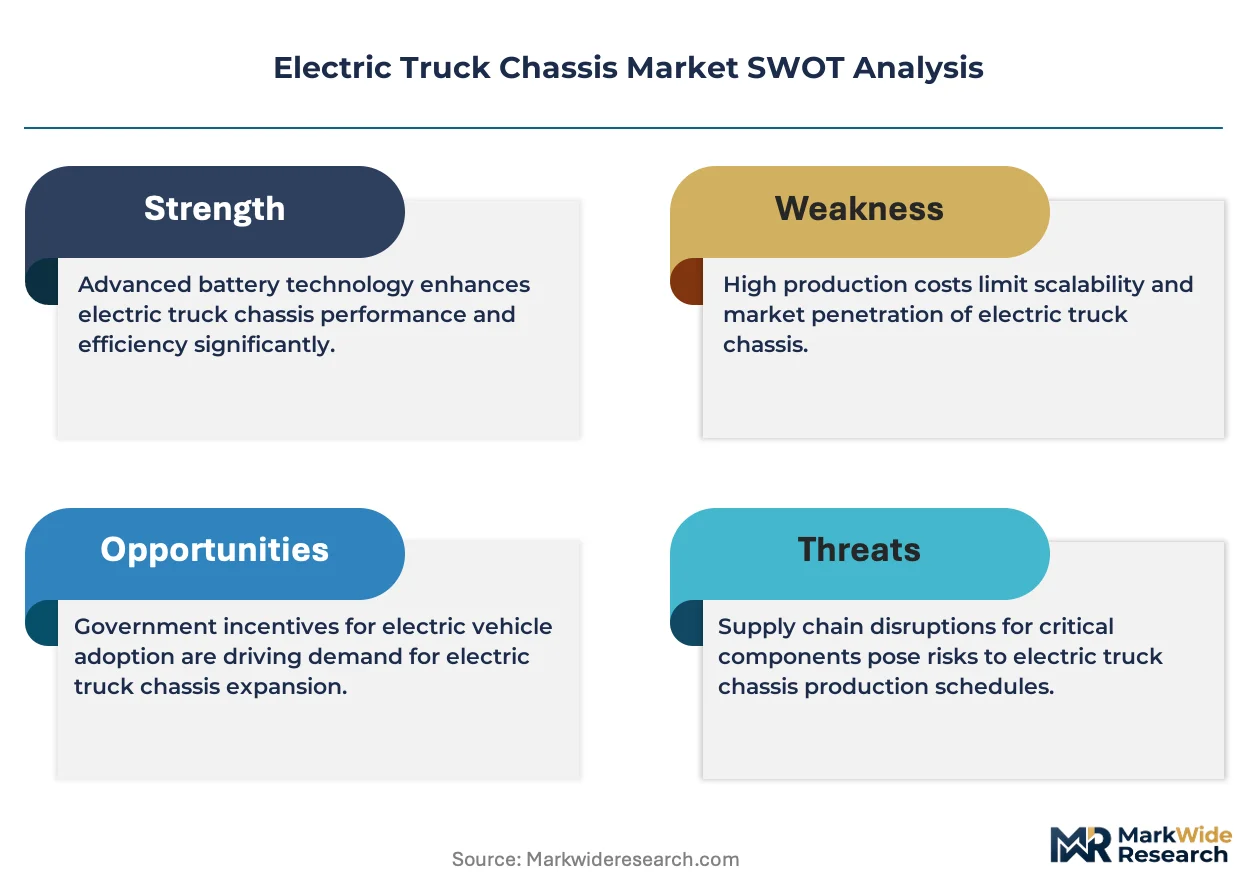
The EPA regulates commercial vehicle emissions through Phase 3 greenhouse gas standards, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in thermal management systems. China's MIIT enforces GB standards for new energy commercial vehicles that dictate battery safety testing and electromagnetic compatibility. India's PLI scheme for automotive manufacturing accelerates domestic chassis assembly capacity. Stakeholders must monitor how evolving battery passport requirements and carbon border adjustments reshape supply chain qualification criteria and export market access conditions.
Market Dynamics
Software-defined chassis management is decoupling hardware sales from recurring revenue streams across the electric truck chassis sector. Battery density improvements and hydrogen fuel cell integration are reshaping powertrain architecture as commercial operators respond to zero-emission mandates and total cost of ownership advantages.
Growth Catalysts
- Zero-emission mandates:The EPA Phase 3 greenhouse gas standards and EU Green Deal are accelerating fleet electrification timelines across last-mile and regional haul routes.
- Battery density improvements:Energy storage housing now accommodates 100 kWh to over 1,000 kWh configurations, extending operational range for heavy-duty duty cycles.
- Total cost of ownership advantages:Light-duty chassis variants serving delivery services demonstrate the shortest payback periods, concentrating operator investment in electrified fleets.
Market Restraints
- Lithium supply concentration:Raw material processing concentrates in China, creating vulnerability for battery management system manufacturers dependent on stable cathode supply.
- Heavy-duty energy density limits:Battery electric configurations above 200 kW face payload penalties that hydrogen fuel cell alternatives have not yet cost-effectively resolved.
- F-Gas Regulation compliance costs:The EU F-Gas Regulation constrains refrigerant choices in thermal management subsystems, elevating engineering complexity for European-market chassis.
Strategic Opportunities
- India's PLI scheme:The Production Linked Incentive scheme for automotive manufacturing accelerates domestic chassis assembly capacity, opening localized supply chain positioning.
- Hydrogen fuel cell convergence:Integration with battery electric architectures creates dual-powertrain platforms for heavy-duty segments above 44-tonne gross vehicle weights.
- Battery passport requirements:Emerging supply chain qualification criteria in the EU create first-mover advantages for chassis manufacturers with traceable cell provenance.
Industry Challenges
- Electromagnetic compatibility certification:China's GB standards for new energy commercial vehicles impose rigorous testing timelines that delay market entry for non-domestic suppliers.
- Thermal management engineering scarcity:Specialized talent for optimizing energy storage housing across temperature extremes remains concentrated among incumbent commercial vehicle manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Truck Chassis Market |
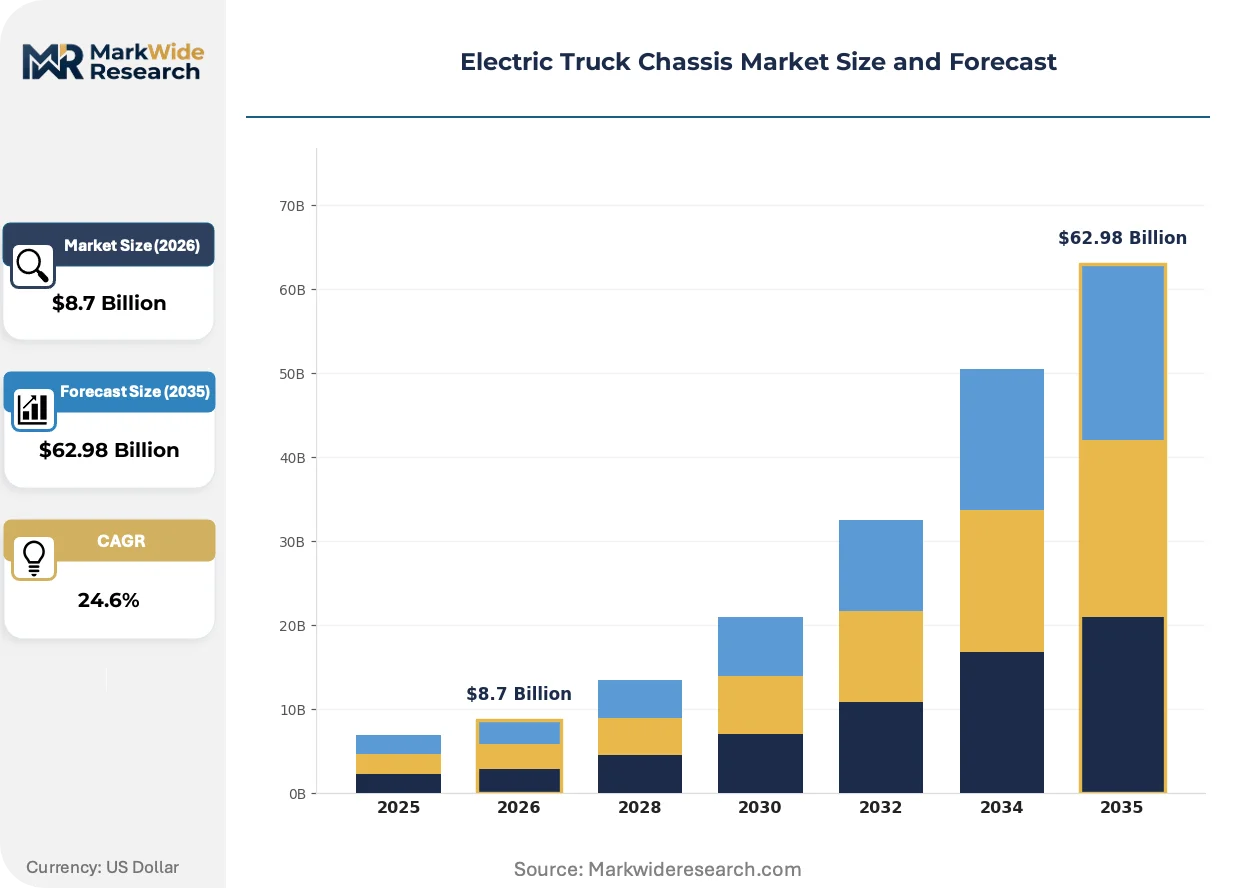
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Duty Chassis, Medium-Duty Chassis, Heavy-Duty Chassis, Specialized Chassis End User: Logistics Providers, Municipalities, Construction Companies, Delivery Services Power Rating: Up to 100 kW, 100 kW to 150 kW, 150 kW to 200 kW, Above 200 kW Technology: Battery Electric, Hydrogen Fuel Cell, Hybrid Electric, Others |
| Companies Covered | Ford Motor Company, Hyundai Motor Company, Volvo Trucks, Mercedes-Benz Group AG, PACCAR Inc., Navistar International Corporation, Scania AB, Tata Motors, Tesla, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Truck Chassis Market Shifts & Advancements
Embedded telematics platforms are transforming chassis from mechanical commodities into data-generating assets. Over-the-air capability extension and predictive maintenance integration are redefining manufacturer-fleet operator relationships across commercial vehicle procurement.
Cell-to-pack battery architecture is eliminating module-level housing, reducing weight and assembly complexity for energy storage systems. Regional haul operators in Germany and the United States are adopting these configurations for 300-500 kWh applications. This structural simplification is decentralizing thermal management responsibility from tier-one suppliers to chassis integrators.
The EU Green Deal's carbon border adjustment mechanism is reshaping export qualification requirements for chassis manufacturers. Steel and aluminum sourcing documentation now determines market access eligibility for European fleet tenders. Heavy-duty variants targeting long-haul displacement face the steepest compliance burden, accelerating in-house smelter partnerships among integrated manufacturers.
Fleet operators are unbundling after-sales service from initial chassis procurement, favoring performance-based contracts over traditional warranty structures. Third-party maintenance providers in China and the United States are capturing brake, suspension, and thermal system servicing previously retained by OEM dealer networks. This disintermediation concentrates in logistics providers operating standardized 3.5 to 12-tonne delivery fleets with predictable duty cycles.
Electric Truck Chassis Market Segmentation
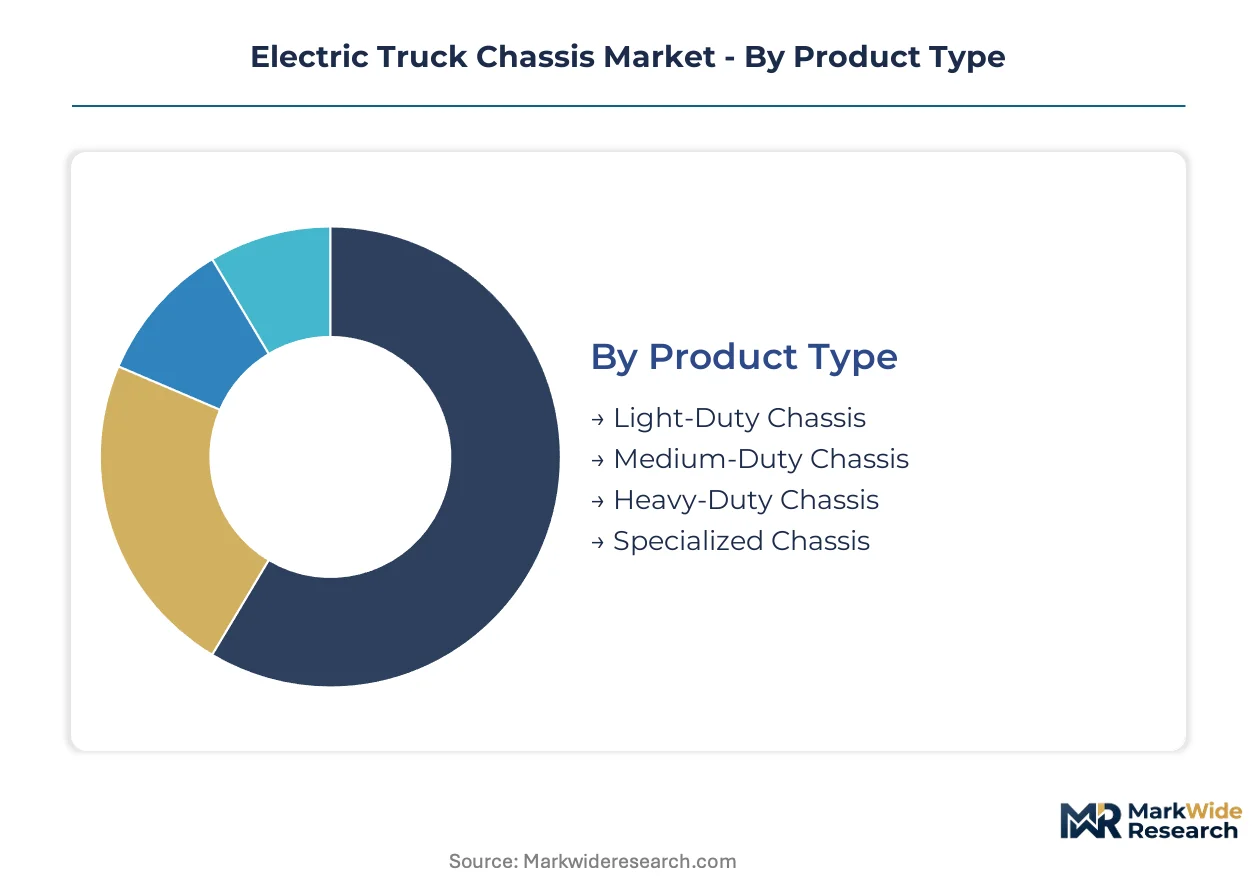
Chassis specification varies dramatically across duty cycles and energy architectures. Fleet operators select platforms based on route distance, payload requirements, and refueling infrastructure availability. Each segmentation dimension carries distinct margin profiles and technology roadmaps.
Product Type:
The customization-standardization spectrum stretches from mass-produced light-duty units to bespoke heavy-duty configurations engineered for specific gross vehicle weight ratings.
- Light-Duty Chassis:Structural frames optimized for 3.5 to 7.5 tonnes gross vehicle weight with modular battery mounting accommodating 100 to 300 kWh configurations. Last-mile delivery services in Germany and the United States concentrate procurement here due to route predictability and depot charging feasibility. Cell-to-pack architecture is eliminating module housing to maximize payload capacity within weight-constrained applications.
- Heavy-Duty Chassis:Reinforced ladder-frame construction supporting 26 to 44 tonnes with energy storage housing exceeding 600 kWh or hydrogen fuel cell integration above 200 kW. Long-haul operators face payload penalties from battery mass that fuel cell alternatives have not yet cost-effectively resolved, concentrating R&D investment among manufacturers targeting this displacement opportunity.
- Medium-Duty Chassis:Bridges urban distribution and regional haul with 7.5 to 26 tonne ratings, serving municipal refuse collection and intercity freight consolidation.
- Specialized Chassis:Custom frame geometries for concrete mixers, fire apparatus, and mobile cranes requiring non-standard power take-off configurations and reinforced mounting points.
Leading the category by volume: Light-Duty Chassis. Growing fastest: Heavy-Duty Chassis.
End User:
Cost tier stratification separates asset-light logistics platforms from capital-intensive municipal procurement with divergent total cost of ownership calculations.
- Logistics Providers:Fleet operators running standardized duty cycles across regional distribution networks prioritize chassis with embedded telematics platforms enabling predictive maintenance and route optimization. Contract terms unbundle after-sales service from initial procurement, favoring performance-based agreements over traditional warranty structures.
- Delivery Services:E-commerce fulfillment networks demand 3.5 to 12-tonne configurations with rapid turnaround between shifts and minimal depot infrastructure requirements. China and the United States host the densest deployment of third-party maintenance providers capturing brake, suspension, and thermal system servicing previously retained by OEM dealer networks.
- Municipalities:Public sector procurement cycles extend 7 to 10 years with specifications mandating domestic content percentages and extended service intervals for refuse collection and utility maintenance applications.
- Construction Companies:Off-road duty cycles and uneven terrain exposure require reinforced suspension mounting points and sealed electrical enclosures beyond standard highway specifications.
Highest volume concentration: Logistics Providers. Steepest expansion trajectory: Delivery Services.
Power Rating:
Application requirements dictate motor sizing with direct implications for thermal management complexity and energy storage housing geometry.
- Above 200 kW:Traction motors exceeding 268 horsepower serving heavy-duty regional haul and long-haul displacement where hydrogen fuel cell configurations compete on energy density and refueling speed metrics. China's MIIT enforces GB standards for electromagnetic compatibility testing that delay market entry for non-domestic suppliers in this power class.
- 100 kW to 150 kW:Dominates medium-duty urban distribution with sufficient continuous output for stop-and-go traffic without the thermal management burden of higher power densities.
- Up to 100 kW:Light-duty last-mile configurations with minimal cooling requirements and simplified battery thermal regulation.
- 150 kW to 200 kW:Bridges medium and heavy classifications for construction equipment and municipal applications requiring intermittent high-torque output.
Volume leadership: 100 kW to 150 kW. Fastest climb: Above 200 kW.
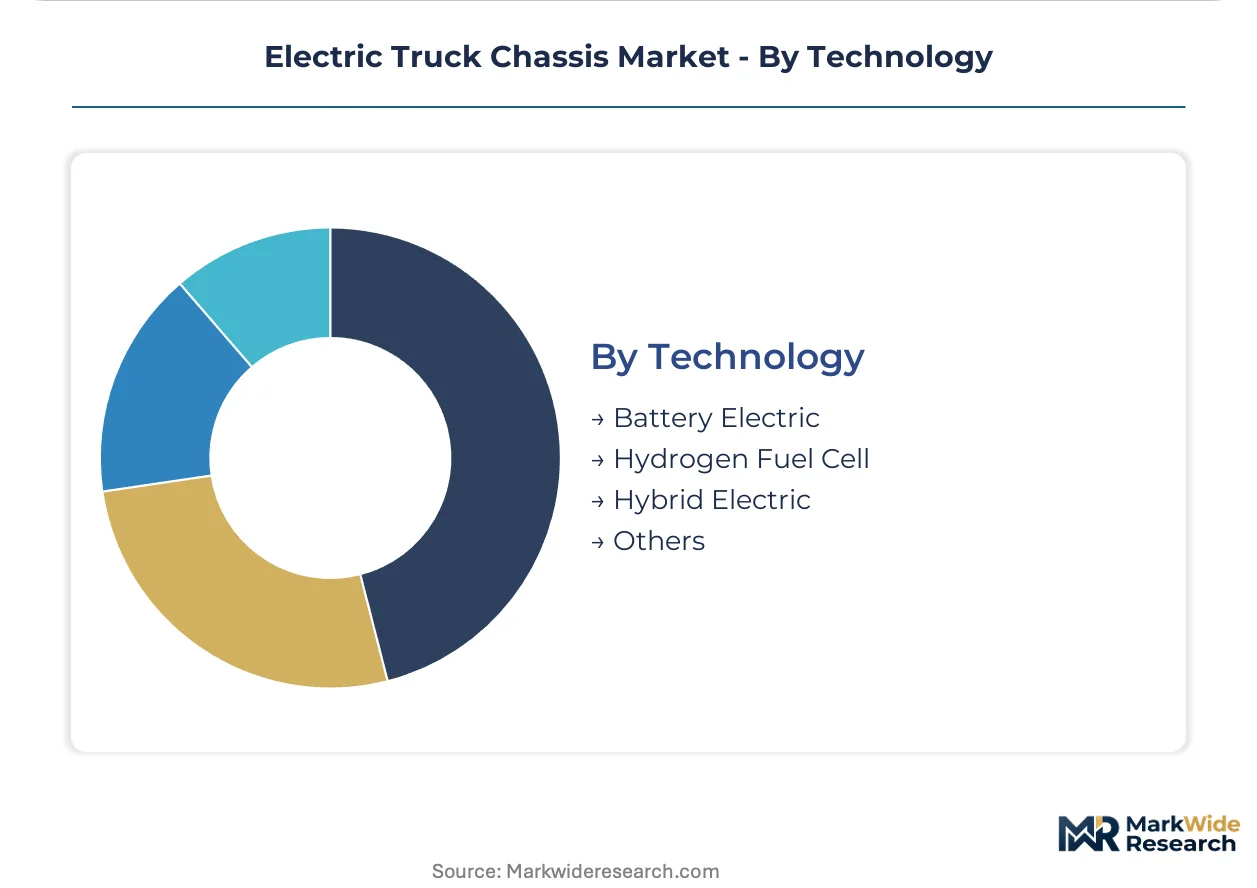
Technology:
Maturity curves separate commercially proven battery electric architectures from emerging fuel cell platforms with infrastructure-dependent deployment constraints.
- Battery Electric:Lithium-ion cell-to-pack configurations eliminating module-level housing now dominate production volumes from 100 kWh to over 1,000 kWh. The EU F-Gas Regulation constrains refrigerant choices in thermal management subsystems, elevating engineering complexity for European-market chassis integrators managing energy storage housing across temperature extremes.
- Hydrogen Fuel Cell:Proton exchange membrane stacks paired with modest battery buffers for heavy-duty segments above 44-tonne gross vehicle weights where energy density and refueling speed dictate operational viability. Dual-powertrain platforms combining fuel cell range extension with battery electric urban operation are emerging from integrated manufacturers.
- Hybrid Electric:Range-extender architectures with downsized combustion engines serving markets with sparse charging infrastructure and extended rural route requirements.
- Others:Experimental solid-state battery prototypes and alternative chemistries including sodium-ion for cost-sensitive applications with reduced energy density requirements.
Current volume dominance: Battery Electric. Gaining share fastest: Hydrogen Fuel Cell.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of battery cells and chassis components, while the United States and Germany absorb the highest volumes of finished electric truck platforms. This production-consumption divide shapes trade flows, regulatory reciprocity, and localized assembly investments across major commercial vehicle markets.
China
Domestic logistics providers operating under Beijing's dual carbon goals are electrifying last-mile fleets at scale. MIIT enforces GB standards for electromagnetic compatibility and battery safety testing that non-domestic suppliers must satisfy before market entry. The Yangtze River Delta hosts concentrated chassis assembly capacity serving both domestic demand and export markets to Southeast Asia.
United States
Regional haul operators across California and the Northeast corridor are responding to EPA Phase 3 greenhouse gas standards with accelerated fleet replacement timelines. The Inflation Reduction Act's commercial clean vehicle credits are restructuring procurement economics for 3.5 to 12-tonne delivery configurations. Detroit-Warren automotive clusters are retooling legacy truck plants for electric platform production.
Germany
Long-haul freight operators along the Rhine-Alpine corridor face EU Green Deal mandates that compress diesel phase-out schedules. The EU F-Gas Regulation constrains thermal management refrigerant choices, elevating engineering complexity for chassis integrators targeting European certification. Baden-Württemberg's industrial belt concentrates R&D investment in heavy-duty fuel cell hybrid architectures.
India
Municipal refuse collection and urban distribution fleets in Maharashtra and Gujarat are expanding under the PLI scheme for automotive manufacturing. The central bank's green financing guidelines are channeling credit toward domestic chassis assembly capacity. Tamil Nadu's automotive corridor is attracting component suppliers seeking tariff-advantaged positioning for export to Middle Eastern markets.
South Korea
Battery manufacturers in the Seoul Capital Area are securing long-term cathode supply contracts with Indonesian nickel processors. METI-aligned standards for commercial vehicle electrification are harmonizing with Japanese technical regulations to facilitate cross-border fleet procurement. Busan-Ulsan port logistics operators are piloting hydrogen fuel cell chassis for container drayage applications.
Electric Truck Chassis Market Competitive Landscape
Top-tier vendors anchor premium platform development, while mid-tier specialists concentrate on regional customization and cost-optimized configurations. The vendor base organizes around three strategic archetypes: integrated automotive conglomerates with captive battery supply, commercial vehicle specialists pivoting from diesel architectures, and technology-first entrants leveraging software-defined chassis management. Capacity expansion and strategic partnerships dominate competitive moves, with particular emphasis on joint ventures securing lithium processing and cell manufacturing capacity.
Among integrated automotive conglomerates, Ford Motor Company and Mercedes-Benz Group AG exemplify tier-one positioning through diversified powertrain portfolios spanning battery electric and fuel cell architectures. Tata Motors anchors the emerging market specialist archetype, representing geographic diversification strategies targeting price-sensitive fleet operators in South Asia and Africa. These three entities occupy positions that reflect contrasting approaches to vertical integration, with varying degrees of in-house cell production versus external supply dependence.
| Leading Market Players |
|---|
| Ford Motor Company |
| Hyundai Motor Company |
| Volvo Trucks |
| Mercedes-Benz Group AG |
| PACCAR Inc. |
| Navistar International Corporation |
| Scania AB |
| Tata Motors |
| Tesla, Inc. |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Yangtze River Delta and family-owned mid-caps across Germany's Baden-Württemberg belt are anchoring supply discipline through captive lithium processing and in-house smelter partnerships. This ownership pattern concentrates pricing power upstream while compressing margins for chassis integrators dependent on external cathode supply.
Pricing Analysis
Margin tightening in heavy-duty configurations reflects lithium carbonate volatility and GB standards compliance costs for electromagnetic certification. Three-tier pricing structure across premium, standard, and economy levels separates Volvo Trucks' embedded telematics bundles from PACCAR's proprietary battery management tiers and Tata Motors' cost-optimized depot-charging platforms. Price differentiation hinges on after-sales service bundling and thermal management refrigerant certification under EU F-Gas Regulation. Delivery services operating 3.5 to 12-tonne fleets exhibit acute price sensitivity, while long-haul operators prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Battery pack refurbishment flows from regional haul operators in Germany and the United States are creating secondary supply channels for 300-500 kWh cell-to-pack modules. Raw material sourcing draws from Indonesian nickel processors, Chilean lithium brine operations, and Chinese cathode active material facilities. Cathode precursor supply concentrates in China, creating single-source vulnerability for European and North American chassis assemblers. Distribution runs through OEM captive networks in China, third-party maintenance providers in the United States, and dealer-retained servicing in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon border adjustment mechanism is erecting a compliance moat that favors chassis manufacturers with documented steel and aluminum provenance, locking out speculative entrants lacking smelter partnerships or traceable supply chains.
For Market Incumbents: Lock in cathode supply through long-term offtake agreements with Indonesian nickel processors and backward integration into cell-to-pack thermal management. Hydrogen fuel cell convergence above 200 kW threatens battery-dominant R&D pipelines, demanding dual-powertrain platform investment. Certification investment in China's GB electromagnetic compatibility standards preserves market access against delayed entry for non-domestic competitors. For New Entrants and Emerging Players: Enter via India's PLI scheme for automotive manufacturing, where domestic chassis assembly capacity expansion outpaces component supplier localization. Municipal refuse collection in Maharashtra and Gujarat offers the most penetrable procurement channel, with 7 to 10 year contract cycles favoring new bidders. A go-to-market angle anchored in green financing partnerships with India's central bank channels credit toward first-mover domestic assembly operations. For Investors and Strategic Acquirers: First-mover battery passport compliance in the EU is the leading indicator that traceable cell provenance will command acquisition premiums across the analysis window. Target chassis integrators with in-house thermal management engineering and established smelter partnerships for carbon border adjustment resilience. Monitor hydrogen fuel cell pilot deployments in South Korea's Busan-Ulsan corridor for heavy-duty platform viability signals.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell-to-pack capacity from Yangtze River Delta producers for heavy-duty configurations. |
| Software-Defined Vehicle Investment | Enables over-the-air performance updates that extend chassis capability without physical retrofit. |
| Geographic Manufacturing Footprint | Establishes Tamil Nadu assembly capacity for tariff-advantaged export to Middle Eastern fleet operators. |
| Charging Infrastructure Partnership | Integrates depot charging feasibility into last-mile delivery procurement specifications. |
| Platform Standardization | Reduces assembly complexity across 3.5 to 44 tonne gross vehicle weight ratings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fleet operations directors, chassis platform engineers, thermal management specialists, and OEM procurement managers supplied operational validation. EPA Phase 3 filings, EU ECHA substance registrations, China MIIT GB standard disclosures, and India PLI scheme beneficiary lists provided demand-side triangulation. Bottom-up chassis production estimates and top-down fleet electrification mandates were reconciled across the modeling period.
Granularity-level modeling distinguished light-duty, medium-duty, and heavy-duty chassis specifications alongside battery electric, hydrogen fuel cell, and hybrid electric propulsion architectures. Power rating tiers, end-user procurement patterns, and regional regulatory clusters were projected across the analysis window. CAGRs derived from production capacity buildouts, fleet replacement timelines, and zero-emission mandate compliance schedules. Cell-to-pack adoption curves and thermal management refrigerant transitions supplied industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or carbon border adjustment enforcement delays. Practitioners should monitor GB standards electromagnetic compatibility testing timelines and EU battery passport implementation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Indonesia Box Truck Market