
 Global Fuel Cell Commercial Vehicle Market | 2026-2036
Global Fuel Cell Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel Cell Commercial Vehicle Market Analysis
Heavy-duty range specifications above 500 miles per refueling cycle is reorganizing procurement priorities across North American and European fleet operators. Toyota Motor Corporation leverages its solid-state hydrogen storage patents to anchor technology leadership in long-haul applications. Hyundai Motor Company sustains manufacturing scale through dedicated fuel cell production lines in South Korea. Nikola Corporation competes on integrated hydrogen station partnerships rather than vehicle hardware alone.
A fuel cell commercial vehicle converts chemical energy from hydrogen or alternative fuels into electrical power through an electrochemical reaction, typically using proton exchange membrane stacks operating at 60-80°C to drive electric motors for freight and passenger transport. Heavy-duty trucks dominate current value pools due to per-unit power requirements exceeding 200 kW, while buses lead unit volumes in early deployment phases. Proton exchange membrane technology occupies the majority of installed capacity given its cold-start reliability, though solid oxide systems are gaining traction for stationary-range extender applications in logistics hubs.
The US Environmental Protection Agency and the National Highway Traffic Safety Administration impose tightening greenhouse gas standards on commercial fleets, while the European Union's F-Gas Regulation and CO2 performance standards for heavy-duty vehicles mandate zero-emission transition pathways. California's Air Resources Board enforces the Advanced Clean Trucks rule requiring manufacturers to sell increasing percentages of zero-emission vehicles. Fleet operators must weigh hydrogen supply security against battery-electric alternatives when committing to multi-decade asset replacement cycles.
Market Dynamics
Proton exchange membrane stack efficiency gains are compressing total cost of ownership for heavy-duty operators, while hydrogen supply security emerges as the binding constraint on fleet conversion timelines.
Growth Catalysts
- The US Inflation Reduction Act:Production tax credits for clean hydrogen are lowering fuel costs for California freight corridors. Fleet operators in the state are accelerating pilot deployments ahead of 2030 mandates.
- EU Green Deal CO2 performance standards:Binding emission ceilings for heavy-duty vehicles are eliminating diesel alternatives for long-haul routes. German logistics operators are trialing fuel cell trucks on the Rhine-Alpine corridor.
- Solid-state hydrogen storage patents:Toyota's intellectual property portfolio is enabling 700-bar refueling systems with faster cycle times. This technology is reducing dwell time at hydrogen stations for commercial fleets.
Market Restraints
- Platinum group metal cost volatility:PEM stack catalyst requirements tie vehicle economics to South African and Russian mining output. Price spikes in ruthenium and iridium directly inflate stack manufacturing costs.
- Electrolyzer manufacturing concentration:European alkaline and PEM electrolyzer supply chains cluster in Germany and Norway. This geographic concentration creates hydrogen production bottlenecks for fleet operators.
- Battery-electric substitution threat:Lithium iron phosphate packs for medium-duty routes now deliver sub-three-hour charging. Urban delivery fleets are bypassing hydrogen infrastructure entirely for depot-charged electrics.
Strategic Opportunities
- Netherlands hydrogen corridor buildout:The Port of Rotterdam hydrogen backbone is creating a dense refueling network for Benelux freight. Logistics operators can deploy fuel cell trucks without range anxiety penalties.
- Japan METI hydrogen roadmap:Subsidies for fuel cell bus procurement in Tokyo and Osaka are stabilizing manufacturing volumes. Bus OEMs are achieving production scale through municipal fleet commitments.
- Fuel cell-battery hybrid architectures:Range extender configurations pairing SOFC stacks with lithium-ion buffers are opening depot-based logistics applications. Warehouse operators in South Korea are piloting these systems for intra-facility shuttles.
Industry Challenges
- High-voltage electrical technician scarcity:PEM stack maintenance requires specialized training in 800V systems. Fleet maintenance departments face recruitment gaps for certified technicians.
- Multi-jurisdiction type approval complexity:UN ECE R134 and US FMVSS 305 certification timelines extend 18-24 months for new vehicle platforms. OEMs must duplicate testing protocols for transatlantic market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel Cell Commercial Vehicle Market |
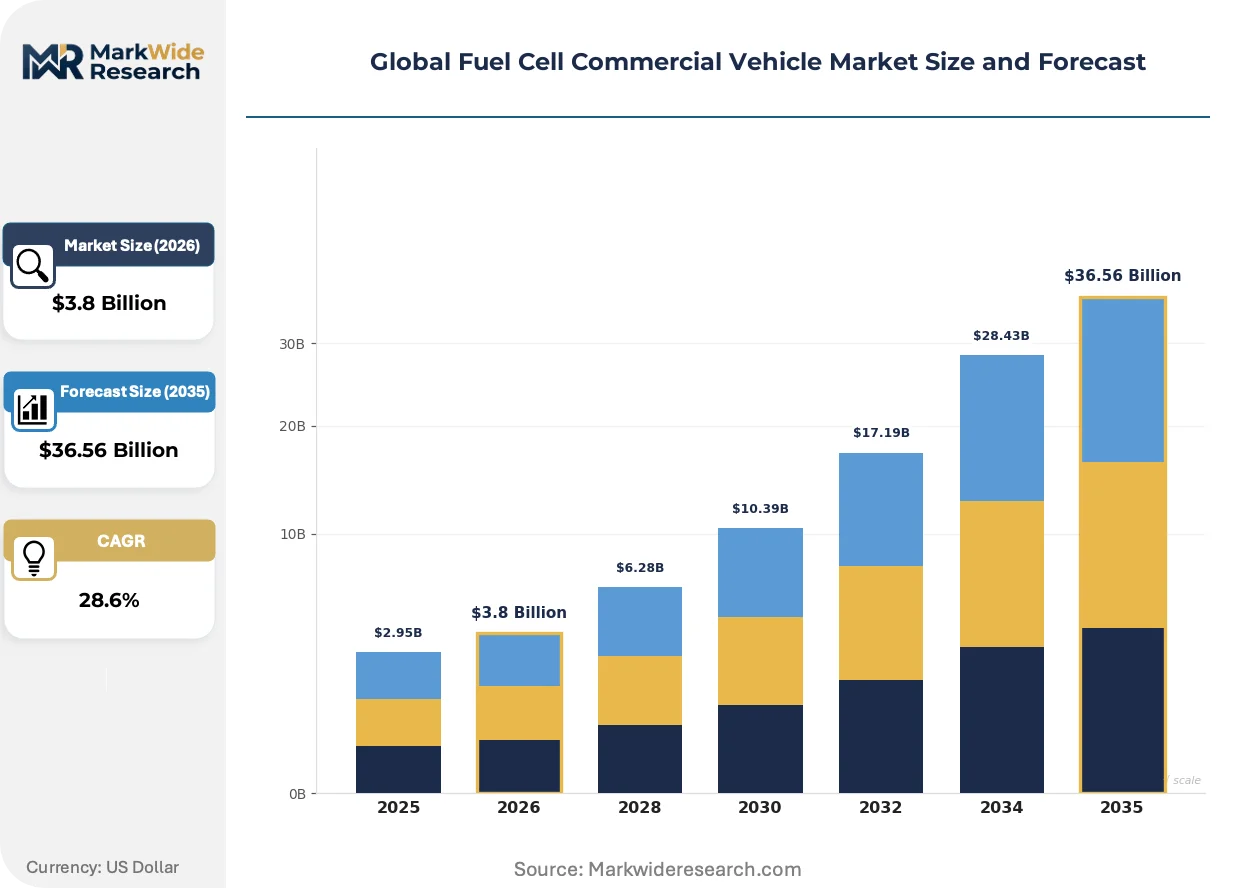
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Light Trucks, Heavy-Duty Trucks, Buses Fuel Type: Hydrogen, Methanol, Natural Gas, Others End User: Logistics, Public Transport, Delivery Services, Freight Transportation Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Others |
| Companies Covered | Hyundai Motor Company, Toyota Motor Corporation, Volvo Group, Mercedes-Benz Group, Nikola Corporation, Hyzon Motors, Foton Motor, New Flyer, PACCAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel Cell Commercial Vehicle Market Emerging Trajectories
Electrochemical system architectures are diversifying beyond proton exchange membranes, while refueling infrastructure deployment patterns are reshaping geographic demand concentration.
Solid oxide fuel cell technology is fragmenting the stationary and range-extender application space. Logistics hubs in Japan and the Netherlands are adopting SOFC systems for depot-based power generation and truck pre-conditioning. This technology is compressing the addressable market for pure PEM solutions in facility-centric operations.
The EU F-Gas Regulation is tightening refrigerant restrictions on thermal management systems. Fuel cell vehicle manufacturers must redesign cooling loops to eliminate hydrofluorocarbon dependencies. Heavy-duty OEMs serving European markets are accelerating CO2 heat pump integration to maintain compliance timelines.
Total cost of ownership contracting is displacing upfront vehicle purchase models for fleet operators. Hydrogen-as-a-service agreements in California and Germany bundle fuel, maintenance, and vehicle lease into per-mile rates. Long-haul freight operators in these markets are transferring technology risk to infrastructure providers through multi-year service commitments.
Global Fuel Cell Commercial Vehicle Market Segmentation
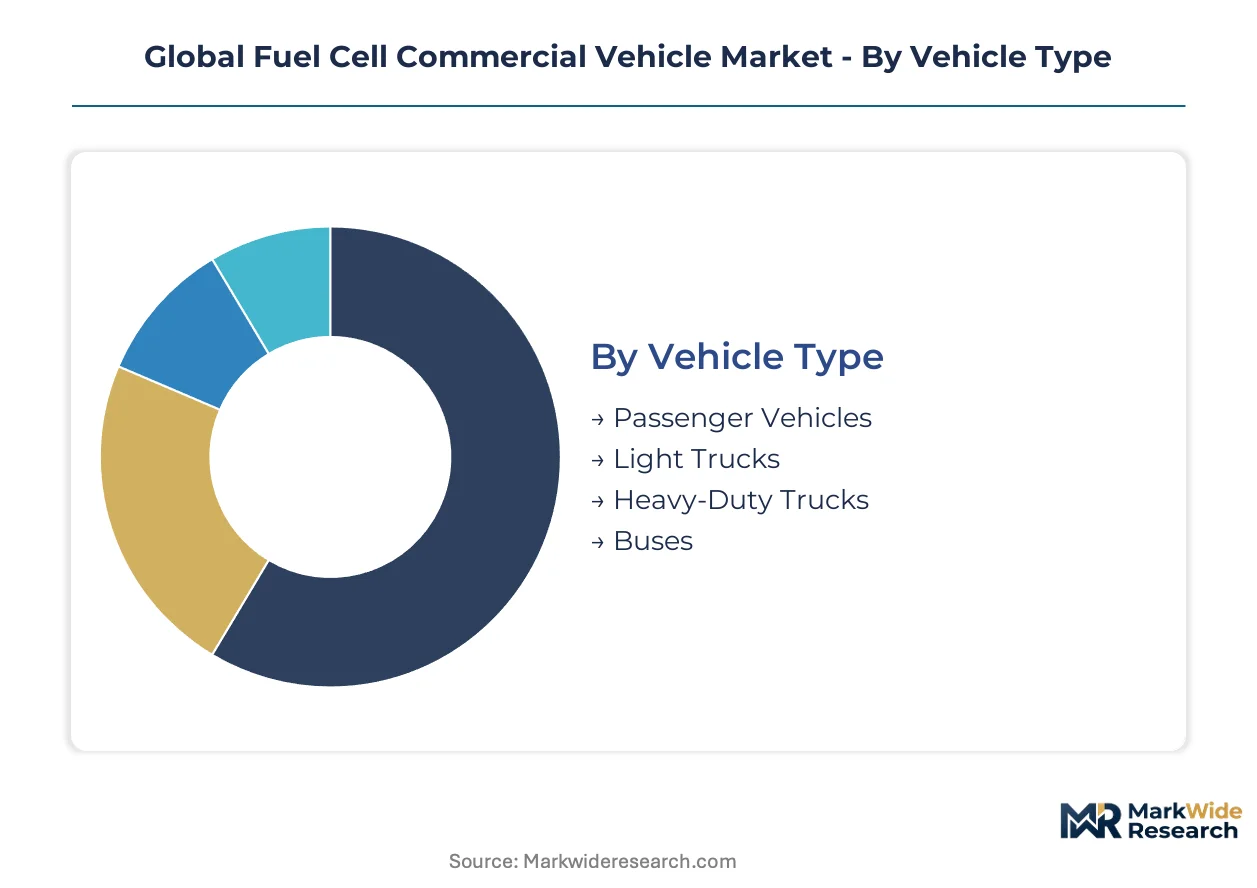
Fleet procurement patterns in fuel cell commercial vehicles diverge sharply by duty cycle and infrastructure access, requiring granular segmentation to align powertrain specifications with operational economics. Procurement channels favor direct OEM relationships for heavy-duty applications while municipal tenders dominate bus deployments.
Vehicle Type:
Channel concentration varies by payload class, with heavy-duty trucks flowing through fleet management companies and buses channeling through municipal procurement offices.
- Heavy-Duty Trucks:Power requirements exceeding 200 kW per unit anchor value concentration in long-haul freight corridors. German operators on the Rhine-Alpine corridor and California fleet managers prioritize these units for routes exceeding 500 miles per cycle, though hydrogen station density constrains deployment geography.
- Buses:Fixed-route predictability enables depot-based refueling infrastructure, concentrating early adoption in Tokyo and Osaka under Japan METI subsidies. Municipal procurement cycles stabilize manufacturing volumes for OEMs serving public transport authorities.
- Light Trucks:Urban delivery fleets in the Netherlands and South Korea pilot fuel cell variants for last-mile applications where battery-electric range falls short.
- Passenger Vehicles:Commercial van applications remain limited to specialized shuttle services and airport ground transport in hydrogen corridor markets.
Heavy-Duty Trucks dominate installed base. Buses are where expansion concentrates fastest for unit volume scaling.
Fuel Type:
Cost tier stratification separates established hydrogen infrastructure markets from emerging alternative fuel trials.
- Hydrogen:Gaseous and liquid storage systems at 350-bar and 700-bar pressures constitute the primary fuel pathway for commercial deployment. California's production tax credits under the US Inflation Reduction Act compress fuel costs for freight operators, while EU Green Deal emissions ceilings eliminate diesel alternatives on key corridors.
- Methanol:Liquid fuel compatibility with existing distribution infrastructure attracts logistics operators in markets with sparse hydrogen station networks. Reforming efficiency losses trade against infrastructure capital requirements.
- Natural Gas:Blended hydrogen-natural gas systems serve transitional fleet strategies in Germany and the Netherlands where biomethane availability overlaps with early hydrogen corridors.
- Others:Ammonia and synthetic fuel research programs in Japan and South Korea target maritime and aviation fuel cell derivatives with technology spillover potential for heavy trucking.
Hydrogen dominates installed base. Methanol is where expansion concentrates for infrastructure-constrained operators.
End User:
Application-specific duty cycles determine refueling frequency tolerance and infrastructure investment returns.
- Logistics:Hub-and-spoke distribution networks in the Netherlands and Germany concentrate demand around port corridors and inland freight terminals. Warehouse operators prioritize fuel cell-battery hybrid architectures for depot-based shuttles with intermittent duty cycles.
- Freight Transportation:Long-haul operators across transcontinental routes face binding constraints from hydrogen supply security and station reliability. Fleet commitments require multi-year hydrogen-as-a-service agreements to transfer technology risk.
- Public Transport:Municipal fleet operators in Tokyo, Osaka, and California cities anchor bus manufacturing scale through consolidated procurement tenders with defined zero-emission transition timelines.
- Delivery Services:Urban last-mile operators in South Korea pilot fuel cell vans where charging depot constraints limit battery-electric alternatives for extended shift patterns.
Logistics dominates installed base. Freight Transportation is where expansion concentrates for revenue per unit scaling.
Technology:
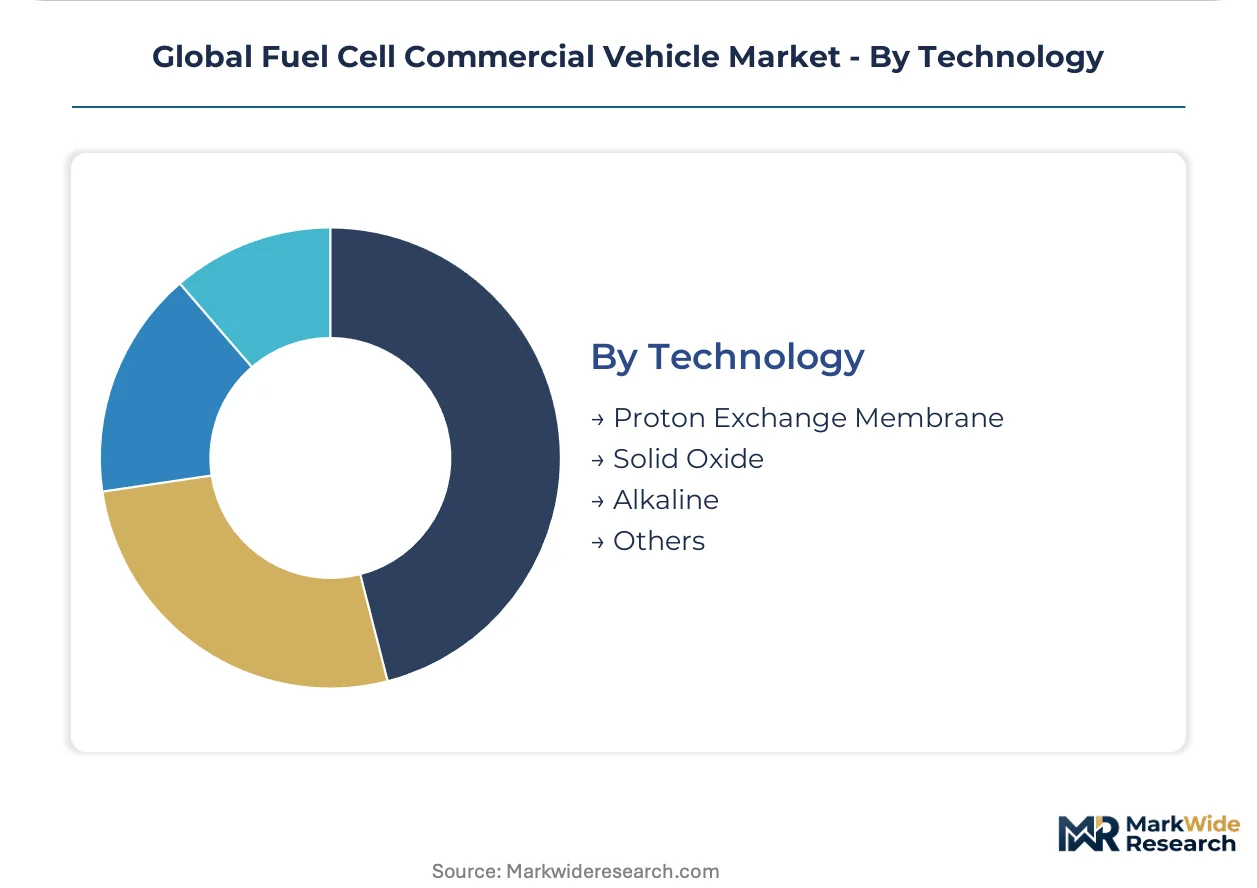
Maturity gradients separate commercially proven stack architectures from emerging system designs targeting stationary and range-extender applications.
- Proton Exchange Membrane:Cold-start reliability at sub-zero temperatures and 60-80°C operating range anchor deployment in mobile commercial applications. Platinum group metal catalyst requirements tie stack economics to South African and Russian mining output volatility.
- Solid Oxide:800-1000°C operating temperatures suit stationary depot power generation and truck pre-conditioning in Japanese and Dutch logistics hubs. Ceramic stack durability challenges limit mobile deployment despite higher electrical efficiency.
- Alkaline:Lower catalyst costs attract stationary applications in European electrolyzer manufacturing clusters, though lower power density constrains vehicle integration.
- Others:Phosphoric acid and molten carbonate systems occupy niche combined heat and power applications with limited commercial vehicle relevance.
Proton Exchange Membrane dominates installed base. Solid Oxide is where expansion concentrates for facility-centric operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stack manufacturing clusters in South Korea and Japan anchor supply-side capacity, while hydrogen corridor buildouts in Germany and California concentrate early fleet deployment. Demand formation depends on refueling infrastructure density and production tax credit availability.
United States
California freight operators dominate pilot deployments along the I-5 corridor between Los Angeles and San Francisco. The US Inflation Reduction Act production tax credits compress clean hydrogen fuel costs for fleet managers. Nikola Corporation maintains hydrogen station partnerships in the Central Valley to anchor long-haul routes.
Germany
Rhine-Alpine logistics operators trial heavy-duty trucks between Rotterdam and Milan under binding EU Green Deal emission ceilings. The KBA enforces UN ECE R134 type approval timelines extending 18-24 months for new platforms. Daimler Truck and Volvo Group manufacturing in Baden-Württemberg concentrate European stack assembly capacity.
Japan
Tokyo and Osaka municipal bus fleets anchor manufacturing volume through METI subsidy programs. The Port of Yokohama hydrogen backbone supplies refueling infrastructure for corridor freight. Toyota Motor Corporation's solid-state storage patents enable 700-bar systems reducing station dwell times.
South Korea
Hyundai Motor Company dedicated production lines in Ulsan sustain manufacturing scale for export markets. The Ministry of Trade, Industry and Energy funds hydrogen station buildouts along the Gyeongbu Expressway. Busan port logistics operators pilot fuel cell-battery hybrid shuttles for depot-based distribution.
Netherlands
Rotterdam port hydrogen backbone creates dense refueling coverage for Benelux freight corridors. EU F-Gas Regulation refrigerant restrictions force CO2 heat pump redesigns in thermal management systems. Logistics operators deploy heavy-duty trucks without range anxiety penalties across the Randstad cluster.
Global Fuel Cell Commercial Vehicle Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated automotive conglomerates with dedicated fuel cell divisions compete against pure-play hydrogen vehicle specialists and commercial vehicle incumbents retrofitting existing platforms. The market fragments across three strategic archetypes: full-stack manufacturers controlling membrane and storage technology, vehicle assemblers sourcing subsystems from tier-one suppliers, and hydrogen infrastructure integrators bundling fuel with asset leases. Dominant competitive moves include hydrogen station partnership formations and dedicated production line investments to achieve manufacturing scale.
Within the integrated automotive tier, Hyundai Motor Company and Toyota Motor Corporation represent archetypes of full-stack technology control, while Nikola Corporation exemplifies the infrastructure-integrator model. Hyundai's South Korea-based manufacturing structure and Toyota's patent portfolio around solid-state storage systems position these entities as technology anchors. Nikola's hydrogen-as-a-service agreements transfer operational risk from fleet operators to infrastructure providers. Volvo Group and Mercedes-Benz Group occupy positions as commercial vehicle incumbents leveraging existing distribution networks for platform deployment.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Volvo Group |
| Mercedes-Benz Group |
| Nikola Corporation |
| Hyzon Motors |
| Foton Motor |
| New Flyer |
| PACCAR |
| Others |
Supply Flow & Price Mechanics
Platinum group metal substitution in PEM stack catalysts is compressing manufacturing economics while simultaneously shifting procurement geography toward South African and Russian mining corridors. This dual displacement redraws cost structures for heavy-duty OEMs and forces fleet operators into long-term hydrogen-as-a-service contracts to buffer commodity volatility.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure for California freight operators through production tax credits that compress clean hydrogen fuel costs. Three-tier pricing structure across premium, standard, and economy levels separates integrated hydrogen-as-a-service bundles from bare vehicle leases and spot-fuel arrangements. Cost compression in economy tiers is intensifying because lithium iron phosphate alternatives now undercut hydrogen on urban routes. Municipal bus fleets exhibit highest price sensitivity due to fixed budget cycles, while long-haul freight operators absorb premium pricing for range security.
Supply Chain Analysis
Strait of Hormuz transit underwrites electrolyzer equipment flows from European manufacturing clusters to Asian deployment markets. Stack assembly draws from South Korea, Japan, and Germany while platinum group metal sourcing rests on South African and Russian mining output. Single-source vulnerability in ruthenium and iridium supply creates manufacturing bottlenecks when geopolitical disruptions interrupt extraction. Distribution runs through dedicated fuel cell production lines at Hyundai Motor Company and Toyota Motor Corporation rather than shared automotive platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story where hydrogen corridor buildouts in Germany, California, and the Netherlands are accelerating fleet conversion timelines ahead of regulatory mandates. Penetration remains concentrated in heavy-duty applications where battery-electric alternatives fail on range specifications.
For Market Incumbents: Consolidate manufacturing scale through dedicated production line investments in South Korea and Germany to defend against battery-electric substitution threats on medium-duty routes. Deepen backward integration into solid-state hydrogen storage technology to capture 700-bar refueling system margins and lock in intellectual property advantages over infrastructure-integrator competitors. For New Entrants and Emerging Players: Differentiate on methanol-reformer compatibility for logistics operators in infrastructure-constrained corridors where hydrogen station density remains insufficient for pure fuel cell deployment. Target Netherlands port logistics and German Rhine-Alpine freight operators with liquid fuel solutions that bypass electrolyzer supply bottlenecks. Pursue depot-based fuel cell-battery hybrid architectures for warehouse shuttle applications where SOFC range extenders open white-space beyond pure PEM competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with hydrogen-as-a-service providers and infrastructure-integrator models that bundle fuel, maintenance, and vehicle leases into per-mile contracts. Long-term viability hinges on electrolyzer manufacturing scale achieving cost parity with gray hydrogen production. Watch hydrogen production tax credit permanence in US legislative cycles as the inflection indicator for capital commitment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Station Partnership Formation | Nikola Corporation's Central Valley network anchors California I-5 corridor fleet commitments. |
| Dedicated Fuel Cell Production Line Investment | Hyundai Motor Company's Ulsan facility sustains export manufacturing scale for European markets. |
| Solid-State Storage Patent Licensing | Toyota Motor Corporation's 700-bar intellectual property reduces commercial fleet dwell times. |
| Hydrogen-as-a-Service Contract Structuring | German logistics operators transfer technology risk through multi-year bundled per-mile agreements. |
| SOFC Range Extender Integration | Japanese logistics hubs adopt stationary depot power generation for truck pre-conditioning applications. |
Methodological Framework
Operator-level perspectives from fleet procurement managers, hydrogen infrastructure developers, PEM stack manufacturing engineers, and electrolyzer supply chain specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC filings from commercial vehicle OEMs, EU ECE type approval databases, and hydrogen corridor development announcements from Japan METI and the US Department of Energy. Bottom-up vehicle deployment tracking across California, Germany, Japan, South Korea, and the Netherlands triangulated against top-down market sizing from production capacity announcements.
Sensitivity analysis around hydrogen production cost trajectories and platinum group metal price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, fuel storage pressure tier, end-use application duty cycle, and regional regulatory cluster. CAGRs derived from electrolyzer manufacturing scale curves and fleet operator replacement cycle timing. Industry-specific inputs incorporated EU Green Deal CO2 performance standard enforcement timelines and California Air Resources Board zero-emission vehicle mandate phase-ins.
Material uncertainties — electrolyzer supply chain concentration, hydrogen production tax credit policy continuity, and battery-electric technology cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about infrastructure buildout pacing and commodity price stabilization. Revision becomes warranted when platinum group metal supply disruptions or US legislative shifts cross thresholds that alter total cost of ownership calculations for heavy-duty operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Truck-As-A-Service Market